
 Envelope Tracking Chips Market | 2026-2036
Envelope Tracking Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Envelope Tracking Chips Market Intelligence
Multi-sourced foundry strategies is recalibrating how envelope tracking chip vendors secure wafer capacity. Qorvo leverages its captive GaN fab network to lock in substrate supply. Skyworks Solutions anchors its position through deep partnerships with Korea-based smartphone OEMs. Qualcomm competes by integrating envelope tracking directly into modem-RF system platforms.
Envelope tracking chips dynamically modulate power supply voltage to RF power amplifiers, matching instantaneous signal envelope amplitude with millisecond-scale response to minimize heat dissipation and extend battery endurance. CMOS-based discrete chips dominate unit shipments for mid-tier smartphones where cost sensitivity overrides peak efficiency, while GaN power amplifier modules capture premium 5G mmWave sockets where thermal density limits conventional silicon. Integrated circuits incorporating envelope tracking plus DC-DC conversion are claiming margin pools in flagship handset designs that demand board-space consolidation.
FCC Part 27 rules on 5G spectrum efficiency shape power amplifier certification requirements for US-bound devices, while EU REACH restrictions on gallium arsenide processing chemicals tighten material sourcing protocols for European markets. South Korea's Radio Waves Act enforces stringent electromagnetic compatibility standards that push local suppliers toward GaN technology migration. Stakeholders must monitor how India's WPC certification timeline shifts affect base station deployment schedules and associated chip procurement cycles.
Market Dynamics
GaN-on-SiC process maturation is compressing power amplifier thermal losses while 5G mmWave deployment accelerates, forcing envelope tracking architectures toward tighter voltage modulation precision. Smartphone OEM procurement power is consolidating around modem-RF platform suppliers who bundle envelope tracking with baseband integration.
Growth Catalysts
- 5G mmWave spectrum allocation:FCC Part 27 efficiency mandates require dynamic power supply modulation for US-bound devices, pulling envelope tracking into premium handset bill-of-materials.
- Thermal density constraints:South Korea's Radio Waves Act electromagnetic compatibility standards push local suppliers toward GaN migration, expanding addressable socket volume for high-efficiency modulators.
- EU REACH chemical restrictions:Gallium arsenide processing constraints tighten material sourcing protocols, accelerating foundry qualification of alternative III-V substrates for European market access.
Market Restraints
- Substrate supply concentration:High-purity SiC wafer output concentrates among a handful of Japanese and US suppliers, exposing envelope tracking module vendors to allocation risk.
- GaN epitaxy cost structure:MOCVD reactor throughput limitations and precious metal precursor costs sustain premium pricing for GaN-on-SiC power amplifiers versus silicon alternatives.
- Modem-RF platform substitution:Integrated baseband-envelope tracking solutions from Qualcomm and MediaTek threaten standalone discrete chip socket availability in flagship tier.
Strategic Opportunities
- India base station buildout:WPC certification timeline compression for 5G small cells creates procurement cycle acceleration for envelope tracking chips in macro and pico cell power amplifiers.
- Automotive V2X connectivity:C-V2X module integration into vehicle telematics units opens adjacent demand for envelope tracking in high-reliability automotive RF chains.
- Open RAN disaggregation:O-RAN Alliance interface specifications enable new vendor entry into remote radio head power amplifier subsystems, fragmenting incumbent supply relationships.
Industry Challenges
- RF mixed-signal design talent scarcity:Millimeter-wave circuit design expertise concentrates among a narrow pool of specialists, constraining product development velocity for mid-tier chip vendors.
- Multi-foundry qualification overhead:Porting envelope tracking designs across TSMC, GlobalFoundries, and Samsung Foundry process nodes demands redundant mask set investment and extended validation cycles.
- Legacy 4G inventory absorption:Carrier aggregation handset volume decline in emerging markets slows envelope tracking retrofit demand, compressing near-term revenue visibility for discrete suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Envelope Tracking Chips Market |
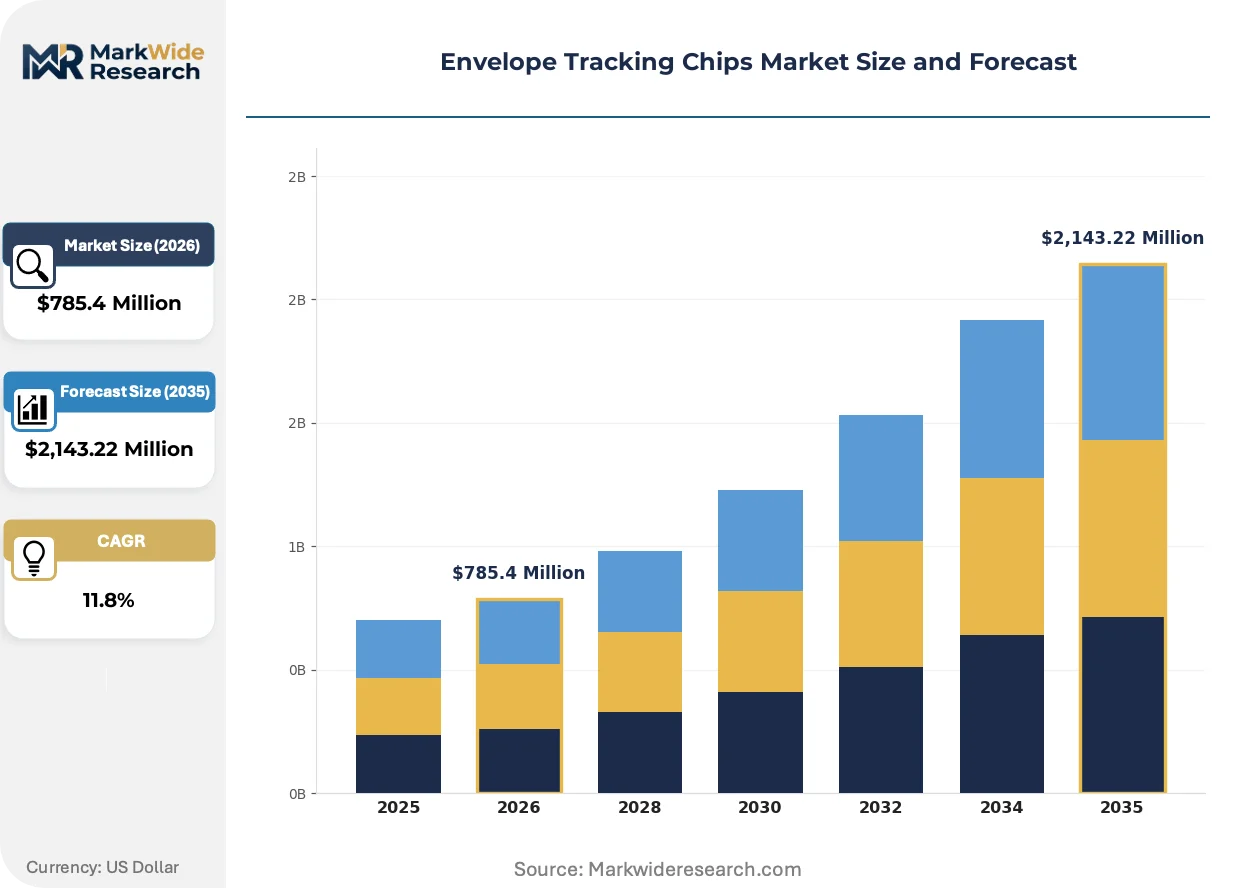
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $2,143.22 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Chips, Integrated Circuits, Power Amplifier Modules, Signal Modulators Technology: CMOS, GaAs, GaN, SiGe Application: Smartphones, Wireless Base Stations, Satellites, IoT Devices, Military Communication End User: Consumer Electronics Manufacturers, Telecom Equipment Makers, Aerospace Firms, Defense Contractors |
| Companies Covered | Qorvo, Skyworks Solutions, Qualcomm, MediaTek, NXP Semiconductors, Texas Instruments, Analog Devices, Efficient Power Conversion, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Envelope Tracking Chips Market Strategic Shifts & Innovations
Envelope tracking architectures are bifurcating between cost-optimized CMOS discrete implementations and premium GaN-integrated modules, with process technology choice now determining competitive positioning rather than circuit topology alone.
GaN-on-SiC power amplifier modules are expanding into flagship 5G mmWave smartphone sockets as Samsung Electronics and Apple procurement specifications harden around thermal efficiency benchmarks. These modules integrate envelope tracking control loops with the power amplifier die itself, collapsing board area requirements while raising barrier-to-entry for fabless competitors lacking captive GaN capacity. The structural consequence is margin compression for standalone envelope tracking chip vendors who must defend socket access through deeper modem partnership integration.
EU REACH restrictions on hexavalent chromium and gallium arsenide etchant chemicals are forcing foundry process requalification across European-bound supply chains. Industrial consequence includes extended qualification timelines for new envelope tracking designs and accelerated migration toward GaN substrates that bypass restricted chemistries. Premium handset OEMs with European distribution exposure are now mandating REACH-compliant material declarations upstream through their RF component suppliers.
Smartphone OEM direct foundry engagement is fragmenting traditional semiconductor distribution channels for envelope tracking chips. Tier-one handset makers now negotiate wafer start commitments directly with TSMC and Samsung Foundry, relegating legacy distributors to logistics and inventory financing roles. This pattern concentrates most visibly in South Korea's Seoul metropolitan cluster, where Samsung Electronics vertical integration with its captive system LSI division sidelines independent envelope tracking vendors without modem-RF platform bundling capability.
Envelope Tracking Chips Market Segmentation
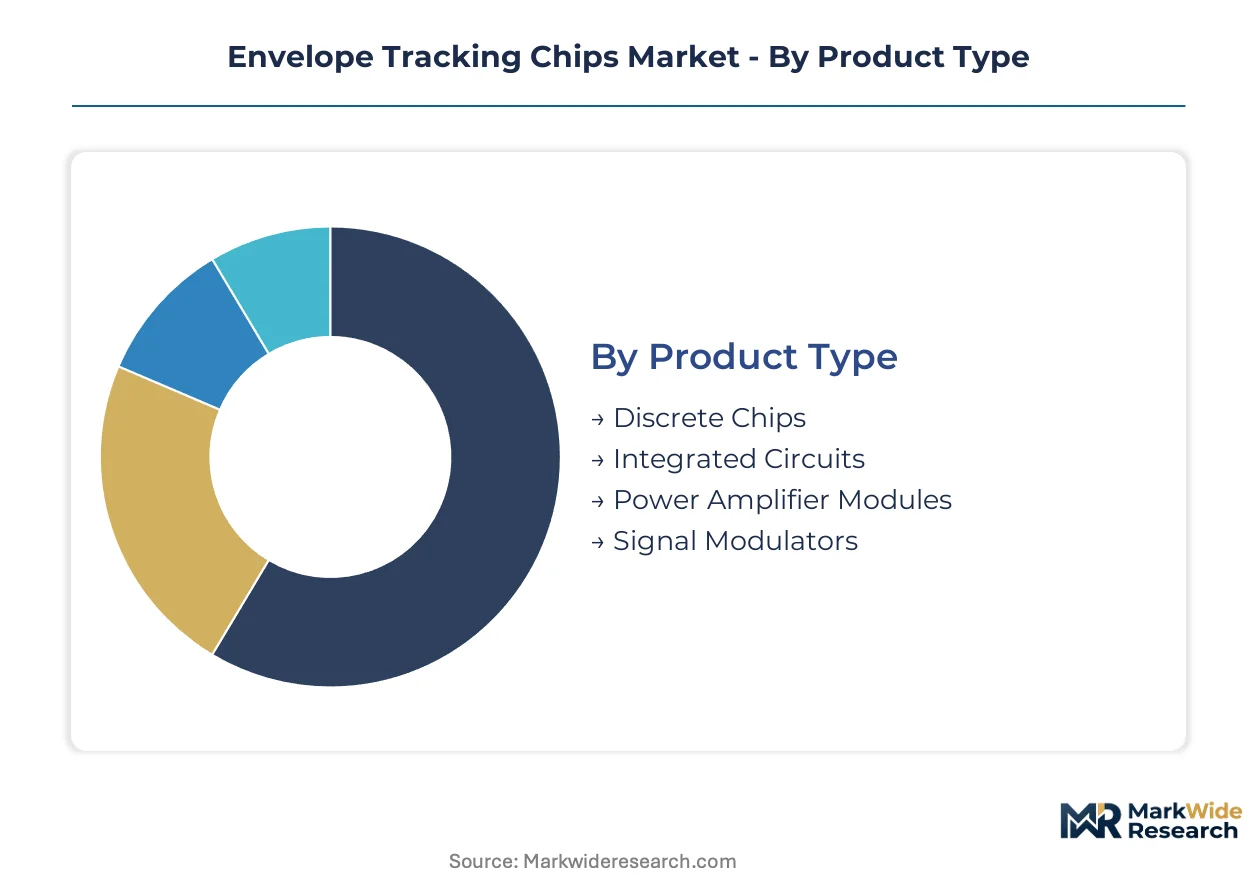
Envelope tracking chip architectures diverge sharply between cost-driven mass-market implementations and precision-engineered premium sockets. Process technology selection now determines competitive positioning more than circuit design alone. Each segment category reflects distinct procurement power structures and qualification barriers.
Product Type:
Volume shipments concentrate in cost-optimized discrete formats while premium sockets absorb integrated solutions that collapse board area.
- Discrete Chips:Standalone CMOS implementations dominate mid-tier smartphone bill-of-materials where procurement teams prioritize unit economics over peak thermal efficiency. Samsung Electronics and Chinese handset OEMs source these through direct TSMC foundry negotiations, bypassing traditional distribution channels.
- Integrated Circuits:Multi-function dies combining envelope tracking with DC-DC conversion capture flagship handset designs demanding space consolidation. Apple and Samsung procurement specifications harden around these solutions for 5G mmWave sub-6 GHz concurrent operation.
- Power Amplifier Modules:GaN-on-SiC integrated modules serve premium 5G mmWave sockets where thermal density limits silicon alternatives.
- Signal Modulators:Specialized components for military and satellite applications requiring extended temperature range operation.
Mature deployment sits with Discrete Chips. Newer deployment is concentrated in Integrated Circuits.
Technology:
Substrate chemistry separates commodity supply from captive capacity, with GaN migration accelerating under regulatory pressure.
- CMOS:Silicon-based processes from TSMC and GlobalFoundries enable lowest-cost envelope tracking for high-volume smartphone sockets. FCC Part 27 efficiency mandates pull CMOS designs toward tighter voltage modulation precision without sacrificing unit economics.
- GaN:Gallium nitride on silicon carbide delivers thermal performance for 5G mmWave power amplifiers where conventional silicon fails. EU REACH restrictions on gallium arsenide etchants accelerate foundry qualification of GaN epitaxy for European market access.
- GaAs:Legacy gallium arsenide processes face chemical restriction headwinds in European supply chains.
- SiGe:Silicon-germanium serves intermediate applications balancing cost and frequency response.
Commercial maturity centers on CMOS. Steepest expansion trajectory belongs to GaN.
Application:
Smartphone procurement volumes dwarf adjacent segments, yet base station deployment timelines create cyclical demand spikes.
- Smartphones:5G mmWave penetration drives envelope tracking into premium handset tiers as thermal constraints intensify. South Korea's Seoul metropolitan cluster anchors demand through Samsung Electronics vertical integration with its system LSI division.
- Wireless Base Stations:Macro and small cell power amplifiers require high-reliability envelope tracking for spectrum efficiency compliance. India's WPC certification timeline compression accelerates procurement cycles for this segment.
- Satellites:Space-qualified components demand radiation-hardened designs with extended operational lifecycles.
- IoT Devices:Low-power wide-area network modules incorporate simplified envelope tracking for battery endurance.
- Military Communication:Secure waveform requirements drive specialized high-reliability procurement specifications.
Established penetration resides in Smartphones. Fastest share gains occur in Wireless Base Stations.
End User:
Direct foundry engagement fragments traditional semiconductor distribution, with tier-one manufacturers negotiating wafer starts independently.
- Consumer Electronics Manufacturers:Smartphone OEMs consolidate procurement around modem-RF platform suppliers who bundle envelope tracking with baseband integration. South Korea's Radio Waves Act electromagnetic compatibility standards push these buyers toward GaN technology migration.
- Telecom Equipment Makers:Base station vendors source envelope tracking chips through qualified vendor lists tied to Open RAN disaggregation timelines.
- Aerospace Firms:Satellite operators demand extended qualification documentation and radiation tolerance certification.
- Defense Contractors:Military specification adherence requires traceable supply chains and ITAR compliance protocols.
Volume concentration aligns with Consumer Electronics Manufacturers. Emerging procurement intensity clusters around Telecom Equipment Makers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon carbide substrate supply concentrates among Japanese and US suppliers, anchoring envelope tracking chip production geography around foundry access points rather than end-market proximity.
United States
FCC Part 27 spectrum efficiency mandates pull envelope tracking into premium 5G handset designs bound for US carriers. The Federal Communications Commission enforces strict power amplifier certification timelines that compress supplier qualification windows. Austin and Dallas-Fort Worth semiconductor clusters host RF design centers serving both smartphone and base station OEMs.
South Korea
Samsung Electronics vertical integration with its system LSI division concentrates envelope tracking demand within the Seoul metropolitan cluster. The Radio Waves Act enforces electromagnetic compatibility standards that accelerate GaN technology migration among local suppliers. Pangyo and Suwon host dense supplier ecosystems feeding captive smartphone production lines.
China
MIIT spectrum allocation for 5G sub-6 GHz and mmWave bands drives domestic base station deployment at scale. The Ministry of Industry and Information Technology coordinates infrastructure buildout timelines that synchronize chip procurement cycles. Shenzhen and Shanghai semiconductor clusters concentrate RF module assembly capacity serving both domestic and export handset OEMs.
Japan
METI industrial policy supports GaN-on-SiC substrate and epitaxy capacity expansion for RF power amplifier applications. The Ministry of Economy, Trade and Industry coordinates supply chain resilience initiatives targeting critical semiconductor materials. Kyushu and Kansai regions anchor high-purity SiC wafer production feeding global foundry networks.
Germany
EU REACH restrictions on gallium arsenide processing chemicals force foundry requalification for European-bound supply chains. The European Chemicals Agency oversees compliance timelines that extend new design validation cycles. Bavaria and Baden-Württemberg host automotive RF development centers exploring C-V2X envelope tracking integration.
Envelope Tracking Chips Market Key Industry Players
Strategic partnerships dominate the current landscape as modem-RF platform bundling reshapes socket access. The vendor base splits between captive GaN capacity holders and fabless designers dependent on foundry allocation. Three archetypes occupy distinct positions: integrated platform suppliers with baseband-envelope tracking fusion, discrete chip specialists defending mid-tier smartphone sockets, and GaN module vendors capturing premium thermal-efficiency specifications. Competitive intensity centers on foundry capacity reservation and direct OEM engagement rather than price alone.
Among US-based RF semiconductor vendors, Qorvo, Skyworks Solutions, and Qualcomm occupy positions spanning the platform-integrated to discrete-specialist spectrum. Qorvo represents the captive-capacity archetype through its in-house GaN fabrication network. Skyworks Solutions exemplifies deep OEM partnership models anchored in Korea-based smartphone supply relationships. Qualcomm sits within the modem-RF integration tier where envelope tracking collapses into baseband system platforms. Each archetype faces margin pressure as Samsung Electronics and Apple procurement specifications harden around thermal efficiency benchmarks and board-space consolidation requirements.
| Leading Market Players |
|---|
| Qorvo |
| Skyworks Solutions |
| Qualcomm |
| MediaTek |
| NXP Semiconductors |
| Texas Instruments |
| Analog Devices |
| Efficient Power Conversion |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
Smartphone OEM bundling of envelope tracking with modem-RF platforms is forcing standalone chip vendors to absorb margin compression while securing alternative foundry capacity. This procurement consolidation concentrates pricing power among platform-integrated suppliers and elevates cost sensitivity for discrete specialists serving mid-tier handset sockets.
Pricing Analysis
Extended warranty and failure-rate guarantee bundling separates premium GaN-on-SiC module pricing from bare-die CMOS transactions. Three-tier pricing structure across premium, standard, and economy levels reflects thermal efficiency certification tiers and volume commitment scale. Pricing pressure stems from Qualcomm and MediaTek modem-RF integration threatening standalone socket availability. Mid-tier smartphone OEMs exhibit acute price sensitivity, while Apple and Samsung procurement tolerates premium positioning for board-space consolidation.
Supply Chain Analysis
Freight cost volatility for high-purity SiC wafers from Japan and the United States amplifies landed cost uncertainty for GaN epitaxy operations. Substrate supply concentrates in Kyushu-based Japanese producers and domestic US suppliers, with MOCVD reactor throughput constraining GaN-on-SiC output expansion. Raw material dependencies include high-purity gallium metal, silicon carbide substrates, and precious metal precursors for epitaxial growth. Single-source vulnerability for SiC wafer supply exposes envelope tracking module vendors to allocation risk. Distribution runs through direct foundry engagement by tier-one smartphone OEMs, bypassing traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity SiC wafer supply concentration among Japanese producers props pricing power for captive GaN capacity holders and constrains fabless competitors. This structural bottleneck sustains margin premiums for vertically integrated suppliers while compressing returns for foundry-dependent players.
For Market Incumbents: Anchor socket access through deeper modem-RF platform partnership integration and accelerate GaN epitaxy capacity expansion in Japan or the United States. Defend against MediaTek and Qualcomm baseband-envelope tracking fusion by securing exclusive design wins with Korea-based smartphone OEMs. Prioritize REACH-compliant material qualification to maintain European market access as gallium arsenide processing restrictions tighten. For New Entrants and Emerging Players: Automotive C-V2X module suppliers represent an underserved buyer archetype with limited incumbent penetration and qualification flexibility. Target Open RAN remote radio head power amplifier subsystems where disaggregated procurement protocols lower barrier-to-entry. Pursue direct engagement with India's WPC certification acceleration timeline for base station envelope tracking procurement cycles. For Investors and Strategic Acquirers: The window for entry favors fabless envelope tracking specialists with qualified GaN-on-SiC designs and established Korea-based smartphone OEM relationships. Long-term viability hinges on modem-RF platform bundling capability or captive substrate access. Watch for SiC wafer supply allocation announcements as inflection indicators for incumbent pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Capacity Expansion | Captive epitaxy investment locks in substrate supply for Samsung and Apple qualification. |
| Modem-RF Platform Integration | Baseband-envelope tracking fusion defends socket access against standalone chip displacement. |
| REACH-Compliant Process Requalification | Alternative III-V substrate qualification secures European market access under chemical restrictions. |
| Direct Foundry Engagement | Wafer start negotiations with TSMC and Samsung Foundry bypass distribution margin extraction. |
| Open RAN Partnership Development | Remote radio head subsystem qualification fragments incumbent base station supply relationships. |
Research Approach
Independent corroboration across RF semiconductor design executives, foundry procurement managers, and smartphone OEM supply chain directors underwrites the qualitative findings. Primary interviews with GaN epitaxy specialists, MOCVD equipment engineers, and base station power amplifier architects combined with secondary validation from SEC 10-K filings, customs wafer trade data, and FCC Part 27 certification databases. Bottom-up smartphone shipment modeling and top-down RF component bill-of-materials analysis triangulate market sizing.
Comparable-period anchoring to historical 5G deployment cycles and GaN-on-SiC adoption trajectories shaped the projection horizon. Segmentation dimensions span product architecture, substrate technology, application socket, and end-user procurement channel. CAGRs derive from unit shipment elasticity to smartphone refresh cycles and base station deployment timelines. Forecast inputs include FCC spectrum efficiency mandate compliance deadlines and India's WPC certification acceleration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SiC wafer supply expansion rates and modem-RF platform substitution velocity. Forecasts reflect assumptions about GaN epitaxy cost reduction trajectories and Open RAN disaggregation adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
Europe 8- Bit Microcontroller Market