
 Greenhouse Irrigation Systems Market | 2026-2036
Greenhouse Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Irrigation Systems Market Outlook
Sensor-to-actuator integration is narrowing the performance gap between premium and mid-tier greenhouse irrigation controllers. Netafim Ltd. leverages its drip emitter heritage to anchor precision agriculture partnerships across European glasshouse clusters. Jain Irrigation Systems Ltd. sustains manufacturing scale through backward integration into polymer extrusion and filter assembly. Rivulis Irrigation Ltd. competes on modular retrofit architectures that reduce installation downtime in existing greenhouse structures.
Greenhouse irrigation systems comprise pressurized water delivery networks, emitters, filtration units, and control interfaces engineered to maintain substrate moisture and nutrient levels within crop-specific thresholds, typically operating at pressures between 1.0 and 2.5 bar for drip configurations. Their primary commercial purpose is to maximize yield per cubic meter of water consumed in controlled-environment agriculture. Drip irrigation retains the dominant installed base due to its compatibility with soilless substrates and hydroponic benches, though automated control systems represent the fastest-expanding technology segment as labor costs rise. Fertigation systems command premium positioning by consolidating irrigation and nutrient dosing into single-loop architectures that reduce chemical waste.
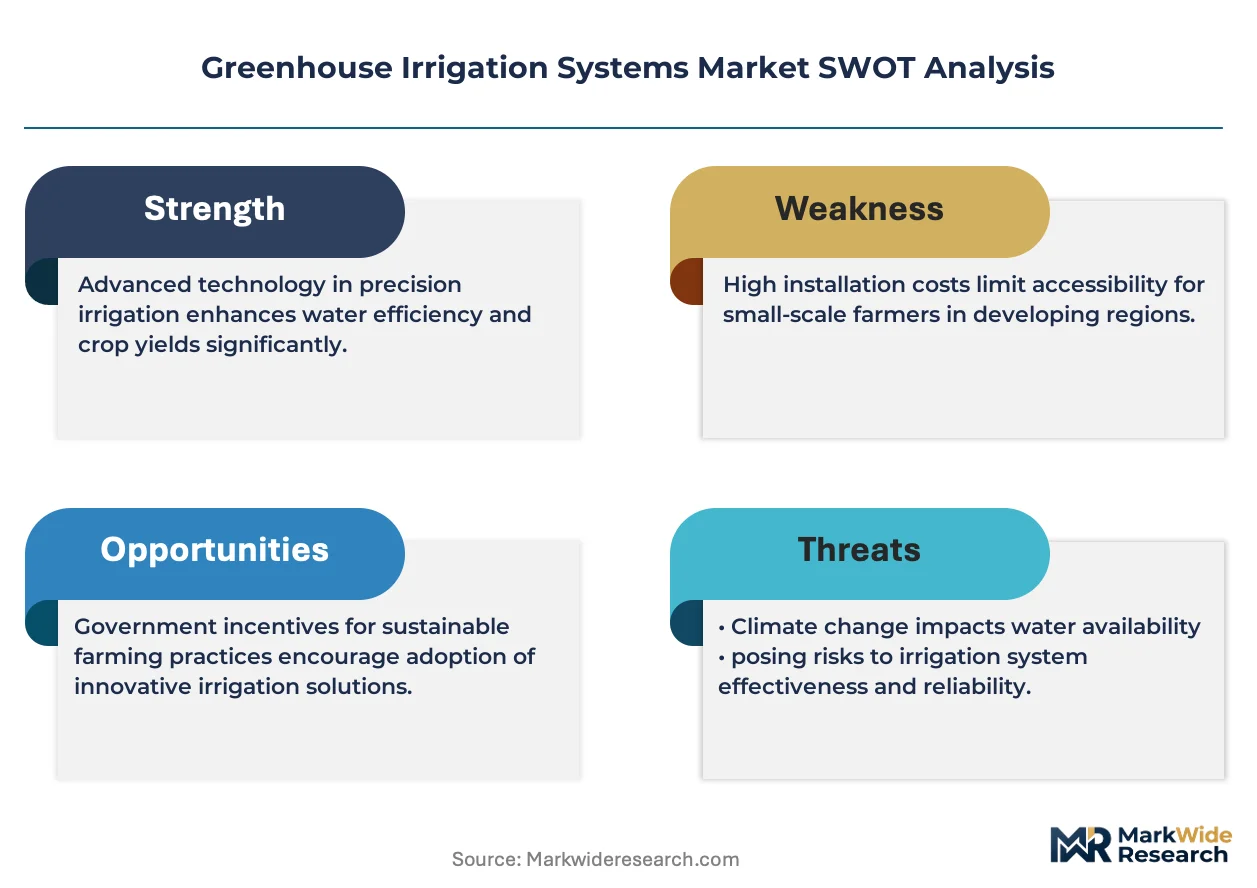
The EU Green Deal and REACH frameworks mandate reduced agricultural runoff and phased reductions in fertilizer leaching, directly shaping emitter design standards and controller certification requirements for greenhouse operators. The EPA and USDA NRCS in the United States parallel this trajectory through cost-share programs that favor water-smart irrigation retrofits in protected agriculture. Stakeholders must monitor how evolving effluent standards in major horticulture regions reshape equipment replacement cycles and service revenue models.
Market Dynamics
The EU Green Deal's water-efficiency mandates are compressing replacement cycles for legacy greenhouse irrigation infrastructure across European protected horticulture clusters. Operators face simultaneous pressure to reduce nutrient runoff while maintaining yield density in soilless cultivation systems.
Growth Catalysts
- REACH effluent standards:Phased fertilizer leaching limits force Dutch and Spanish glasshouse operators toward closed-loop fertigation architectures with real-time drainage monitoring.
- Hydroponic bench expansion:Soilless substrate adoption in Mediterranean basin protected vegetable cultivation creates compatible demand for pressure-compensated drip networks.
- Labor cost escalation:Rising agricultural wages in Israel and Morocco accelerate sensor-to-actuator automation deployments in existing greenhouse structures.
Market Restraints
- Polymer input volatility:Polyethylene and polypropylene price swings compress margin stability for emitter and tubing manufacturers dependent on petrochemical feedstocks.
- Controller firmware fragmentation:Proprietary communication protocols between irrigation hardware and climate management systems create integration friction for multi-vendor greenhouse operators.
- Filtration consumable lock-in:Disc and screen filter replacement schedules tie operators to original equipment suppliers, limiting procurement flexibility.
Strategic Opportunities
- USDA NRCS cost-share programs:EQIP water-smart irrigation incentives create favorable financing conditions for precision retrofit projects in California and Arizona protected agriculture.
- Substrate-agnostic emitter designs:Universal drip stakes compatible with rockwool, coco coir, and peat-based media reduce inventory complexity for diversified greenhouse operations.
- Wireless soil moisture mesh networks:LoRaWAN and NB-IoT connectivity standards enable retrofit sensor deployments without trenching for cable infrastructure in existing glasshouses.
Industry Challenges
- Horticultural data science talent scarcity:Greenhouse operators struggle to recruit personnel capable of interpreting sensor telemetry and calibrating irrigation setpoints for crop-specific thresholds.
- CE marking timeline compression:Evolving EU machinery directive requirements for automated irrigation controllers extend certification cycles and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Irrigation Systems Market |
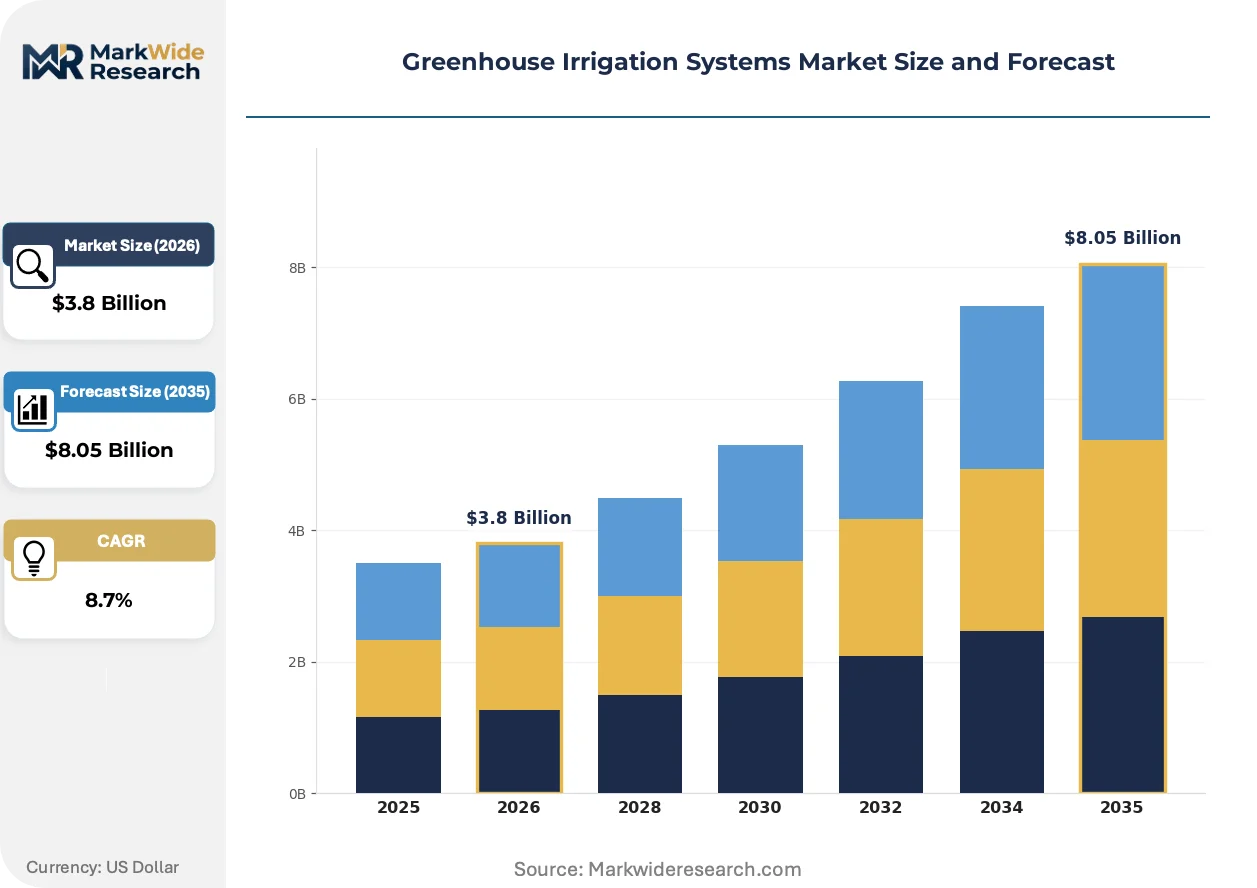
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Irrigation, Surface Irrigation, Subsurface Irrigation Technology: Smart Sensors, Automated Control Systems, Pumping Solutions, Fertigation Systems End User: Commercial Greenhouses, Research Institutes, Agricultural Producers, Home Gardens Installation: Permanent Installations, Temporary Installations, Modular Systems, Retrofit Solutions |
| Companies Covered | Jain Irrigation Systems Ltd., Irritec Inc., The Toro Company, Hunter Industries, Inc., Rain Bird Corporation, Netafim Ltd., Nelson Irrigation Corporation, Lindsay Corporation, Rivulis Irrigation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Irrigation Systems Market Strategic Shifts
Sensor-to-actuator latency reduction is compressing the performance differentiation between premium and mid-tier greenhouse irrigation controllers. Three developments are reshaping equipment specifications and procurement patterns.
Capacitive soil moisture sensing is collapsing the calibration burden that previously separated professional-grade substrate monitoring from consumer alternatives. Large-scale tomato and pepper producers in Almería and Westland are deploying factory-calibrated probes at density levels previously restricted to research stations. The technology is collapsing the service revenue model built around manual tensiometer readings and grower intuition.
EPA effluent guidelines for concentrated animal feeding operations are extending to greenhouse nutrient discharge permits in California's Central Valley. The state's regional water quality control boards now mandate drainage capture and reuse for operations above defined acreage thresholds. Protected berry and leafy green producers are responding with closed-loop fertigation systems that eliminate runoff entirely.
Subscription-based irrigation-as-a-service contracts are displacing capital purchase models among mid-scale greenhouse operators in Morocco and Turkey. Equipment suppliers retain ownership of controller hardware and charge per-hectare fees tied to growing season duration. This shift concentrates procurement authority with agronomic service providers rather than individual growers.
Greenhouse Irrigation Systems Market Segmentation
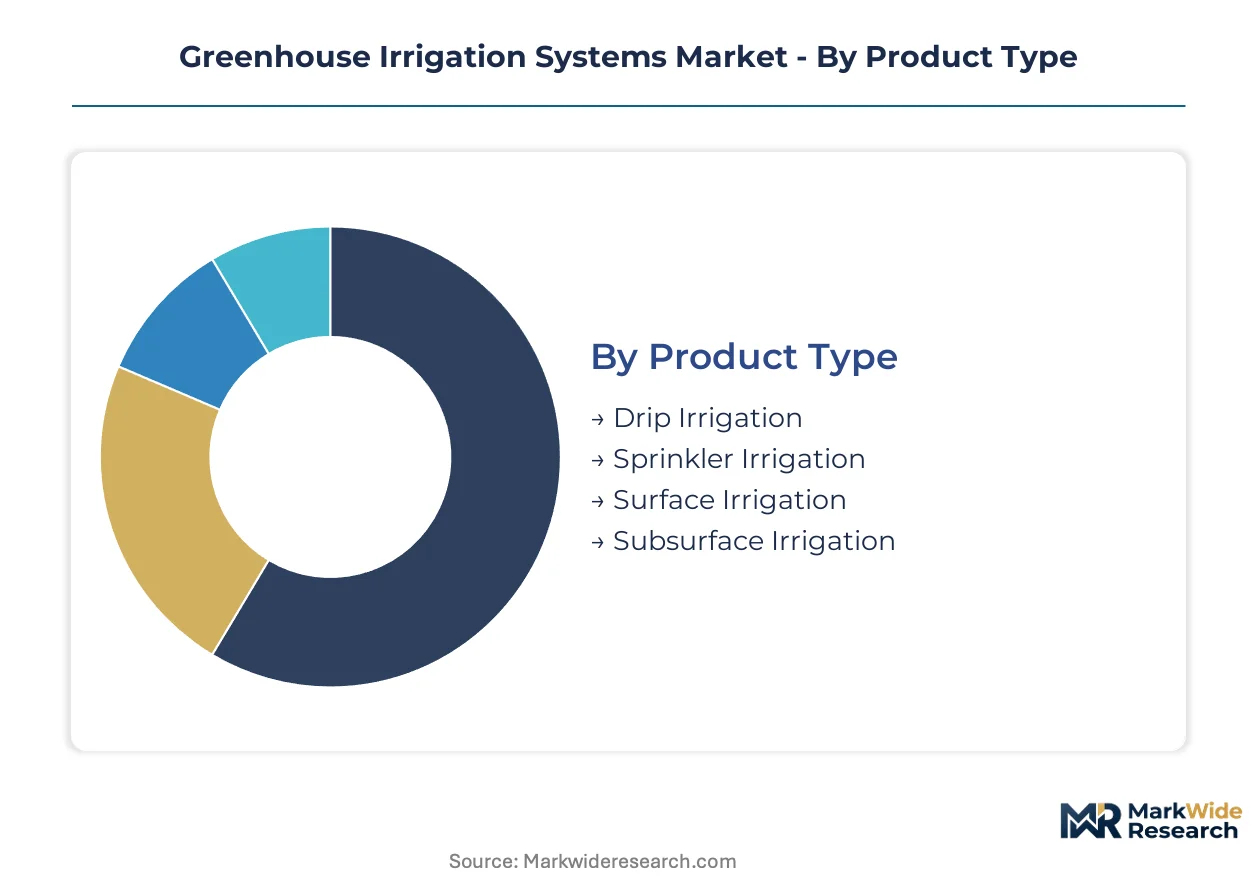
Equipment segmentation in greenhouse irrigation reveals how capital allocation priorities diverge between established protected horticulture clusters and emerging controlled-environment agriculture. Technology tier selection directly determines water-use efficiency compliance and labor substitution economics across regulatory jurisdictions.
Product Type:
Application context dictates emitter architecture selection, with substrate compatibility and pressure requirements varying sharply between soil-based and soilless cultivation systems.
- Drip Irrigation:Pressure-compensated emitters operating at 1.0-2.5 bar dominate soilless substrate applications in Almería and Westland glasshouse clusters. Dutch operators facing REACH effluent mandates are retrofitting drainage capture modules onto existing drip networks to achieve closed-loop compliance.
- Sprinkler Irrigation:Overhead misting configurations serve propagation stages and leafy green production in Israeli net-house structures. Labor cost pressures in Morocco's Souss-Massa region are accelerating automation retrofits for overhead systems previously managed manually.
- Surface Irrigation:Flood-and-drain benches retain niche deployment in research institute pilot facilities testing substrate alternatives. The method requires substantial floor space and drainage infrastructure rarely justified in commercial operations.
- Subsurface Irrigation:Capillary mat systems embedded beneath benches deliver water directly to root zones with minimal evaporation loss. Spanish tomato producers in Granada province are trialing subsurface configurations to reduce humidity-related disease pressure.
Drip irrigation commands the established base. The steepest expansion runs through subsurface configurations in water-stressed Mediterranean jurisdictions.
Technology:
Customer sophistication tier determines automation depth, with premium controllers separating climate-integrated operations from basic timer-based installations.
- Smart Sensors:Capacitive soil moisture probes with factory calibration are collapsing the performance gap between research-grade and commercial monitoring. Large-scale pepper producers in Turkey's Antalya province are deploying sensor densities previously restricted to experimental stations.
- Automated Control Systems:Sensor-to-actuator loops with sub-minute latency enable real-time setpoint adjustments for substrate moisture and electrical conductivity. Israeli operators pay premium pricing for controllers integrating directly with climate management platforms.
- Pumping Solutions:Variable-frequency drive configurations optimize energy consumption across fluctuating demand curves in multi-zone greenhouse complexes. Italian pump suppliers are bundling pressure management with filtration skids to capture retrofit opportunities.
- Fertigation Systems:Single-loop architectures consolidating irrigation and nutrient dosing reduce chemical waste and labor input. California's Central Valley berry producers are adopting closed-loop fertigation to satisfy regional water quality board discharge permits.
Automated control systems anchor premium procurement decisions. Smart sensors are climbing the fastest as calibration burdens diminish and hardware costs compress.
End User:
Volume scale and regulatory exposure create distinct procurement patterns across operator categories, from institutional research to commercial production.
- Commercial Greenhouses:Professional protected horticulture operations in the Netherlands and Spain drive demand for integrated climate-irrigation platforms. EU Green Deal water-efficiency mandates are compressing replacement cycles for legacy infrastructure across these clusters.
- Research Institutes:Experimental stations require precision dosing and data logging capabilities for cultivar development protocols. Wageningen University facilities specify equipment with research-grade telemetry export functions.
- Agricultural Producers:Mid-scale soilless vegetable operations in Morocco and Turkey are shifting toward subscription-based irrigation-as-a-service contracts to avoid capital expenditure.
- Home Gardens:Hobby-scale greenhouse operators purchase timer-based drip kits through agricultural retail channels. The segment shows minimal automation penetration due to price sensitivity and technical complexity barriers.
Commercial greenhouses concentrate revenue volume. Research institutes set specification standards that diffuse into commercial practice.
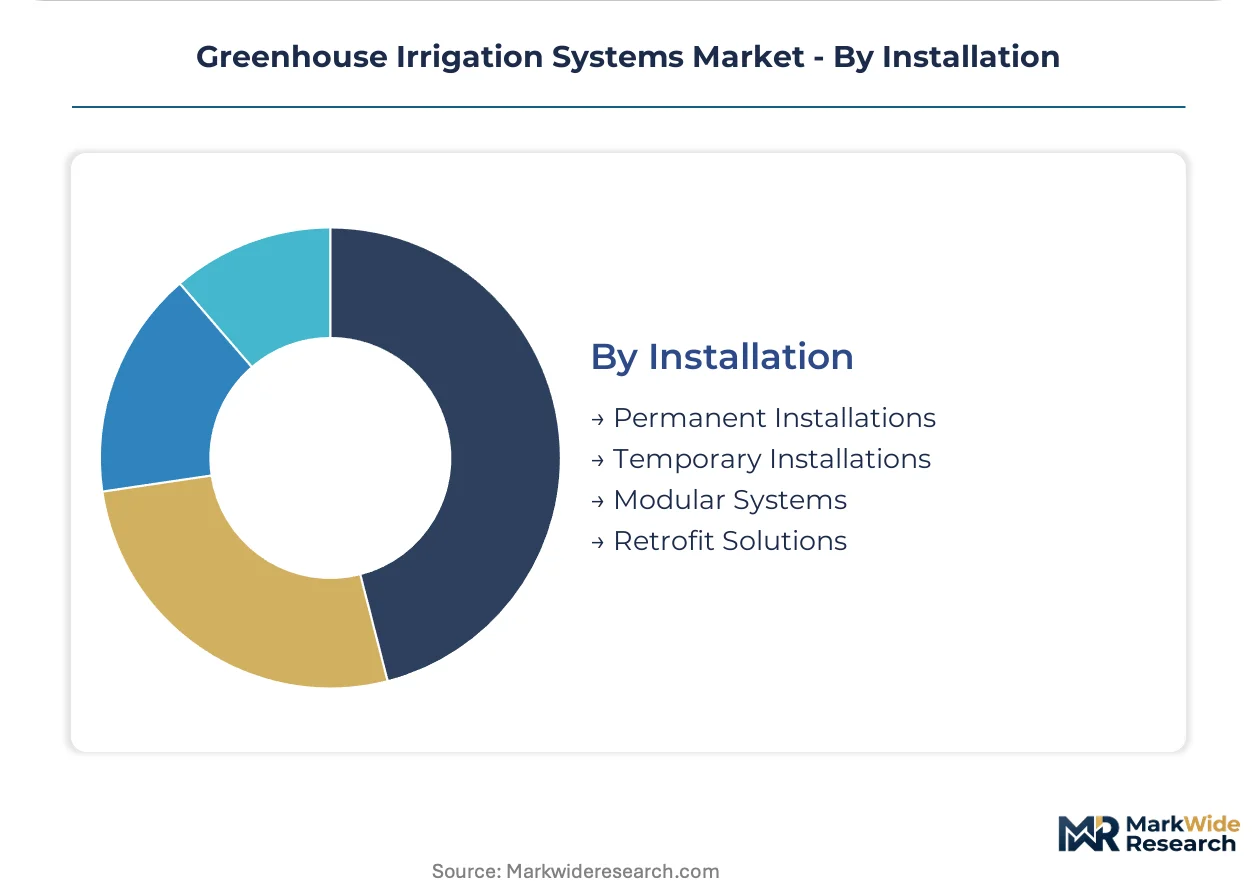
Installation:
Existing structure constraints and seasonal operational patterns determine capital deployment approach across greenhouse portfolios.
- Permanent Installations:Fixed infrastructure with embedded plumbing and electrical infrastructure serves year-round production facilities. New glasshouse construction in the Netherlands typically specifies permanent drip networks with climate controller integration.
- Temporary Installations:Seasonal field-to-greenhouse transitions in Turkey's Mediterranean coast use portable drip lines and mobile pump skids. The configuration minimizes capital commitment for operations with uncertain crop rotation schedules.
- Modular Systems:Pre-engineered skids with standardized connection points reduce installation downtime in existing structures. Rivulis Irrigation competes aggressively on modular architectures that limit operational disruption during retrofit.
- Retrofit Solutions:Wireless sensor networks and battery-powered valve controllers enable automation upgrades without trenching for cable infrastructure. LoRaWAN connectivity standards are accelerating retrofit adoption in older Spanish glasshouses with concrete floors.
Permanent installations retain the largest installed base. Retrofit solutions are expanding most quickly as labor costs rise and wireless connectivity standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial greenhouse operators in water-stressed jurisdictions drive regional demand concentration. Buyers prioritize closed-loop fertigation architectures to satisfy tightening effluent regulations. Procurement authority clusters with large-scale protected horticulture operations facing simultaneous yield and compliance pressures.
Netherlands
Westland and Aalsmeer glasshouse clusters demand integrated climate-irrigation platforms with real-time drainage monitoring. EU Green Deal water-efficiency mandates compress replacement cycles for legacy infrastructure. Dutch operators retrofit existing drip networks with capture modules to achieve closed-loop compliance under REACH phased fertilizer limits.
Spain
Almería and Granada protected vegetable producers expand pressure-compensated drip deployments across soilless substrate operations. Regional water quality boards mandate drainage reuse for operations above defined acreage thresholds. Spanish tomato producers trial subsurface capillary configurations to reduce humidity-related disease pressure in coastal greenhouses.
United States
California Central Valley berry and leafy green producers adopt closed-loop fertigation to satisfy regional water quality board discharge permits. EPA effluent guidelines extending to greenhouse nutrient discharge reshape equipment specifications. Arizona and California protected agriculture operators leverage USDA NRCS EQIP cost-share incentives for precision retrofit projects.
Israel
Negev Desert and coastal plain net-house structures automate overhead misting systems previously managed manually. Rising agricultural wages accelerate sensor-to-actuator deployments across existing greenhouse portfolios. Israeli operators pay premium pricing for controllers integrating directly with climate management platforms.
Morocco
Souss-Massa region protected horticulture shifts toward subscription-based irrigation-as-a-service contracts to avoid capital expenditure. Labor cost pressures drive automation retrofits in seasonal field-to-greenhouse transitions. Equipment suppliers retain controller ownership and charge per-hectare fees tied to growing season duration.
Greenhouse Irrigation Systems Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base separates into irrigation heritage firms with drip emitter legacies, climate-platform integrators, and modular retrofit specialists. Two strategic archetypes dominate: vertically integrated manufacturers with captive polymer supply, and service-layer bundlers offering subscription-based equipment access. Competitive moves concentrate on backward integration into filtration assembly and wireless connectivity standardization.
Among heritage drip specialists, Netafim Ltd. and Jain Irrigation Systems Ltd. occupy positions shaped by manufacturing scale and polymer extrusion control. Rivulis Irrigation Ltd. exemplifies the modular retrofit archetype with architectures limiting operational disruption. These three anchors represent distinct competitive vectors: emitter heritage, vertical manufacturing integration, and installation-flexible system design.
| Leading Market Players |
|---|
| Jain Irrigation Systems Ltd. |
| Irritec Inc. |
| The Toro Company |
| Hunter Industries, Inc. |
| Rain Bird Corporation |
| Netafim Ltd. |
| Nelson Irrigation Corporation |
| Lindsay Corporation |
| Rivulis Irrigation Ltd. |
| Others |
Value Chain & Pricing Dynamics
Israeli polymer compounding facilities supplying polyethylene and polypropylene feedstocks anchor upstream cost structures, concentrating margin capture with emitter and tubing manufacturers possessing captive extrusion capabilities or long-term offtake arrangements with petrochemical suppliers.
Pricing Analysis
Cost-plus contracts with ethylene and propylene indexation dominate procurement between polymer suppliers and irrigation equipment manufacturers. Pricing stratifies across premium climate-integrated controllers, standard automated systems, and economy timer-based installations. Cost compression in mid-tier hardware is intensifying because capacitive sensor commoditization erodes calibration-service margins. Agricultural producers in Morocco and Turkey exhibit highest price sensitivity, favoring subscription-based irrigation-as-a-service contracts over capital purchases.
Supply Chain Analysis
Export control restrictions on precision sensor technology and wireless communication modules limit component flows from certain jurisdictions to greenhouse irrigation controller manufacturers. Supply concentrates in Israel for drip emitter innovation, Italy for pump and filtration skids, and China for polymer extrusion and basic controller assembly. The chain draws from petrochemical feedstocks, precision electronics, and filtration media. Single-source vulnerability runs through semiconductor components for sensor-to-actuator loops. Distribution runs through agronomic service providers and direct OEM sales to large greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greenhouse irrigation systems sit in early-cycle expansion as EU Green Deal water-efficiency mandates force replacement of legacy infrastructure across European protected horticulture clusters.
For Market Incumbents: Harden polymer supply security through backward integration into extrusion capabilities or locked-in offtake agreements with Israeli and Saudi petrochemical suppliers. Deepen climate platform integration to defend against modular retrofit specialists capturing upgrade cycles in existing glasshouse structures. For New Entrants and Emerging Players: Pursue wireless retrofit automation in Spain's aging Almería and Granada greenhouse portfolios, where concrete floors obstruct trenching for cable infrastructure. Target subscription-based service contracts in Morocco's Souss-Massa region, positioning against capital-constrained mid-scale producers through per-hectare seasonal fee structures. For Investors and Strategic Acquirers: Capital is best deployed toward modular retrofit specialists with LoRaWAN-enabled architectures and established service-layer bundling capabilities. The long-term viability window favors equipment-as-a-service models that concentrate recurring revenue and lock in consumable filter replacement schedules. Watch for inflection when regional water quality boards in California and Arizona extend drainage capture mandates to smaller acreage thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captures margin pools from petrochemical volatility and secures emitter supply continuity. |
| Climate Platform Integration Partnership | Netafim and Rivulis compete for direct API connections with Priva and Ridder climate controllers. |
| Subscription-Based Irrigation-as-a-Service Launch | Morocco's Souss-Massa operators avoid capital expenditure while suppliers retain hardware ownership. |
| Wireless Retrofit Sensor Network Deployment | LoRaWAN standards enable automation upgrades in Spanish glasshouses without concrete floor trenching. |
| Closed-Loop Fertigation System Certification | California Central Valley berry producers satisfy Regional Water Quality Control Board discharge permits. |
Study Parameters
The analysis maps drip irrigation, sprinkler systems, subsurface configurations, and fertigation architectures, each validated through greenhouse operations managers, agronomic service providers, climate controller integration specialists, and polymer procurement leads at equipment manufacturers. Primary interview findings triangulate against customs trade data for polyethylene and polypropylene flows, SEC filings from listed irrigation equipment suppliers, EU Green Deal implementation progress reports, and USDA NRCS EQIP disbursement records. Bottom-up equipment shipment estimates reconcile with top-down water-efficiency compliance spending projections.
Assumptions held fixed include REACH phased fertilizer leaching limits proceeding on announced schedules, capacitive soil moisture sensor calibration costs continuing their decline curve, and wireless connectivity standards maturing without protocol fragmentation. The model segments by product type, technology tier, end-user category, and installation approach across the projection horizon. CAGRs derive from replacement cycle compression analysis under regulatory mandate scenarios and labor cost elasticity estimates for automation adoption. Forecast inputs include greenhouse construction permits in Almería and Westland clusters and NRCS cost-share program enrollment trends.
Macroeconomic conditions sit as an overlay; deviation in agricultural wage inflation trajectories, petrochemical price volatility, or interest rate environments affecting capital expenditure decisions would shift the trajectory. Material shifts in EU machinery directive certification timelines or EPA effluent guideline scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Agriculture Logistics Market