
 Global Irrigation Automation Market | 2026-2036
Global Irrigation Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Irrigation Automation Market Foresight
Israeli drip-irrigation specialists is broadening the upstream component base for automated water-delivery systems. Netafim leverages polymer science expertise to sustain dominance in emitter manufacturing. Jain Irrigation Systems Ltd. anchors South Asian market presence through extensive dealer networks. The Toro Company differentiates via golf-course automation portfolios in North America.
Irrigation automation encompasses electromechanical systems that regulate water distribution through soil-moisture feedback loops, pressure-compensated emitters, and programmable logic controllers operating at 12-24V DC. These systems reduce applied water volumes by enabling variable-rate application aligned to crop evapotranspiration coefficients. Sensor-based automation technology leads product development intensity, while AI-driven platforms represent the fastest-expanding margin pool. Controllers and valves capture the largest installed-base revenue share, though soil moisture sensors are penetrating new crop categories fastest.
EPA water-quality standards and the EU F-Gas Regulation shape equipment specifications for outdoor electromechanical systems across multiple jurisdictions. FDA's FSMA produce safety rules indirectly drive precision-irrigation investment by linking water-source documentation to harvest compliance. China's MEE enforces irrigation-efficiency benchmarks in water-stressed northern provinces. Stakeholders must monitor how fragmented national water-rights frameworks alter payback calculations for capital-intensive automation retrofits.
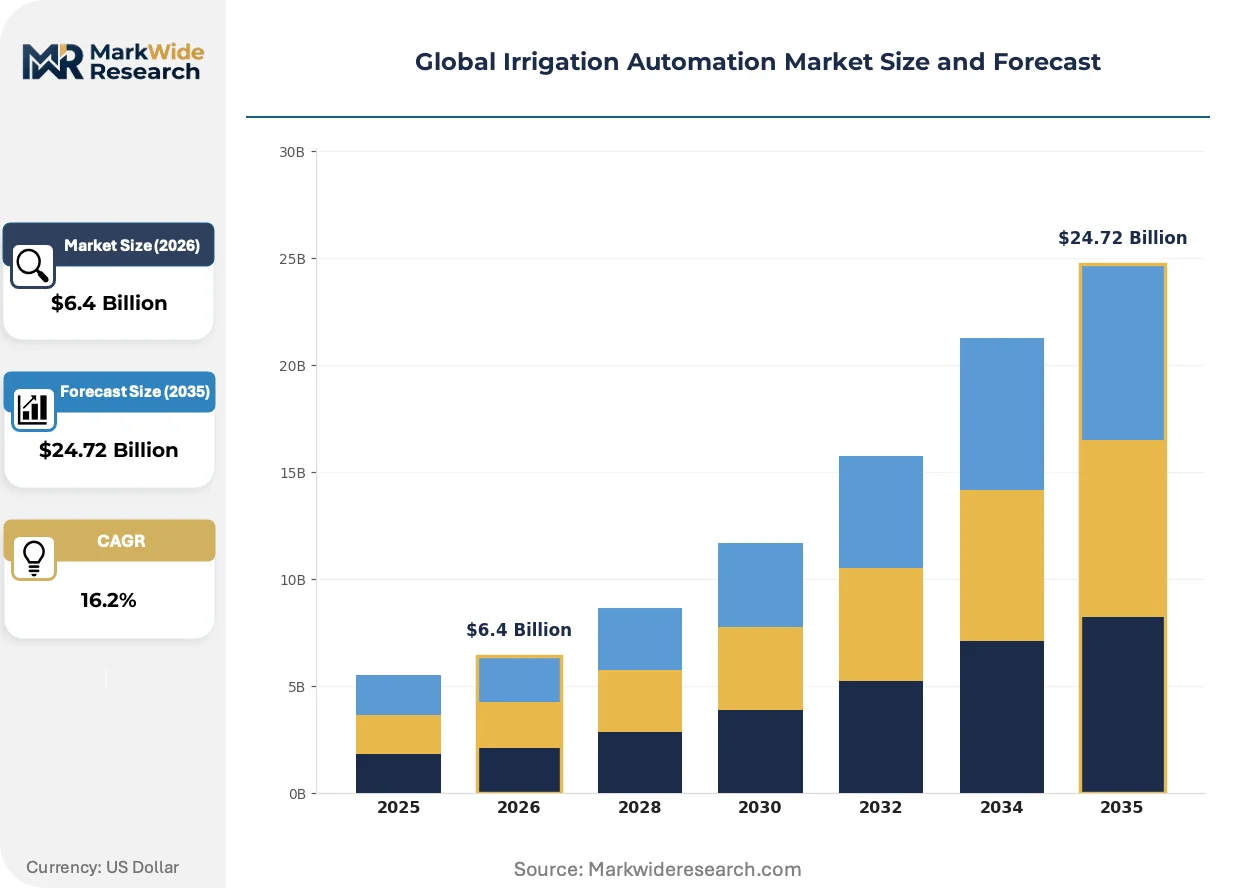
Market Dynamics
The EU Green Deal's water-efficiency mandates are compressing hardware replacement cycles across European agricultural equipment fleets, forcing capital reallocation toward sensor-integrated automation platforms ahead of natural depreciation schedules.
Growth Catalysts
- Basin-wide allocation reforms:Australia's Murray-Darling Basin water trading reforms favor precision delivery systems that document volumetric compliance in real-time, accelerating sensor deployment across cotton and almond operations.
- Produce safety documentation:FDA's FSMA rules indirectly pull precision-irrigation investment by linking water-source traceability to harvest compliance, particularly in leafy green supply chains.
- Polymer science advances:Pressure-compensated emitter manufacturing improvements enable uniform flow distribution across undulating terrain, expanding addressable acreage in California's Central Valley.
Market Restraints
- Copper and semiconductor input volatility:Programmable logic controllers and solenoid valves depend on copper windings and silicon components subject to supply dislocation, compressing margin predictability for system integrators.
- Dealer network concentration:South Asian market access routes through fragmented distributor tiers create working capital intensity for equipment vendors seeking rural penetration.
- Legacy 12V DC infrastructure:Existing field wiring in mature irrigation districts limits upgrade pathways to higher-voltage sensor arrays without trenching costs.
Strategic Opportunities
- Northern China efficiency benchmarks:China's MEE irrigation-efficiency mandates in water-stressed provinces create compliance-driven demand for soil-moisture feedback systems in wheat and maize belts.
- AI-driven platform convergence:Machine learning crop models integrating satellite evapotranspiration data with ground sensor networks open recurring revenue streams beyond hardware installation.
- Golf-course automation portfolios:Turf management's precision requirements offer margin refuge from commodity crop price cycles, with North American clubs leading subscription-based controller adoption.
Industry Challenges
- Agronomy-software integration talent:Field deployment of automated systems requires personnel fluent in both hydraulic engineering and crop science, a combination scarce in rural labor markets.
- Fragmented water-rights documentation:Basin-specific allocation rules complicate payback calculations for capital-intensive retrofits, delaying purchase decisions in jurisdictions with unsettled entitlement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Irrigation Automation Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $24.72 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
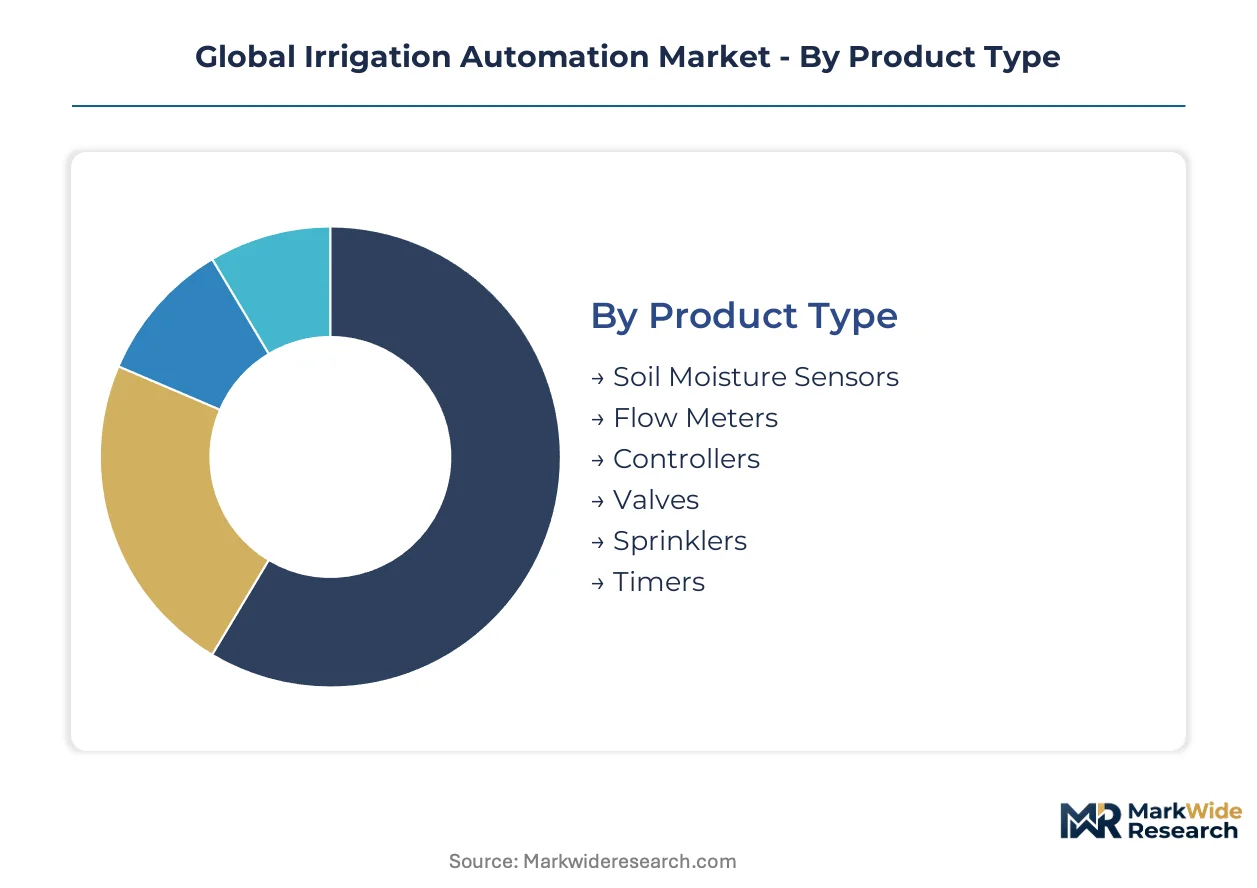
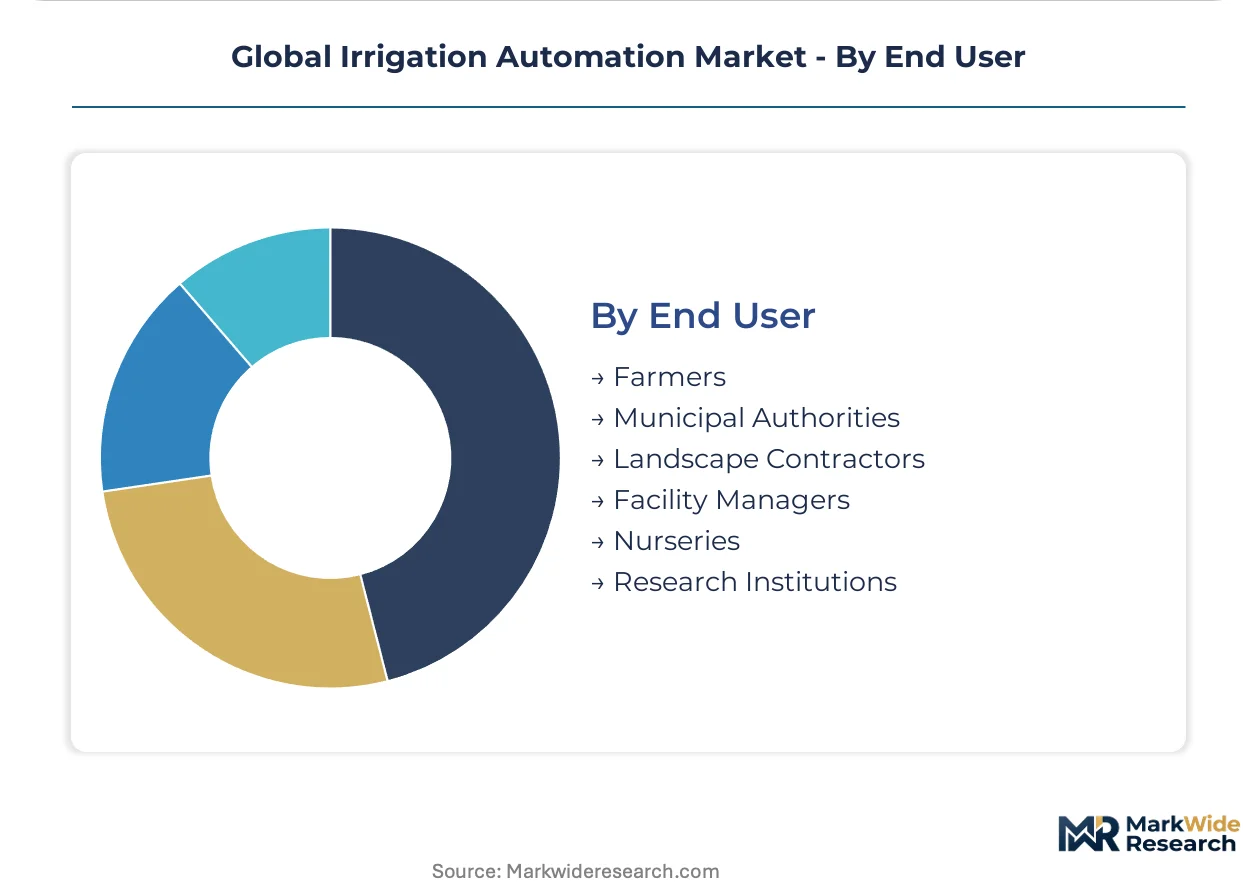
| Segmentation | Product Type: Soil Moisture Sensors, Flow Meters, Controllers, Valves, Sprinklers, Timers Automation Technology: Remote Control, Sensor-based, AI-driven, Weather-based, Timer-based, Manual Override Application: Crop Farming, Golf Courses, Parks, Greenhouses, Landscaping, Sports Turf End User: Farmers, Municipal Authorities, Landscape Contractors, Facility Managers, Nurseries, Research Institutions |
| Companies Covered | Valmont Industries, Inc., The Toro Company, Netafim, Lindsay Corporation, Jain Irrigation Systems Ltd., Rain Bird Corporation, Hunter Industries, Nelson Irrigation Corporation, Galcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Irrigation Automation Market Shifts & Advancements
Digital agriculture platforms are compressing the feedback loop between field sensing and valve actuation, replacing time-based irrigation schedules with biometric crop response models that recalibrate hourly.
Sensor-based automation technology is overtaking timer-driven controllers across high-value perennial crops. Almond and vineyard operators in California's Central Valley are retrofitting pressure-compensated drip lines with capacitance soil probes and cellular telemetry. This shift is compressing equipment vendor margins on standalone timers while expanding recurring revenue from cloud-based analytics subscriptions.
REACH substance restrictions and the EU F-Gas Regulation are reshaping electromechanical specifications for outdoor automation hardware. Manufacturers must reformulate polymer formulations and eliminate specific refrigerant-based cooling systems from valve actuator designs. Specialty crop equipment suppliers serving Dutch greenhouse clusters are accelerating compliance redesigns ahead of enforcement deadlines.
Buyers in Australia's Murray-Darling Basin are consolidating procurement decisions through irrigation service cooperatives rather than individual farm capital budgets. These aggregators negotiate system-wide sensor deployments across multiple holdings, displacing single-farm vendor relationships. Cotton growers in New South Wales are leading this behavioral shift, pooling telemetry infrastructure to share basin-wide allocation data.
Global Irrigation Automation Market Segmentation
Segmentation in irrigation automation reveals how hardware specifications, control intelligence, and user economics fragment procurement decisions across agricultural, recreational, and institutional settings. Each dimension carries distinct margin structures and replacement-cycle dynamics that reshape vendor positioning.
Product Type:
Supply concentration in emitter manufacturing and controller assembly creates divergent margin pools across component categories.
- Controllers:Programmable logic units operating at 12-24V DC coordinate valve actuation and sensor feedback loops. California's Central Valley almond operations drive demand for multi-zone units with cellular telemetry integration. Copper winding costs and semiconductor availability constrain margin predictability for system integrators.
- Soil Moisture Sensors:Capacitance and tensiometric probes measure volumetric water content and matric potential at root-zone depths. Australia's Murray-Darling Basin cotton growers deploy these for real-time allocation compliance documentation. Sensor-based automation technology leads product development intensity in this segment.
- Valves:Pressure-compensated solenoid units regulate flow distribution across undulating terrain.
- Flow Meters:Ultrasonic and electromagnetic devices measure volumetric delivery for billing and compliance.
- Sprinklers:Gear-driven and impact heads distribute water across field crops and turf applications.
- Timers:Electromechanical and digital scheduling units represent legacy infrastructure with shrinking replacement demand.
Today's leader: Controllers. Tomorrow's challenger: Soil Moisture Sensors.
Automation Technology:
Cost tier differentiation separates capital-intensive retrofits from low-entry control upgrades across farm sizes.
- Sensor-based:Soil-moisture feedback loops trigger valve actuation when thresholds breach crop-specific setpoints. High-value perennial crops in California's Central Valley favor these systems for water-stress avoidance. AI-driven platforms represent the fastest-expanding margin pool building on this foundation.
- AI-driven:Machine learning models integrate satellite evapotranspiration data with ground sensor networks for predictive irrigation scheduling. North American golf courses adopt subscription-based analytics platforms for turf management precision.
- Remote Control:Cellular and radio-frequency interfaces enable off-site system management.
- Weather-based:Evapotranspiration calculations adjust schedules using local meteorological data.
- Timer-based:Fixed-interval programming dominates low-value annual crop applications.
- Manual Override:Emergency bypass functions maintain operational continuity during system failures.
Sensor-based systems anchor current installed value. AI-driven platforms capture the steepest expansion trajectory.
Application:
Volume concentration in commodity crop farming contrasts with margin refuge in precision turf management.
- Crop Farming:Large-scale field operations deploy drip lines, center pivots, and linear move systems across wheat, maize, cotton, and almond acreage. China's MEE irrigation-efficiency benchmarks in northern provinces pull sensor adoption in water-stressed regions.
- Golf Courses:Turf management's exacting moisture requirements sustain premium controller pricing. North American clubs lead subscription-based automation adoption, insulating vendors from commodity crop price cycles.
- Greenhouses:Controlled-environment agriculture demands precision fertigation and humidity management.
- Parks:Municipal irrigation systems balance water conservation with aesthetic maintenance.
- Landscaping:Commercial and residential installation services specify mid-tier controller packages.
- Sports Turf:Stadium and training facility managers prioritize playability and recovery timing.
Crop farming commands installed-base volume. Golf courses defend margin per acre.
End User:
Customer type fragmentation shapes procurement channel economics and service bundling requirements.
- Farmers:Individual operators and cooperative members evaluate payback periods against water savings and yield protection. Australia's Murray-Darling Basin irrigation service cooperatives consolidate procurement across multiple holdings, displacing single-farm vendor relationships.
- Municipal Authorities:Parks departments and water districts specify open-protocol systems for multi-site management.
- Landscape Contractors:Installation and maintenance firms specify mid-tier packages for commercial clients.
- Facility Managers:Corporate and institutional campuses balance sustainability reporting with operational reliability.
- Nurseries:Container and field operations require precision moisture control for transplant survival.
- Research Institutions:Agricultural universities and extension services deploy experimental sensor arrays.
Farmers dominate unit volume. Municipal authorities standardize procurement protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment sourcing patterns as manufacturers relocate assembly to jurisdictions with streamlined electromechanical compliance regimes, compressing landed costs for sensor-integrated systems.
United States
California's Central Valley almond and vineyard operators drive sensor-based retrofit demand amid chronic water scarcity. EPA water-quality standards and FDA FSMA produce safety rules mandate documented water-source traceability. Fresno County and Kern County clusters concentrate precision-drip deployments with cellular telemetry integration.
China
Northern province wheat and maize belts face tightening irrigation-efficiency mandates from MEE. China's dual carbon goals accelerate hardware replacement in water-stressed regions. The Beijing-Tianjin-Hebei corridor anchors domestic controller manufacturing capacity expansion.
Australia
Murray-Darling Basin cotton growers consolidate procurement through irrigation service cooperatives for real-time allocation compliance. Basin-wide water trading reforms favor precision delivery systems with volumetric documentation. New South Wales operations lead telemetry infrastructure pooling across multiple holdings.
Germany
Dutch greenhouse cluster suppliers accelerate REACH substance compliance redesigns for valve actuator polymer formulations. EU F-Gas Regulation eliminates refrigerant-based cooling from outdoor electromechanical specifications. Baden-Württemberg precision engineering firms supply pressure-compensated emitter components.
Israel
Drip-irrigation specialists broaden upstream polymer science capabilities for automated water-delivery systems. National water-efficiency imperatives dating to the 1950s sustain emitter manufacturing expertise. Netafim anchors global emitter supply from central district production facilities.
Global Irrigation Automation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven analytics subscriptions and satellite-data integration partnerships. The vendor base stratifies across three tiers: integrated irrigation systems providers, component specialists in emitter and valve manufacturing, and software-centric platform developers. Dominant competitive moves include backward integration into polymer formulation capabilities and strategic partnerships with cellular telemetry providers to secure recurring revenue streams beyond hardware installation.
Within the integrated systems tier, Valmont Industries, Inc. and Lindsay Corporation exemplify scale-driven equipment vendors with pivot irrigation manufacturing heritage. Netafim occupies a distinctive position as an emitter technology anchor, representing the specialist archetype that backward-integrated into polymer science capabilities. Jain Irrigation Systems Ltd. sits within the emerging-market access tier, exemplifying distributors leveraging extensive dealer networks for South Asian penetration. These three archetypes—scale-integrated, technology-specialist, and geography-focused—capture divergent margin pools across hardware and recurring revenue segments.
| Leading Market Players |
|---|
| Valmont Industries, Inc. |
| The Toro Company |
| Netafim |
| Lindsay Corporation |
| Jain Irrigation Systems Ltd. |
| Rain Bird Corporation |
| Hunter Industries |
| Nelson Irrigation Corporation |
| Galcon |
| Others |
Supply & Pricing Matrix
Irrigation service cooperatives in Australia's Murray-Darling Basin anchor procurement volume and negotiate system-wide deployments, compressing channel margins while elevating subscription-based analytics as the dominant pricing model for precision water-delivery systems.
Pricing Analysis
Distributor margins on hardware components face compression as direct procurement by cooperative aggregators displaces tiered dealer markups. Three-tier pricing structure across premium cellular-telemetry controllers, standard programmable logic units, and economy timer-based systems separates subscription-bundled offerings from transactional equipment sales. Cost compression in copper-wound solenoid valves is intensifying because semiconductor supply dislocation feeds into controller manufacturing. Price sensitivity concentrates among commodity crop operators in South Asia, while North American golf courses defend premium tier willingness-to-pay.
Supply Chain Analysis
Dual-sourcing requirements for pressure-compensated emitters and polymer formulations are emerging as large-scale operators in California's Central Valley mandate supplier qualification redundancy. Manufacturing concentrates in Israel for emitter technology, the United States for controller assembly, and China for valve actuator components. Raw material dependencies span copper windings, silicon semiconductors, and specialized polymer resins. Single-source vulnerability in semiconductor supply for programmable logic units threatens production continuity. Distribution runs through irrigation service cooperatives in Australia, fragmented dealer networks in South Asia, and direct OEM relationships in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in irrigation automation rests on AI-driven platform convergence that transforms hardware installation revenue into recurring analytics subscriptions, compressing customer acquisition costs while elevating lifetime value per acre under management.
For Market Incumbents: Extend backward integration into polymer formulation capabilities to secure captive supply of pressure-compensated emitters against raw material volatility. Deepen cellular telemetry partnerships to lock in recurring revenue streams before emerging software-centric platform developers displace hardware-centric positioning. Prioritize certification investment for EU F-Gas Regulation compliance ahead of enforcement deadlines affecting valve actuator designs. For New Entrants and Emerging Players: Irrigation service cooperatives represent the most penetrable channel archetype for bypassing fragmented dealer tiers in South Asia and Australia. Target white-space opportunities in China's northern province wheat and maize belts where MEE efficiency mandates create compliance-driven demand without entrenched incumbent relationships. Pursue satellite-data integration partnerships as the go-to-market angle for AI-driven crop modeling differentiation. For Investors and Strategic Acquirers: Precision agriculture technology divisions of diversified industrial conglomerates are the most active acquirer in this space, seeking sensor-integrated automation platforms to complement existing equipment portfolios. Long-term viability favors vendors with recurring revenue density exceeding hardware replacement cycles. Acquisition target archetype: software-centric platform developers with machine learning crop models and established cellular telemetry infrastructure. Watch for basin-wide water allocation reform announcements as the signal indicating accelerated capital deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Netafim's emitter manufacturing dominance demonstrates captive supply advantages in pressure-compensated technology. |
| AI-Driven Platform Development | Machine learning crop models integrating satellite evapotranspiration data open recurring revenue beyond hardware installation. |
| Cellular Telemetry Partnership | Real-time volumetric compliance documentation satisfies Australia's Murray-Darling Basin allocation reform requirements. |
| EU Regulatory Compliance Redesign | REACH substance restrictions and F-Gas Regulation mandate polymer reformulation for valve actuator outdoor specifications. |
| Irrigation Service Cooperative Engagement | Procurement consolidation across multiple holdings in Australia displaces single-farm vendor relationships and compresses channel economics. |
Research Methodology
Multiple input streams — primary interviews with irrigation equipment executives, agronomists at almond and vineyard operations, procurement leads at irrigation service cooperatives, and regulatory affairs specialists — were reconciled against secondary validation from EPA water-quality filings, EU F-Gas regulatory documentation, MEE efficiency benchmark disclosures, and customs trade data for polymer and semiconductor components. Bottom-up triangulation across component-level bill-of-materials analysis and top-down reconciliation with basin-wide water allocation records anchored volume and value estimates.
Data-stream reconciliation across product type, automation technology tier, application segment, and end-user archetype fed into the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle compression, regulatory mandate timelines, and technology adoption curve modeling specific to sensor-based feedback systems and AI-driven platform penetration. Industry-specific forecast inputs included basin-wide allocation reform implementation schedules and cellular telemetry infrastructure deployment rates.
Revisions become necessary when copper and semiconductor supply dislocations intensify, EU enforcement timelines for F-Gas Regulation accelerate, or China's MEE efficiency benchmarks expand beyond northern provinces. Deviation in basin-specific water-rights documentation clarity would shift capital-intensive retrofit payback calculations and delay purchase decisions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Fertigation Control System Market