
 Africa Agricultural Irrigation Machinery Market | 2026-2036
Africa Agricultural Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Agricultural Irrigation Machinery Market Outlook
Trained irrigation technician availability is rotating toward deficit in East African markets while North African training institutes produce surplus graduates. Netafim Limited leverages its drip irrigation specialization to dominate high-value export crop zones. Valmont Industries anchors center-pivot sales across South African commercial grain operations. Lindsay Corporation competes through localized manufacturing partnerships that reduce import lead times for replacement components.
Africa agricultural irrigation machinery comprises engineered systems designed to apply controlled water volumes to crops through pressurized networks, surface channels, or subsurface emitters, typically operating at pressures between 0.5 and 10 bar depending on technology configuration. These systems serve the primary commercial purpose of stabilizing yields against rainfall variability while enabling cultivation of water-intensive cash crops in arid and semi-arid agro-ecological zones. Drip irrigation captures premium margin pools among horticulture exporters who require precise fertigation integration, while sprinkler systems retain volume leadership across extensive cereal production landscapes. Automated control systems represent the fastest-expanding technology segment as cellular connectivity penetration enables remote valve management for dispersed smallholder cooperatives.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces water-use licensing that restricts unmonitored extraction from stressed catchments, directly elevating demand for metered precision irrigation technologies. Ethiopia's Ministry of Water and Energy mandates efficiency standards for pumped systems that favor low-pressure technology adoption across state-led irrigation schemes. Kenya's Water Resources Authority imposes abstraction charges calibrated to consumption volumes, creating financial incentives for subsurface irrigation investments that minimize evaporative losses. Stakeholders must monitor how national water pricing reforms reshape total cost-of-ownership calculations across different technology configurations.
Market Dynamics
Climate-induced water scarcity across the Sahel and Horn of Africa is forcing commercial farms to abandon rain-fed cultivation, triggering wholesale replacement of flood irrigation with pressurized precision systems that meter every liter extracted from declining aquifers.
Growth Catalysts
- Ethiopia's Awash Valley horticulture expansion:Large-scale flower and vegetable export zones require drip fertigation systems to meet EU phytosanitary standards for water residue limits.
- Kenya Water Resources Authority abstraction charges:Volume-based tariffs on pumped groundwater create immediate payback calculations for subsurface drip investments that cut evaporative losses by half.
- Solar PV cost compression:Photovoltaic module prices enable off-grid pumping without diesel dependency, unlocking irrigation for smallholder cooperatives beyond grid extension.
Market Restraints
- Steel and polymer input volatility:Center-pivot manufacturing depends on galvanized steel and polyethylene resin, both subject to import tariff fluctuations in African customs unions.
- Spare parts supply concentration:Precision emitter nozzles and pressure regulators ship primarily from Israeli and Italian production facilities, creating 12-16 week lead times for East African distributors.
- Low-pressure system mandates:Ethiopia's Ministry of Water and Energy efficiency standards technically exclude high-pressure sprinkler architectures from state procurement tenders.
Strategic Opportunities
- Rwanda's hillside irrigation gap:Terraced smallholder plots remain 90% rain-fed, presenting unmet demand for portable micro-sprinkler kits with gravity-fed tank integration.
- Cellular-enabled automation convergence:Integration of IoT soil moisture sensors with mobile payment platforms allows cooperative managers to trigger valve clusters remotely without on-site technicians.
- South African water-use licensing:Department of Agriculture restrictions on unmonitored extraction from the Orange River catchment mandate flow-metered systems, creating compliance-driven replacement cycles.
Industry Challenges
- Certified technician scarcity:East African markets face acute deficit of pressure system diagnosticians, while North African training institutes produce surplus graduates who emigrate to Gulf states.
- Legacy flood irrigation infrastructure:Existing canal networks in Sudan's Gezira Scheme require complete hydraulic redesign to accommodate pressurized distribution, doubling effective capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Agricultural Irrigation Machinery Market |
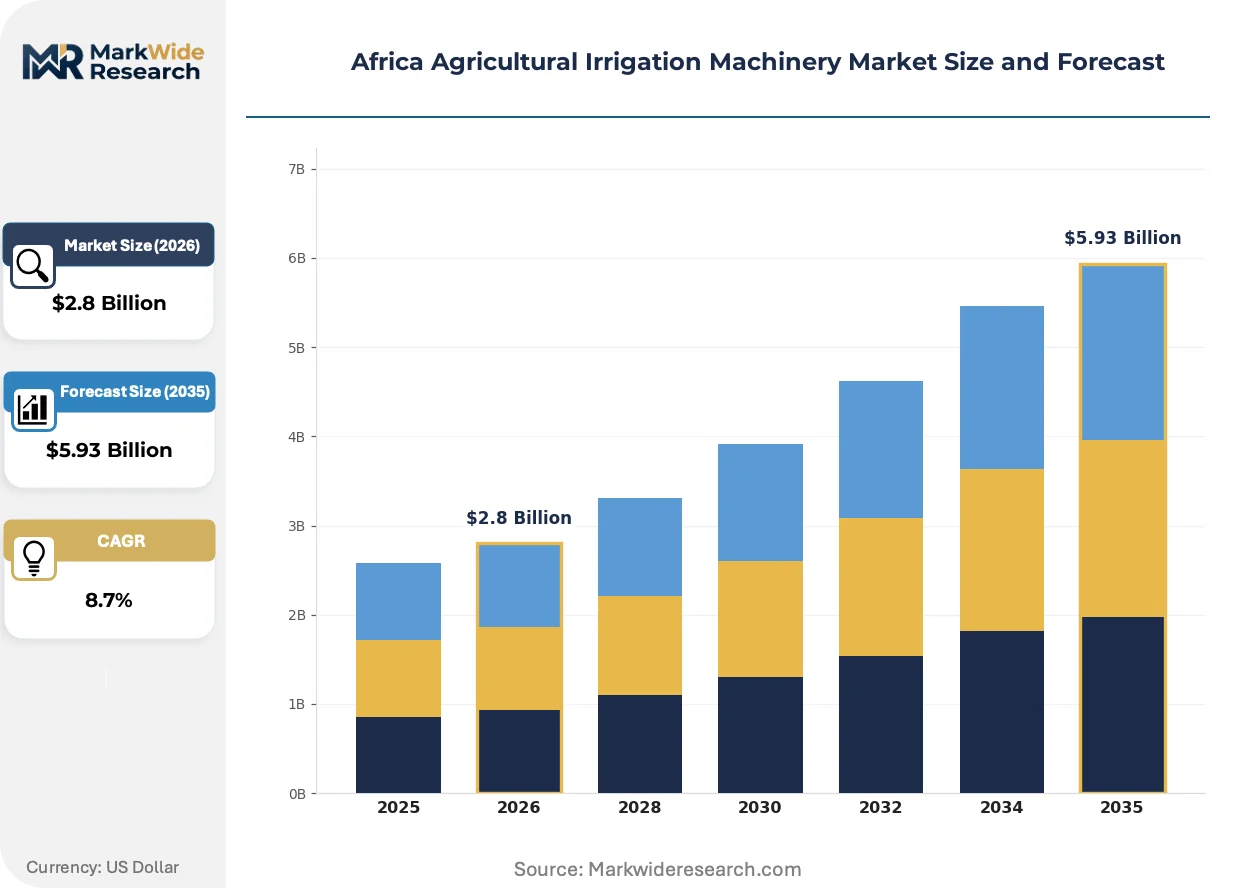
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation Technology: Automated Systems, Pumping Solutions, Control Systems, Low-Pressure Technology End User: Commercial Farms, Smallholder Farmers, Cooperatives, Agricultural Enterprises Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Agricultural Shows |
| Companies Covered | Netafim Limited, Valmont Industries, Lindsay Corporation, Rain Bird Corporation, Rivulis Irrigation, Nelson Irrigation Corporation, Jain Irrigation Systems Ltd, Deere & Company, The Toro Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Agricultural Irrigation Machinery Market Strategic Shifts
Solar-powered pumping hardware is converging with digital control layers to create autonomous irrigation nodes that operate without grid connection or on-site supervision, compressing the viable farm size for mechanized water delivery.
Subsurface drip emitter technology is miniaturizing flow passages to sub-one-liter-per-hour rates while maintaining clog resistance through labyrinthine turbulent flow paths. High-value avocado and macadamia orchards in Kenya's Meru County are adopting these ultra-low-flow configurations to match root-zone uptake rates precisely. The structural consequence is displacement of traditional micro-sprinkler grids in tree crop applications where canopy wetting risks fungal disease.
South Africa's Department of Agriculture, Land Reform and Rural Development water-use licensing framework now requires real-time extraction telemetry for commercial abstraction permits. This mandate forces retrofit of flow meters and automated shutoff valves onto existing pump stations. Grain operations in the Western Cape are responding by bundling meter installation with full control system upgrades rather than piecemeal compliance.
Smallholder cooperatives are consolidating equipment procurement through aggregator platforms that pool demand across hundreds of farms for volume pricing on shared pivot systems. Kenya's horticultural export clusters around Naivasha and Thika are piloting cooperative ownership models where irrigation assets rotate seasonally between member plots. This shared-infrastructure approach is displacing individual smallholder pump purchases where capital constraints previously limited penetration.
Africa Agricultural Irrigation Machinery Market Segmentation
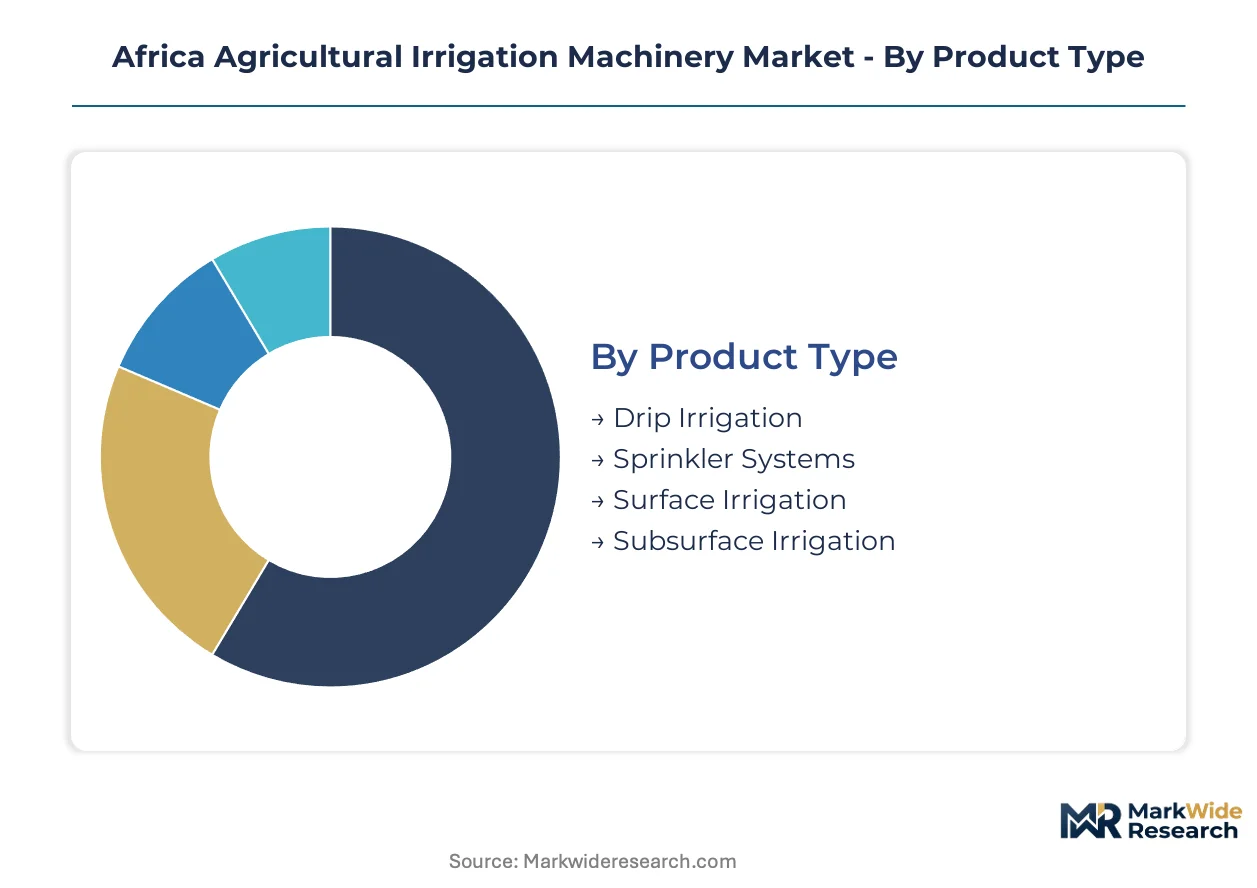
Technology choice in African irrigation machinery directly determines capital recovery timelines and operational flexibility across diverse agro-ecological zones. Segmentation reveals where equipment suppliers capture premium pricing versus where volume sales dominate procurement patterns.
Product Type:
Margin pools concentrate in precision delivery technologies that reduce water abstraction costs for commercial exporters facing volume-based tariffs.
- Drip Irrigation:Pressurized networks with emitters operating at 0.5-2 bar deliver water directly to root zones through polyethylene laterals. Ethiopia's Awash Valley flower exporters deploy these systems to meet EU phytosanitary residue limits while cutting pumping energy by half. The dominant share belongs to Drip Irrigation, while Sprinkler Systems is closing the gap fastest.
- Sprinkler Systems:Center-pivot and lateral-move architectures distribute water through overhead nozzles at 2-4 bar operating pressure. South African commercial grain operations in the Western Cape favor these for extensive cereal coverage where uniform application trumps precision.
- Surface Irrigation:Gravity-fed canal and furrow systems remain prevalent in Sudan's Gezira Scheme despite hydraulic inefficiency. Legacy infrastructure locks in flood irrigation where capital constraints prevent pressurized retrofits.
- Subsurface Irrigation:Buried emitter lines at 20-40 centimeter depth eliminate evaporative losses entirely. Kenya's Water Resources Authority abstraction charges make this technology economically viable for groundwater-dependent horticulture clusters around Naivasha.
Technology selection tracks water scarcity severity and regulatory pressure on extraction volumes.
Technology:
Cost tiers separate basic mechanical systems from digitally integrated platforms commanding 3-4x hardware premiums.
- Automated Systems:IoT-enabled valve clusters with cellular connectivity allow remote operation without on-site technicians. Kenyan smallholder cooperatives pilot these where aggregator platforms pool demand across hundreds of farms for shared infrastructure. Automated Systems holds the revenue concentration, while Low-Pressure Technology is expanding most quickly.
- Pumping Solutions:Solar PV-driven submersible and surface pumps eliminate diesel dependency for off-grid operations. Photovoltaic module cost compression unlocks irrigation beyond grid extension for dispersed smallholders.
- Control Systems:Programmable logic controllers manage pressure, flow, and filtration sequencing. South Africa's water-use licensing mandates real-time extraction telemetry, forcing retrofit installations.
- Low-Pressure Technology:Gravity-fed and minimal-energy distribution architectures comply with Ethiopia's Ministry of Water and Energy efficiency standards. State procurement tenders technically exclude high-pressure alternatives.
Regulatory efficiency mandates and solar cost curves are accelerating technology substitution timelines.
End User:
Customer type dictates equipment scale, financing mechanisms, and service intensity requirements.
- Commercial Farms:Large-scale operations with dedicated technical staff deploy full automation and precision fertigation. South African grain estates and Ethiopian horticulture zones anchor equipment demand volumes. Commercial Farms commands procurement value, while Cooperatives is gaining share fastest.
- Smallholder Farmers:Individual plots under 5 hectares face capital constraints limiting penetration to portable kits and shared pump arrangements. Rwanda's hillside terraces present unmet demand for gravity-fed micro-sprinkler solutions.
- Cooperatives:Aggregated smallholder groups consolidate equipment procurement through rotating seasonal ownership models. Kenya's Thika horticulture clusters pilot shared pivot systems.
- Agricultural Enterprises:Investor-backed farming ventures with professional management deploy capital-intensive center-pivot and drip networks at scale.
Cooperative ownership models are displacing individual smallholder purchases where capital access remains constrained.
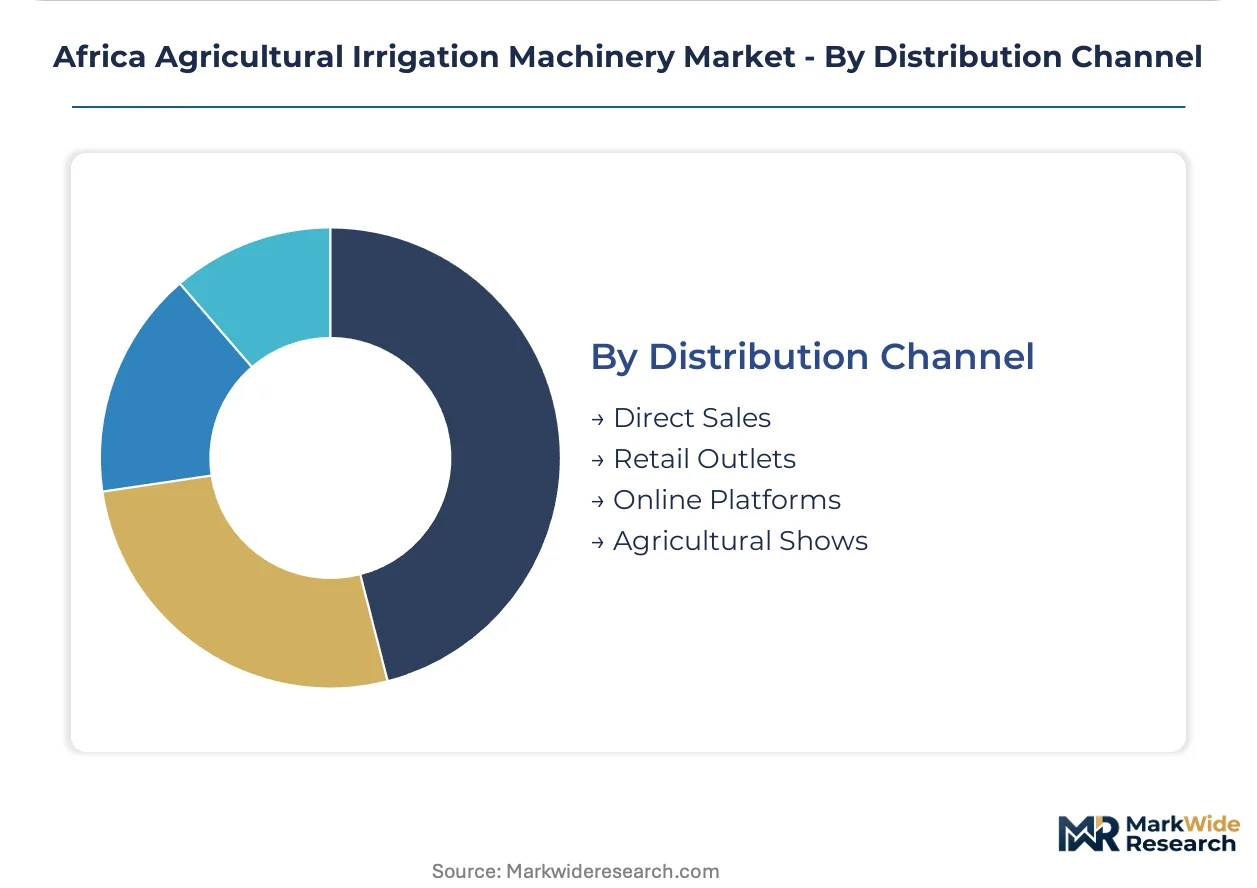
Distribution Channel:
Supply chain configuration determines spare parts availability and technical support reach.
- Direct Sales:Manufacturer-to-farm transactions for large commercial installations include design, installation, and maintenance bundling. Netafim Limited and Valmont Industries deploy technical teams for complex system commissioning. Direct Sales dominates transaction value, while Online Platforms is climbing the fastest.
- Retail Outlets:Agricultural equipment dealers stock standard pump and component inventories for immediate replacement needs. East African distributors face 12-16 week lead times for precision emitters from Israeli and Italian production facilities.
- Online Platforms:Digital procurement channels emerge for standardized solar pump kits and portable irrigation components. Mobile payment integration enables cooperative managers to trigger equipment purchases remotely.
- Agricultural Shows:Seasonal exhibitions facilitate equipment demonstrations and financing program enrollment for smallholder aggregations.
Channel mix shifts toward direct technical engagement for complex systems and digital platforms for standardized hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's Department of Agriculture, Land Reform and Rural Development anchors the continent's regulatory framework for commercial irrigation through water-use licensing mandates. This policy architecture cascades across national jurisdictions with varying enforcement intensity.
South Africa
The Western Cape grain belt and Limpopo horticulture zones drive center-pivot and drip system procurement. The Department of Agriculture, Land Reform and Rural Development requires real-time extraction telemetry for commercial abstraction permits. Grain operations near Ceres retrofit flow meters with full control system upgrades to maintain compliance.
Ethiopia
State-led irrigation schemes in the Awash Valley anchor demand for low-pressure precision systems serving flower and vegetable exporters. The Ministry of Water and Energy mandates efficiency standards that technically exclude high-pressure sprinkler architectures from public tenders. Large-scale horticulture projects around Adama deploy drip fertigation networks to meet EU phytosanitary residue limits.
Kenya
Horticulture clusters around Naivasha and Thika concentrate equipment demand among avocado and macadamia producers. The Water Resources Authority imposes volume-based abstraction charges on pumped groundwater that accelerate subsurface drip adoption. Smallholder cooperatives pilot shared pivot ownership models with seasonal rotation between member plots.
Sudan
The Gezira Scheme retains extensive flood irrigation infrastructure despite hydraulic inefficiency. National water pricing reforms remain stalled, limiting capital recovery timelines for pressurized retrofits. Canal network redesign requirements around Wad Madani double effective capital needs for mechanized system adoption.
Rwanda
Terraced hillside plots remain predominantly rain-fed, creating latent demand for portable micro-sprinkler solutions. The national agricultural transformation agenda prioritizes irrigation expansion but capital constraints limit individual smallholder purchases. Gravity-fed tank integration pilots in the Northern Province test kit-based distribution models.
Africa Agricultural Irrigation Machinery Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that fragments across technology configurations and geographic coverage. The upper tier commands premium positioning through bundled design-installation-maintenance offerings for commercial estates. Specialist players occupy narrower niches in drip emitter manufacturing, solar pumping hardware, or regional distribution networks. Competitive moves concentrate on localized manufacturing partnerships that compress import lead times and cooperative procurement platforms that aggregate smallholder demand.
Within the integrated systems tier, Netafim Limited and Valmont Industries exemplify divergent geographic anchoring strategies. Netafim represents the precision delivery archetype with specialization in drip irrigation networks. Valmont occupies the extensive mechanization position through center-pivot and lateral-move architectures. Lindsay Corporation sits within the regional manufacturing partnership model, leveraging distributed fabrication to reduce replacement component lead times for East African distributors.
| Leading Market Players |
|---|
| Netafim Limited |
| Valmont Industries |
| Lindsay Corporation |
| Rain Bird Corporation |
| Rivulis Irrigation |
| Nelson Irrigation Corporation |
| Jain Irrigation Systems Ltd |
| Deere & Company |
| The Toro Company |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-sixteen-week lead times for precision emitter nozzles from Israeli and Italian production facilities concentrate pricing power with integrated distributors who maintain regional buffer inventories. East African farm cooperatives absorb premium markups on replacement components while South African commercial estates negotiate direct manufacturer relationships that bypass tariff-laden import channels.
Pricing Analysis
Price spreads between premium drip fertigation systems and economy sprinkler kits widen across Ethiopian state procurement corridors versus Kenyan smallholder cooperatives. Three-tier pricing structure across premium, standard, and economy levels segments buyers by after-sales service bundling and installation complexity. Cost compression in solar PV modules is intensifying price competition among pumping solution providers. Smallholder aggregations exhibit acute price sensitivity, while Ethiopian horticulture exporters prioritize precision over unit economics.
Supply Chain Analysis
Inventory concentration for galvanized steel center-pivot components rests on South African fabrication hubs and Chinese polymer resin suppliers. Manufacturing draws from Israeli emitter technology, Italian pressure regulator designs, and East Asian photovoltaic cell production. Single-source vulnerability permeates precision nozzle supply where replacement orders queue at original production facilities. Distribution runs through direct technical engagement for complex systems and agricultural equipment dealers for standardized pump inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cooperative procurement platforms fragment demand aggregation across hundreds of smallholder farms, creating service niches for specialized distributors who bridge capital constraints with shared infrastructure models.
For Market Incumbents: Compound technical service capabilities through certified technician training institutes in East African deficit zones where North African graduate emigration drains local supply. Anchor spare parts warehousing in Nairobi and Addis Ababa to compress replacement lead times threatening customer retention. Defend against solar-integrated entrants by bundling legacy pump retrofits with cellular automation layers. For New Entrants and Emerging Players: CE marking fast-track for low-pressure gravity-fed kits unlocks Rwanda's hillside terrace segment where 90% of plots remain rain-fed. Target Kenyan Water Resources Authority compliance-driven replacement cycles with subsurface drip configurations that halve evaporative losses. Pursue cooperative aggregator partnerships as the primary go-to-market channel rather than individual farm sales. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents with irrigation divisions lacking geographic focus or digital integration capabilities. Five-to-ten-year viability hinges on cellular-enabled automation convergence and solar cost curves continuing to compress viable farm sizes. Monitor Ethiopia's Ministry of Water and Energy efficiency standard enforcement as the inflection signal for low-pressure technology substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Partnership | Lindsay Corporation's distributed fabrication model reduces replacement component lead times for East African distributors. |
| Certified Technician Training Program | Netafim Limited's technical institutes address acute diagnostician scarcity threatening system uptime in Kenyan horticulture zones. |
| Cooperative Procurement Platform | Shared pivot ownership models displace individual smallholder purchases where capital constraints previously limited penetration. |
| Solar-Integrated Pump Retrofit | Photovoltaic module cost compression unlocks off-grid irrigation beyond grid extension for dispersed smallholders. |
| Cellular Automation Integration | IoT soil moisture sensors with mobile payment platforms enable remote valve management without on-site technicians. |
Study Parameters
Desk research of customs trade databases, national water authority regulatory filings, and agricultural machinery import records preceded structured interviews with irrigation system distributors, cooperative procurement managers, commercial farm operations directors, and Ministry of Water and Energy officials. Primary fieldwork across Ethiopia's Awash Valley, Kenya's Naivasha horticulture clusters, and South Africa's Western Cape grain belt validated secondary demand estimates. Bottom-up equipment procurement tallies triangulated against top-down sectoral water abstraction licensing data.
Variance decomposition across technology segments, end-user categories, and national regulatory frameworks shaped the analytical approach over the projection horizon. Modeled dimensions include product type configuration, automation technology tier, cooperative versus commercial ownership structure, and distribution channel intensity. CAGRs derived from equipment replacement cycle analysis, regulatory mandate implementation timelines, and solar PV cost curve extrapolation. Forecast inputs incorporated Ethiopian state irrigation scheme expansion schedules and Kenyan Water Resources Authority tariff escalation pathways.
Decision-makers should treat outputs as directional under assumptions of continued solar module cost compression and stable national water pricing reform trajectories; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market