
 Weed Trimmer Market | 2026-2036
Weed Trimmer Market Size, Share, and Industry Trends Forecast 2026-2036
Weed Trimmer Market Analytics
Brushless motor electrification is reshaping weed trimmer engineering by eliminating carbon brushes, reducing thermal losses, and enabling precise electronic speed control. Stihl leverages its captive engine foundry network to sustain gas-powered dominance in professional forestry and municipal channels. Husqvarna anchors its position through battery platform standardization across trimmers, blowers, and chainsaws, creating ecosystem lock-in for landscape contractors. Ego competes on high-voltage architecture, differentiating its 56V battery system from the 18V-40V mainstream.
A weed trimmer is a handheld or robotic vegetation management device employing a rotating monofilament line, fixed blade, or flail head to sever grasses and woody stems at controlled heights, typically operating at 3,000-12,000 RPM depending on power source and cutting attachment. The equipment serves residential lawn maintenance, commercial landscaping, highway verge management, and precision agriculture border clearing. Battery-powered units are capturing the fastest growth trajectory as lithium-ion energy density improvements extend runtime beyond 45 minutes at professional duty cycles, though gas-powered systems still occupy the highest torque segments for brush-cutting applications. Robotic trimmers remain nascent, with margin pools concentrated in sensor fusion and autonomous navigation software rather than mechanical hardware.
EPA Phase 3 small nonroad engine standards and California Air Resources Board (CARB) evaporative emissions regulations are forcing two-stroke engine redesigns or outright platform abandonment, directly accelerating electric alternative adoption. The EU F-Gas Regulation and REACH chemical restrictions on fuel additives further constrain gas-powered equipment market access across European member states. Stakeholders must monitor battery recycling mandates from the EU Battery Regulation and emerging right-to-repair legislation in multiple US states, as these frameworks will determine aftermarket parts economics and product lifecycle profitability.
Market Dynamics
Brushless motor electrification and EPA Phase 3 small nonroad engine standards are converging to force a platform transition from two-stroke gas systems to battery-powered architectures across professional and residential segments.
Growth Catalysts
- Lithium-ion energy density gains:Cell chemistry improvements now deliver 45+ minute runtime at professional duty cycles, erasing the performance gap with gas alternatives for grass trimming applications.
- EPA Phase 3 and CARB evaporative emissions rules:Compliance costs for two-stroke engine redesigns push manufacturers toward electric platform development, accelerating retail shelf space reallocation.
- Urban green space maintenance budgets:Municipalities in the United States, Germany, and China are expanding groundskeeping contracts, driving fleet refresh cycles among landscape contractors.
Market Restraints
- Cobalt and lithium carbonate price volatility:Battery pack input costs fluctuate with mining supply disruptions, compressing margin stability for mid-tier electric trimmer producers.
- Brushless motor controller supply concentration:Semiconductor fabrication for high-efficiency motor drives clusters in East Asian foundries, exposing brands to geographic supply risk.
- Torque limitations for brush-cutting:Gas-powered systems retain dominance in woody stem applications above 15mm diameter where battery voltage architectures under 60V deliver insufficient cutting force.
Strategic Opportunities
- Robotic perimeter navigation:Sensor fusion and RTK-GPS positioning enable autonomous trimmer deployment for golf course rough maintenance and solar farm vegetation management.
- Battery platform standardization:Ecosystem lock-in across trimmers, blowers, and chainsaws creates recurring revenue streams from charger and cell pack attachment sales.
- EU Battery Regulation recycling mandates:Early compliance with end-of-life collection and black mass recovery requirements positions brands for preferential market access across member states.
Industry Challenges
- Power electronics firmware development:Brushless motor control algorithms require embedded systems expertise scarce among legacy gas-engine engineering teams, forcing talent acquisition or external partnership.
- Dual inventory complexity:Retailers and distributors must simultaneously stock gas, corded electric, and battery-powered SKUs, straining warehouse space and working capital allocation during the transition window.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weed Trimmer Market |
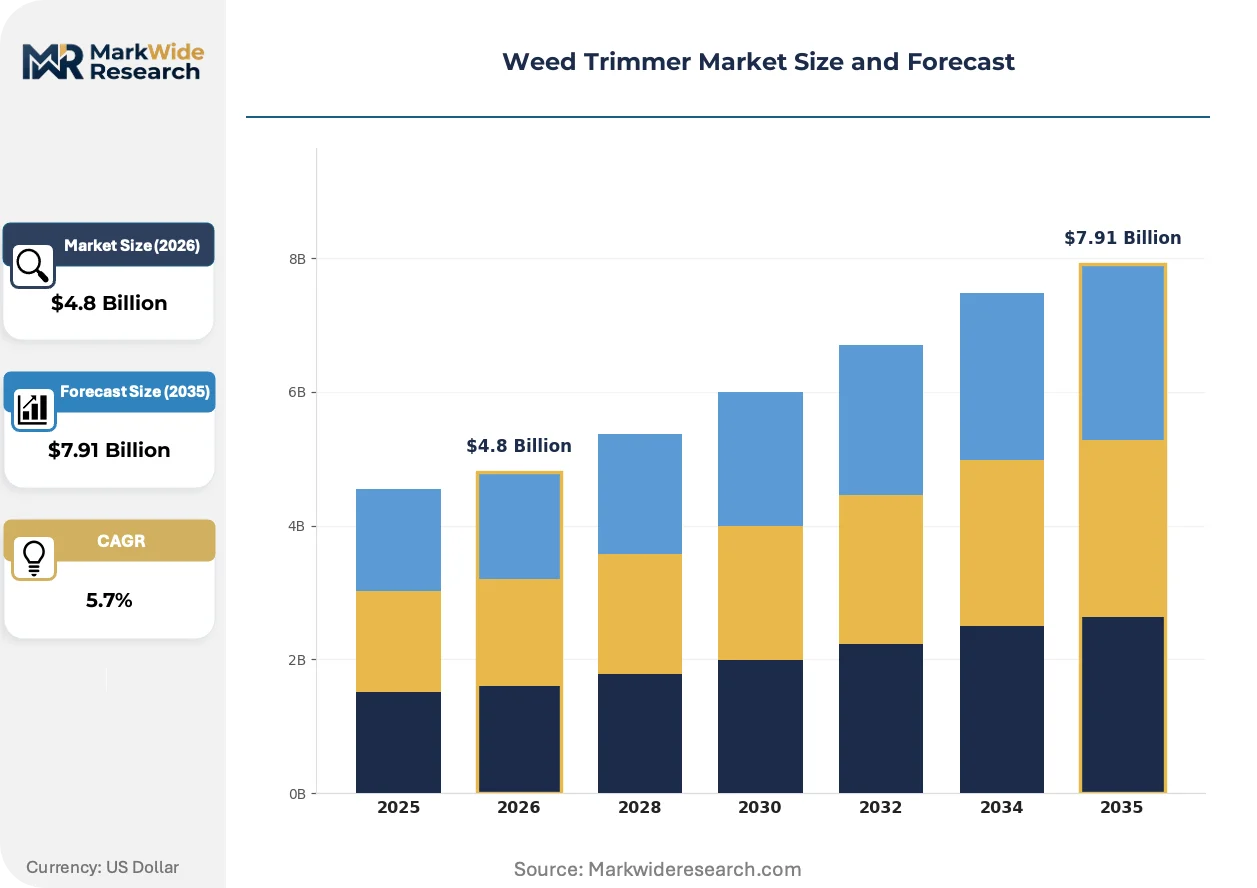
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded Electric, Battery-Powered, Gas-Powered, Robotic End User: Residential, Commercial, Landscape Professionals, Government Technology: Brushless Motor, Brush Motor, Manual, Hybrid Distribution Channel: Online Retail, Hardware Stores, Home Improvement Centers, Specialty Stores |
| Companies Covered | Stihl, Echo, Husqvarna, DeWalt, Greenworks, Ego, Worx, RedMax, Shindaiwa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weed Trimmer Market Evolving Landscape
Electrification is rewriting product architecture while regulatory deadlines compress development timelines. Three distinct vectors are reshaping competitive positioning: motor technology migration, emissions compliance mechanics, and contractor procurement behavior.
High-voltage battery architectures are migrating from niche professional use toward mainstream residential channels. Ego's 56V platform demonstrated that elevated voltage delivers gas-comparable torque without the weight penalties of earlier 18V-40V systems. Homeowners with quarter-acre lots now specify voltage ratings as a primary purchase filter, forcing retailers to reconfigure shelf layouts by power platform rather than brand.
REACH chemical restrictions on fuel additives and the EU F-Gas Regulation are eliminating gas-powered equipment market access across European member states. Manufacturers face divergent compliance pathways: redesign two-stroke engines for evaporative emissions control or abandon the architecture entirely. Landscape contractors in Germany and France are responding by accelerating battery fleet conversion ahead of regulatory deadlines.
Service bundling is reshaping how commercial buyers acquire vegetation management capability. Municipalities and property management firms now specify equipment-plus-maintenance contracts rather than capital purchase, transferring uptime risk to OEMs or their dealer networks. This shift is most visible in United States metropolitan markets where facilities outsourcing has compressed in-house groundskeeping staff.
Weed Trimmer Market Segmentation
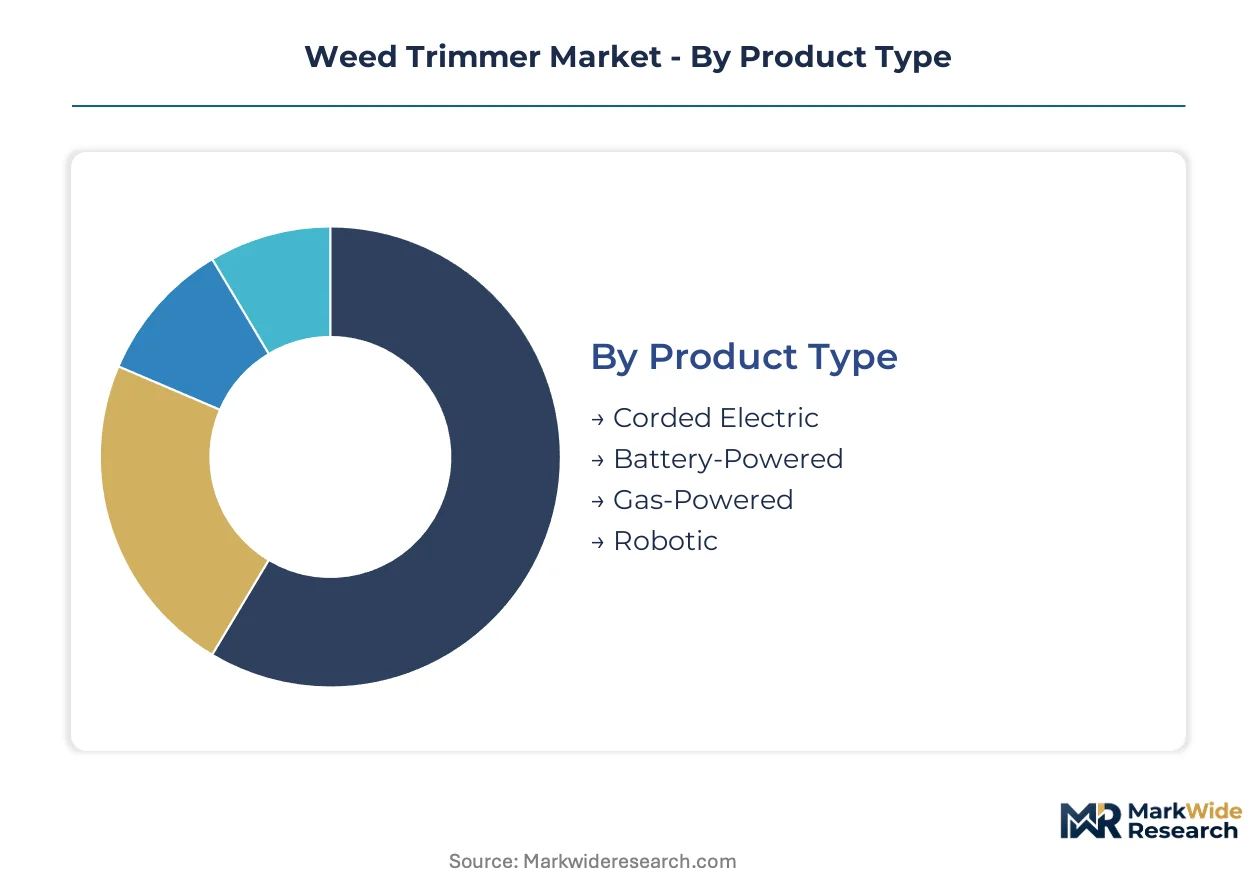
Weed trimmer segmentation reveals divergent margin structures and service intensity requirements across power platforms and buyer categories. Equipment type determines warranty exposure, spare parts velocity, and dealer training investments.
Product Type:
After-sales-service intensity varies sharply across power architectures, with battery platforms generating recurring revenue from cell pack replacement while gas systems demand seasonal tune-up programs.
- Battery-Powered:Lithium-ion cell architectures operating at 18V-80V with brushless motor drives dominate professional fleet refresh cycles. Landscape contractors in the United States specify these units for municipal groundskeeping contracts where noise ordinances restrict gas equipment operation.
- Gas-Powered:Two-stroke and four-stroke internal combustion engines deliver sustained torque for brush-cutting applications above 15mm stem diameter. Germany's commercial forestry sector retains gas dominance where battery runtime limitations interrupt extended clearing operations.
- Corded Electric:AC-powered motors with unlimited runtime serve residential users with small, contiguous lots and accessible outdoor power outlets. China accounts for concentrated manufacturing of these cost-optimized units.
- Robotic:Autonomous units with RTK-GPS navigation and perimeter sensing target golf course rough maintenance and solar farm vegetation management. Sensor fusion software and autonomous path planning algorithms constitute the primary value capture mechanism.
By volume, Battery-Powered leads. By growth pace, Robotic is ahead.
End User:
Procurement sophistication separates buyer tiers, with commercial accounts negotiating fleet pricing and service bundling while residential purchases respond to retail promotional calendars.
- Residential:Homeowners maintaining lawns under 0.5 acres prioritize weight reduction and storage footprint over runtime specifications. Battery platform standardization across yard tools influences brand selection.
- Commercial:Property management firms and facilities outsourcing contractors specify equipment-plus-maintenance contracts transferring uptime risk to OEM dealer networks. United States metropolitan markets exhibit concentrated procurement of these bundled service agreements.
- Landscape Professionals:Independent contractors and regional landscaping companies operate mixed fleets requiring cross-platform technician training and parts inventory. CARB compliance deadlines are accelerating electric conversion timelines.
- Government:Municipal parks departments and highway maintenance agencies issue multi-year procurement contracts with domestic content requirements and emissions compliance stipulations. EPA Phase 3 standards reshape specification criteria.
Residential purchases dominate unit volume. Commercial contracts generate the steepest expansion trajectory in value terms.
Technology:
Power electronics expertise is concentrating competitive advantage, with motor controller firmware determining thermal efficiency and battery runtime optimization.
- Brushless Motor:Electronic commutation eliminates carbon brush friction losses and enables precise RPM modulation via field-oriented control algorithms. Professional-grade trimmers deploy this architecture exclusively.
- Brush Motor:Mechanical commutation with carbon brushes persists in entry-level corded units where cost minimization overrides efficiency targets. Replacement brush sets sustain aftermarket parts revenue.
- Manual:Human-powered cutting mechanisms serve niche applications including noise-restricted zones and precision border edging where motorized equipment risks plant damage.
- Hybrid:Dual-power architectures combining battery electric drive with range-extending gas generators remain experimental, targeting commercial users with intermittent heavy-load requirements.
Brushless Motor commands professional segment revenue. Hybrid architectures are climbing the fastest from negligible base deployment.
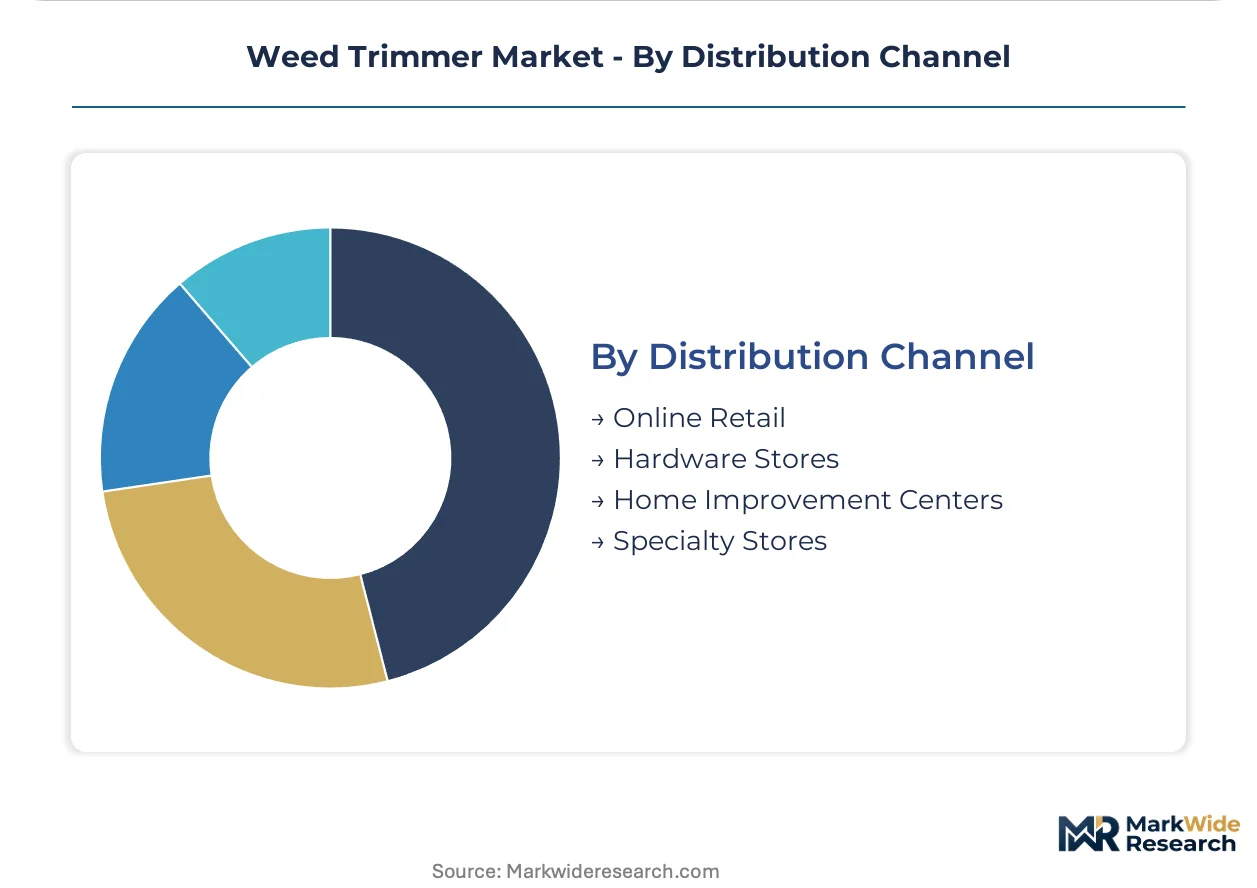
Distribution Channel:
Channel economics reflect working capital intensity and technical consultation requirements, with specialty dealers commanding margin premiums for assembly and training services.
- Hardware Stores:Independent and regional hardware retailers stock entry-level corded and battery units with limited SKU breadth. Staff technical knowledge varies, pushing buyers toward self-service selection.
- Home Improvement Centers:Big-box retailers allocate seasonal floor space to prominent battery platform displays, leveraging private-label exclusives and promotional financing. These channels capture the majority of residential battery trimmer volume.
- Specialty Stores:Authorized dealer networks provide pre-delivery inspection, warranty registration, and technician training for professional-grade equipment. Stihl and Husqvarna restrict their professional lines to these channels.
- Online Retail:Direct-to-consumer and marketplace platforms compete on price transparency and review aggregation, with free shipping thresholds influencing cart composition. Battery platform ecosystem lock-in reduces cross-shopping intensity.
Home Improvement Centers lead in unit volume. Online Retail is expanding most quickly as battery platform familiarity reduces in-person consultation needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export professional-grade trimmer systems to North American landscape contractors, while Chinese producers supply cost-optimized corded units to European retail channels. Battery platform standardization and emissions compliance deadlines are reshaping procurement patterns across buyer geographies.
United States
Municipal groundskeeping contracts in Texas and Florida are expanding fleet refresh cycles for landscape professionals. EPA Phase 3 small nonroad engine standards are forcing two-stroke platform abandonment ahead of 2025 compliance deadlines. Atlanta and Phoenix metropolitan areas exhibit concentrated demand for battery-powered equipment where noise ordinances restrict gas operation.
Germany
Commercial forestry operations in Bavaria retain gas-powered dominance for brush-cutting applications above 15mm stem diameter. REACH chemical restrictions on fuel additives and the EU F-Gas Regulation are eliminating gas equipment market access across member states. Stuttgart industrial clusters host captive motor foundries supplying European professional channels with emissions-compliant engine architectures.
China
Urban green space maintenance budgets in Beijing and Shanghai are rising with municipal beautification campaigns. GB standards for small engine emissions align with dual carbon goals under MIIT industrial policy directives. Yangtze River Delta manufacturing zones concentrate lithium-ion cell production for battery platform export to North American and European OEMs.
Japan
Precision agriculture border clearing in Hokkaido and Kyushu drives demand for lightweight handheld trimmers. METI energy efficiency standards for power tools accelerate brushless motor adoption across residential and professional segments. Nagoya industrial corridors host precision machining facilities for monofilament line cutting head components.
Australia
Solar farm vegetation management contracts in Queensland and Western Australia are piloting robotic trimmer deployment with RTK-GPS navigation. TGA-equivalent equipment safety frameworks and state-level occupational health regulations shape professional procurement specifications. Sydney and Melbourne metropolitan councils specify battery fleet conversion in municipal maintenance tenders.
Weed Trimmer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent distribution economics. Authorized dealer networks command margin premiums for assembly and training services, while mass retail channels compete on price transparency and promotional financing. Two strategic archetypes dominate: ecosystem builders standardizing battery platforms across tool categories, and torque specialists defending gas-powered dominance in heavy-load applications. Competitive moves concentrate on portfolio electrification and geographic certification compliance rather than capacity expansion.
Among German-engineered equipment manufacturers, Stihl anchors the professional forestry and municipal channel tier through captive foundry networks and restricted distribution. Husqvarna exemplifies the ecosystem-builder archetype, standardizing battery platforms across vegetation management tool categories to create contractor lock-in. Ego occupies a position on the high-voltage differentiation vector, competing with elevated voltage architectures against mainstream battery systems. These three companies represent divergent responses to emissions regulation compression and electrification transition economics.
| Leading Market Players |
|---|
| Stihl |
| Echo |
| Husqvarna |
| DeWalt |
| Greenworks |
| Ego |
| Worx |
| RedMax |
| Shindaiwa |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta lithium-ion cell foundries anchor global battery pack supply, with capacity utilization swings transmitting directly into OEM pricing power across professional and residential trimmer tiers. EPA Phase 3 compliance deadlines compress the transition window, forcing simultaneous gas-engine clearance sales and battery platform premium positioning.
Pricing Analysis
18V-40V mainstream battery architectures command mid-tier positioning while 56V high-voltage systems capture gas-comparable torque premiums and entry-level corded units compete on absolute cost. Three-tier pricing structure across premium brushless, standard brushed-motor, and economy corded levels differentiates by runtime specification and after-sales bundling. Cost compression in entry-level cordless tiers is intensifying because Chinese cell oversupply and direct-to-consumer channel expansion erode brand premiums. Residential homeowners exhibit highest price sensitivity, while landscape contractors prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Lithium carbonate from Chile and Australia, cobalt from the Democratic Republic of Congo, and rare earth magnets from China feed cell chemistry and brushless motor fabrication. Semiconductor fabrication for motor controllers clusters in Taiwan and South Korea, creating single-source vulnerability for high-efficiency drive electronics. Distribution runs through big-box home improvement centers for residential volume and authorized dealer networks for professional-grade equipment requiring assembly and training services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery platform economics are redefining competitive moats, with interoperability across trimmers, blowers, and chainsaws creating ecosystem lock-in that transcends single-tool brand loyalty.
For Market Incumbents: Build captive battery platform moats through backward integration into cell pack assembly and charger ecosystem standardization. Secure exclusive dealer network capacity in Texas and Florida municipal procurement corridors before CARB compliance deadlines accelerate fleet conversion. Invest in brushless motor firmware development teams to offset semiconductor supply concentration risk from East Asian foundries. For New Entrants and Emerging Players: Build out robotic perimeter navigation capabilities for golf course and solar farm vegetation management contracts where autonomous deployment remains underpenetrated. Target Australian solar farm operators and German municipal tenders as most penetrable early-adopter segments. Pursue equipment-as-a-service revenue models that transfer uptime risk and generate recurring maintenance streams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ecosystem builders with standardized battery platforms over torque specialists defending gas-engine legacy architectures. Long-term viability hinges on compliance with EU Battery Regulation recycling mandates and emerging right-to-repair legislation across multiple US states. Watch for EPA Phase 3 enforcement acceleration as the signal indicating tipping point timing for electric platform dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Creates ecosystem lock-in across trimmers, blowers, and chainsaws for landscape contractors. |
| Brushless Motor Controller Development | Captures margin from power electronics firmware scarce among legacy gas-engine engineering teams. |
| Robotic Navigation Sensor Fusion | Enables autonomous deployment for golf course rough and solar farm vegetation management contracts. |
| EU Battery Regulation Compliance | Positions brands for preferential market access across member states via recycling mandate adherence. |
| Authorized Dealer Network Expansion | Secures margin premiums for assembly, warranty registration, and technician training services. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with landscape contractors, municipal procurement officers, and aftermarket service heads combined with secondary validation from EPA regulatory filings, CARB evaporative emissions databases, and customs trade data for lithium-ion cell imports. Triangulation across bottom-up SKU-level volume builds and top-down OEM revenue assessments anchored market sizing. Field interviews with Stihl and Husqvarna authorized dealers, Ego direct-to-consumer channel managers, and Chinese contract manufacturers supplied channel economics and margin structure intelligence.
Forecast inputs span power platform migration curves, regulatory compliance deadline impacts, and lithium-ion energy density improvement trajectories across the analysis window. Segmentation dimensions modeled include product type architecture, end-user procurement sophistication, brushless versus brushed motor technology, and distribution channel working capital intensity. CAGRs derive from fitted adoption curves for electric platform displacement of gas-powered units, with professional fleet refresh cycles and municipal contract award patterns as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by high-voltage platform specialists or robotic navigation software entrants would shift outcomes. Cross-checking against EPA enforcement action intensity and EU Battery Regulation implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market