
 Global Anal Irrigation Systems Market | 2026-2036
Global Anal Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anal Irrigation Systems Market Foresight
China is narrowing its import dependency for medical-grade silicone tubing and precision pump components used in anal irrigation systems. Coloplast A/S leverages its vertically integrated catheter manufacturing to sustain cost leadership across European distribution channels. Wellspect Healthcare anchors its competitive position through dedicated urology and continence care specialization. B. Braun Melsungen AG competes via hospital-grade sterilization protocols that extend into integrated system offerings.
Anal irrigation systems are closed-loop fluid delivery devices that introduce controlled volumes of water into the rectum to facilitate complete bowel evacuation, typically operating at pressures below 200 mbar to prevent mucosal injury. These systems serve patients with neurogenic bowel dysfunction, chronic constipation, and post-surgical anorectal conditions where pharmacological management proves insufficient. Automated systems command premium positioning due to programmable pressure profiling and compliance tracking features, while disposable kits capture volume through infection-control protocols in acute care settings. Home care providers increasingly specify portable units with battery-operated pumps, shifting procurement away from hospital-grade equipment tethered to wall supplies.
The FDA's Class II device designation mandates 510(k) premarket notification for new anal irrigation entrants, while the EU Medical Device Regulation requires notified body certification under stricter clinical evaluation benchmarks. Japan's PMDA enforces JIS-standard biocompatibility testing for silicone components entering its reimbursement catalog. Stakeholders must monitor evolving reimbursement granularity across national health technology assessment bodies, as coding specificity determines whether home-based irrigation achieves parity with institutional billing rates.
Market Dynamics
The migration of bowel management from institutional settings to home environments is compressing equipment specifications toward portable, battery-operated systems that sacrifice clinical-grade precision for patient autonomy and reimbursement accessibility.
Growth Catalysts
- Germany's statutory reimbursement codes:Statutory health insurance catalogs in Germany list transanal irrigation with dedicated procedure codes, removing out-of-pocket barriers that limit uptake in comparable European markets.
- Neurogenic bowel dysfunction prevalence:Spinal cord injury and multiple sclerosis patient registries in North America and Western Europe are expanding the addressable population for prescription irrigation systems.
- Closed-loop fluid delivery engineering:Pressure-limited pump architectures operating below 200 mbar are eliminating mucosal injury risks that previously restricted clinical acceptance.
Market Restraints
- Medical-grade silicone supply concentration:Precision extrusion capabilities for biocompatible tubing remain concentrated among German and Japanese specialty polymer processors, exposing assemblers to input bottlenecks.
- FDA 510(k) pathway duration:The FDA's Class II device designation requires substantial equivalence demonstrations that extend time-to-market for novel pressure-control algorithms.
- Pharmacological constipation management:Prescription laxative and prokinetic protocols retain first-line status in primary care, limiting specialist referrals to irrigation therapy.
Strategic Opportunities
- Japan's PMDA reimbursement catalog expansion:Japan's Ministry of Health, Labour and Welfare is evaluating home-based irrigation for national health insurance inclusion, which would unlock the world's most aged patient population.
- Pediatric spina bifida applications:Underpenetrated pediatric urology clinics represent a white space where caregiver-administered irrigation could displace chronic enema dependence.
- Telehealth-integrated compliance tracking:Bluetooth-enabled pump logs that transmit to remote stoma therapy nurses are creating subscription revenue models beyond device sales.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing for novel polymer formulations extends development cycles by 18-24 months.
- Stoma therapy nursing workforce gaps:Specialized continence nurse training programs in the UK and Australia are failing to graduate sufficient practitioners to support home-based patient education.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anal Irrigation Systems Market |
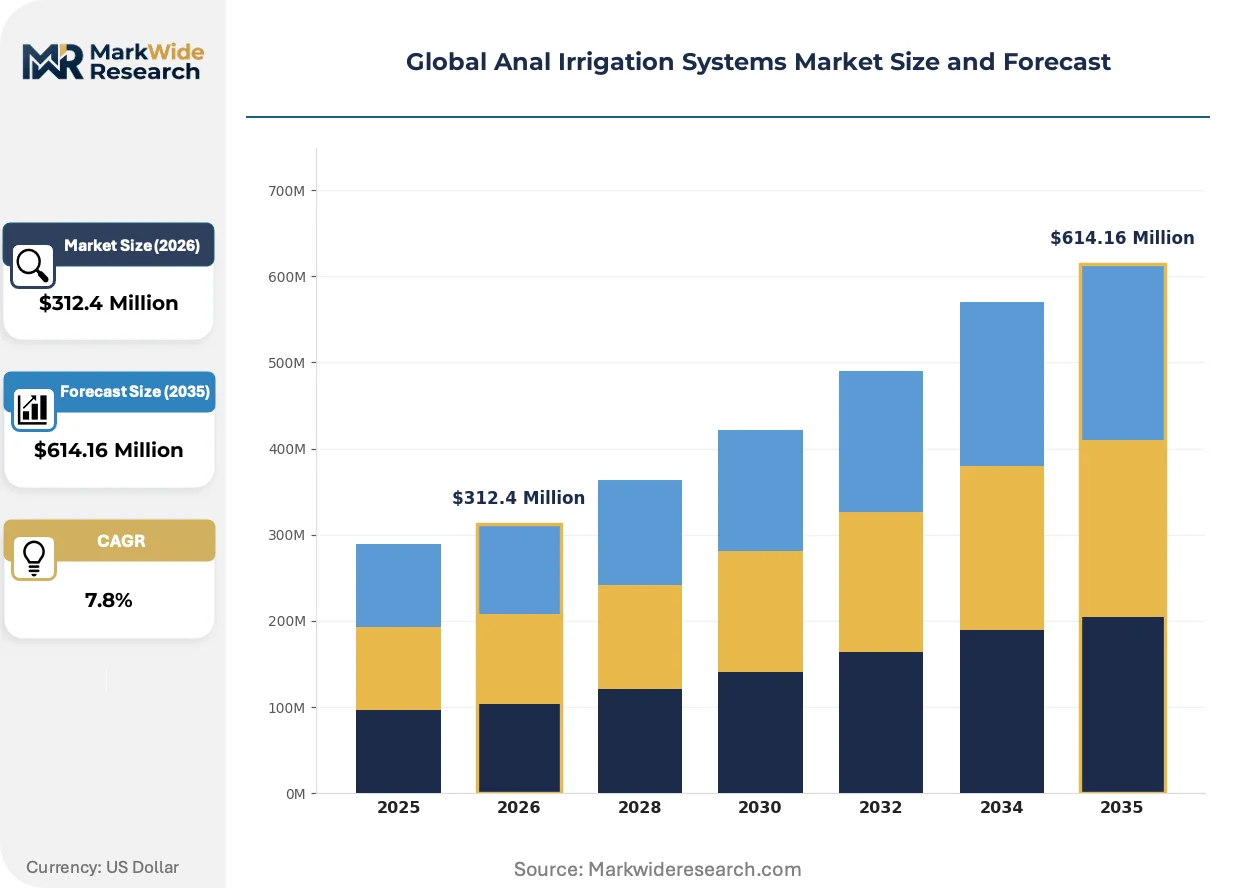
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $614.16 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Irrigators, Automated Systems, Pulsatile Devices, Disposable Kits Application: Chronic Fissure Relief, Fistula Treatment, Proctitis Care, Post-Surgical Healing End User: Specialty Clinics, Ambulatory Surgery Centers, Home Care Providers, Gastroenterology Units Deployment: Standalone Devices, Integrated Systems, Portable Units, Hospital-Grade Equipment |
| Companies Covered | Coloplast A/S, ConvaTec Group PLC, Becton, Dickinson and Company, Consure Medical Pvt. Ltd., Wellspect Healthcare, B. Braun Melsungen AG, Renew Medical Pty Ltd., MBH-International A/S, ProSys International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anal Irrigation Systems Market Shifts & Advancements
Equipment architecture is bifurcating between institutional precision systems and consumer-oriented portability, with software-enabled remote monitoring emerging as the decisive value-creation layer across both tiers.
Miniaturized peristaltic pump mechanisms are migrating from hospital-grade wall-tethered consoles toward handheld battery-operated units. Home care providers and independent living patients are adopting these portable architectures faster than acute care procurement cycles permit. This migration from clinical to domestic settings is compressing average selling prices while expanding addressable volume through retail pharmacy and direct-to-patient channels.
The EU Medical Device Regulation's stricter clinical evaluation benchmarks are forcing notified body recertification of legacy irrigation systems that previously qualified under the Medical Device Directive. Manufacturers must now generate post-market clinical follow-up data on mucosal safety outcomes. German and French urology suppliers are responding by consolidating clinical evidence across multiple national registries to satisfy MDR Annex XIV requirements.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, treating irrigation system maintenance as a separate line item subject to competitive tender. Group purchasing organizations in the US and NHS Supply Chain in the UK are driving this disintermediation of manufacturer service revenue. The shift is most visible in multi-site hospital systems standardizing on single-source disposable kits while dual-sourcing pump hardware.
Global Anal Irrigation Systems Market Segmentation
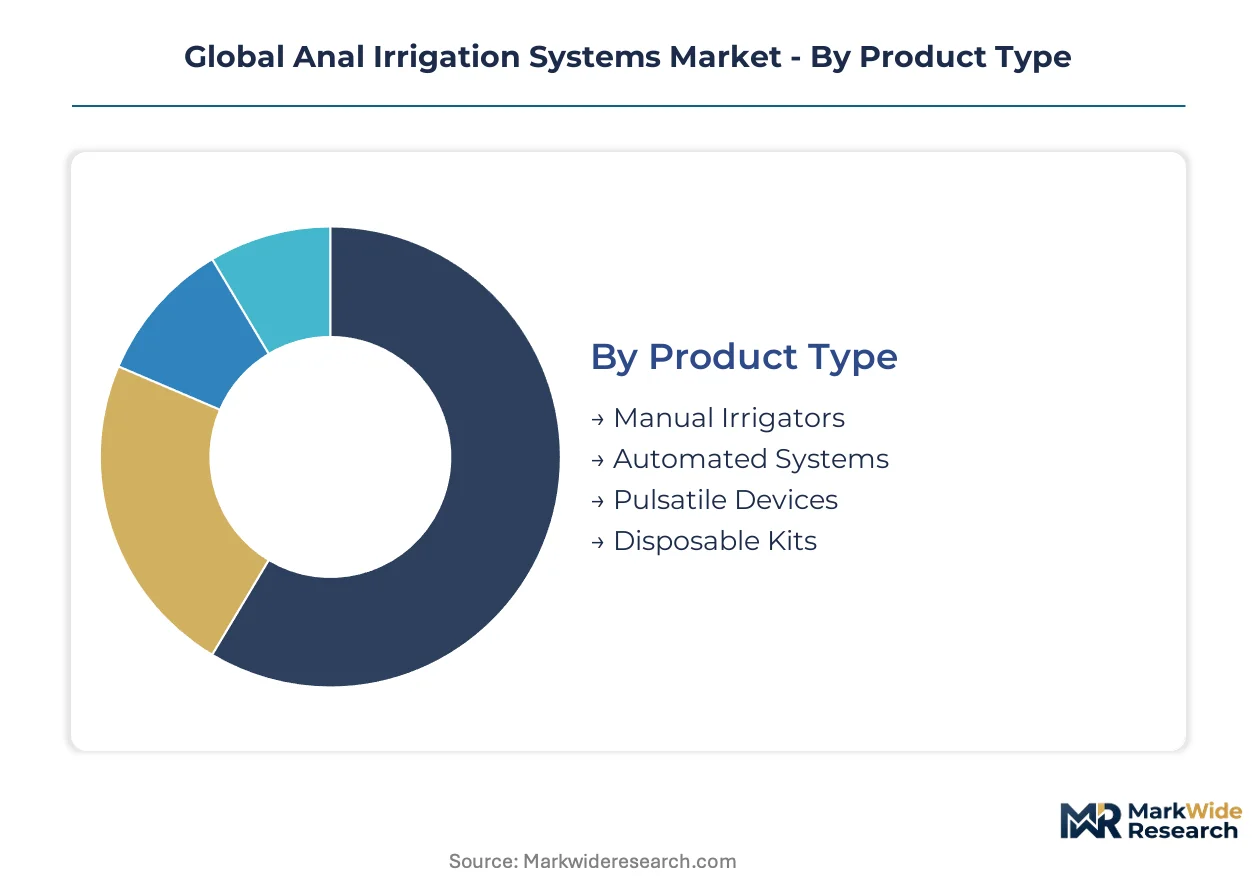
Anal irrigation systems fragment across four distinct dimensions that shape procurement patterns and clinical adoption curves. Product architecture determines reimbursement eligibility, while deployment format dictates whether patients qualify for home-based therapy or remain tethered to institutional settings.
Product Type:
Cost tier stratification separates premium programmable systems from basic mechanical alternatives, with reimbursement codes often restricting coverage to specific pressure-control capabilities.
- Manual Irrigators:Gravity-fed or squeeze-bulb mechanisms deliver water volumes without electrical components. German statutory health insurance catalogs reimburse these units for pediatric spina bifida patients where caregiver administration dominates home protocols.
- Automated Systems:Microprocessor-controlled pumps maintain pressure below 200 mbar through programmable profiling algorithms. Demand concentrates in North American spinal cord injury registries where patient autonomy drives preference for self-administered bowel management without nursing supervision.
- Pulsatile Devices:Rhythmic pressure oscillation mimics natural peristaltic patterns. UK stoma therapy nurses specify these for neurogenic bowel dysfunction cases refractory to constant-flow irrigation.
- Disposable Kits:Single-use tubing and collection assemblies packaged for infection control. French hospital procurement committees mandate these for post-surgical anorectal recovery wards to eliminate cross-contamination risks.
Automated systems command the established base. The steepest expansion runs through disposable kits as acute care settings tighten sterilization protocols.
Application:
Clinical indication determines pressure parameters, irrigation frequency, and whether therapy qualifies for prescription coverage versus over-the-counter procurement.
- Chronic Fissure Relief:Low-pressure warm water irrigation promotes mucosal healing without mechanical trauma. Italian colorectal surgeons prescribe these protocols as first-line alternatives to lateral internal sphincterotomy.
- Fistula Treatment:Antiseptic solution compatibility requires specialized tubing materials resistant to chemical degradation. Japanese PMDA biocompatibility standards for silicone components create regulatory gatekeeping for entrants targeting cryptoglandular fistula management.
- Proctitis Care:Anti-inflammatory medication delivery through irrigation systems demands precise temperature control. Australian gastroenterology units favor portable units allowing patients to maintain therapy during ulcerative colitis flare management at home.
- Post-Surgical Healing:Pressure-limited delivery protects fresh anastomotic sites following hemorrhoidectomy or sphincter repair. US ambulatory surgery centers bundle disposable kits into episode-of-care payments to reduce readmission penalties.
Post-surgical applications anchor institutional procurement volumes. Pediatric spina bifida protocols within chronic fissure relief are climbing the fastest as caregiver-administered alternatives to chronic enema dependence.
End User:
Customer type dictates equipment specifications, with home care providers driving portable miniaturization while hospital units prioritize sterilization compatibility and capital depreciation schedules.
- Specialty Clinics:Dedicated proctology and colorectal practices maintain wall-tethered precision systems for supervised patient training. German continence clinics serve as gatekeepers for statutory reimbursement authorization.
- Ambulatory Surgery Centers:Same-day discharge protocols require take-home disposable kits with simplified instructions. US Medicare bundled payment models incentivize these centers to select lowest-total-cost irrigation solutions.
- Home Care Providers:Durable medical equipment suppliers specify battery-operated pumps with carrying cases. Netherlands home nursing organizations negotiate volume contracts for patients with spinal cord injury requiring daily bowel management.
- Gastroenterology Units:Hospital-based departments integrate irrigation systems into broader inflammatory bowel disease management pathways. NHS Trusts in England standardize on single-manufacturer disposable contracts to simplify supply chain logistics.
Gastroenterology units represent the largest installed base. Home care providers are expanding most quickly as patients migrate from institutional to self-directed bowel management.
Deployment:
Physical configuration determines whether equipment travels with patients or remains fixed in clinical infrastructure, with software layers increasingly bridging both modalities.
- Standalone Devices:Self-contained pump and reservoir units operate without connectivity to hospital information systems. Spanish regional health services procure these for rural primary care centers lacking IT integration capabilities.
- Integrated Systems:Hardwired connections to building utilities and electronic health records enable usage logging for compliance documentation. Swedish hospital construction standards now mandate these for new colorectal ward builds.
- Portable Units:Battery-powered handheld pumps with collapsible reservoirs fit airline carry-on restrictions. Canadian veterans affairs programs distribute these to spinal cord injury patients for travel independence.
- Hospital-Grade Equipment:Stainless steel housings withstand industrial sterilization cycles and continuous duty operation. French university hospitals retain these for research protocols requiring precise pressure measurement validation.
Hospital-grade equipment retains dominance in capital budgets. Portable units are gaining share fastest as reimbursement frameworks expand home-based therapy eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Class II device designation for anal irrigation systems anchors the United States as the regulatory reference point shaping clinical evidence requirements worldwide. Germany's statutory reimbursement codes for transanal irrigation create the most permissive access environment in Europe. Japan's PMDA is evaluating home-based irrigation for national health insurance inclusion.
United States
Spinal cord injury patient registries and multiple sclerosis treatment centers drive prescription irrigation system demand across rehabilitation medicine networks. FDA 510(k) premarket notification requirements extend time-to-market for novel pressure-control algorithms. The Midwest and Southeast hospital systems concentrate procurement volume for post-surgical anorectal recovery protocols.
Germany
Statutory health insurance catalogs list transanal irrigation with dedicated procedure codes, removing out-of-pocket barriers that limit uptake in comparable European markets. EU Medical Device Regulation notified body certification under stricter clinical evaluation benchmarks governs product entry. Bavarian and North Rhine-Westphalian continence clinics serve as gatekeepers for reimbursement authorization.
Japan
The world's most aged patient population creates structural demand for home-based bowel management solutions among neurogenic dysfunction cases. PMDA enforces JIS-standard biocompatibility testing for silicone components entering its reimbursement catalog. Tokyo and Osaka medical device distribution channels concentrate specialized urology and continence care supply.
United Kingdom
NHS Supply Chain standardization drives competitive tendering for disposable irrigation kits across hospital trusts. NHS Trusts in England standardize on single-manufacturer disposable contracts to simplify supply chain logistics. London and Midlands stoma therapy nursing networks face workforce gaps that constrain home-based patient education expansion.
China
Domestic manufacturers are narrowing import dependency for medical-grade silicone tubing and precision pump components. NMPA medical device registration requirements shape local production quality benchmarks. Yangtze River Delta and Pearl River Delta industrial clusters concentrate precision polymer processing capabilities for biocompatible tubing.
Global Anal Irrigation Systems Market Competitive Landscape
Vertically integrated medical device conglomerates and specialized continence care specialists split the market across institutional and home care procurement channels. The vendor base concentrates among European and North American headquartered firms with established urology and wound care portfolios. Two strategic archetypes dominate: diversified medtech platforms leveraging catheter manufacturing scale, and focused continence therapy specialists building clinical education networks. Competitive moves center on backward integration into silicone component production and telehealth-integrated compliance tracking software layers.
Within the diversified medtech tier, Coloplast A/S and B. Braun Melsungen AG exemplify scale-driven positioning through established European distribution infrastructure and hospital-grade sterilization protocols. Wellspect Healthcare occupies a specialist position anchored in dedicated urology and continence care clinical education. Among emerging market participants, Consure Medical Pvt. Ltd. represents the India-based fabrication archetype targeting cost-optimized disposable kit production.
| Leading Market Players |
|---|
| Coloplast A/S |
| ConvaTec Group PLC |
| Becton, Dickinson and Company |
| Consure Medical Pvt. Ltd. |
| Wellspect Healthcare |
| B. Braun Melsungen AG |
| Renew Medical Pty Ltd. |
| MBH-International A/S |
| ProSys International Ltd. |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese medical-grade silicone extruders exposes assemblers to input bottlenecks that compress pricing spreads between premium programmable systems and economy mechanical alternatives while forcing geographic diversification in component sourcing.
Pricing Analysis
German statutory reimbursement codes sustain the widest price spreads globally, with automated systems commanding substantial premiums over gravity-fed alternatives. Pricing stratifies across premium programmable, standard pulsatile, and economy manual tiers based on pressure-control certification levels and after-sales service bundling. Cost compression in the disposable kit segment is intensifying because hospital procurement committees unbundle maintenance contracts from capital equipment purchases. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare bundled payment constraints, while spinal cord injury registries in North America show lowest sensitivity where patient autonomy drives preference.
Supply Chain Analysis
Export-control restrictions on precision polymer processing equipment limit technology transfer to emerging manufacturing hubs, constraining supply expansion. Component sourcing draws from Germany and Japan for biocompatible tubing extrusion, China for pump motor assemblies, and the United States for microprocessor controllers. Single-source vulnerability concentrates in medical-grade silicone supply where specialty polymer processors maintain oligopolistic positioning. Distribution runs through hospital procurement committees and group purchasing organizations in developed markets, with direct-to-patient channels expanding through retail pharmacy networks in home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through NHS Supply Chain standardization in the United Kingdom and group purchasing organization consolidation across United States hospital systems, compressing manufacturer margins while favoring scale-backed incumbents.
For Market Incumbents: Harden supply chain resilience through captive silicone tubing production or exclusive partnerships with German specialty polymer processors to insulate against input bottlenecks. Deepen clinical education networks for stoma therapy nurses to defend against emerging telehealth-integrated compliance tracking entrants. Pressure-limited pump algorithm R&D investment represents the critical differentiation lever as FDA 510(k) pathways extend time-to-market for novel architectures.
For New Entrants and Emerging Players: Pediatric spina bifida applications in underpenetrated European and North American urology clinics represent the most penetrable entry point where caregiver-administered protocols displace chronic enema dependence. Japan's pending PMDA reimbursement catalog expansion offers regulatory-first-mover positioning in the world's most aged patient population. Direct-to-patient digital marketing through spinal cord injury patient advocacy organizations provides the lowest customer acquisition cost channel outside institutional procurement gatekeepers.
For Investors and Strategic Acquirers: EU Medical Device Regulation recertification deadlines reshape the acquisition landscape toward targets with established notified body relationships and consolidated post-market clinical follow-up data. Five-to-ten year viability favors specialized continence care platforms with telehealth software layers over pure hardware manufacturers. The signal to watch is Japan's Ministry of Health, Labour and Welfare reimbursement decision timing, which would unlock immediate volume expansion for positioned suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Annex XIV compliance secures notified body certification for EU market access. |
| Reimbursement Strategy | German statutory insurance catalog inclusion removes patient out-of-pocket barriers. |
| Hospital System Partnership | NHS Trust standardization contracts lock in disposable kit volume commitments. |
| Software Companion Development | Bluetooth-enabled compliance tracking creates subscription revenue beyond device sales. |
| Backward Integration | Captive silicone tubing production insulates against German-Japanese supply concentration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with stoma therapy nurses, hospital procurement managers, biomedical engineers, and continence clinic directors. Secondary validation drew from FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement contract registries, and national health technology assessment body reimbursement decisions. Bottom-up patient registry analysis and top-down medical device trade flow triangulation anchored volume estimates.
Calibration against historical reimbursement code expansions and regulatory approval timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, clinical indication, end-user type, and deployment configuration alongside regional regulatory cluster differentiation. CAGRs were derived from patient population epidemiology trajectories and reimbursement accessibility curves. Neurogenic bowel dysfunction prevalence registries and statutory insurance catalog update frequencies served as industry-specific forecast inputs.
Practitioners should monitor PMDA reimbursement catalog decisions, EU MDR enforcement consistency, and medical-grade silicone supply availability for early signals of forecast deviation. Cross-checking against national patient advocacy organization therapy adoption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market