
 Brazil Agricultural Irrigation Machinery Market | 2026-2036
Brazil Agricultural Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Agricultural Irrigation Machinery Market Outlook
Project finance and operational leasing for irrigation assets is rewriting competitive access across Brazil's agricultural machinery sector. Netafim Limited leverages its drip irrigation specialization to anchor premium positioning among large-scale soybean operators. Valmont Industries, Inc. sustains manufacturing scale through its Brazilian production footprint and dealer network density. Jain Irrigation Systems Ltd. competes on integrated micro-irrigation systems that reduce water application costs for vegetable growers.
Agricultural irrigation machinery encompasses equipment engineered to apply controlled water volumes to crops through pressurized or gravity-driven distribution networks, typically operating at pressures between 10 and 150 psi depending on system architecture. These systems incorporate pumps, filtration units, emitters, and control valves designed to optimize water use efficiency across variable terrain and soil conditions. Sprinkler systems dominate installed base value due to established service infrastructure and compatibility with Brazil's extensive grain production, while sensor-based systems represent the fastest-expanding technology category as telemetry adoption reduces labor input for scheduling decisions. Drip irrigation captures concentrated margin pools in high-value fruit and vegetable applications where water scarcity premiums justify capital-intensive precision layouts.
ANA (Agência Nacional de Águas) water concession frameworks and INCRA land use standards shape equipment specifications by mandating flow metering and efficiency thresholds in regulated river basins. ANVISA and Ministry of Agriculture inspection protocols govern material safety for food-contact irrigation components, creating compliance differentiation among suppliers. Stakeholders must monitor ANA's basin-level abstraction limits and embedded energy cost trajectories to calibrate portfolio exposure between gravity-fed and pump-dependent system architectures.
Market Dynamics
ANA's basin-level abstraction limits and embedded energy cost trajectories are forcing equipment specification pivots across Brazil's agricultural machinery sector, compressing demand toward gravity-fed architectures in water-stressed river basins.
Growth Catalysts
- ANA Water Concession Frameworks:Mandated flow metering and efficiency thresholds in regulated basins are accelerating equipment replacement cycles among large-scale operators.
- Center-West Soybean Expansion:Irrigation-dependent cultivation in Mato Grosso and Goiás is pulling center-pivot and linear-move system deployments.
- Telemetry Integration:Sensor-based scheduling systems are reducing labor input requirements and expanding addressable farm scale for automated distributors.
Market Restraints
- Embedded Energy Cost Volatility:Pump-dependent architectures face margin compression from Brazilian grid tariff fluctuations and diesel price instability.
- Import Concentration Risk:Critical filtration and emitter components concentrate sourcing from Israeli and Italian suppliers, exposing lead time volatility.
- Technical Limitation in Variable Terrain:Drip system uniformity degrades on undulating topography common in Minas Gerais coffee zones, constraining addressable acreage.
Strategic Opportunities
- Underpenetrated Northeast Fruit Belt:Bahia and Pernambuco mango and grape zones show sub-15% drip penetration against Mediterranean benchmarks.
- INCRA Land Regularization Incentives:Formalized tenure documentation unlocks subsidized credit lines for cooperative machinery procurement.
- PV-Diesel Hybrid Convergence:Solar pumping integration with existing diesel infrastructure is opening off-grid expansion in remote Cerrado settlements.
Industry Challenges
- Certification Timeline Compression:ANVISA food-contact material approvals and Ministry of Agriculture inspection protocols extend product launch cycles by 8-14 months.
- Integration Complexity with Legacy Furrow Systems:Retrofit compatibility gaps between pressurized emitters and existing gravity canal networks stall upgrade decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Agricultural Irrigation Machinery Market |
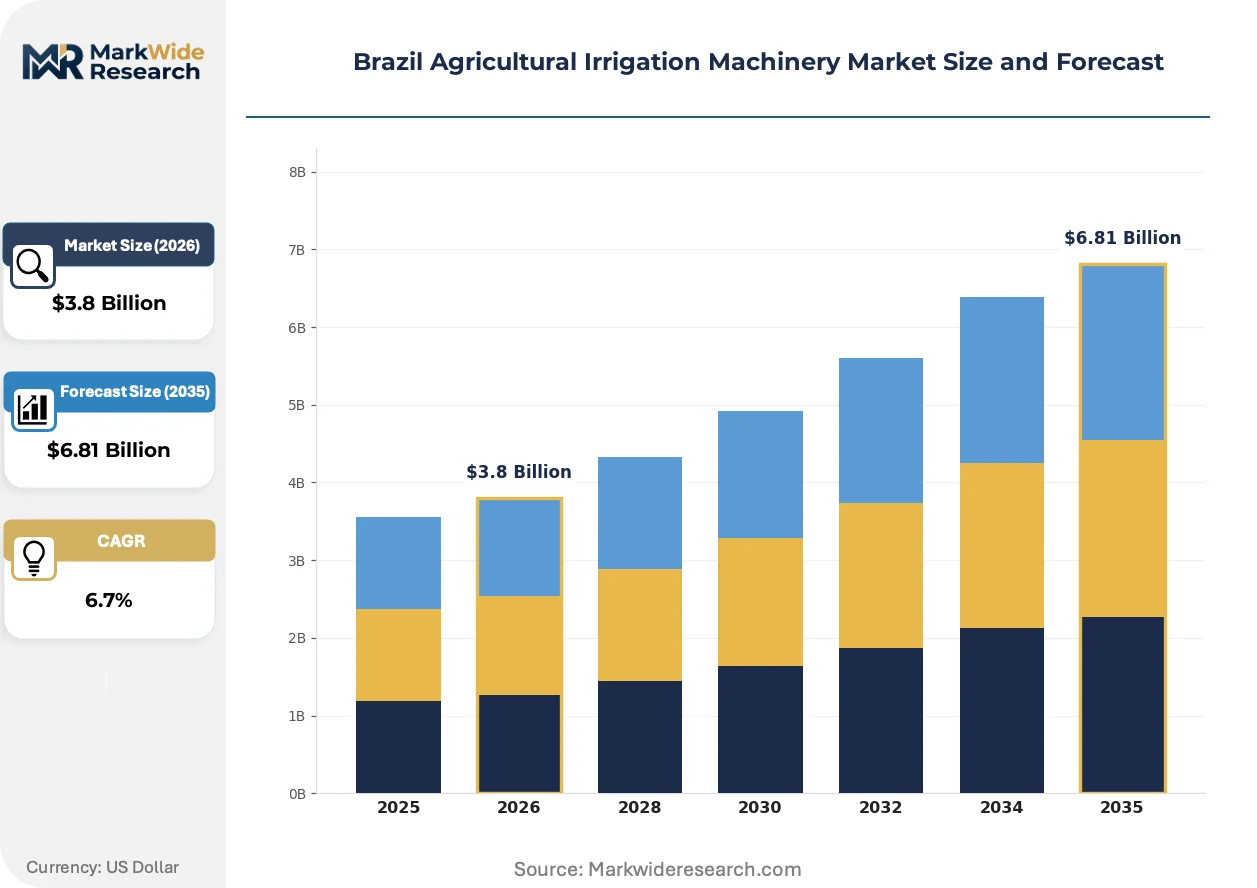
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation Technology: Gravity Flow, Pump Irrigation, Automated Systems, Sensor-Based Systems End User: Farmers, Agricultural Cooperatives, Contractors, Government Application: Fruits, Vegetables, Grains, Turf |
| Companies Covered | Netafim Limited, Rain Bird Corporation, Valmont Industries, Inc., The Toro Company, Jain Irrigation Systems Ltd., Lindsay Corporation, Rivulis Irrigation Ltd., Mikro-Irriga, Bauer Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Agricultural Irrigation Machinery Market Strategic Shifts
Telemetry and variable-rate application technologies are digitizing irrigation scheduling decisions, compressing the traditional agronomist-dependent service model and enabling autonomous operation at expanding farm scales across Brazil's major belts.
Variable-frequency drive pump controllers paired with soil-moisture sensor networks are digitizing water application precision. Large-scale sugarcane operators in São Paulo state are deploying these systems at accelerating rates. The technology is digitizing energy cost structures and enabling real-time tariff optimization against time-of-use electricity pricing.
ANA's basin-level abstraction limits and embedded flow-metering mandates are reshaping equipment specifications in the Paraná and Tocantins-Araguaia basins. Industrial consequence includes mandatory telemetry retrofit requirements for existing concessions. São Paulo state operators face the most compressed compliance timelines, driving accelerated distributor inventory turnover.
Cooperative procurement consortia are consolidating machinery acquisition decisions, displacing individual farm-level capital planning. Traditional dealer-direct sales channels face margin compression as these consortia centralize specification authority and negotiate volume terms. This concentration is most visible in Mato Grosso's soybean belt, where three cooperatives account for dominant center-pivot placements.
Brazil Agricultural Irrigation Machinery Market Segmentation
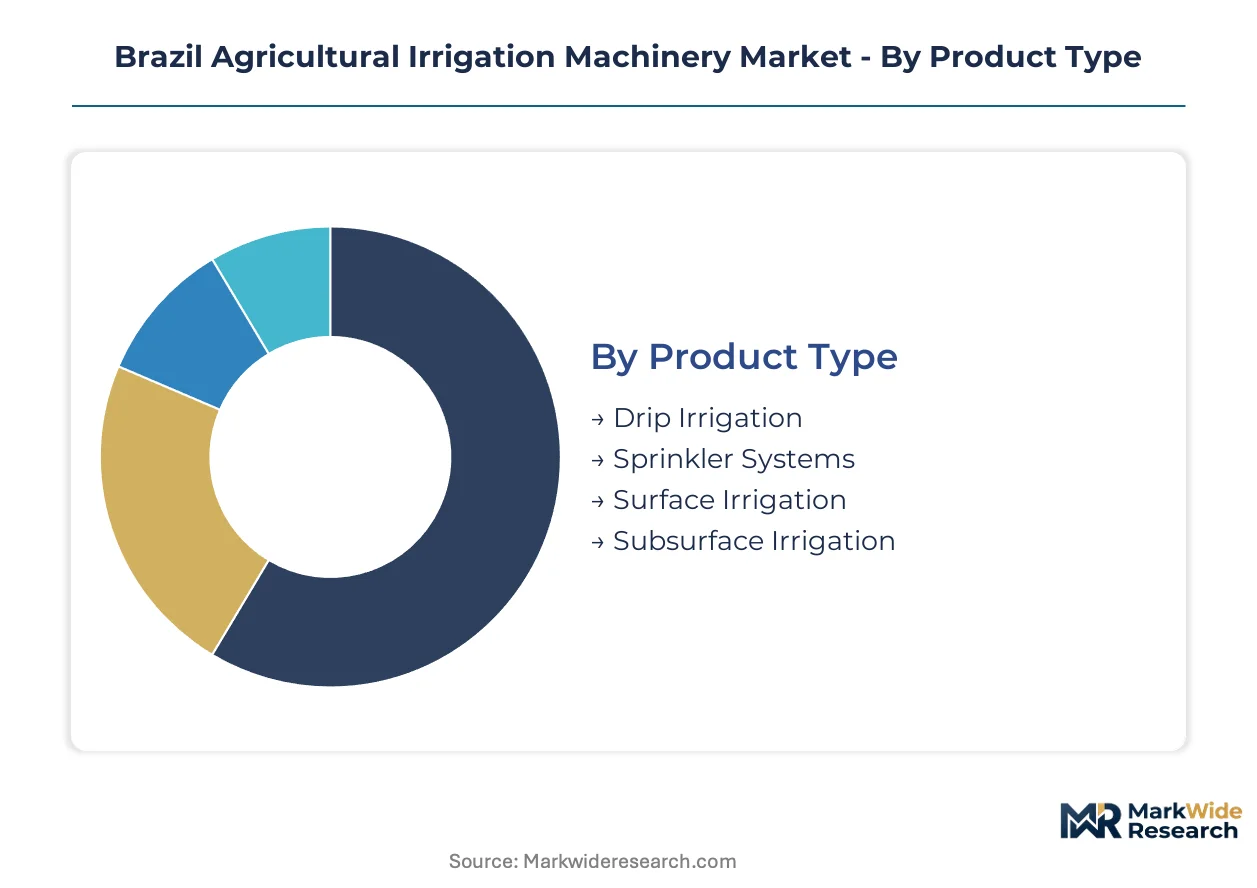
Brazil's irrigation machinery market fragments across four distinct dimensions that shape procurement patterns and technology adoption. Product architecture determines water efficiency profiles and capital intensity. Technology sophistication governs labor substitution potential and regulatory compliance. End-user structure concentrates buying power toward cooperative consortia. Application specificity drives margin differentiation between commodity grains and high-value horticulture.
Product Type:
Equipment architecture spans pressurized precision delivery to gravity-dependent surface distribution, with water stress severity and crop value determining optimal configuration.
- Drip Irrigation:Networks of pressure-compensating emitters and filtration subsystems deliver water directly to root zones at 10-25 psi operating pressure. São Paulo's citrus belt and Bahia's mango zones concentrate demand, with ANA abstraction limits accelerating retrofit from flood methods.
- Sprinkler Systems:Center-pivot and linear-move configurations dominate Mato Grosso's soybean expansion, leveraging established dealer service infrastructure and compatibility with large-scale mechanized farming. Water application uniformity challenges on undulating Cerrado terrain constrain addressable acreage in select zones.
- Surface Irrigation:Gravity-fed furrow and border-strip methods persist in legacy rice cultivation across Rio Grande do Sul, constrained by rising labor costs and ANA efficiency mandates in regulated basins.
- Subsurface Irrigation:Buried dripperline installations minimize evaporative losses in high-value vegetable production, with adoption concentrated in Pernambuco's irrigated perimeters where water scarcity premiums justify installation complexity.
Established volume favors Sprinkler Systems; emerging adoption favors Drip Irrigation.
Technology:
Energy input and control sophistication stratify procurement decisions, with grid tariff volatility and telemetry integration reshaping specification priorities.
- Gravity Flow:Unpowered distribution through canal networks and siphon tubes serves low-lift topography in southern rice systems. Goiás operators face mounting pressure to meter and report flows under ANA basin regulations.
- Pump Irrigation:Diesel and electric centrifugal pumps dominate pressurized system architectures. Embedded energy cost volatility compresses margins for operators dependent on grid power in Minas Gerais coffee zones.
- Automated Systems:Programmable valve controllers and remote monitoring infrastructure reduce labor scheduling requirements. Large-scale sugarcane processors in São Paulo state deploy these configurations at accelerating rates.
- Sensor-Based Systems:Soil-moisture telemetry and variable-frequency drive pumps enable real-time tariff optimization against time-of-use electricity pricing. This architecture climbs the fastest among Center-West grain operators seeking labor substitution.
Capital deployment tilts toward Pump Irrigation for immediate acreage expansion; compliance pressure and labor scarcity accelerate Sensor-Based Systems.
End User:
Procurement authority concentrates toward entities with balance sheet capacity and subsidized credit access, displacing individual farm-level equipment decisions.
- Farmers:Individual owner-operators dominate vegetable and fruit segments below 50 hectares, constrained by collateral requirements for precision equipment financing.
- Agricultural Cooperatives:Consolidated buying power across Mato Grosso's soybean belt enables volume-negotiated center-pivot placements. Three cooperatives account for dominant machinery procurement in key districts.
- Contractors:Mobile irrigation service providers supply seasonal water application to grain operations lacking owned infrastructure, prevalent in Goiás rental arrangements.
- Government:Federal and state irrigation perimeter development programs specify equipment packages for settlement projects, with INCRA land regularization unlocking subsidized credit lines.
Procurement volume aggregates toward Agricultural Cooperatives; policy leverage concentrates with Government programs.
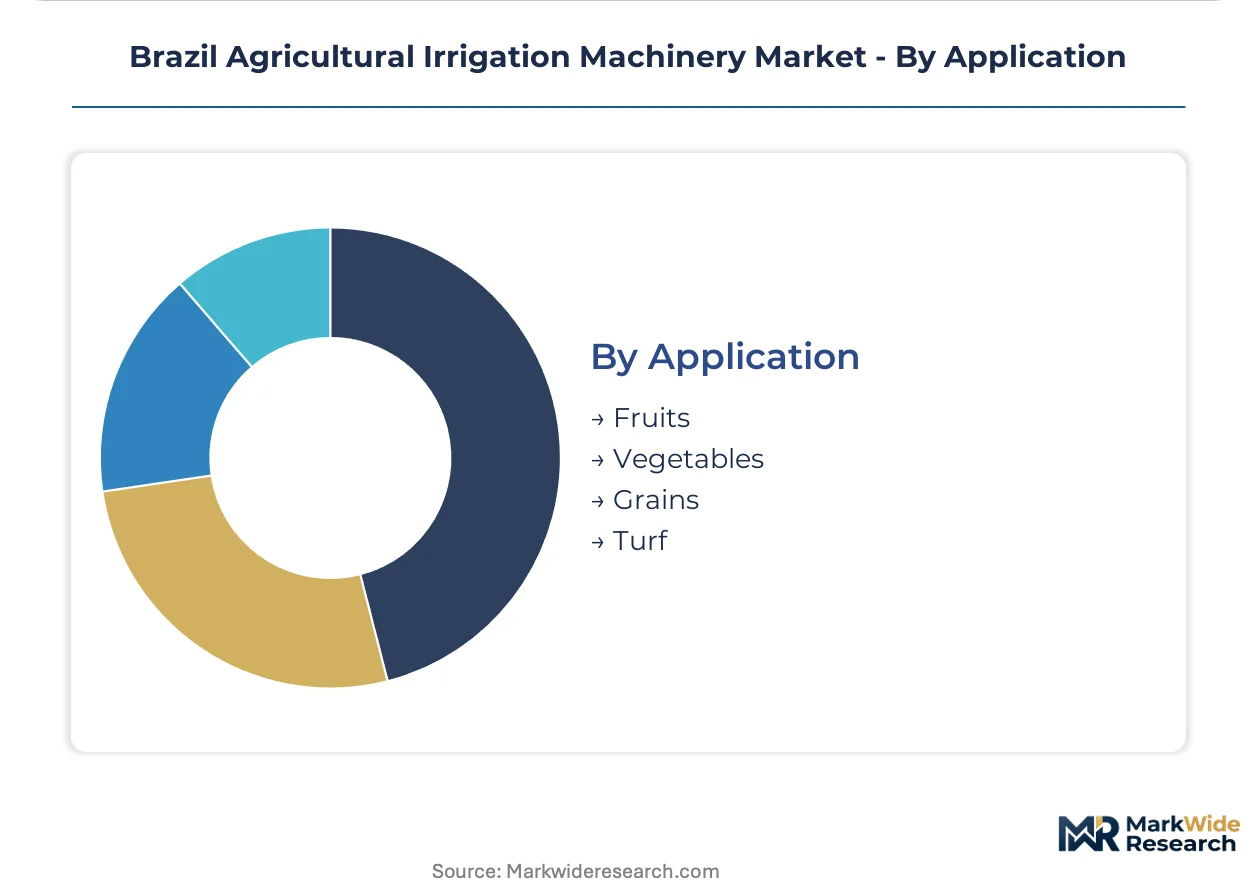
Application:
Crop value per hectare and water sensitivity determine acceptable capital intensity and technology sophistication thresholds.
- Fruits:Mango, grape, and citrus operations in the Northeast and São Paulo state justify drip infrastructure investment, with sub-15% penetration in Bahia against Mediterranean benchmarks indicating expansion runway.
- Vegetables:Tomato and leafy green producers in Pernambuco and Minas Gerais deploy precision emitter systems to manage phytosanitary risk and water cost exposure.
- Grains:Soybean and corn irrigation in Mato Grosso and Goiás pulls center-pivot and linear-move system deployments, with yield insurance premiums favoring supplemental irrigation adoption.
- Turf:Sports field and golf course maintenance represents niche demand concentrated in São Paulo and Rio de Janeiro metropolitan peripheries.
Revenue concentration aligns with Grains; margin expansion potential concentrates in Fruits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANA's basin-level abstraction limits and INCRA land regularization incentives are redistributing machinery demand across Brazil's agricultural belts, concentrating procurement authority in states with formalized water concessions and subsidized credit access.
São Paulo
Sugarcane processors deploy sensor-based scheduling systems at accelerating rates to optimize against time-of-use electricity pricing. ANA's mandatory telemetry retrofit requirements for existing concessions compress compliance timelines here more aggressively than elsewhere. The Ribeirão Preto cluster anchors center-pivot and linear-move system deployments for large-scale grain operations.
Mato Grosso
Center-West soybean expansion pulls irrigation-dependent cultivation into previously rain-fed areas, with yield insurance premiums favoring supplemental irrigation adoption. Three agricultural cooperatives concentrate dominant machinery procurement decisions across key districts. The Sorriso-Sinop corridor exhibits the densest center-pivot installation rates in the Cerrado biome.
Bahia
Mango and grape zones show sub-15% drip penetration against Mediterranean benchmarks, indicating substantial expansion runway for precision emitter systems. Water scarcity premiums in the São Francisco Valley justify capital-intensive infrastructure investments. The Juazeiro-Petrolina irrigated perimeter anchors Northeast fruit belt modernization.
Minas Gerais
Coffee zone operators face embedded energy cost volatility from grid tariff fluctuations, compressing margins for pump-dependent architectures. Drip system uniformity degrades on undulating topography common in southern growing areas, constraining addressable acreage. The Triângulo Mineiro sub-region exhibits the most advanced variable-frequency drive pump controller adoption.
Goiás
Mobile irrigation service providers supply seasonal water application to grain operations lacking owned infrastructure, prevalent in rental arrangements across the state. ANA basin regulations mount pressure to meter and report flows from gravity-fed canal networks. The Rio Verde-Anápolis axis concentrates contractor fleet deployments for soybean coverage.
Brazil Agricultural Irrigation Machinery Market Competitive Environment
Channel-controlling players compete with product-specialist players across Brazil's agricultural irrigation machinery sector. The vendor base fragments across Israeli drip-irrigation specialists, US center-pivot manufacturers, and regional service integrators. Three strategic archetypes dominate: precision-emitter technology leaders, mechanized system scale producers, and cooperative-facing distribution consolidators. M&A activity concentrates on dealer network density expansion, while portfolio diversification moves target telemetry integration capabilities.
Within the precision-technology tier, Netafim Limited and Jain Irrigation Systems Ltd. exemplify specialized emitter and filtration expertise. Valmont Industries, Inc. occupies a position among scale-driven mechanized system fabricators with established Brazilian production footprints. Rain Bird Corporation and The Toro Company sit within the integrated control-systems archetype, spanning residential through agricultural applications.
| Leading Market Players |
|---|
| Netafim Limited |
| Rain Bird Corporation |
| Valmont Industries, Inc. |
| The Toro Company |
| Jain Irrigation Systems Ltd. |
| Lindsay Corporation |
| Rivulis Irrigation Ltd. |
| Mikro-Irriga |
| Bauer Group |
| Others |
Value Chain & Pricing Dynamics
Santos-Paranaguá port freight corridors govern landed cost structures for Israeli emitter assemblies and Italian filtration subsystems, concentrating margin pressure on distributors serving Mato Grosso soybean operators while enabling price premiums for Bahia fruit belt precision layouts.
Pricing Analysis
Certification level (ANVISA food-contact grade versus standard agricultural tier) creates the primary spread between premium emitter systems and commodity-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ANA-mandated flow metering driving specification upgrades toward mid-tier and above. Cost compression in standard-tier pump architectures is intensifying because embedded energy volatility erodes operating margins. Individual vegetable growers below 50 hectares exhibit highest price sensitivity, while agricultural cooperatives leverage volume consolidation for least sensitivity.
Supply Chain Analysis
Tariff exposure between Israel and Brazil dominates sourcing risk for pressure-compensating emitters and advanced filtration membranes. Manufacturing concentrates in Israel, Italy, and domestic Brazilian assembly facilities for mechanized pivot systems. Raw material dependencies center on specialized polymers, precision-machined brass components, and variable-frequency drive electronics. Single-source vulnerability runs through Israeli drip-irrigation technology licensors. Distribution runs through cooperative procurement consortia displacing traditional dealer-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry platform interoperability is shifting competitive advantage toward ecosystem orchestrators capable of integrating sensor hardware, cloud analytics, and utility tariff optimization across Brazil's fragmented farm scale.
For Market Incumbents: Pre-empt cooperative procurement consolidation by anchoring exclusive supply agreements with Mato Grosso's three dominant machinery buyers. Deepen backward integration into filtration membrane production to offset Israeli sourcing lead time volatility. Invest in ANVISA fast-track certification capabilities to compress product launch cycles against regulatory timeline compression. For New Entrants and Emerging Players: Pursue Bahia's São Francisco Valley mango and grape zones where sub-15% drip penetration against Mediterranean benchmarks indicates white-space availability. Target mobile irrigation service provider segments in Goiás rental arrangements lacking owned infrastructure. Lead with PV-diesel hybrid pumping integration as differentiated entry proposition for remote Cerrado settlements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized agricultural equipment divisions lacking telemetry integration capabilities. Five-to-ten year viability favors precision-emitter technology leaders with ANA compliance-ready product portfolios. Monitor ANA basin-level abstraction limit enforcement intensity as inflection indicator for mandatory retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Unifies sensor networks with ANA-mandated flow metering for São Paulo sugarcane processors. |
| Backward Integration into Filtration | Captures margin pools currently concentrated among Israeli and Italian component suppliers. |
| Cooperative Procurement Partnership | Locks volume commitments from Mato Grosso's three dominant machinery-buying consortia. |
| PV-Diesel Hybrid System Development | Opens off-grid expansion in remote Cerrado settlements beyond grid infrastructure reach. |
| ANVISA Fast-Track Certification Investment | Compresses product launch cycles against 8-14 month regulatory approval timelines. |
Study Parameters
Operator-level perspectives from agricultural cooperative procurement directors, irrigation contractor fleet managers, sugarcane processing plant engineers, and ANA basin regulation compliance officers anchored the qualitative base. Secondary validation drew from ANA water concession framework documentation, INCRA land regularization program records, Ministry of Agriculture inspection protocol filings, and embedded energy cost trajectory databases. Bottom-up equipment deployment estimates triangulated against top-down agricultural credit flow analysis.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated regulatory enforcement pathways. Segmentation dimensions spanned product architecture, technology sophistication, end-user structure, and application specificity alongside regional water stress severity tiers. CAGRs derived from equipment replacement cycle analysis, cooperative expansion capital commitment tracking, and telemetry adoption curve modeling. Forecast inputs incorporated ANA basin-level abstraction limit rollout schedules and PV-diesel hybrid cost convergence trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Israeli precision-emitter specialists or Chinese solar pumping entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
United States Irrigation Valves Market