
 Graphics Processing Unit (GPU) Market | 2026-2036
Graphics Processing Unit (GPU) Market Size, Share, and Industry Trends Forecast 2026-2036
Graphics Processing Unit (GPU) Market Intelligence
Taiwan is tilting the GPU supply balance through its concentration of leading-edge foundry capacity. NVIDIA Corporation anchors the AI accelerator segment with vertically integrated software-hardware ecosystems. Advanced Micro Devices Inc. competes on open standards and data center GPU density. Intel Corporation leverages domestic U.S. fabrication investments to differentiate its foundry-bound accelerator roadmap.
A graphics processing unit is a parallel-processor semiconductor containing thousands of cores optimized for simultaneous thread execution, typically manufactured on sub-5nm process nodes with high-bandwidth memory stacks. Its primary commercial purpose is to render visual output and accelerate matrix-intensive workloads from gaming frames to neural network training. Discrete GPU and server GPU categories command the dominant margin pools, while integrated GPU solutions occupy cost-sensitive mobile and client computing tiers. Ray tracing and AI acceleration technologies are reshaping product differentiation as tensor operations displace traditional shader-bound architectures.
The U.S. Department of Commerce export controls, the EU Chips Act capacity targets, and China's MIIT domestic semiconductor directives collectively fragment procurement geography and foundry access rules. GPU vendors must navigate divergent compliance regimes to maintain supply continuity across jurisdictions. Stakeholders should monitor which regulatory perimeter—American, European, or Chinese—absorbs their next capacity commitment before locking process node roadmaps.
Market Dynamics
Generative AI training clusters at hyperscale data centers are absorbing server-class accelerators faster than foundry capacity can expand, compressing procurement timelines and concentrating bargaining power among cloud infrastructure operators.
Growth Catalysts
- Hyperscale AI training clusters:Cloud operators are deploying thousand-GPU pods for foundation model development, creating sustained demand for high-bandwidth memory stacks and advanced packaging.
- U.S. CHIPS Act subsidies:Domestic fabrication incentives are reshoring advanced node capacity, reducing geopolitical supply risk for North American accelerator procurement.
- Ray tracing in gaming and visualization:Real-time path tracing pipelines are forcing GPU architecture evolution toward dedicated RT cores and tensor operation units.
Market Restraints
- Leading-edge foundry concentration:Sub-5nm capacity concentrates in Taiwan, creating single-point-of-failure exposure for advanced AI chip supply chains.
- High-bandwidth memory supply constraints:HBM3 and HBM3e stack production remains captive to three memory suppliers, limiting accelerator output regardless of logic die availability.
- Export control compliance burden:U.S. Department of Commerce licensing requirements are fragmenting product SKUs and delaying market access for China-bound shipments.
Strategic Opportunities
- Edge AI inference acceleration:Automotive and industrial vision systems are creating demand for low-power discrete GPUs outside data center environments.
- EU Chips Act capacity targets:European foundry subsidies are opening alternative fabrication pathways for non-leading-edge accelerators and automotive-grade GPUs.
- Open accelerator standards:CXL and UCIe interconnect protocols are enabling multi-vendor GPU pooling, reducing software lock-in for enterprise buyers.
Industry Challenges
- CoWoS advanced packaging bottleneck:Chip-on-wafer-on-substrate capacity constraints are throttling high-end accelerator output despite available logic wafers.
- Compiler and software stack portability:CUDA-optimized codebases create switching costs that complicate competitive silicon adoption in research and enterprise settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphics Processing Unit (GPU) Market |
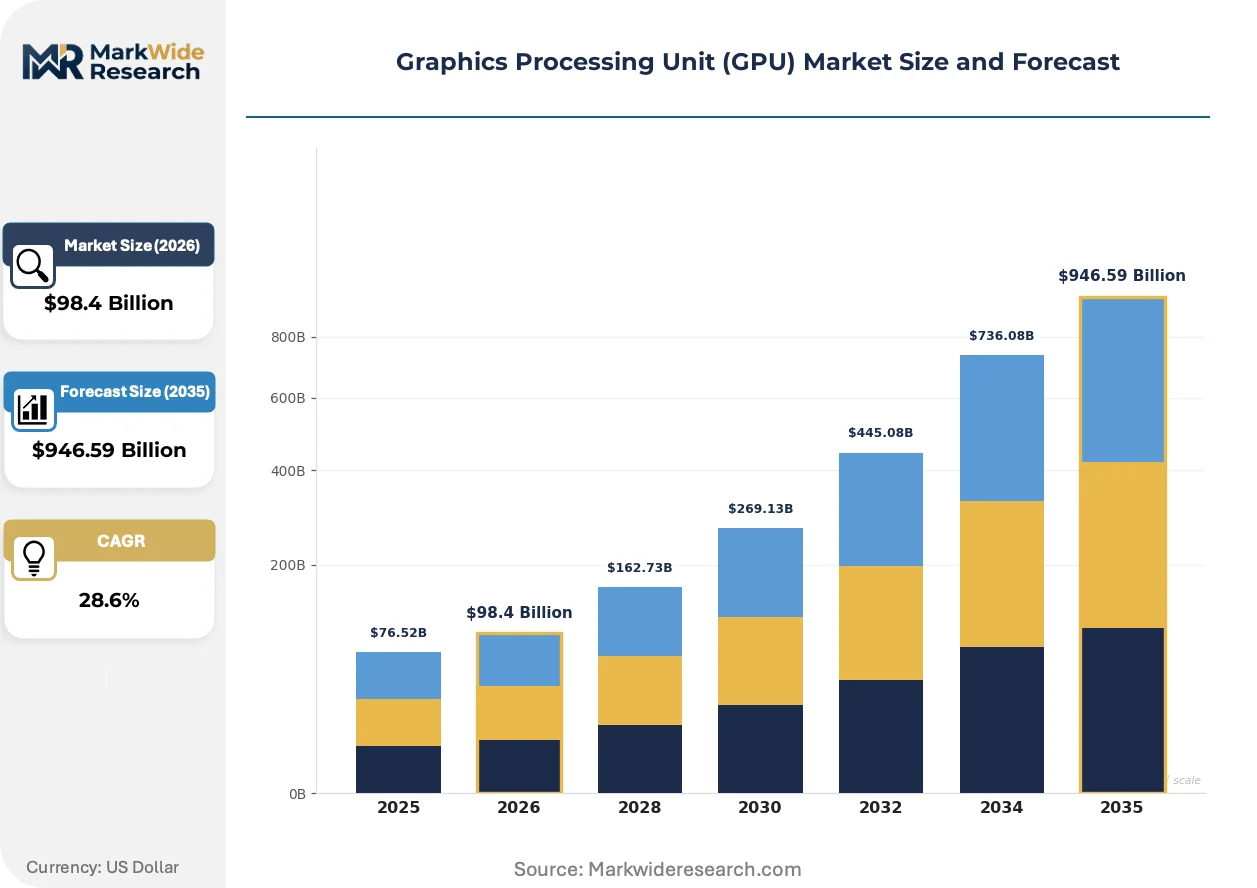
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $946.59 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete GPU, Integrated GPU, Workstation GPU, Mobile GPU, Server GPU Technology: Ray Tracing, Tensor Cores, GDDR6 Memory, Multi-GPU, AI Acceleration Application: Gaming, Professional Visualization, Data Center, Artificial Intelligence, Cryptocurrency Mining End User: OEMs, Cloud Service Providers, Research Institutes, Content Creators, Financial Analysts |
| Companies Covered | Amazon Web Services, Microsoft Corporation, NVIDIA Corporation, Samsung Electronics Co., Ltd., Apple Inc., Advanced Micro Devices Inc., Alphabet Inc., Qualcomm Incorporated, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphics Processing Unit (GPU) Market Strategic Shifts & Innovations
Accelerator architectures are fragmenting into training-optimized and inference-optimized designs, while software ecosystems and interconnect standards compete to define the next decade of GPU value capture.
Tensor processing units within GPU dies are migrating from sparse, general-purpose shader arrays toward dense matrix operation engines with dedicated FP8 and INT8 pathways. Hyperscale operators are deploying these architectures within liquid-cooled racks exceeding 100kW per cabinet. The shift is compressing product refresh cycles from 24 months toward 12-month cadences for training-class silicon.
The EU AI Act risk-classification framework is mandating transparency and traceability requirements for high-risk AI systems deployed on GPU infrastructure. Hardware vendors must now document training compute consumption and energy intensity for models above specified capability thresholds. European enterprise buyers are prioritizing accelerators with built-in telemetry and audit logging to preempt compliance friction.
Cloud marketplace procurement of GPU instances is displacing direct hardware ownership among mid-market AI developers and research institutions. Reserved capacity contracts and spot-market bidding are fragmenting buyer commitment structures. This pattern is most pronounced in North American and European markets where capital discipline favors operational expenditure models over data center buildouts.
Graphics Processing Unit (GPU) Market Segmentation
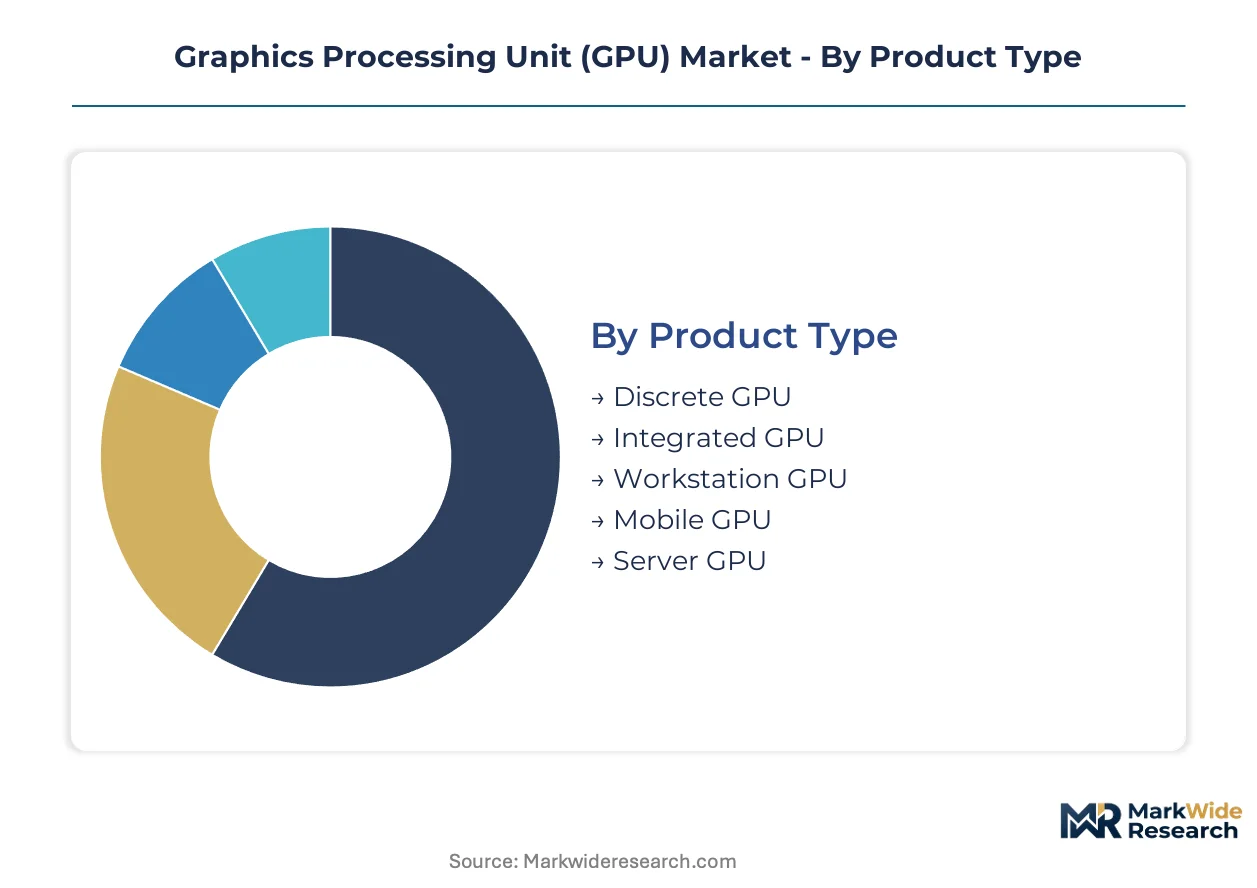
GPU market segmentation reveals divergent margin architectures across product tiers. Technology roadmaps, application intensity, and procurement models create distinct competitive arenas requiring separate strategic positioning.
Product Type:
Mature discrete architectures coexist with emerging server-class accelerators as foundry capacity reallocates toward data center demand.
- Discrete GPU:Standalone graphics cards with dedicated GDDR6X or GDDR7 memory subsystems and PCIe x16 interfaces. Gaming enthusiasts and cryptocurrency miners in the United States and Germany absorb the bulk of high-end inventory, though mining demand volatility creates inventory cycle risk.
- Server GPU:Multi-die accelerators with HBM3e stacks and NVLink or CXL interconnect fabrics for hyperscale training clusters. Cloud service providers in Virginia, Washington state, and Frankfurt am Main are securing multi-year allocation contracts ahead of CoWoS capacity expansion.
- Integrated GPU:Silicon embedded within CPU dies sharing system memory bandwidth. Intel and AMD processor platforms for cost-sensitive enterprise clients in India and Brazil.
- Workstation GPU:Professional-grade silicon with certified drivers for CAD and media pipelines. Autodesk and Dassault Systèmes software ecosystems in Japan and France.
- Mobile GPU:Low-power architectures for smartphone and tablet SOCs. Qualcomm and MediaTek design wins across Southeast Asian handset assembly.
Discrete GPU retains volume leadership; Server GPU holds the steepest expansion curve.
Technology:
Cost tier separation between premium tensor architectures and baseline memory configurations is widening as AI training workloads command pricing premiums.
- AI Acceleration:Dedicated matrix multiplication units supporting FP8, BF16, and INT8 precisions for neural network inference and training. Hyperscale operators in Singapore and the Netherlands are specifying these capabilities as mandatory for new infrastructure procurement.
- Ray Tracing:Hardware-accelerated bounding volume hierarchy traversal for real-time path tracing. Triple-A game development studios in Sweden and Canada are driving adoption through Unreal Engine 5 pipelines.
- Tensor Cores:NVIDIA-proprietary mixed-precision units within CUDA cores. Academic research clusters in Switzerland and Australia.
- GDDR6 Memory:High-speed discrete memory for mid-range gaming cards. System integrators in Poland and Mexico.
- Multi-GPU:SLI, CrossFire, or NVLink scaling across multiple dies. Render farms for visual effects in New Zealand and South Korea.
AI Acceleration commands the highest silicon allocation priority; Ray Tracing is climbing the fastest among consumer-facing technologies.
Application:
Customer type differentiation separates capital-intensive data center deployments from discretionary consumer purchases with divergent procurement cycles.
- Data Center:Foundation model training, recommendation inference, and scientific simulation workloads consuming megawatt-scale power. Microsoft, Amazon, and Google facility expansions in Iowa, Oregon, and Northern Virginia are absorbing the majority of advanced accelerator output.
- Gaming:Real-time rendering for PC and console platforms with refresh cycles tied to holiday purchasing patterns. Steam hardware survey data shows concentration in the United States, China, and Russia.
- Artificial Intelligence:Enterprise fine-tuning and edge deployment outside hyperscale environments. Automotive perception systems suppliers in Germany and Japan.
- Professional Visualization:Medical imaging, architectural rendering, and oil reservoir simulation. Siemens Healthineers and Schlumberger operations.
- Cryptocurrency Mining:Proof-of-work hashing with Ethereum transition reducing demand. Residual activity in Kazakhstan and Texas.
Data Center absorbs the dominant share of leading-edge capacity; Gaming maintains the broadest installed base across consumer segments.
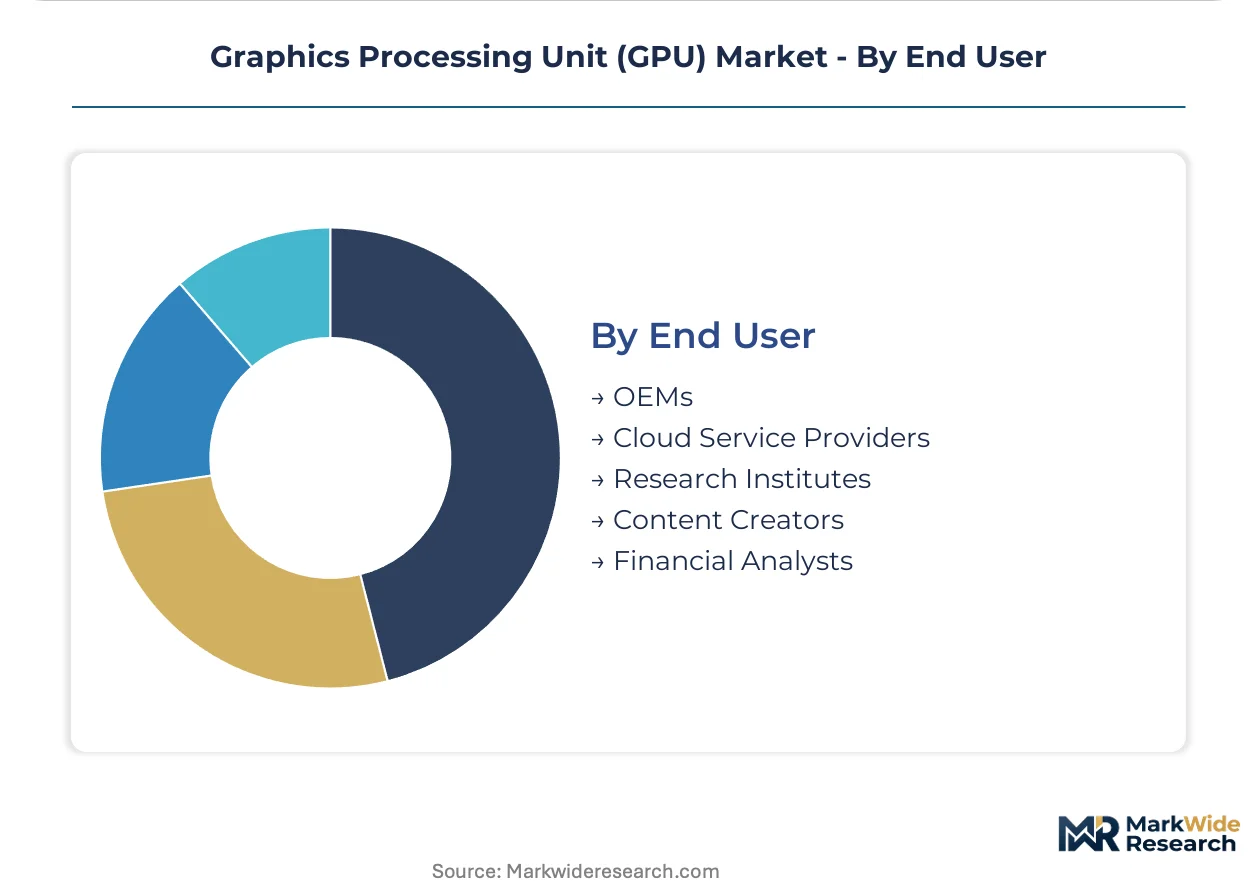
End User:
Supply concentration among foundry-accessible buyers is reshaping allocation hierarchies versus fragmented retail channels.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform designing custom silicon alongside merchant GPU procurement. Reserved instance pricing in Dublin, Singapore, and São Paulo data centers.
- OEMs:Dell, HPE, and Lenovo integrating accelerators into enterprise server platforms. Corporate refresh cycles in the United Kingdom and Australia.
- Research Institutes:CERN, Oak Ridge National Laboratory, and RIKEN securing allocation for physics and climate simulation. EU EuroHPC and U.S. DOE facility competitions.
- Content Creators:Individual professionals and boutique studios for video production and 3D rendering. YouTube and TikTok creator economies in Indonesia and Nigeria.
- Financial Analysts:Quantitative trading firms deploying GPUs for risk modeling and backtesting. Citadel and Two Sigma infrastructure in New York and London.
Cloud Service Providers control the dominant procurement volume; Research Institutes are expanding most quickly through national supercomputing initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Commerce export control frameworks are redrawing foundry access and procurement geography for advanced accelerators. Taiwan concentrates leading-edge fabrication capacity. Hyperscale data center clusters in Virginia, Washington state, and Frankfurt am Main are absorbing record accelerator volumes.
United States
Hyperscale operators in Northern Virginia and Oregon are deploying thousand-GPU pods for foundation model training. The CHIPS Act is reshoring advanced node fabrication through domestic foundry subsidies. Austin and Phoenix are emerging as semiconductor manufacturing clusters with new leading-edge facilities under construction.
Taiwan
TSMC fabricates the majority of advanced AI chips at its Hsinchu and Tainan facilities, creating single-point-of-failure exposure for global supply chains. The National Development Council is coordinating semiconductor cluster expansion amid geopolitical risk mitigation pressures. Kaohsiung is developing specialty packaging capacity to relieve CoWoS bottlenecks.
China
Domestic AI training demand is accelerating despite U.S. export controls restricting access to advanced accelerators. MIIT directives are channeling investment toward indigenous GPU design and fabrication capabilities. Shanghai and Beijing are hosting R&D clusters for domestic alternatives to restricted merchant silicon.
Germany
Automotive perception system suppliers in Stuttgart and Munich are creating demand for edge AI inference accelerators. The EU Chips Act is targeting domestic foundry capacity expansion through subsidy programs. Dresden's silicon cluster is attracting non-leading-edge accelerator fabrication commitments.
Singapore
Cloud infrastructure operators are securing multi-year GPU allocation contracts for Southeast Asian AI service delivery. The Economic Development Board is incentivizing advanced packaging and testing investments. Data center capacity in Tuas is expanding to serve regional generative AI inference demand.
Graphics Processing Unit (GPU) Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. The market structure consolidates around vertically integrated software-hardware ecosystems, with open-standard challengers occupying secondary positions. Three archetypes dominate: proprietary stack vendors, open accelerator specialists, and captive cloud silicon designers. Competitive moves center on foundry allocation contracting and compiler ecosystem lock-in.
Within the proprietary ecosystem tier, NVIDIA Corporation anchors AI accelerator positioning through CUDA-optimized software stacks. Advanced Micro Devices Inc. and Intel Corporation exemplify the open-standard competitive vector, targeting data center buyers seeking reduced switching costs. Among cloud-native silicon designers, Amazon Web Services and Microsoft Corporation represent the vertical integration archetype, developing custom accelerators alongside merchant GPU procurement.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| NVIDIA Corporation |
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Advanced Micro Devices Inc. |
| Alphabet Inc. |
| Qualcomm Incorporated |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
Taiwan's sub-5nm foundry concentration at TSMC facilities feeds directly into margin capture by hyperscale cloud operators securing multi-year allocation contracts. HBM3e memory stack scarcity and CoWoS advanced packaging bottlenecks compress accelerator output regardless of logic die availability, shifting bargaining power toward buyers with guaranteed capacity.
Pricing Analysis
North American hyperscale operators pay premiums exceeding European enterprise buyers by substantial margins due to guaranteed allocation priority and liquid-cooled rack deployment commitments. Pricing stratifies across training-class accelerators, inference-optimized silicon, and gaming discrete GPUs based on memory bandwidth specifications and interconnect fabric capabilities. Cost compression in mid-range gaming tiers is intensifying because cryptocurrency mining demand volatility creates inventory cycle risk. Cloud service providers exhibit the lowest price sensitivity due to operational expenditure models, while individual content creators and boutique studios face acute budget constraints.
Supply Chain Analysis
High-bandwidth memory wafers from South Korea, advanced packaging substrates from Taiwan, and leading-edge logic dies from TSMC's Hsinchu and Tainan facilities form the critical input triad. GPU output rests on photoresist chemicals from Japan, silicon wafers from Germany and Japan, and specialty gases from the United States. Single-source vulnerability in CoWoS packaging capacity creates structural risk for training-class accelerator availability. Distribution runs through direct allocation contracts with hyperscale operators, bypassing traditional channel intermediaries for server-class silicon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accelerator architecture fragmentation into training-optimized and inference-optimized designs creates niche opportunities for specialized entrants. Edge AI deployment outside data center environments is fragmenting procurement patterns across automotive and industrial vision systems.
For Market Incumbents: Harden software ecosystem lock-in through compiler toolchain investments that raise switching costs for CUDA-optimized codebases. Secure foundry allocation commitments in Phoenix and Austin through CHIPS Act facility partnerships to mitigate Taiwan concentration risk. Deepen backward integration into HBM3e memory supply through captive arrangements with South Korean suppliers.
For New Entrants and Emerging Players: Establish a beachhead in automotive edge inference accelerators for Stuttgart and Munich perception system suppliers seeking alternatives to data center-class silicon. Target EU Chips Act subsidy pathways in Dresden for non-leading-edge accelerator fabrication commitments. Lead with open-standard CXL and UCIe interconnect compatibility to reduce enterprise buyer switching costs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across server-class accelerator design houses due to multi-billion-dollar foundry prepayment requirements. Five-to-ten-year viability favors firms with guaranteed TSMC allocation or domestic U.S. fabrication pathways. Watch hyperscaler custom silicon announcements from Amazon Web Services and Microsoft Corporation as inflection indicators for merchant GPU displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Expansion | Relieves advanced packaging bottlenecks throttling NVIDIA and AMD accelerator output. |
| CUDA Ecosystem Deepening | Raises code portability barriers protecting incumbent software-hardware integration. |
| Open Interconnect Adoption | Enables multi-vendor GPU pooling through CXL and UCIe protocol implementation. |
| Edge AI Accelerator Launch | Captures automotive and industrial inference demand outside hyperscale data centers. |
| Domestic Foundry Commitment | Secures CHIPS Act subsidy access for Intel and emerging U.S.-based fabrication. |
Research Approach
The analysis maps discrete GPU, server GPU, integrated GPU, workstation GPU, and mobile GPU segments, each validated through hyperscale infrastructure planners, semiconductor procurement executives, foundry account managers, and automotive tier-one supplier engineers. Primary interviews combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, TSMC technology symposium materials, and EU Chips Act implementation documents. Bottom-up unit shipment estimates triangulated against top-down foundry wafer allocation data.
Assumptions held fixed include U.S. Department of Commerce export control continuity and TSMC leading-edge capacity expansion timelines, while variables included hyperscaler custom silicon adoption rates and EU foundry subsidy disbursement pacing. Segmentation dimensions modeled encompass product type, technology capability tier, application intensity, and end-user procurement structure across the projection horizon. CAGRs derived from wafer start forecasts, memory supply constraints, and cloud infrastructure deployment pipelines.
Stress conditions across foundry geopolitical disruption, HBM supply contraction, and hyperscaler demand volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and technology transition pacing. Cross-checking against hyperscaler earnings call capex guidance and foundry revenue recognition patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Edge Artificial Intelligence Chips Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Americas Digital Signal Processor Market