
 United States Data Center Processor Market | 2026-2036
United States Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Processor Market Insights
Hyperscale cloud computing is consolidating its grip on procurement volumes across the United States data center processor landscape. Intel Corporation sustains broad manufacturing scale across x86 architectures for enterprise workloads. NVIDIA Corporation dominates parallel processing architectures for artificial intelligence training and inference. Ampere Computing specializes in ARM-based cloud-native processors that challenge incumbent power efficiency benchmarks.
Data center processors are integrated circuits engineered for continuous high-throughput computation in thermally constrained server environments, typically fabricated on sub-5 nanometer process nodes with thermal design power ratings exceeding 200 watts. CPU shipments retain the largest revenue footprint among processor types, though GPU accelerators command premium pricing for machine learning workloads. Cloud providers represent the fastest-growing end user segment, driven by custom silicon programs and multi-cloud deployment strategies that bypass traditional server vendor channels.
The CHIPS and Science Act directs Department of Commerce funding toward domestic foundry expansion, while NIST cybersecurity frameworks shape supply chain verification requirements for federal data center procurements. EPA energy efficiency standards and state-level renewable power mandates in California and Texas are tightening operational parameters for processor thermal profiles. Stakeholders must weigh captive silicon investments against merchant supply resilience as power density constraints reshape facility economics.
Market Dynamics
Hyperscale cloud providers are deploying captive processor designs that bypass traditional merchant silicon supply chains, compressing procurement cycles while concentrating design talent in Northern Virginia and Austin. This vertical integration is reshaping competitive positioning across the domestic data center landscape.
Growth Catalysts
- CHIPS and Science Act funding:Department of Commerce capital injections are accelerating domestic foundry construction in Arizona and Texas, reducing reliance on overseas fabrication for advanced node processors.
- AI inference demand:Enterprise adoption of large language model deployments is driving GPU accelerator procurement volumes beyond historical server refresh cycles.
- Power density mandates:Northern Virginia's Data Center Alley is forcing 50-kilowatt rack deployments as utility interconnection queues extend beyond 36 months.
Market Restraints
- Advanced packaging bottlenecks:CoWoS and 2.5D interposer capacity constraints at Taiwan-based OSATs are throttling high-bandwidth memory integration for AI accelerators.
- EPA carbon intensity rules:Proposed power usage effectiveness thresholds threaten operational permits for facilities running thermal design power ratings above 350 watts per socket.
- Neuromorphic silicon substitution:Early-stage analog in-memory compute architectures from federal research labs are targeting inference workloads below 10 watts.
Strategic Opportunities
- Edge inference nodes:Autonomous vehicle data lakes in Detroit and Pittsburgh are creating distributed processor demand outside hyperscale concentration zones.
- DOE exascale procurement:National laboratory supercomputing contracts mandate domestic content verification, opening captive supply chain opportunities for emerging foundries.
- Silicon photonics convergence:Co-packaged optical interconnects are enabling 100-terabit chip-to-chip bandwidth that electrical signaling cannot sustain.
Industry Challenges
- Advanced node lithography talent:Domestic cleanroom engineering programs are producing fewer than 400 qualified technicians annually against foundry expansion timelines.
- Legacy x86 integration friction:ARM-based cloud-native workloads require hypervisor re-architecture that extends enterprise migration timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Processor Market |
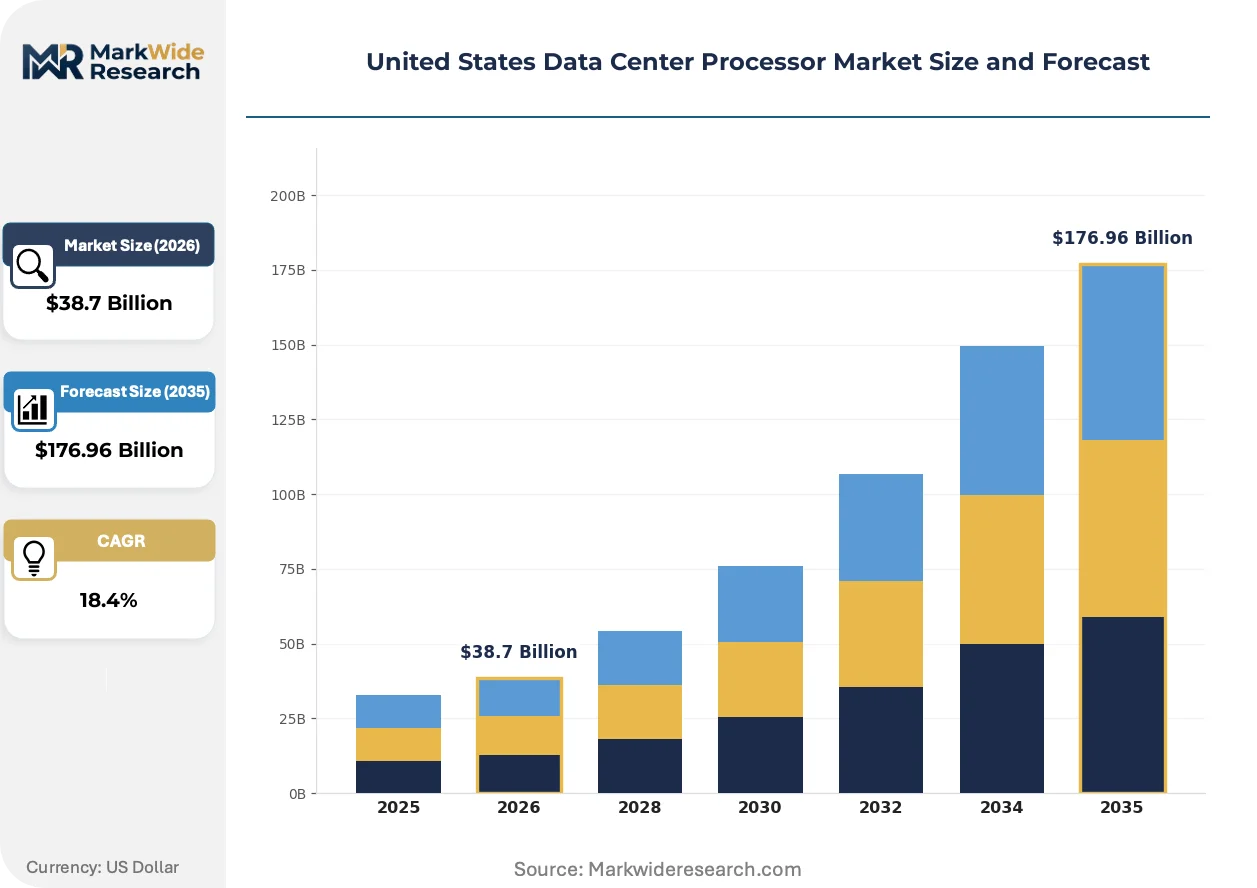
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPU, GPU, FPGA, ARM End User: Cloud Providers, Enterprises, Colocation, Government Deployment Model: On-Premises, Hybrid, Multi-Cloud, Private Application: Big Data Analytics, Machine Learning, Web Hosting, Virtualization |
| Companies Covered | Ampere Computing, Broadcom Inc, Intel Corporation, IBM Corporation, Qualcomm Incorporated, Advanced Micro Devices, Arm Holdings, Amazon Web Services, NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Processor Market Trends and Innovations
Processor architectures are fragmenting across workload-specific designs as power constraints and thermal density limits force abandonment of general-purpose scaling. Custom silicon programs are compressing the traditional three-year server refresh cycle into 18-month design iterations.
Chiplet-based modular designs are rewriting integration economics for data center processors. AMD and Intel are disaggregating memory controllers, I/O die, and compute tiles into separate chiplets that TSMC and Intel Foundry Services assemble through advanced packaging. Hyperscale buyers are demanding socket-level customization that merchant silicon historically could not accommodate. This modularity is compressing time-to-market for workload-optimized configurations while elevating packaging complexity to a primary competitive variable.
The EPA's proposed ENERGY STAR Version 4.0 server specifications are tightening idle power draw ceilings and mandating granular power telemetry reporting. These standards are forcing processor vendors to embed sub-watt monitoring circuits and dynamic voltage-frequency scaling algorithms that respond to real-time carbon intensity signals. Federal data center procurements through the General Services Administration are prioritizing compliance, creating a bifurcated market between certified and non-certified silicon.
Direct liquid cooling adoption is accelerating procurement model evolution across enterprise and colocation segments. Buyers are shifting from capital expenditure-based server ownership toward thermal-density-rated rack leasing that bundles processor, cooling infrastructure, and power allocation. This unbundling is most visible in Phoenix and Dallas-Fort Worth markets where ambient temperatures exceed 40 degrees Celsius for 90 days annually, making air-cooled deployments economically untenable for accelerators above 700 watts.
United States Data Center Processor Market Segmentation
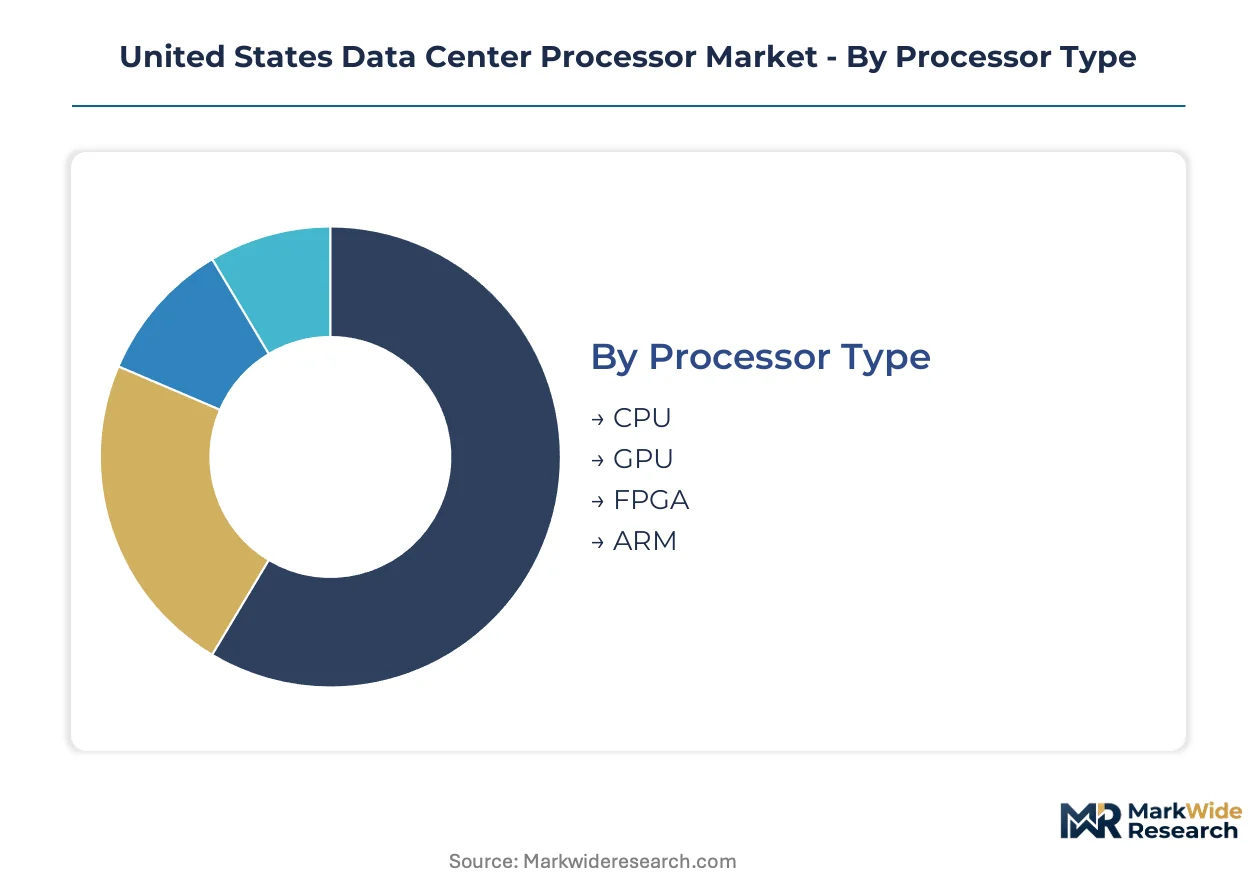
Processor segmentation in the United States data center market reflects divergent thermal constraints, software ecosystem dependencies, and workload parallelization requirements. Buyers select architectures based on power density limits, inference latency tolerances, and hypervisor compatibility rather than raw transistor counts alone.
Processor Type:
Architectural differentiation centers on instruction set parallelism, memory bandwidth hierarchies, and thermal design power envelopes that dictate rack-level deployment economics.
- CPU:x86 and ARM-based central processors handle sequential workloads with extensive legacy software optimization. Northern Virginia's Data Center Alley concentrates CPU procurement for general-purpose virtualization as power constraints favor moderate thermal footprints over accelerator density.
- GPU:Massively parallel tensor architectures from NVIDIA and AMD dominate training workloads for large language models. Texas-based hyperscale facilities are absorbing GPU volumes that exceed historical server refresh cycles by factors of three to five as inference demand compounds.
- FPGA:Field-programmable gate arrays from Xilinx and Intel enable custom logic for low-latency financial trading and network function virtualization.
- ARM:Cloud-native instruction sets from Ampere Computing and AWS Graviton challenge x86 power efficiency benchmarks in containerized workloads.
CPU leads on scale; GPU leads on momentum.
End User:
Procurement concentration varies by capital intensity, captive silicon capabilities, and compliance requirements that shape vendor selection criteria.
- Cloud Providers:AWS, Microsoft Azure, and Google Cloud operate custom silicon programs that bypass traditional merchant supply chains. These buyers command socket-level customization and compress design cycles to eighteen-month iterations.
- Enterprises:Fortune 500 manufacturers and financial services firms maintain on-premises infrastructure for regulatory data sovereignty. Michigan automotive data lakes and Pittsburgh robotics clusters are creating distributed demand outside hyperscale zones.
- Colocation:Equinix and Digital Realty operate multi-tenant facilities where thermal-density-rated rack leasing bundles processors with liquid cooling infrastructure.
- Government:DOE national laboratories mandate domestic content verification under CHIPS Act procurement rules, opening captive supply opportunities for emerging foundries.
Cloud providers dominate procurement volume; government contracts offer the steepest expansion trajectory for domestic silicon.
Deployment Model:
Infrastructure topology selection reflects data gravity requirements, latency sensitivities, and regulatory jurisdiction constraints across federal and state frameworks.
- On-Premises:Dedicated facilities in enterprise campuses retain sensitive workloads under direct operational control. Defense contractors and pharmaceutical manufacturers favor this model for ITAR and FDA compliance boundaries.
- Hybrid:Split architectures connect private infrastructure with public cloud burst capacity. California enterprises deploy hybrid models to satisfy state renewable power mandates while maintaining core data sovereignty.
- Multi-Cloud:Workload portability across AWS, Azure, and Google Cloud reduces vendor lock-in but complicates processor optimization. Financial services firms in New York and Chicago lead multi-cloud adoption for trading system resilience.
- Private:Single-tenant cloud environments replicate hyperscale operational models without shared infrastructure. Healthcare systems deploy private clouds to isolate HIPAA-regulated patient data.
Hybrid deployments anchor current infrastructure; multi-cloud architectures are gaining share fastest among regulated industries.
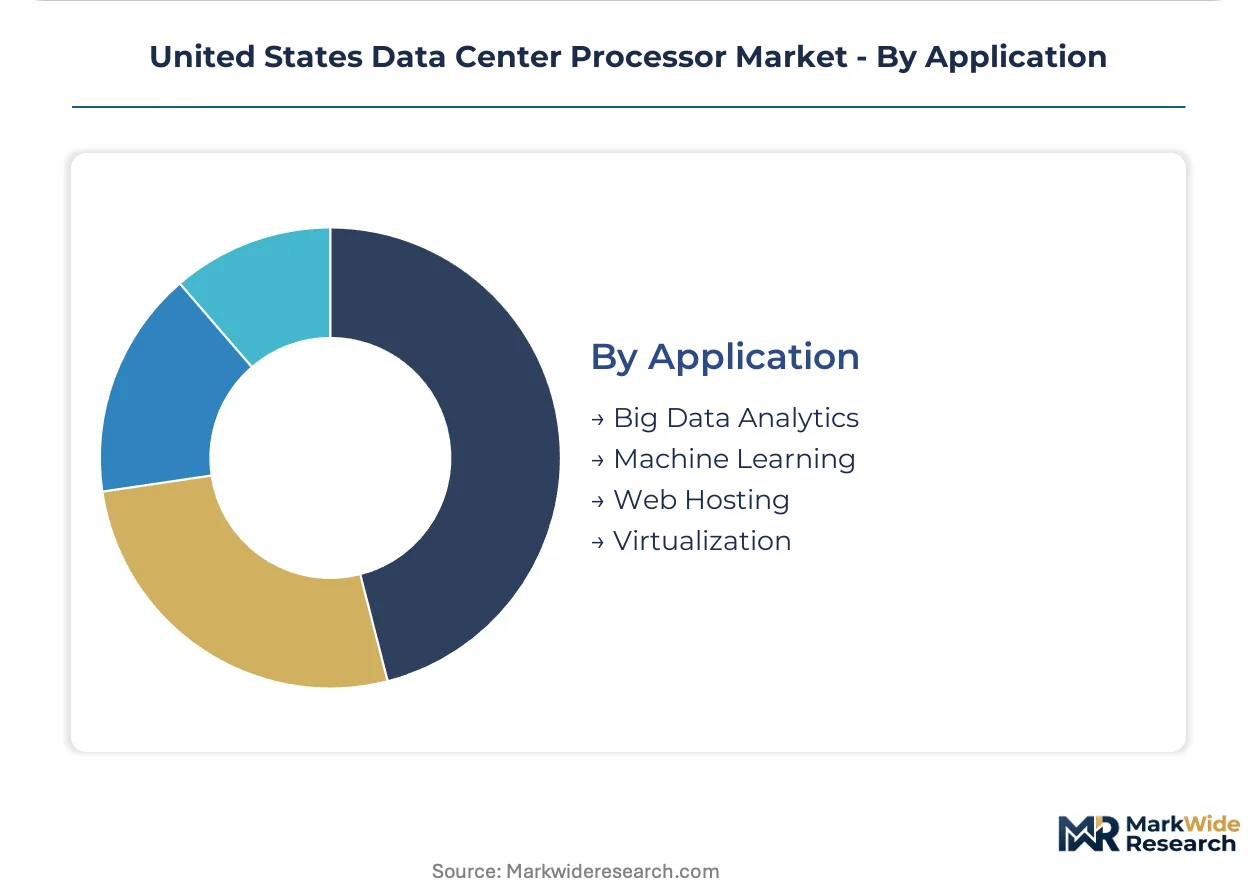
Application:
Workload characteristics determine memory hierarchy requirements, interconnect bandwidth needs, and the economic viability of specialized versus general-purpose silicon.
- Big Data Analytics:Apache Spark and Hadoop clusters demand high-memory CPU configurations with NVMe storage hierarchies. Retail and logistics enterprises in Illinois and Ohio deploy analytics infrastructure for supply chain optimization.
- Machine Learning:Training and inference pipelines require GPU accelerators with high-bandwidth memory and tensor cores. Arizona and Texas foundry-adjacent facilities are concentrating ML training capacity to minimize data movement costs.
- Web Hosting:Content delivery and application serving prioritize per-watt transaction throughput over peak compute density. Edge nodes in Florida and Georgia handle latency-sensitive web workloads.
- Virtualization:Hypervisor consolidation of legacy enterprise workloads sustains x86 CPU demand despite ARM competitive pressure. Federal agencies maintain virtualization estates for cost efficiency in General Services Administration-managed facilities.
Virtualization retains the largest installed base; machine learning exhibits the steepest demand curve as model complexity compounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data Center Alley in Northern Virginia anchors domestic processor demand as hyperscale cloud providers concentrate captive silicon design talent across the Washington metropolitan corridor.
California
Santa Clara County fabs and San Francisco Bay Area AI labs drive GPU accelerator procurement for large language model training. California's Title 24 building efficiency standards mandate granular power telemetry reporting for data center facilities exceeding 500 kilowatts. Los Angeles and Silicon Valley colocation operators are deploying direct liquid cooling infrastructure to satisfy state renewable power mandates while maintaining accelerator density.
Texas
Austin and Dallas-Fort Worth hyperscale campuses absorb processor volumes exceeding historical server refresh cycles by factors of three to five. Texas Commission on Environmental Quality rules on water usage for cooling systems are accelerating closed-loop liquid cooling adoption. Taylor and Round Rock foundry-adjacent facilities concentrate machine learning training capacity to minimize data movement costs between fabrication and deployment.
Arizona
Phoenix metropolitan data centers face 90-day annual ambient temperature extremes exceeding 40 degrees Celsius, making air-cooled deployments economically untenable for accelerators above 700 watts. Arizona Corporation Commission interconnection queue delays extending beyond 36 months are forcing 50-kilowatt rack deployments. Intel Foundry Services operations in Chandler create captive supply chain opportunities for emerging domestic fabrication.
Illinois
Chicago financial exchanges and Aurora enterprise campuses sustain demand for FPGA-based low-latency trading infrastructure. Illinois Commerce Commission rate structures for data center power are influencing thermal design power selection criteria. Retail and logistics enterprises in Rockford and Peoria deploy analytics infrastructure for supply chain optimization using high-memory CPU configurations.
Oregon
Hillsboro and Portland metropolitan facilities leverage Pacific Northwest hydroelectric power to satisfy carbon intensity requirements for federal cloud procurements. Oregon Department of Environmental Quality air quality permits are tightening operational parameters for diesel backup generators supporting processor-critical loads. Prineville and Boardman hyperscale campuses represent distributed demand outside Northern Virginia concentration zones.
United States Data Center Processor Market Competitive Landscape
Captive silicon programs dominate the current landscape as hyperscale cloud providers compress design cycles into eighteen-month iterations. The vendor base clusters around three strategic archetypes: merchant silicon incumbents with broad x86 manufacturing scale, parallel processing specialists commanding premium pricing for AI workloads, and ARM-based challengers targeting cloud-native power efficiency benchmarks. Competitive positioning hinges on foundry capacity allocation and advanced packaging integration capabilities rather than instruction set architecture alone.
Within the merchant silicon tier, Intel Corporation and Advanced Micro Devices exemplify scale-driven incumbents with disaggregated chiplet architectures. NVIDIA Corporation occupies a distinct position among parallel processing specialists as tensor core demand compounds beyond historical server refresh patterns. Ampere Computing represents the ARM-native challenger archetype with cloud-native instruction sets that challenge x86 thermal footprints. These three anchors illustrate the competitive fragmentation between general-purpose legacy optimization and workload-specific accelerator dominance.
| Leading Market Players |
|---|
| Ampere Computing |
| Broadcom Inc |
| Intel Corporation |
| IBM Corporation |
| Qualcomm Incorporated |
| Advanced Micro Devices |
| Arm Holdings |
| Amazon Web Services |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
TSMC's wafer pricing index cascades through the United States data center processor supply chain, compressing margins for merchant silicon vendors while hyperscale captives absorb cost volatility through backward integration into foundry partnerships.
Pricing Analysis
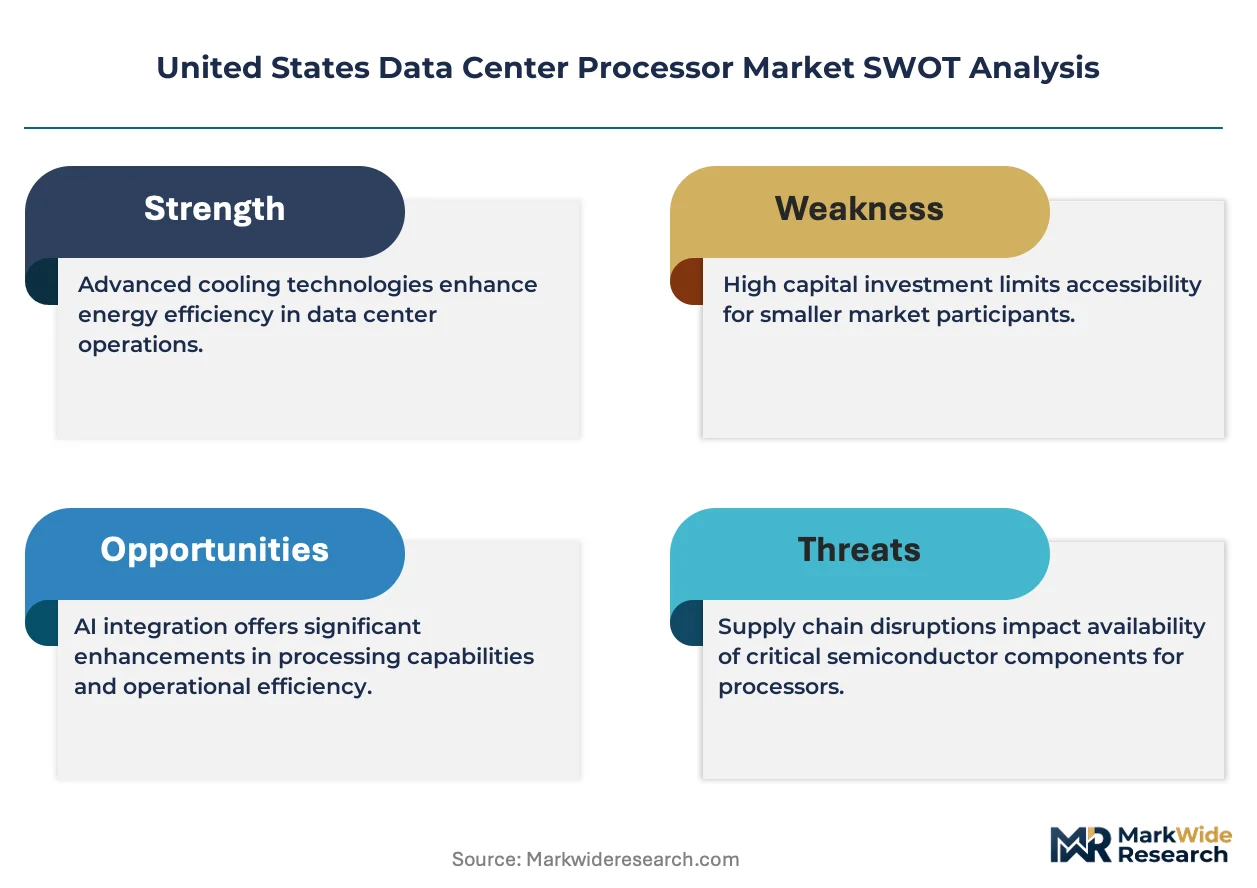
Input-cost pass-through from advanced node fabrication dominates pricing structures across the merchant silicon tier. Three-tier pricing structure across premium accelerator, standard server CPU, and economy cloud-native tiers reflects thermal design power segmentation and memory bandwidth hierarchies. Cost compression in the standard tier is intensifying because hyperscale buyers are consolidating procurement volumes around socket-level customization. Enterprise IT departments exhibit the highest price sensitivity due to extended server refresh cycles, while cloud providers prioritize performance-per-watt metrics over unit economics.
Supply Chain Analysis
CHIPS Act domestic content mandates are reshaping sourcing patterns for federal data center procurements, compelling vendors to qualify emerging foundry capacity in Arizona and Texas. Taiwan, South Korea, and the United States anchor global supply for sub-5 nanometer logic fabrication, with CoWoS advanced packaging capacity concentrated at Taiwan-based OSATs. The supply chain draws from high-purity silicon wafers, EUV photoresists, and high-bandwidth memory stacks as critical inputs. Single-source vulnerability at Taiwan packaging houses threatens AI accelerator delivery timelines. Distribution runs through direct hyperscale procurement channels that bypass traditional server OEM hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States data center processor market functions as a geographic-arbitrage play where Arizona's foundry-adjacent deployment zones command premium thermal-density pricing against Northern Virginia's power-constrained rack economics.
For Market Incumbents: Extend chiplet disaggregation roadmaps to capture socket-level customization demand from hyperscale buyers before ARM-native architectures erode x86 virtualization share. Prioritize advanced packaging capacity reservations at domestic OSATs to mitigate Taiwan concentration risk. Invest in liquid-cooled reference designs that satisfy EPA carbon intensity thresholds for federal procurement eligibility. For New Entrants and Emerging Players: Cloud-native ARM licensing partnerships offer the lowest-friction entry vector for fabless processor startups targeting containerized workloads. Edge inference nodes in Detroit and Pittsburgh represent the most penetrable white-space geography outside hyperscale concentration zones. Pursue DOE national laboratory qualification pathways to establish domestic content credibility under CHIPS Act procurement rules. For Investors and Strategic Acquirers: Consolidation pressure builds where advanced packaging capabilities concentrate among a handful of OSATs with CoWoS expertise. The five-to-ten year viability window favors acquisition targets with established foundry relationships and federal security clearance pathways. Watch hyperscale capex guidance revisions as the primary inflection signal for merchant silicon demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Program Expansion | AWS Graviton and Microsoft Cobalt deployments displace merchant CPU volumes in cloud-native workloads. |
| Domestic Foundry Qualification | Intel Foundry Services and TSMC Arizona secure CHIPS Act compliance for federal supercomputing contracts. |
| Advanced Packaging Capacity Buildout | CoWoS expansion at domestic OSATs reduces Taiwan dependency for AI accelerator HBM integration. |
| Direct Liquid Cooling Infrastructure | Phoenix and Dallas-Fort Worth colocation operators bundle thermal-density-rated rack leasing with processor procurement. |
| Silicon Photonics Integration | Co-packaged optical interconnects enable 100-terabit chip-to-chip bandwidth for exascale training clusters. |
Research Methodology
Direct dialogue with hyperscale procurement executives, foundry operations directors, federal contracting officers, and thermal infrastructure engineers grounded the qualitative assessment. Primary insights were cross-referenced against secondary sources including SEC 10-K filings, hyperscaler capex disclosures, DOE exascale procurement documentation, and EPA ENERGY STAR server specification drafts. Bottom-up triangulation against top-down market sizing validated segment-level assumptions across processor architectures and deployment models.
Segmentation outputs across the modeling period reflect discrete-event simulation of procurement cycles, thermal density constraints, and regulatory compliance thresholds. The analytical framework modeled processor type, end-user archetype, deployment topology, and application workload as core dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating power density mandates and AI inference adoption curves. Foundry capacity expansion timelines and CHIPS Act funding disbursement schedules served as critical forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for neuromorphic analog compute would alter the outlook for low-wattage inference deployment. Forecasts reflect assumptions regarding domestic foundry yield maturation and hyperscale vertical integration momentum. Geopolitical disruption to Taiwan Strait logistics or EPA carbon intensity rule acceleration represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
Application Processor Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
Data Processing Neuromorphic Chip Market