
 Europe Semiconductor Etch Equipment Market | 2026-2036
Europe Semiconductor Etch Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Semiconductor Etch Equipment Market Foresight
Memory chip manufacturers are unwinding legacy procurement patterns as foundries scale advanced-node capacity in Dresden and Leuven. Applied Materials, Inc leverages its dry etch portfolio to anchor high-volume logic production lines across Central Europe. Lam Research Corporation competes through specialized plasma etch systems tailored to EUV-resist processing requirements. Tokyo Electron Ltd sustains its position by controlling wet etch chemistry delivery for next-generation memory stacks.
Semiconductor etch equipment encompasses systems that selectively remove material from wafer surfaces using chemical, plasma, or ion-based processes, typically operating at pressures from millitorr to atmospheric ranges with sub-nanometer precision control. These tools enable pattern transfer from photoresist masks into underlying films of silicon, dielectric, or metal, forming the interconnect and transistor structures essential to integrated circuit functionality. Dry etch systems dominate capital allocation as leading-edge nodes demand anisotropic profiles impossible with wet chemistry alone. Foundries represent the fastest-expanding end-user category as Europe's sovereign chip initiatives attract pure-play operators to the region. Plasma etch technology leads in revenue contribution due to its versatility across logic, memory, and power device applications.
The EU Chips Act and REACH compliance frameworks are reshaping equipment qualification requirements, with ECHA chemical restrictions forcing wet etch chemistry reformulation across installed tool bases. CE marking and MDR-derived safety standards extend certification burdens to subcomponent suppliers, compressing margins for non-integrated vendors. Stakeholders must monitor how the EU AI Act's chip traceability provisions cascade into etch equipment data-logging specifications before the next procurement cycle.
Market Dynamics
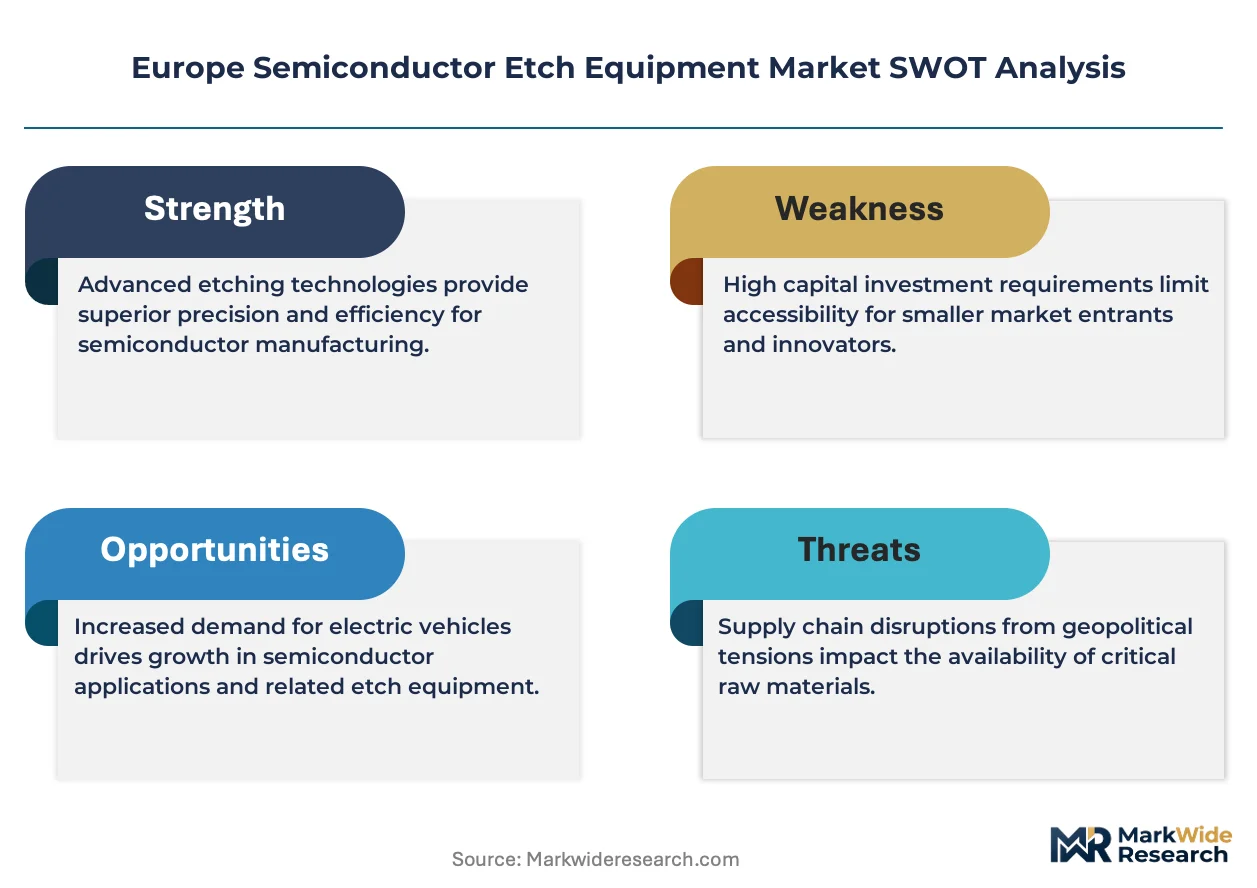
Equipment suppliers face structural pressure as EU Chips Act funding concentrates new foundry builds in Germany, the Netherlands, and France while REACH chemical restrictions force simultaneous wet etch chemistry reformulation across installed bases.
Growth Catalysts
- Electric vehicle powertrain semiconductor content:Automotive chipmakers in Germany and France are expanding etch equipment procurement to meet rising silicon carbide and IGBT demand from EV manufacturers.
- EU Chips Act capital deployment:Public funding channels are accelerating domestic fabrication capacity construction, directly lifting equipment orders for Dresden and Leuven expansion projects.
- EUV lithography scaling:Advanced-node logic production requires plasma etch systems capable of EUV-resist pattern transfer with sub-nanometer precision control.
Market Restraints
- Fluorinated gas supply concentration:Critical etch chemistries depend on limited European suppliers subject to F-Gas Regulation phase-down schedules.
- CE marking certification burdens:MDR-derived safety standards extend to subcomponent vendors, compressing margins for non-integrated equipment suppliers.
- Legacy wet etch substitution limits:Isotropic chemistry cannot achieve anisotropic profiles required at 3nm nodes, constraining memory stack processing options.
Strategic Opportunities
- Poland and Czech Republic packaging clusters:Advanced packaging capacity expansion in Central Europe creates demand for specialized dielectric etch systems.
- EU AI Act chip traceability mandates:Data-logging specifications for etch equipment will differentiate qualified suppliers in the next procurement cycle.
- Atomic layer etch convergence:Hybrid plasma-thermal processes enable Angstrom-scale precision for gate-all-around transistor architectures.
Industry Challenges
- Plasma physicist talent scarcity:Specialized expertise in reactor design and process chemistry is concentrated among a small pool of experienced engineers in Leuven and Dresden.
- Installed base chemistry transition:REACH compliance requires reformulating wet etch chemistries without disrupting production continuity at operating fabs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Semiconductor Etch Equipment Market |
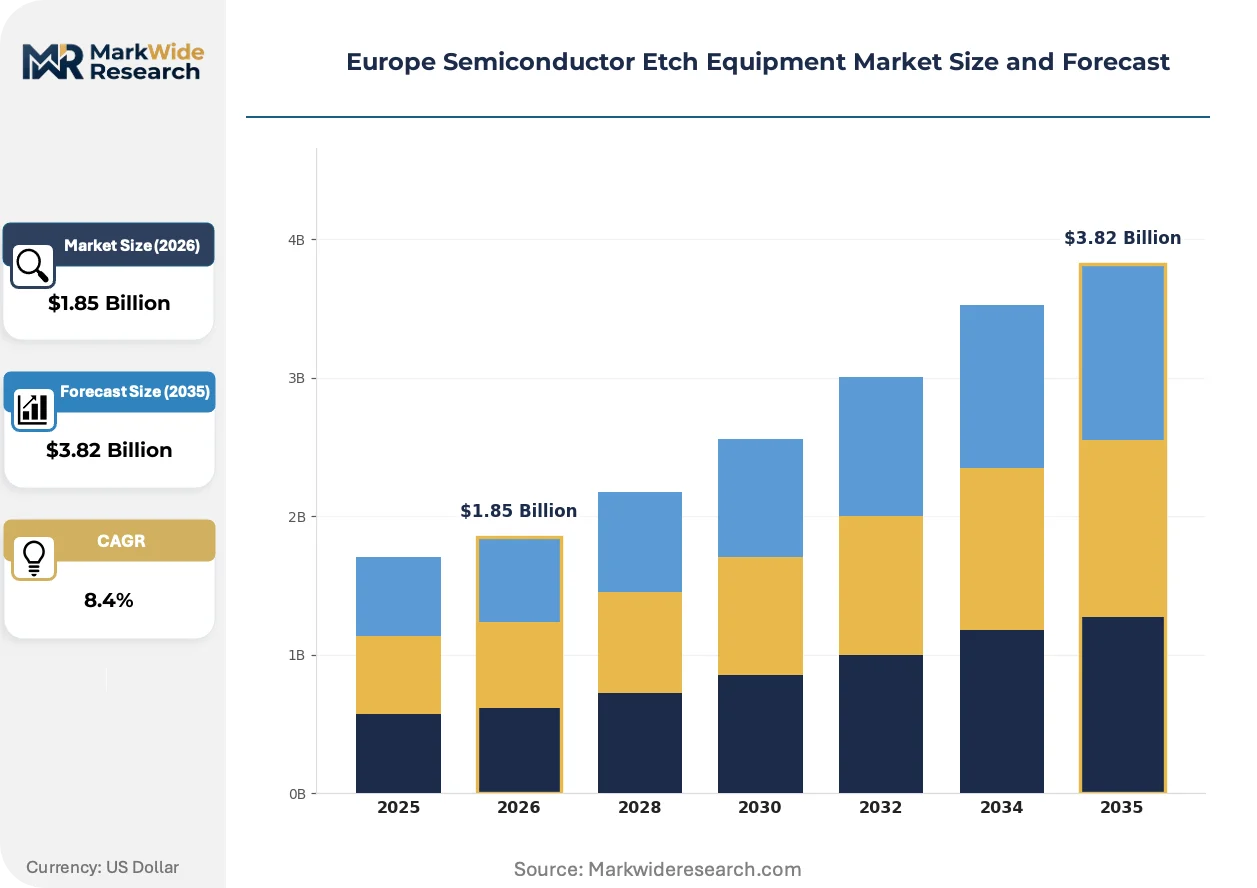
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Etch, Wet Etch, Plasma Etch, Reactive Ion Etch Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Laser Annealing End User: Foundries, Integrated Device Manufacturers, Memory Chip Manufacturers, Fabless Companies Application: Microelectronics, Photonics, MEMS, Nanotechnology |
| Companies Covered | Applied Materials, Inc, Lam Research Corporation, Hitachi High-Tech Europe GmbH, SPTS Technologies Ltd., ASM International, Tokyo Electron Ltd., RENA Technologies GmbH, Oxford Instruments, EV Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Semiconductor Etch Equipment Market Shifts & Advancements
Process control architectures are evolving rapidly as European foundries scale EUV-based production and regulatory frameworks tighten chemical accountability requirements.
Atomic layer etch technology is fragmenting process development roadmaps across European IDMs. This technique enables single-atom removal precision for 2nm-class gate structures. Foundries in Dresden are adopting ALE modules for critical dimension control in high-volume logic lines. The technology is fragmenting capital allocation between incremental plasma upgrades and disruptive ALE platform investments.
REACH chemical restrictions are forcing wet etch chemistry reformulation across the European installed base. ECHA's PFAS restriction proposals threaten fluorinated polymer components in process kits. Equipment vendors serving Leuven and Dresden fabs are accelerating alternative material qualification programs. Memory manufacturers face the steepest transition costs due to high-volume wet bench configurations.
Long-term service contracting is displacing transactional maintenance arrangements in European foundry procurement. Pure-play operators in Germany and the Netherlands are bundling etch chamber refurbishment with predictive analytics subscriptions. OEMs are responding with outcome-based uptime guarantees rather than hourly service rates. This shift is most visible at Dresden's expanding logic facilities where tool utilization targets exceed 95 percent.
Europe Semiconductor Etch Equipment Market Segmentation
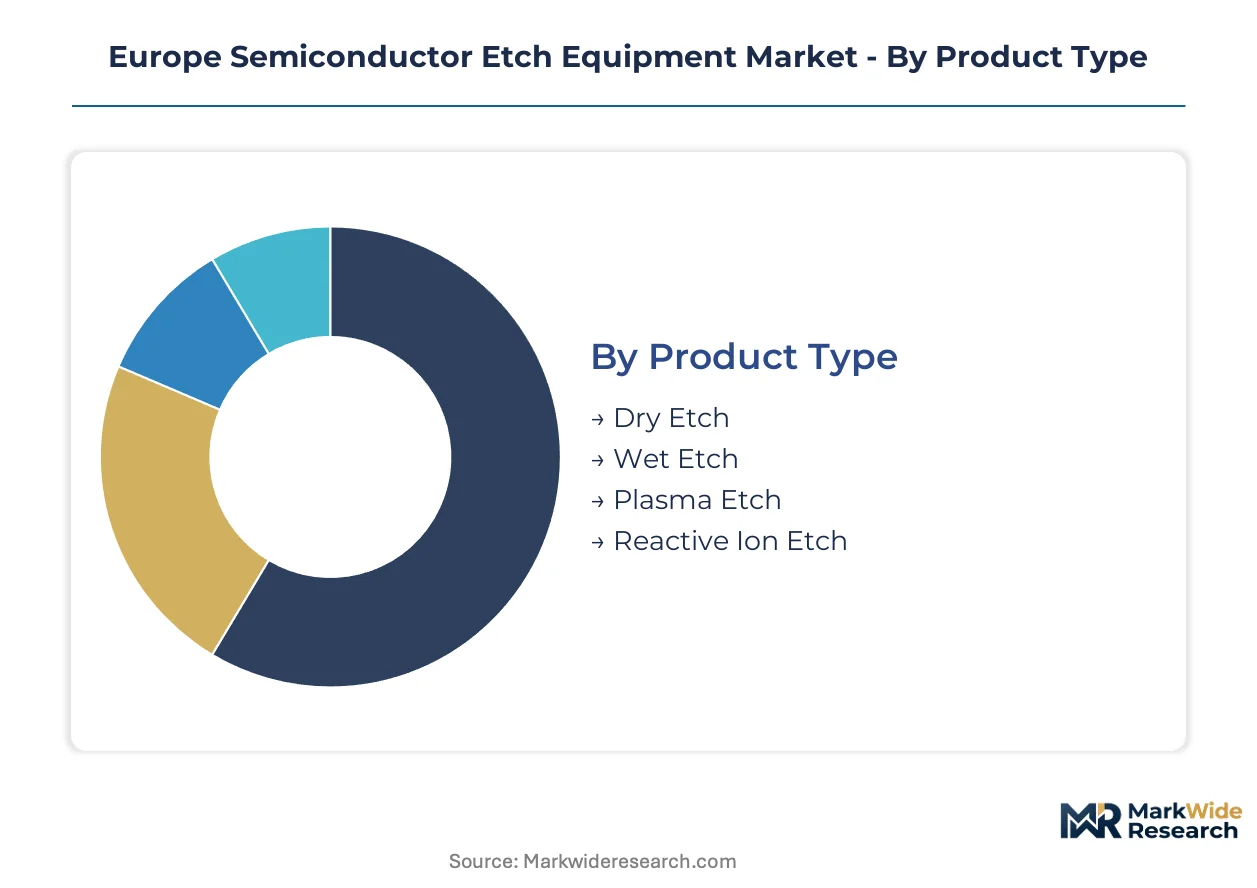
Etch equipment segmentation reveals how technology choices align with Europe's sovereign chip manufacturing priorities. Procurement patterns diver sharply between legacy memory facilities and advanced-node foundries emerging under EU Chips Act funding.
Product Type:
Dry etch systems dominate German and Dutch fab investments, while wet etch retains installed base concentration in legacy memory clusters.
- Dry Etch:Anisotropic plasma systems enable sub-nanometer precision for EUV-resist pattern transfer in leading-edge logic production. Dresden and Leuven foundries are scaling capacitively coupled plasma configurations for gate-all-around transistor architectures.
- Plasma Etch:Inductively coupled reactors deliver high-density ion flux for dielectric and metal etch applications. French automotive chipmakers are procuring these systems for silicon carbide power device fabrication.
- Wet Etch:Isotropic chemistry processes blanket films for memory stack and MEMS release applications. REACH compliance is forcing chemistry reformulation across Leuven's high-volume wet bench installations.
- Reactive Ion Etch:Low-pressure ion bombardment systems serve research institutions and pilot lines. Czech packaging clusters are adopting these tools for dielectric etch in advanced interposer manufacturing.
Dry etch holds the largest share; momentum sits with plasma etch configurations.
Technology:
Process technology selection tracks the migration from planar to three-dimensional device architectures across European IDMs.
- Atomic Layer Deposition:Angstrom-scale thickness control enables conformal dielectric and metal films for 2nm-class transistors. Dresden foundries are integrating ALE-ALD hybrid modules for critical dimension uniformity.
- Chemical Vapor Deposition:Plasma-enhanced CVD systems deposit low-k dielectrics and barrier layers for interconnect scaling. Netherlands-based equipment vendors are qualifying these processes for EUV lithography compatibility.
- Physical Vapor Deposition:Sputtering systems deposit metal seed layers and hard masks for patterning stacks. German memory manufacturers maintain installed base concentration for tungsten and copper metallization.
- Laser Annealing:Millisecond thermal processing activates dopants without thermal budget damage to delicate structures. French research consortia are piloting these systems for advanced logic process development.
Chemical Vapor Deposition anchors current procurement volumes; Atomic Layer Deposition is climbing the fastest as gate-all-around architectures mature.
End User:
Customer type distribution reflects the structural shift from integrated manufacturing to foundry-centric production models.
- Foundries:Pure-play operators command the most aggressive etch tool roadmaps for EUV-based logic production. Germany's expanding Dresden cluster and Netherlands greenfield sites are driving multi-billion euro equipment commitments.
- Integrated Device Manufacturers:Vertically integrated manufacturers balance leading-edge and mature node requirements. French and German automotive chip IDMs are prioritizing power device etch capacity for EV supply chains.
- Memory Chip Manufacturers:3D NAND stack scaling demands high-aspect-ratio etch systems with atomic layer precision. Leuven facilities are transitioning from planar to vertical cell architectures.
- Fabless Companies:Design houses without fabrication assets rely on foundry partners for process development access. Polish and Romanian design centers are influencing etch specification requirements through foundry partnerships.
Integrated Device Manufacturers retain substantial installed base; Foundries are gaining share fastest as EU Chips Act capital deploys.
Application:
Application segmentation maps etch demand to Europe's strategic technology priorities beyond commodity logic and memory.
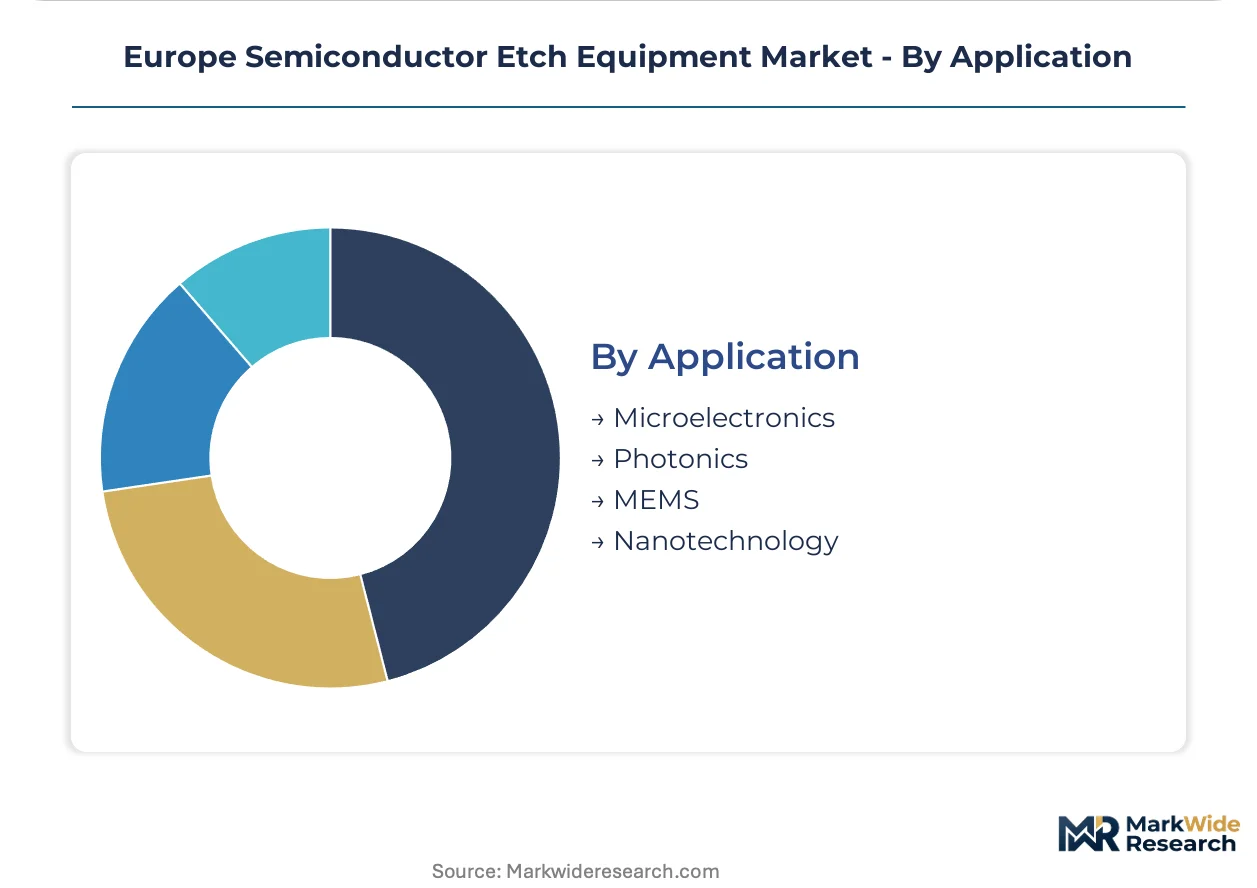
- Microelectronics:Conventional integrated circuit manufacturing encompasses logic, memory, and analog device fabrication. German and Dutch production facilities concentrate the bulk of European microelectronics etch demand.
- MEMS:Microelectromechanical systems require specialized release etch and deep silicon etch processes. French and Italian sensor manufacturers are expanding capacitive and piezoelectric device capacity.
- Photonics:Silicon photonics integration demands precise sidewall control for optical waveguide formation. Netherlands research institutes are scaling photonics pilot lines with dedicated etch modules.
- Nanotechnology:Research applications span quantum devices, 2D materials, and novel memory concepts. Swiss and Belgian university cleanrooms maintain specialized etch tool installations for exploratory work.
Microelectronics commands dominant equipment allocation; MEMS is expanding most quickly as automotive sensor demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in semiconductor equipment logistics, connecting Bavarian fabrication clusters to North Sea ports and Black Sea manufacturing zones.
Germany
Dresden's Silicon Saxony cluster anchors German etch equipment demand as Infineon and Bosch expand 300mm wafer capacity for automotive power semiconductors. The F-Gas Regulation phases down fluorinated etch chemistries, forcing chemistry reformulation across operating fabs. Bavaria's Greater Munich area concentrates equipment vendor R&D facilities serving Austrian and Czech packaging corridors.
Netherlands
Eindhoven's Brainport region drives plasma etch procurement for EUV lithography integration at ASML's supplier ecosystem. The Dutch National Growth Fund channels public capital into domestic semiconductor equipment manufacturing. Randstad logistics hubs manage inbound tool shipments for Leuven-bound foundry projects.
France
Grenoble's Minatec campus anchors CEA-Leti research driving atomic layer etch process development for 2nm-class transistors. The France 2030 investment plan targets sovereign semiconductor manufacturing capacity near Paris-Saclay. Auvergne-Rhône-Alpes automotive suppliers are procuring silicon carbide etch systems for EV inverter production.
Belgium
Leuven's IMEC research consortium sets etch equipment roadmaps for European foundry partners scaling 3nm logic processes. Flanders Innovation & Entrepreneurship provides capital grants for cleanroom infrastructure expansion. Antwerp's port infrastructure handles wet chemistry imports subject to REACH compliance verification.
Poland
Wrocław's emerging packaging cluster creates demand for dielectric etch systems in advanced interposer manufacturing. EU cohesion funds support semiconductor supply chain diversification into Central Europe. Lower Silesia's technical universities feed plasma process engineering talent to Dresden and Leuven facilities.
Europe Semiconductor Etch Equipment Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and service contracting dimensions. The vendor base concentrates around three tiers: integrated platform suppliers commanding foundry accounts, regional specialists serving IDM maintenance programs, and research-oriented players anchoring university-industry partnerships. Dominant competitive moves include long-term service contract bundling and predictive analytics integration.
Within the integrated platform tier, Applied Materials, Inc and Lam Research Corporation exemplify scale-driven equipment suppliers. Tokyo Electron Ltd occupies a position bridging wet and dry etch technology domains. These three anchors demonstrate how geographic diversification across US, Japanese, and European R&D footprints shapes competitive positioning in EU-funded fabrication projects.
| Leading Market Players |
|---|
| Applied Materials, Inc |
| Lam Research Corporation |
| Hitachi High-Tech Europe GmbH |
| SPTS Technologies Ltd. |
| ASM International |
| Tokyo Electron Ltd. |
| RENA Technologies GmbH |
| Oxford Instruments |
| EV Group |
| Others |
Supply & Pricing Matrix
CE marking and MDR-derived safety standards gate both supplier qualification and price differentiation simultaneously, compressing margins for non-integrated vendors while rewarding OEMs with captive certification capabilities across German and Dutch foundry accounts.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy tiers based on chamber refurbishment bundling and predictive analytics subscription depth. Price differentiation rests on CE certification tier and after-sales service integration, with foundries commanding steepest discounts through multi-year uptime guarantee contracts. Cost compression in the standard tier is intensifying as Polish and Czech packaging clusters consolidate procurement. Memory chip manufacturers exhibit highest price sensitivity due to high-volume wet bench configurations, while EU Chips Act-funded logic foundries prioritize performance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Asian component hubs through Rotterdam and Hamburg ports constrain margin recovery for equipment vendors serving Leuven and Dresden expansion timelines. Manufacturing concentration in Japan, the United States, and South Korea feeds critical plasma source assemblies and vacuum pump subsystems to European integration facilities. Single-source vulnerability sits with fluorinated gas supply concentration under F-Gas Regulation phase-down schedules. Distribution runs through Randstad logistics hubs for Dutch-German corridor foundries, with Antwerp handling REACH-compliant wet chemistry verification for Belgian memory facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's semiconductor etch equipment market tracks a cyclical recovery pattern as EU Chips Act capital deployment accelerates domestic fabrication capacity construction across the projection horizon.
For Market Incumbents: Fortify service contracting capabilities through predictive analytics platform integration and long-term uptime guarantee structures. Counter margin compression from REACH compliance-driven chemistry reformulation by anchoring refurbishment revenue streams at Dresden and Leuven operating fabs. Prioritize vertical integration into fluorinated gas alternative qualification programs to offset F-Gas Regulation supply constraints. For New Entrants and Emerging Players: Anchor in Poland and Czech Republic packaging corridors where dielectric etch demand outpaces established vendor coverage. Target advanced interposer manufacturing segments with specialized reactive ion etch configurations absent from incumbent portfolios. Pursue university-industry partnership channels through IMEC and CEA-Leti research consortia to bypass capital-intensive foundry qualification barriers. For Investors and Strategic Acquirers: EU AI Act chip traceability mandates reshape the acquisition landscape toward equipment vendors with embedded data-logging architectures. Favor targets with demonstrated REACH compliance transition experience across installed wet etch bases. Monitor ECHA PFAS restriction proposal advancement as the critical signal for chemistry reformulation cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Etch Platform Development | ALE module integration at Dresden foundries enables gate-all-around transistor volume production. |
| REACH-Compliant Chemistry Reformulation | ECHA PFAS restrictions force wet etch chemistry transitions across Leuven memory installations. |
| Long-Term Service Contract Bundling | Predictive analytics subscriptions displace transactional maintenance at Netherlands pure-play operators. |
| Packaging Corridor Geographic Expansion | Wrocław interposer manufacturing creates dielectric etch demand outside incumbent strongholds. |
| EU AI Act Data-Logging Integration | Chip traceability specifications differentiate qualified suppliers in next procurement cycles. |
Research Methodology
The analysis maps dry etch, plasma etch, wet etch, and reactive ion etch sub-sectors, each validated through equipment procurement directors, fab operations managers, plasma process engineers, and aftermarket service heads. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, SEMI equipment market databases, EU Chips Act funding disbursement records, and ECHA regulatory proposal trackers. Bottom-up equipment shipment tallies triangulated against top-down foundry capex aggregation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled technology type, end-user category, application segment, and regional production hub dimensions. CAGRs derived from equipment shipment run-rates correlated with fab construction timelines and EU funding tranche schedules. Industry-specific inputs incorporated EUV lithography node migration patterns and F-Gas Regulation phase-down compliance costs.
Material uncertainties — abrupt EU funding suspension, ECHA chemical restriction acceleration, or plasma physicist talent migration disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU Chips Act capital continuity and REACH compliance timeline adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Tape on Reel Feeder Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Solar Module Production Equipment Market