
 ARM-Based Servers Market | 2026-2036
ARM-Based Servers Market Size, Share, and Industry Trends Forecast 2026-2036
ARM-Based Servers Market Analysis
Hyperscale buyer concentration is decoupling from traditional x86 procurement patterns as cloud service providers diversify silicon sourcing. Ampere Computing leverages purpose-built core density to anchor high-performance computing contracts. Fujitsu Limited sustains supercomputing credibility through the A64FX architecture. Marvell Technology competes in 5G infrastructure with embedded ARM server subsystems.
ARM-based servers employ reduced instruction set computing architectures with 64-bit processing cores, system-on-chip integration, and power envelopes typically below 250 watts per socket, purpose-built for parallelizable workloads and thermal-constrained environments. Rack servers occupy the dominant hardware form factor as hyperscalers standardize 48V power architectures and liquid cooling backplanes. Containerization technology is reshaping software deployment patterns by matching lightweight virtualization to ARM's thread-per-watt efficiency profile.
Europe's Ecodesign for Servers framework and F-Gas Regulation constrain thermal design power thresholds and refrigerant choices across data center deployments. China's GB standards and MIIT dual carbon goals mandate domestic silicon preference and energy efficiency benchmarks for state-backed computing facilities. Stakeholders must monitor sovereign compute mandates and cooling technology roadmaps as procurement criteria fragment across regulatory jurisdictions.
Market Dynamics
Hyperscale cloud procurement patterns are decoupling from x86 legacy commitments as thermal density constraints and sovereign compute mandates force silicon diversification at scale.
Growth Catalysts
- AI inference workload expansion:Cloud service providers deploy ARM servers for parallelized neural network processing at lower thermal envelopes than general-purpose alternatives.
- Europe's F-Gas Regulation:Data center operators face refrigerant phase-down mandates that accelerate liquid cooling adoption compatible with ARM's power-efficient socket designs.
- China's MIIT dual carbon goals:State-backed computing facilities must meet energy efficiency benchmarks that favor domestic ARM-based silicon over imported alternatives.
Market Restraints
- Software ecosystem fragmentation:Legacy enterprise applications require x86 emulation layers or native recompilation, extending deployment timelines for ARM migrations.
- Memory subsystem supply concentration:High-bandwidth memory controllers for server-grade SoCs depend on a concentrated foundry base in East Asian manufacturing clusters.
- Instruction set architecture licensing complexity:ARM's royalty structures and architectural variant restrictions create cost unpredictability for custom chip designers.
Strategic Opportunities
- Edge computing infrastructure buildouts:Telecommunications carriers in Germany and Japan deploy ARM-based micro data centers for 5G network slicing and low-latency services.
- Sovereign cloud mandates:France's ANSM and Germany's KBA procurement guidelines increasingly specify domestic or European-sourced silicon for regulated workloads.
- Container-native workload portability:Kubernetes orchestration layers abstract hardware dependencies, enabling ARM server penetration into DevOps pipelines previously locked to x86.
Industry Challenges
- Firmware and bootloader standardization gaps:Server vendors maintain proprietary system initialization stacks that complicate multi-sourced ARM deployments.
- Compiler toolchain maturity:Optimized code generation for ARM's Neoverse cores requires specialized expertise scarce in enterprise IT organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ARM-Based Servers Market |
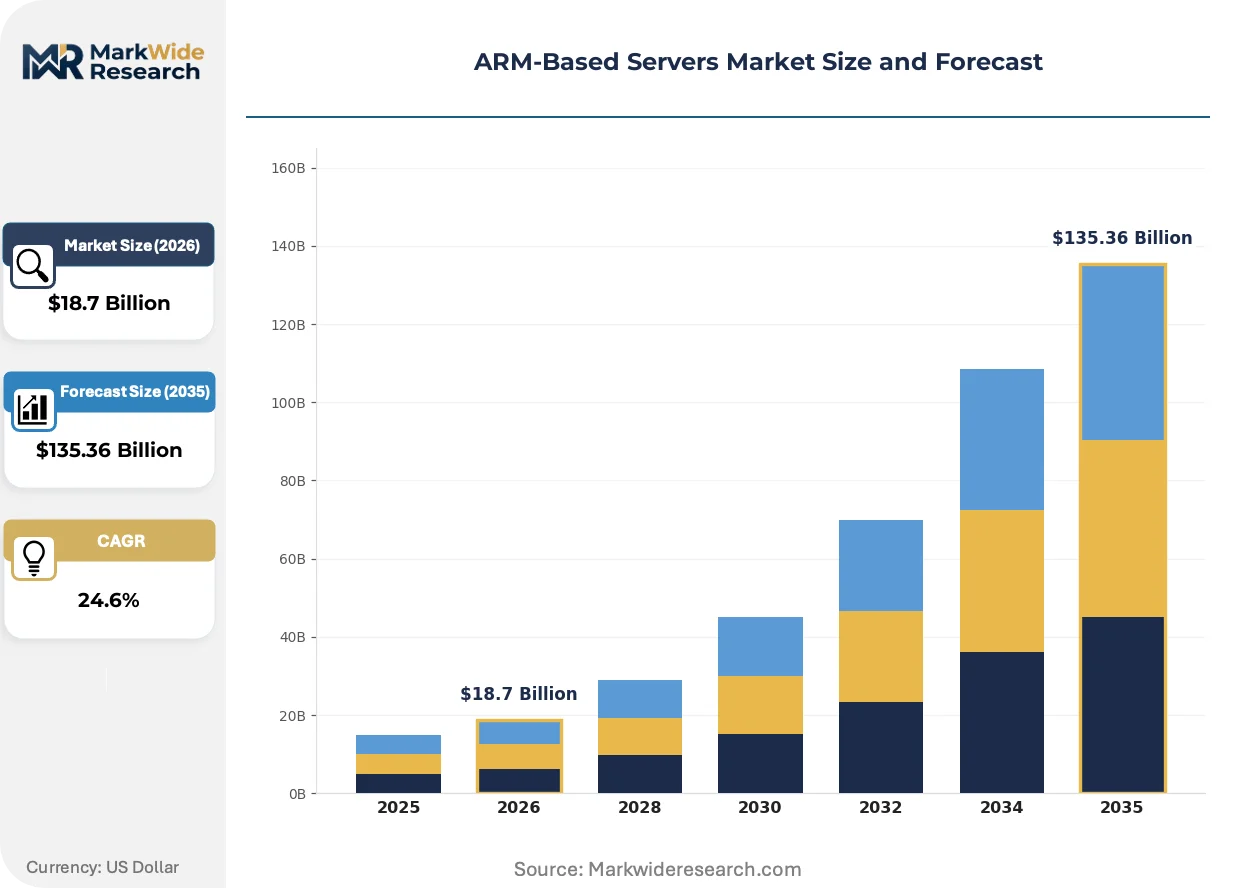
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Board Computers, Microservers, Blade Servers, Rack Servers End User: Cloud Service Providers, Telecom, Enterprises, Research Institutions Deployment: On-Premises, Hybrid Cloud, Private Cloud, Public Cloud Technology: Virtualization, Containerization, Edge Computing, Machine Learning |
| Companies Covered | Huawei Technologies, ARM Limited, Ampere Computing, Broadcom Inc., Qualcomm Technologies, Fujitsu Limited, Marvell Technology, NXP Semiconductors, AWS Graviton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ARM-Based Servers Market Emerging Trajectories
Chiplet-based server processor design is fragmenting monolithic silicon economics. Purpose-built accelerators are displacing general-purpose cores for targeted workloads. Software-defined power management is compressing operational expenditure structures.
Chiplet interconnect technology is modularizing ARM server processor architectures into discrete compute, memory, and I/O tiles. Hyperscalers including Microsoft and Amazon Web Services adopt chiplet-based custom silicon for workload-specific optimization. This disaggregation is modularizing supply chain relationships and enabling faster iteration cycles than monolithic designs permit.
The EU's F-Gas Regulation mandates refrigerant phase-downs that constrain traditional vapor-compression cooling in data centers. Operators respond with liquid cooling backplanes and two-phase immersion systems optimized for ARM's thermal profiles. Northern European facilities in Sweden and Finland lead deployment, leveraging ambient cooling advantages with high-density ARM racks.
Cloud buyers increasingly specify outcome-based infrastructure contracts tied to workload performance per watt rather than hardware ownership. This restructures vendor relationships toward operational expenditure models. China's state-owned cloud operators and India's Reliance Jio exemplify this shift, procuring ARM servers through managed service agreements with domestic system integrators.
ARM-Based Servers Market Segmentation
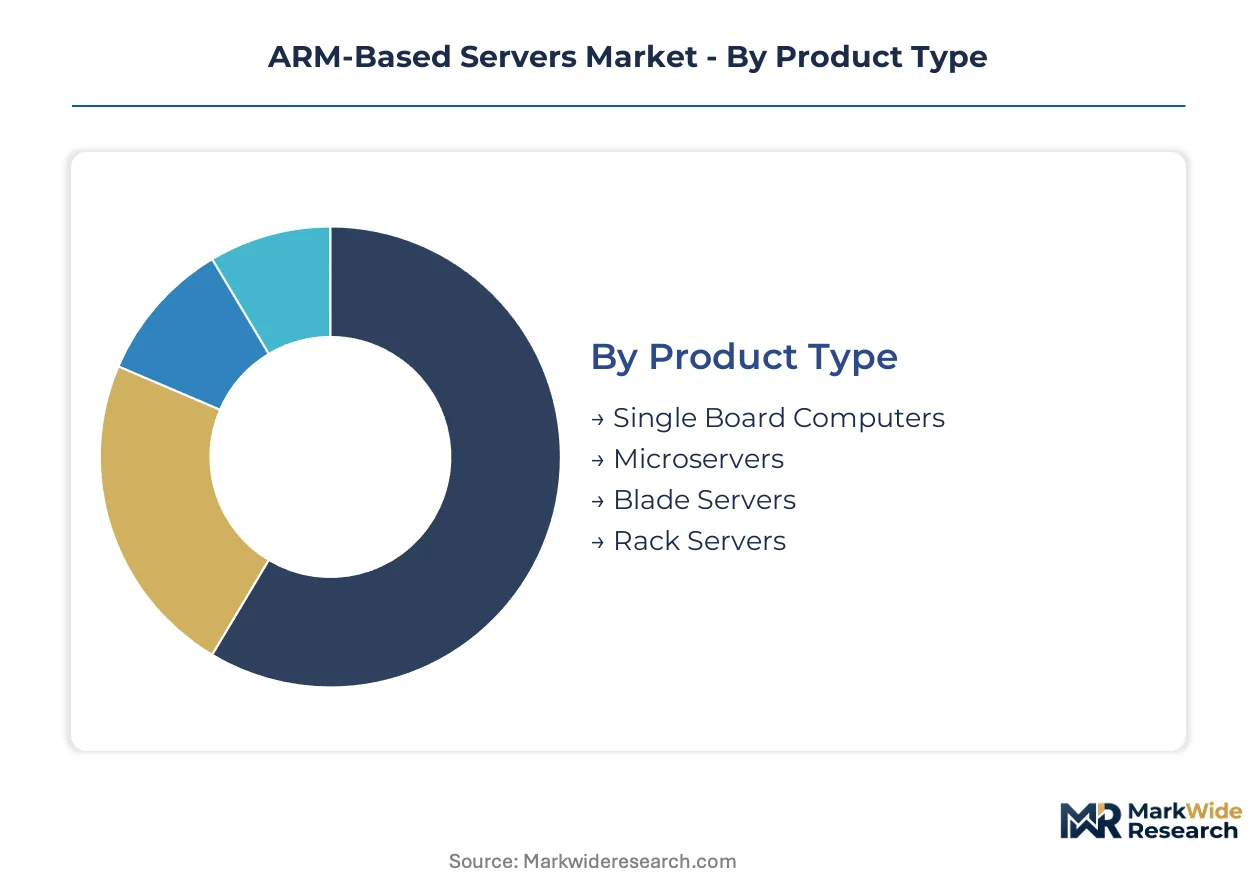
ARM server procurement patterns diverge sharply across deployment scales and workload types. Hyperscalers prioritize rack-density and thermal efficiency, while edge operators optimize for form-factor constraints and power envelopes.
Product Type:
Volume deployments concentrate in standardized rack formats, while premium configurations target specialized compute densities.
- Rack Servers:Standardized 19-inch enclosures housing multi-socket ARM SoCs with 48V power distribution and liquid cooling backplanes. Hyperscale facilities in Sweden and Finland deploy these for AI inference clusters where thermal density exceeds 30kW per rack.
- Blade Servers:Modular chassis architectures sharing redundant power and cooling infrastructure across multiple compute nodes. Telecom operators in Germany specify blade formats for 5G core network functions requiring hot-swappable serviceability.
- Microservers:Compact single-socket designs optimized for web serving and lightweight container workloads.
- Single Board Computers:Integrated compute modules for embedded edge applications with constrained physical footprints.
Mature deployment sits with rack servers. Newer deployment is concentrated in microservers.
End User:
Customer concentration follows sovereign cloud mandates and carrier infrastructure cycles.
- Cloud Service Providers:Hyperscale buyers including Microsoft Azure and Amazon Web Services deploy custom ARM silicon at fleet scale. These operators negotiate directly with chip designers, bypassing traditional server OEM channels to optimize workload-specific performance per watt.
- Telecom:Carriers in Japan and Germany build ARM-based edge infrastructure for network slicing and ultra-reliable low-latency services. NTT Docomo and Deutsche Telekom specify ARM servers for 5G standalone core deployments.
- Enterprises:Financial services and manufacturing firms adopt ARM for secondary workloads and development environments.
- Research Institutions:National laboratories deploy ARM clusters for climate modeling and genomics pipelines.
Research institutions anchor mature HPC deployments. Cloud service providers are expanding fastest.
Deployment:
Infrastructure ownership models reshape silicon procurement criteria and cooling investment profiles.
- Public Cloud:Multi-tenant infrastructure where ARM servers serve ephemeral compute instances. Providers amortize hardware costs across millions of customers, justifying custom silicon development for marginal efficiency gains.
- Hybrid Cloud:Workload portability between on-premises ARM clusters and public cloud burst capacity. Enterprises in regulated sectors use this model to maintain data residency while accessing elastic scale.
- Private Cloud:Single-tenant ARM deployments for sovereign data requirements.
- On-Premises:Traditional enterprise data center ownership with full hardware control.
On-premises retains legacy footprint. Public cloud is climbing the fastest.
Technology:
Software abstraction layers determine hardware selection flexibility and migration friction.
- Containerization:Docker and Kubernetes orchestration enables workload portability across ARM and x86 substrates. DevOps pipelines at cloud-native firms standardize on ARM for microservices where per-instance cost optimization outweighs legacy compatibility.
- Machine Learning:ARM's NEON and SVE instruction extensions accelerate inference without discrete accelerators. Edge deployments in computer vision and natural language processing exploit this integration for latency-sensitive applications.
- Virtualization:Hypervisor abstraction for multi-tenant resource isolation.
- Edge Computing:Distributed processing architectures minimizing data transmission.
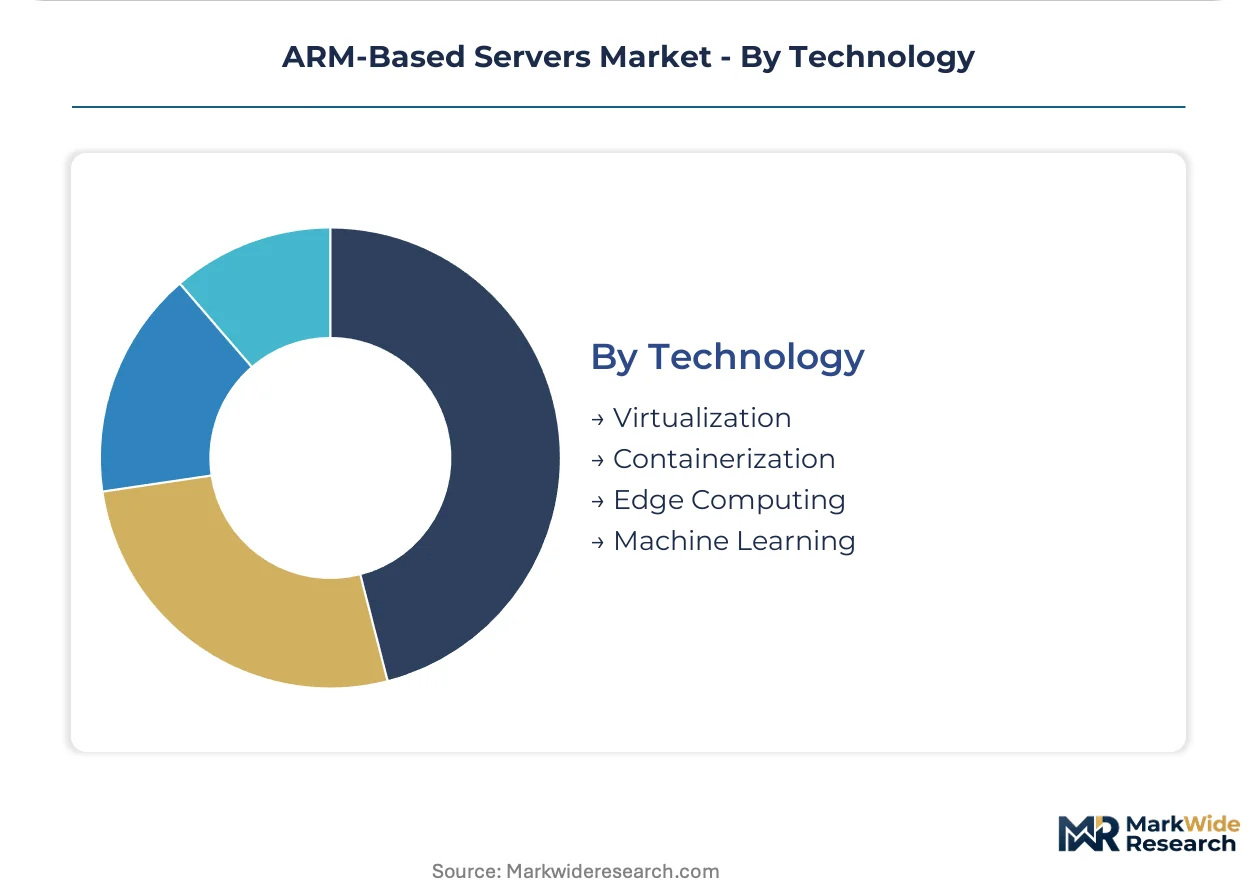
Virtualization represents established enterprise practice. Containerization is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of ARM server procurement as domestic hyperscalers accelerate sovereign silicon deployments. State-backed computing initiatives in Beijing and Shanghai are reshaping regional demand concentration.
China
MIIT dual carbon goals mandate energy efficiency benchmarks that favor domestic ARM-based silicon over imported alternatives. GB standards enforce power usage effectiveness thresholds for state-backed data centers. Yangtze River Delta facilities in Shanghai and Hangzhou deploy high-density ARM racks for AI inference clusters exceeding 30kW per cabinet.
United States
Hyperscale cloud operators negotiate directly with chip designers, bypassing traditional server OEM channels to optimize workload-specific performance per watt. The country's national technology regulator maintains export control frameworks affecting semiconductor supply chains. Northern Virginia data center clusters and Oregon hyperscale campuses anchor the largest ARM server deployments outside China.
Germany
Telecom carriers specify ARM servers for 5G standalone core deployments requiring hot-swappable serviceability. KBA procurement guidelines increasingly specify domestic or European-sourced silicon for regulated workloads. Frankfurt and Berlin metropolitan data centers lead liquid cooling adoption compatible with ARM thermal profiles under F-Gas Regulation constraints.
Japan
NTT Docomo builds ARM-based edge infrastructure for network slicing and ultra-reliable low-latency services. METI efficiency standards accelerate displacement of legacy x86 installations in telecommunications facilities. Tokyo and Osaka metropolitan clusters concentrate domestic ARM server manufacturing partnerships with Fujitsu Limited.
Sweden
Northern European facilities leverage ambient cooling advantages with high-density ARM racks exceeding conventional thermal densities. The country's environmental protection framework enforces refrigerant phase-downs that accelerate liquid cooling adoption. Luleå and Stockholm data center campuses host hyperscale ARM deployments serving pan-European cloud workloads.
ARM-Based Servers Market Vendor Landscape
Chinese producers anchor one tier; US specialists hold custom silicon design relationships with hyperscale cloud operators. The vendor base separates into three distinct strata: fabless chip designers licensing ARM architecture, integrated device manufacturers with captive foundry capacity, and cloud-native silicon operators developing proprietary server processors. Strategic archetypes include workload-optimized core specialists, telecom-embedded subsystem providers, and sovereign compute enablers. Competitive moves concentrate on architectural licensing negotiations and liquid cooling backplane partnerships.
Within the custom silicon tier, Ampere Computing and Marvell Technology occupy positions as fabless designers serving hyperscale procurement channels. Fujitsu Limited exemplifies the integrated manufacturer archetype with supercomputing credibility through A64FX architecture deployment. These three companies represent distinct geographic concentrations: US-based fabless specialists, Japanese integrated manufacturers, and emerging Chinese sovereign compute providers including Huawei Technologies.
| Leading Market Players |
|---|
| Huawei Technologies |
| ARM Limited |
| Ampere Computing |
| Broadcom Inc. |
| Qualcomm Technologies |
| Fujitsu Limited |
| Marvell Technology |
| NXP Semiconductors |
| AWS Graviton |
| Others |
Supply Flow & Price Mechanics
Performance-per-watt divergence between custom silicon and merchant ARM cores bifurcates procurement economics across hyperscale and enterprise tiers. Hyperscalers negotiate direct architectural licenses that compress per-socket costs below traditional OEM channels, while enterprise buyers absorb premium markups for validated system integrations and firmware support.
Pricing Analysis
Volume procurement by cloud service providers extracts margin through direct chip designer relationships, while enterprise segments face higher per-unit costs for smaller lot sizes and certification overhead. Price differentiation hinges on core density configurations and liquid cooling compatibility grades under Europe's F-Gas Regulation. Cost compression in standard rack formats intensifies as domestic Chinese silicon expands sovereign supply. Cloud service providers exhibit lowest price sensitivity; regulated enterprises in financial services show highest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced foundry capacity serving ARM server SoC production. High-bandwidth memory controllers and substrate materials draw from concentrated East Asian manufacturing clusters. Tariff exposure on semiconductor fabrication equipment threatens expansion timelines for non-captive designers. Distribution runs through direct hyperscale procurement channels and domestic system integrators in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ARM server market is becoming a vertical-integration race as hyperscalers pursue captive silicon design to escape merchant chip pricing and secure supply allocation priority.
For Market Incumbents: Deploy architectural licensing leverage to anchor long-term hyperscale contracts before custom silicon proliferation erodes merchant core demand. Deepen foundry partnerships in Taiwan and South Korea to secure capacity reservation against sovereign compute buildouts in China. Accelerate liquid cooling certification programs to capture F-Gas Regulation-driven retrofit cycles in European data centers. For New Entrants and Emerging Players: Launch via edge computing infrastructure partnerships with telecommunications carriers in Germany and Japan, where 5G network slicing requirements outstrip incumbent supply capacity. Target sovereign cloud mandates in France and Germany specifying domestic or European-sourced silicon for regulated workloads. Pursue container-native DevOps channels where Kubernetes abstraction minimizes x86 migration friction. For Investors and Strategic Acquirers: Re-rating potential sits with fabless designers possessing Neoverse architectural licenses given hyperscale procurement decoupling from x86 legacy commitments. Long-term viability favors specialists with established liquid cooling integration partnerships and MIIT-compliant product roadmaps for Chinese state-backed facilities. Watch hyperscaler capex disclosure shifts toward custom silicon development as inflection indicator for merchant core demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | AWS Graviton and Microsoft Azure bypass OEM channels to optimize workload-specific performance per watt. |
| Liquid Cooling Backplane Partnership | Swedish and Finnish facilities deploy high-density ARM racks exceeding 30kW per cabinet under F-Gas constraints. |
| Sovereign Compute Certification | China's MIIT dual carbon goals mandate domestic ARM silicon preference for state-backed Yangtze River Delta facilities. |
| Chiplet Architecture Adoption | Modular compute-memory-I/O tiles enable faster iteration cycles than monolithic designs for hyperscaler procurement. |
| Edge Infrastructure Buildout | NTT Docomo and Deutsche Telekom specify ARM servers for 5G standalone core network functions. |
Methodological Framework
Document review covered hyperscaler capex disclosures, MIIT policy circulars, and F-Gas Regulation implementation guidance, complemented by interviews with cloud infrastructure procurement leads, semiconductor foundry planning officers, and data center cooling system engineers. Secondary validation drew from SEC 10-K filings, EIA power consumption data, and customs records for server component trade flows. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment projections.
Segment-level outputs across product type, end user, deployment model, and technology abstraction layers were generated through iterative calibration against sovereign compute procurement volumes and thermal design power trajectories. CAGRs were derived from slope-consistent growth paths anchored to verified hyperscale deployment announcements and efficiency mandate compliance deadlines. Foundry capacity expansion schedules and refrigerant phase-down timelines served as industry-specific forecast inputs.
Geopolitical export control expansion, foundry yield volatility, and regulatory enforcement variance across EU member states are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about architectural license availability and liquid cooling adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Processor Chip Market