
 Image Signal Processor and Vision Processor Market | 2026-2036
Image Signal Processor and Vision Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Image Signal Processor and Vision Processor Market Outlook
Silicon carbide substrate integration is expanding thermal headroom in automotive vision processors, enabling higher-resolution pipelines without active cooling penalties. STMicroelectronics leverages captive SiC foundry capacity to anchor supply security for Tier-1 automotive programs. Texas Instruments Incorporated sustains broad catalog coverage across industrial and automotive vision segments with programmable DSP architectures. Qualcomm Technologies dominates premium smartphone ISP sockets through computational photography co-processing with AI accelerators.
An image signal processor is a dedicated digital circuit that performs demosaicing, noise reduction, tone mapping, and color space conversion on raw sensor data, typically handling throughput rates exceeding gigapixels per second for real-time video pipelines; vision processors extend this functionality with neural network inference engines for object detection, semantic segmentation, and scene understanding in embedded systems. SoC-based processors capture the largest revenue pool by integrating CPU, GPU, ISP, and NPU subsystems onto monolithic die, while FPGA-based processors occupy high-mix low-volume defense and medical imaging applications where reconfigurability commands premium pricing. AI-based processing represents the fastest-expanding technology segment as transformer-based vision models displace convolutional networks in accuracy-critical deployments.
FDA clearance pathways for AI-enabled diagnostic imaging devices shape product development timelines and clinical validation budgets for vision processor vendors targeting healthcare. The EU AI Act imposes conformity assessment obligations on high-risk computer vision systems, while NHTSA FMVSS testing protocols govern automotive camera performance thresholds for pedestrian detection and lane-keeping assist. Stakeholders must monitor evolving multi-jurisdictional certification requirements that fragment go-to-market strategies across consumer, automotive, and medical end uses.
Market Dynamics
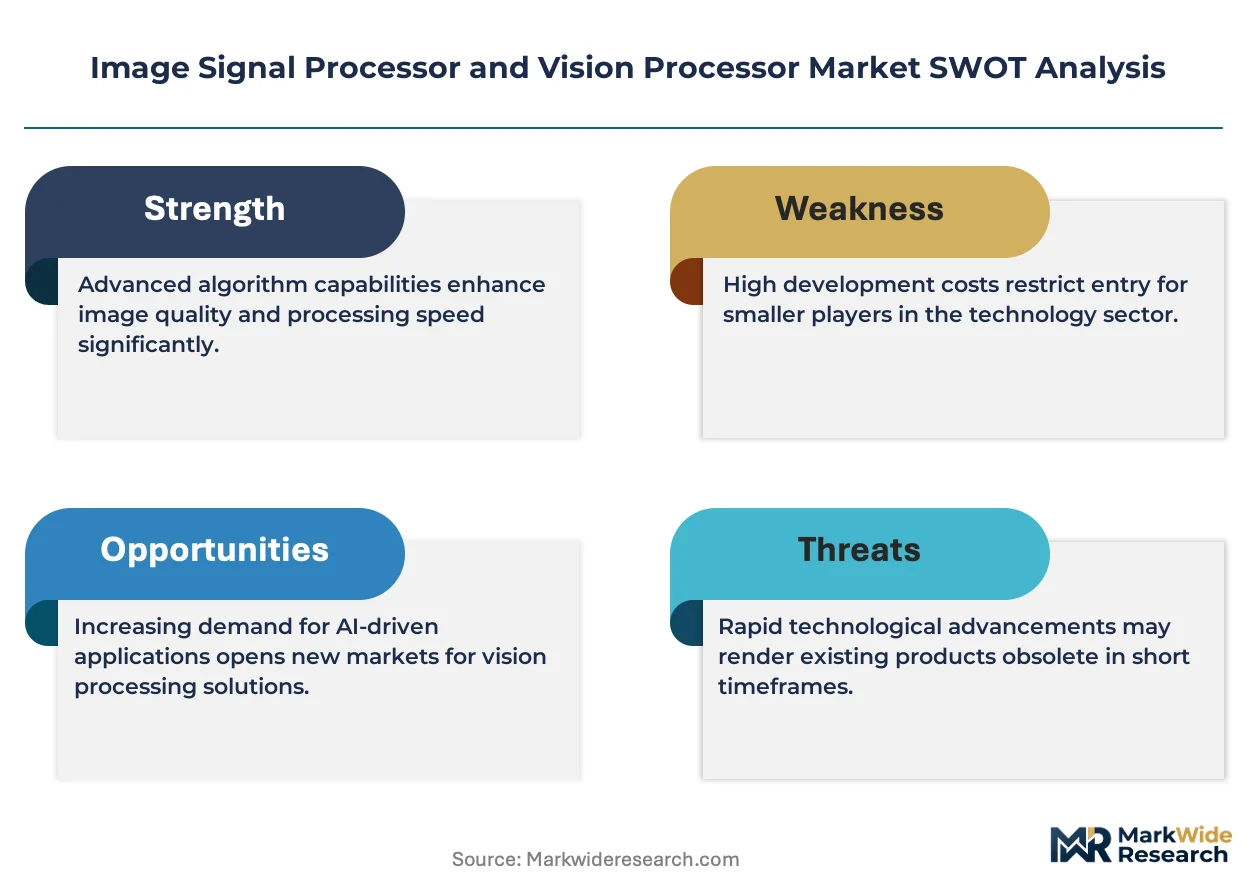
Transformer-based vision models are compressing algorithm development cycles while fragmenting hardware requirements across edge and cloud inference tiers. Automotive OEMs now specify neural network performance per watt as a primary procurement metric, forcing silicon vendors to rearchitect memory hierarchies and data movement paths.
Growth Catalysts
- EU AI Act compliance mandates:High-risk computer vision deployments in autonomous vehicles and medical diagnostics face mandatory conformity assessments, creating captive demand for certified processor platforms with documented algorithmic transparency.
- Silicon carbide thermal headroom:SiC substrate integration enables passive-cooled 8K video pipelines in engine-bay automotive cameras, eliminating fan failure modes that degrade ADAS reliability.
- China EV production scale:Domestic electric vehicle manufacturers consume vision SoCs at volumes that justify captive foundry investments, compressing import dependency for advanced driver-assistance systems.
Market Restraints
- Advanced node wafer scarcity:Sub-7nm fabrication capacity concentrates at TSMC and Samsung Foundry, creating allocation bottlenecks for NPU-integrated vision processors targeting premium automotive sockets.
- EU AI Act documentation burden:Conformity assessment obligations for high-risk computer vision systems extend product development timelines and inflate clinical validation budgets for healthcare-targeting vendors.
- FPGA substitution in defense:Reconfigurable logic platforms retain pricing power in low-volume military imaging applications where post-deployment algorithm updates outweigh unit cost premiums.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for semiconductor assembly and testing attract vision processor packaging investments serving domestic smartphone and automotive electronics manufacturing.
- Computational photography convergence:Co-processing architectures that fuse ISP pipelines with transformer-based denoising models open premium smartphone sockets previously locked by vertically integrated competitors.
- NHTSA FMVSS testing protocol expansion:Pending pedestrian detection performance thresholds for low-light conditions mandate sensor fusion upgrades, creating retrofit demand for multi-camera vision processors in existing vehicle platforms.
Industry Challenges
- Neural architecture search expertise scarcity:Automated optimization of vision transformer implementations for heterogeneous SoC fabrics requires rare cross-domain fluency in machine learning and silicon physical design.
- FDA 510(k) pathway compression:AI-enabled diagnostic imaging devices face evolving clinical validation requirements that fragment product roadmaps across oncology, ophthalmology, and pathology end uses.
- Legacy automotive camera interface migration:MIPI CSI-2 to Automotive SerDes protocol transitions force simultaneous software stack revalidation and hardware redesign for Tier-1 vision module suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Signal Processor and Vision Processor Market |
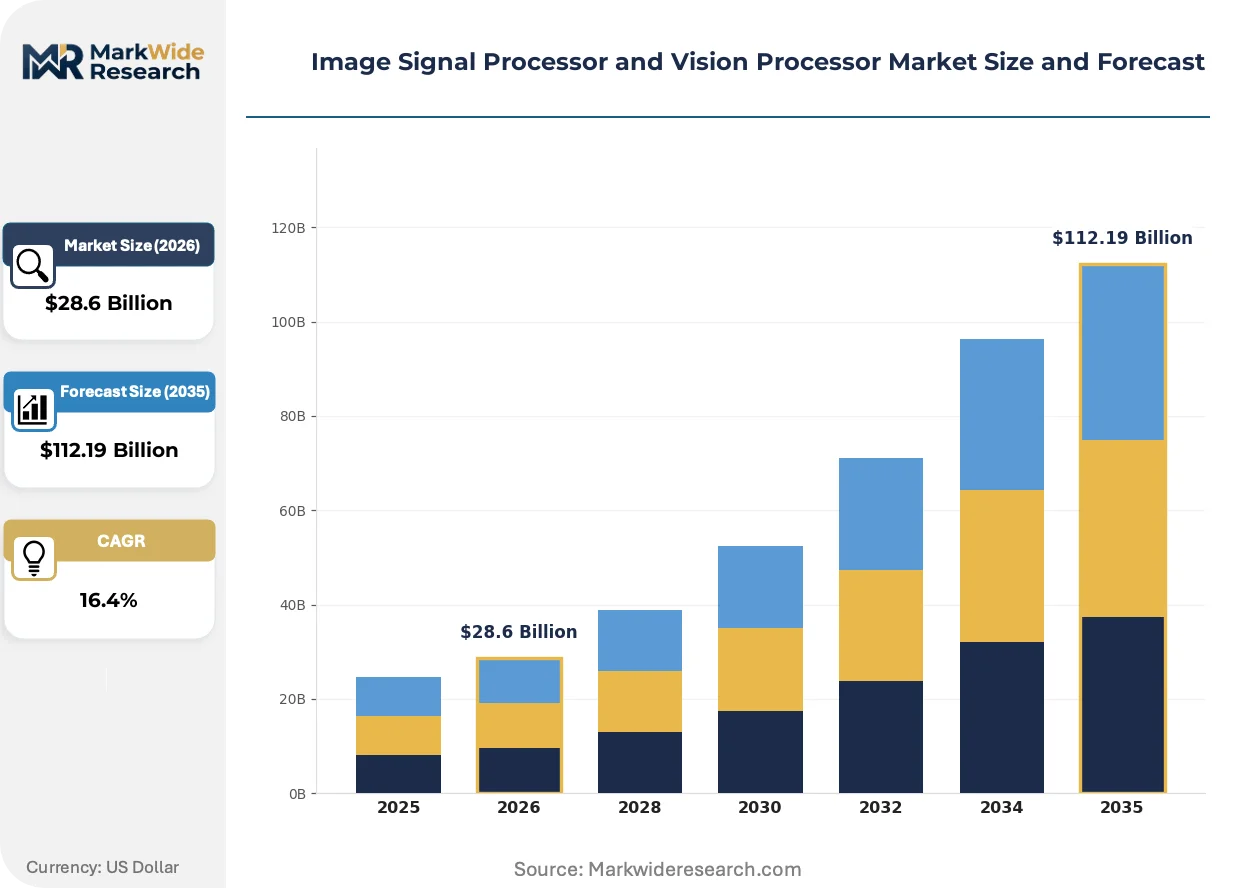
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dedicated Processors, FPGA-Based Processors, SoC-Based Processors, DSP-Based Processors Application: Smartphones, Surveillance Cameras, Automotive Cameras, Drones End User: Consumers, Manufacturers, Tier-1 Suppliers, Research Institutions Technology: AI-Based Processing, Real-Time Processing, Multi-Resolution Processing, High Dynamic Range Imaging |
| Companies Covered | STMicroelectronics, Texas Instruments Incorporated, Samsung Electronics, Qualcomm Technologies, Sony Corporation, ON Semiconductor, NXP Semiconductors, Analog Devices, Fujitsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Signal Processor and Vision Processor Market Strategic Shifts
Neural network inference at the sensor edge is collapsing traditional ISP-NPU boundaries into unified compute fabrics. This convergence demands new programming models and memory architectures that treat demosaicing and object detection as interleaved pipeline stages rather than sequential processing blocks.
Transformer-based vision encoders are rewriting accuracy-efficiency tradeoffs in embedded perception systems. Automotive Tier-1s now specify Swin Transformer and DETR variants for pedestrian detection subsystems, compressing convolutional network deployment timelines from 18-month validation cycles to 6-month software updates. This acceleration is fragmenting hardware roadmaps between fixed-function accelerators and programmable DSP arrays.
The EU AI Act risk classification framework imposes documentation and audit trail mandates on high-risk computer vision deployments. Medical imaging device manufacturers face expanded clinical evidence requirements for diagnostic AI, while automotive suppliers must maintain algorithm version control across million-unit fleets. Germany's KBA and France's ANSM coordinate enforcement approaches that fragment compliance strategies across member states.
Automotive OEM procurement teams now specify outcome-based performance guarantees for vision processor subsystems. Tier-1 suppliers assume liability for combined sensor-processor-algorithm accuracy metrics rather than component-level specifications, compressing margin structures and forcing vertical integration into lens and housing manufacturing. This shift concentrates contract awards at suppliers with captive optical and thermal mechanical capabilities.
Image Signal Processor and Vision Processor Market Segmentation
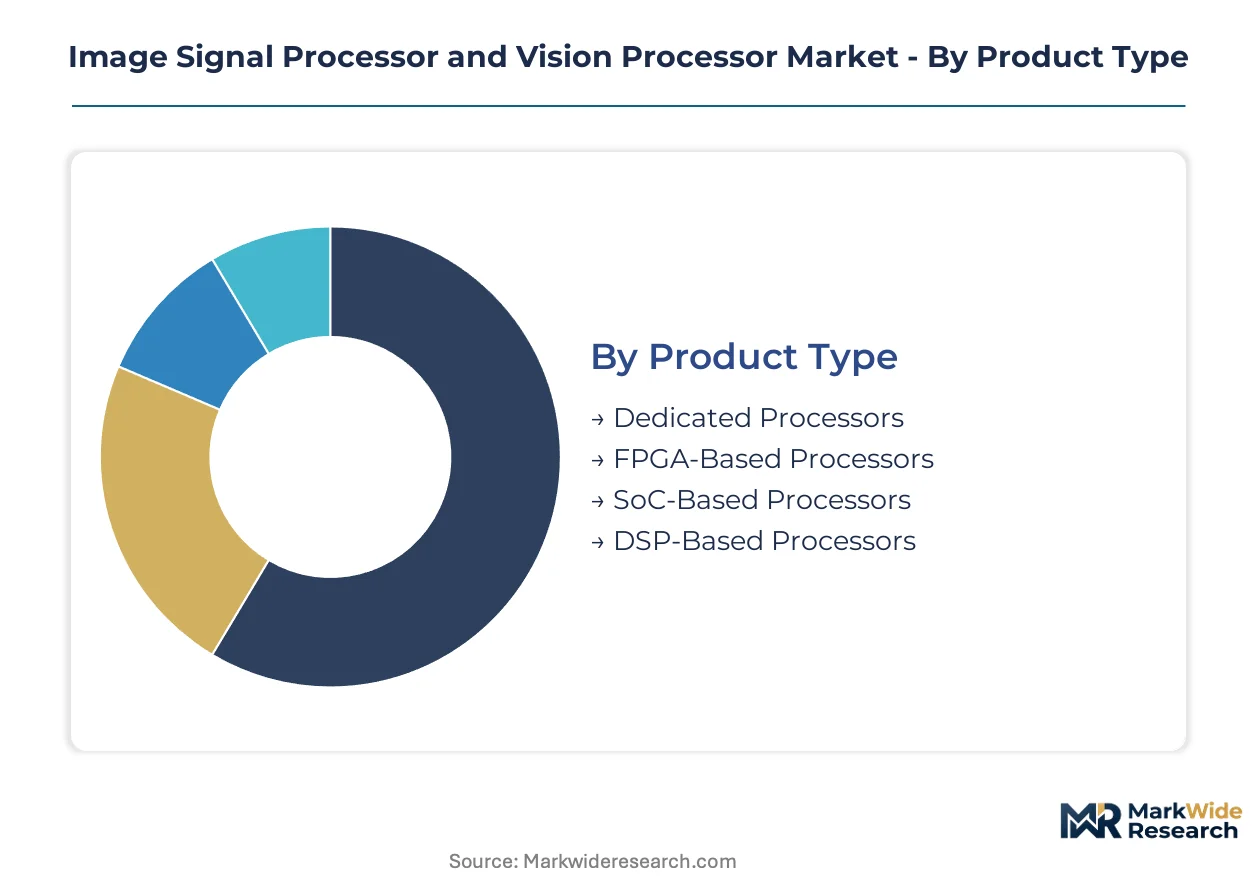
Vision processor procurement patterns diverge sharply across end-use contexts, with automotive OEMs demanding thermal-hardened SoC platforms while smartphone vendors prioritize die-size efficiency. Understanding these segment boundaries clarifies where silicon vendors must architect distinct memory hierarchies, power envelopes, and software ecosystems to capture design wins.
Product Type:
Buyers differentiate primarily by volume scale and customization needs, with mass-market applications demanding monolithic integration and defense-medical programs tolerating reconfigurable logic premiums.
- SoC-Based Processors:Monolithic integration of CPU, GPU, ISP, and NPU subsystems onto single die enables the lowest power-per-inference metrics for battery-constrained devices. Automotive ADAS programs in Germany and China specify these platforms for multi-camera fusion pipelines, though sub-7nm wafer allocation at TSMC and Samsung Foundry constrains supply security for premium sockets.
- Dedicated Processors:Discrete ISPs handle demosaicing, noise reduction, and tone mapping at throughput rates exceeding gigapixels per second without neural acceleration. Surveillance camera deployments across Indian smart city programs consume these devices where latency tolerance permits cloud-offloaded inference.
- FPGA-Based Processors:Reconfigurable logic platforms command pricing premiums in low-volume defense imaging applications where post-deployment algorithm updates outweigh unit costs.
- DSP-Based Processors:Programmable architectures sustain catalog coverage across industrial automation segments requiring flexible filter pipelines without full AI acceleration.
SoC-based processors lead volumes today; FPGA-based processors are gaining share fastest in military-medical niches.
Application:
Resolution requirements and environmental hardening separate these contexts, with engine-bay installations demanding passive thermal solutions absent in climate-controlled consumer electronics.
- Automotive Cameras:Vision processors here must survive 125°C ambient operation while delivering 8K video pipelines for pedestrian detection. Silicon carbide substrate integration at STMicroelectronics enables this thermal headroom without active cooling, though MIPI CSI-2 to Automotive SerDes protocol transitions force simultaneous software and hardware redesigns for Tier-1 suppliers.
- Smartphones:Computational photography co-processing with AI accelerators drives socket wins through transformer-based denoising models that displace traditional ISP pipelines. Qualcomm Technologies dominates this segment by fusing ISP and NPU into unified compute fabrics.
- Surveillance Cameras:Edge inference demands concentrate in Chinese safe-city deployments where domestic SoC design capabilities reduce import dependency.
- Drones:Swappable payload requirements favor modular processor architectures with standardized thermal interfaces across commercial and agricultural use cases.
Smartphone applications lead volumes today; automotive cameras are expanding most quickly as NHTSA FMVSS testing protocols mandate sensor fusion upgrades.
End User:
Procurement authority and technical specification control determine how processor requirements flow from final application to silicon vendor.
- Tier-1 Suppliers:These entities now assume liability for combined sensor-processor-algorithm accuracy metrics rather than component-level specifications, compressing margin structures and forcing backward integration into lens and housing manufacturing.
- Manufacturers:Consumer electronics OEMs specify die-size and power envelopes that prioritize battery life over absolute inference throughput.
- Research Institutions:Academic and national laboratory procurement favors programmable platforms supporting algorithm publication and reproducibility.
- Consumers:End-user purchasing of aftermarket dashcams and home security systems drives cost-optimized processor selection with minimal feature differentiation.
Manufacturers lead volumes today; Tier-1 suppliers are climbing the fastest as automotive OEMs outsource subsystem integration.
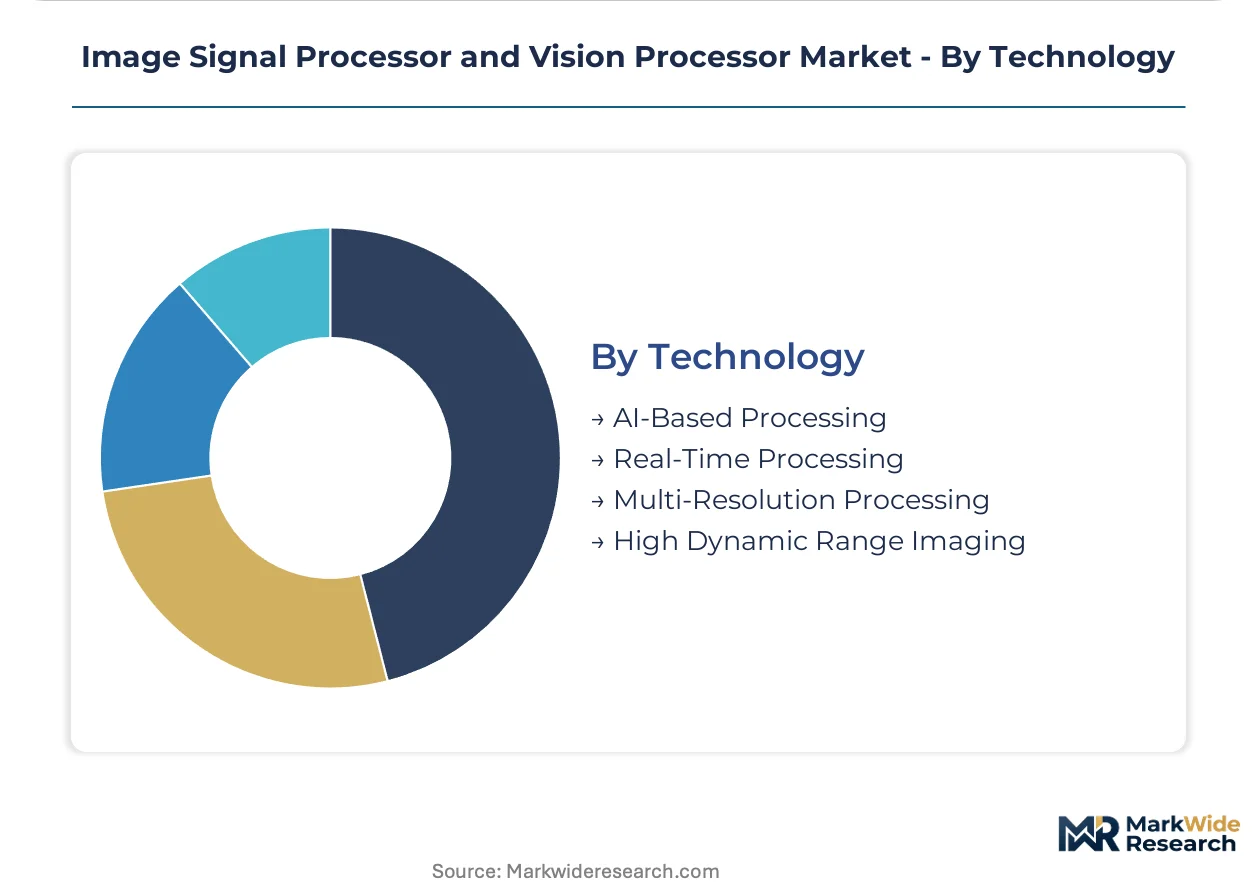
Technology:
Algorithm-architecture co-evolution separates legacy pipelines from transformer-based implementations, with accuracy-critical deployments demanding new programming models.
- AI-Based Processing:Neural network inference engines for object detection and semantic segmentation now displace fixed-function ISP blocks. Vision transformers compress validation cycles from 18 months to 6 months, though automated optimization for heterogeneous SoC fabrics requires scarce cross-domain expertise in machine learning and silicon physical design.
- Real-Time Processing:Deterministic latency guarantees for autonomous vehicle emergency braking systems mandate dedicated hardware queues bypassing operating system schedulers.
- High Dynamic Range Imaging:Multi-exposure fusion pipelines enable 120dB+ scene capture for automotive tunnel-exit scenarios.
- Multi-Resolution Processing:Simultaneous stream generation at full, half, and quarter resolution supports both human display and machine perception subsystems.
Real-time processing leads volumes today; AI-based processing shows the steepest expansion trajectory as EU AI Act compliance mandates documented algorithmic transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta anchors the highest concentration of vision processor design houses and foundry partnerships, with domestic EV manufacturers consuming SoCs at volumes that justify captive semiconductor investments.
China
Domestic electric vehicle manufacturers BYD and NIO drive vision SoC consumption at scales justifying captive foundry investments, compressing import dependency for advanced driver-assistance systems. MIIT's GB standards for automotive electronics mandate cybersecurity certifications that filter foreign processor vendors. The Pearl River Delta cluster around Shenzhen houses camera module integrators supplying BYD's vertical manufacturing ecosystem.
United States
NHTSA FMVSS testing protocol expansions for pedestrian detection in low-light conditions mandate sensor fusion upgrades across Detroit Three vehicle platforms. The CHIPS and Science Act directs federal subsidies toward domestic 7nm fabrication capacity for automotive-qualified silicon. Austin's semiconductor corridor hosts design centers serving both automotive Tier-1s and defense imaging programs requiring ITAR compliance.
Germany
Automotive OEM procurement teams at BMW and Mercedes-Benz specify outcome-based performance guarantees that compress supplier margins and force backward integration into lens manufacturing. Germany's KBA coordinates EU AI Act enforcement approaches for autonomous vehicle vision systems that fragment compliance strategies. Stuttgart's automotive electronics cluster concentrates Tier-1 development centers for multi-camera fusion pipelines.
South Korea
Samsung Electronics and SK Hynix anchor memory supply security for heterogeneous SoC architectures integrating ISP and NPU subsystems. MFDS regulates AI-enabled medical imaging devices through evolving clinical validation pathways that extend product development timelines. Seoul's Pangyo Techno Valley hosts fabless design houses specializing in computational photography accelerators for smartphone OEMs.
India
Production-linked incentive schemes for semiconductor assembly and testing attract vision processor packaging investments serving domestic smartphone and automotive electronics manufacturing. BIS certification requirements for electronic components create technical barriers for unqualified imports. Tamil Nadu's electronics manufacturing cluster near Chennai hosts Foxconn and Dixon facilities assembling camera modules for export markets.
Image Signal Processor and Vision Processor Market Competitive Environment
Capacity expansion dominates the current landscape as silicon vendors race to secure sub-7nm wafer allocations at TSMC and Samsung Foundry. The market structures around three tiers: integrated device manufacturers with captive foundry capacity, fabless specialists licensing IP cores, and programmable logic vendors serving defense-medical niches. Strategic archetypes include thermal-hardened automotive platform vendors, computational photography convergence players, and reconfigurable defense imaging suppliers. M&A activity concentrates on optical component acquisitions and AI accelerator IP purchases.
Within the integrated device manufacturer tier, STMicroelectronics exemplifies vertical control through captive silicon carbide foundry capacity serving Tier-1 automotive programs. Texas Instruments Incorporated occupies a position spanning industrial and automotive segments with programmable DSP architectures. Qualcomm Technologies anchors premium smartphone ISP sockets through computational photography co-processing architectures. These three entities represent distinct competitive vectors: substrate-level thermal innovation, catalog breadth across automation markets, and AI-ISP fusion for mobile imaging.
| Leading Market Players |
|---|
| STMicroelectronics |
| Texas Instruments Incorporated |
| Samsung Electronics |
| Qualcomm Technologies |
| Sony Corporation |
| ON Semiconductor |
| NXP Semiconductors |
| Analog Devices |
| Fujitsu |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide wafer price indices cascade through automotive vision processor supply chains into three-tier pricing structures across premium, standard, and economy levels. Automotive OEM procurement teams leverage volume commitments to compress margins at Tier-1 suppliers, while smartphone vendors absorb die-size premiums for computational photography co-processing.
Pricing Analysis
Input-cost pass-through from sub-7nm wafer scarcity at TSMC and Samsung Foundry concentrates pricing pressure on premium automotive SoC tiers. Certification-grade differentiation separates EU AI Act-compliant platforms from uncertified alternatives, with FDA-cleared medical imaging processors commanding the widest margins. Cost compression in standard-tier surveillance camera chips intensifies because Chinese domestic foundry capacity expands supply. Smartphone OEMs exhibit least price sensitivity due to computational photography feature premiums, while Indian assembly houses face tightest procurement constraints.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, creating single-source vulnerability for advanced node fabrication. Taiwan, South Korea, and the United States anchor geographic supply concentration for NPU-integrated vision processors. Silicon carbide substrates draw from STMicroelectronics' captive foundry and external SiC wafer vendors. EU AI Act documentation requirements impose regulatory friction on cross-border component flows. Distribution runs through Tier-1 automotive module suppliers and smartphone OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's MIIT certification requirements and India's PLI scheme incentives for semiconductor assembly. Regulatory divergence creates cost differentials exceeding 15% for equivalent vision processor packaging.
For Market Incumbents: Deepen backward integration into silicon carbide substrate production to defend automotive socket margins against emerging Chinese foundry competition. Expand captive 7nm capacity allocation through CHIPS Act subsidy capture in the United States. Prioritize EU AI Act conformity assessment pre-certification to compress Tier-1 supplier validation cycles.
For New Entrants and Emerging Players: India's PLI scheme for semiconductor assembly and testing opens a window for packaging-focused entrants to capture smartphone and automotive electronics manufacturing demand. Target surveillance camera SoC design for Chinese safe-city deployments where domestic certification requirements filter foreign competition. Pursue fabless IP licensing models to bypass sub-7nm foundry allocation bottlenecks.
For Investors and Strategic Acquirers: Asymmetric upside sits with reconfigurable logic specialists serving defense-medical niches where post-deployment algorithm updates sustain pricing power. Five-to-ten-year viability hinges on transformer-based vision model hardware-software co-optimization capabilities. Watch for NHTSA FMVSS low-light pedestrian detection protocol finalization as fleet retrofit demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Capacity Expansion | STMicroelectronics' captive SiC substrate integration anchors thermal-hardened automotive supply security. |
| EU AI Act Conformity Pre-Certification | Documented algorithmic transparency accelerates Tier-1 supplier validation cycles for high-risk deployments. |
| India PLI Packaging Investment | Production-linked incentives attract vision processor assembly serving domestic smartphone and automotive electronics. |
| Transformer Model Hardware-Software Co-Optimization | Swin Transformer and DETR variant acceleration compresses 18-month validation cycles to 6-month software updates. |
| Automotive SerDes Protocol Migration | MIPI CSI-2 to Automotive SerDes transitions force simultaneous hardware redesign and software stack revalidation. |
Study Parameters
Coverage spans China, the United States, Germany, South Korea, and India, with primary inputs from each regional cluster. Primary interviews with automotive Tier-1 procurement directors, smartphone OEM platform engineers, fabless design house CTOs, and foundry capacity planning managers combined with secondary validation from SEC 10-K filings, MIIT GB standard publications, NHTSA FMVSS docket records, and EU AI Act implementation guidance. Bottom-up and top-down triangulation cross-validated silicon vendor revenue disclosures against vehicle production databases and smartphone shipment estimates.
Granularity-level modeling treated product type, application, end user, and technology as fully specified dimensions across the projection horizon. Automotive camera content per vehicle, smartphone die-size efficiency curves, and surveillance camera edge inference penetration served as industry-specific forecast inputs. CAGRs derived from logistic adoption curve fitting against historical semiconductor content growth patterns.
Revisions become necessary when sub-7nm foundry allocation constraints tighten, EU AI Act enforcement approaches fragment across member states, or NHTSA FMVSS testing protocols expand beyond current pedestrian detection scopes. Forecasts reflect assumptions about continued transformer-based model displacement of convolutional networks and sustained China EV production scale. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Infrared Imaging Market
Imaging
Camera Stabilizer Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
Raman-Imaging System Market
Imaging
Mobile Camera Module Market
Imaging
On-Chip Color Filters Market
Imaging
Compact Camera Module Market
Imaging
LCD Digital Microscope Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
X-Ray Market
Imaging
Global Image Processing Systems Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Camera Technology Market
Imaging
Silent Scan Technology Market
Imaging
North America Digital Camera Market
Imaging
Global Whole Slide Imaging Market