
 Mobile Chipset Market | 2026-2036
Mobile Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Chipset Market Outlook
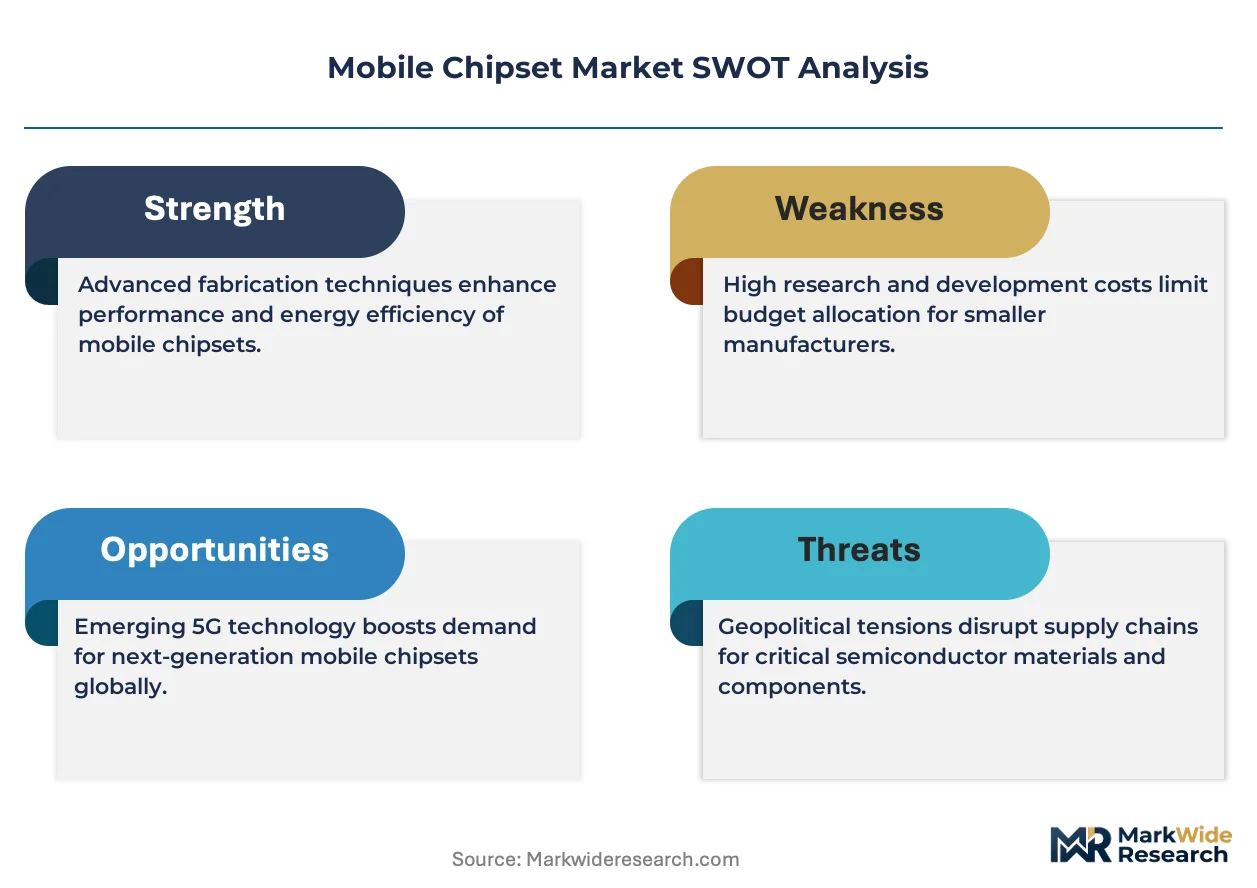
The EU Green Deal is pivoting semiconductor procurement toward lower-carbon foundry partnerships across the mobile supply chain. Qualcomm Technologies leverages its vertical integration into RF front-end modules to sustain premium-tier pricing power. MediaTek anchors mid-range smartphone volumes through aggressive 5G chipset refresh cycles. Samsung Electronics dominates captive supply for its Galaxy device portfolio while competing for external foundry business.
A mobile chipset integrates the central processing unit, graphics processor, modem, and memory controller onto a single silicon die, typically fabricated through extreme ultraviolet lithography at nodes between 3nm and 28nm depending on performance and cost targets. Application processors command the largest revenue share as smartphone computational demands intensify for on-device AI inference. Modem chipsets represent the fastest-expanding product category as 5G standalone networks reach mass deployment. Foundry technology at 5nm and 7nm nodes captures disproportionate margin pools due to equipment scarcity and yield optimization complexity.
The EPA regulates hazardous substance reporting for semiconductor manufacturing facilities operating within the United States. REACH and RoHS frameworks in Europe restrict specific chemicals in chipset packaging and substrate materials, directly influencing material selection and compliance costs. China's MIIT enforces domestic 5G standards that shape modem design requirements for devices sold in that market. Stakeholders must monitor foundry capacity allocation decisions between leading-edge and mature nodes as AI-driven demand reshapes semiconductor supply priorities.
Market Dynamics
Extreme ultraviolet lithography scarcity at 3nm and 5nm nodes concentrates foundry bargaining power among three facilities worldwide, forcing smartphone OEMs into multi-year capacity reservations that reshape chipset procurement economics.
Growth Catalysts
- 5G Standalone Network Deployment:Mobile network operators in China, South Korea, and Germany accelerate modem chipset refresh cycles as sub-6 GHz and mmWave spectrum allocations finalize.
- EU Green Deal Carbon Border Adjustments:Semiconductor packaging suppliers face binding emissions disclosure requirements that favor foundries with verified renewable energy procurement.
- On-Device AI Inference Demand:Application processor architectures integrate neural processing units to execute large language model tasks locally, eliminating cloud latency for voice and imaging workloads.
Market Restraints
- EUV Scanner Equipment Monopoly:Single-source dependency for 0.33 NA and 0.55 NA lithography systems creates 18-month order backlogs that gate node advancement.
- Fluorinated Gas Supply Concentration:Etching chemistry for 3nm finFET and gate-all-around structures relies on Japanese and Korean material suppliers vulnerable to export licensing friction.
- Substrate Warpage at Advanced Nodes:Thermal expansion mismatch between silicon dies and organic substrates degrades yield below 5nm, compressing effective wafer output.
Strategic Opportunities
- India PLI Scheme for Semiconductor Assembly:Fiscal incentives for display and chipset packaging attract OSAT relocation from Greater China, diversifying geographic risk.
- Automotive-Grade Modem Integration:Telematics control units in connected vehicles require automotive-qualified 5G chipsets with extended temperature ranges, opening premium pricing tiers.
- Chiplets and 2.5D Interposer Architectures:Disaggregating modem, NPU, and memory controller functions onto separate dies reduces yield loss and enables foundry node mixing.
Industry Challenges
- Compound Semiconductor Talent Scarcity:RF front-end design for mmWave beamforming requires gallium nitride expertise concentrated among legacy defense contractors and academic programs.
- REACH Compliance Timeline Compression:ECHA substance-of-very-high-concern candidate list expansion forces rapid reformulation of underfill and molding compounds with 12-month implementation windows.
- Legacy Node Capacity Reallocation:Foundry investment diversion toward AI accelerator demand at 4nm and 5nm strains 28nm supply for mid-range smartphone chipsets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Chipset Market |
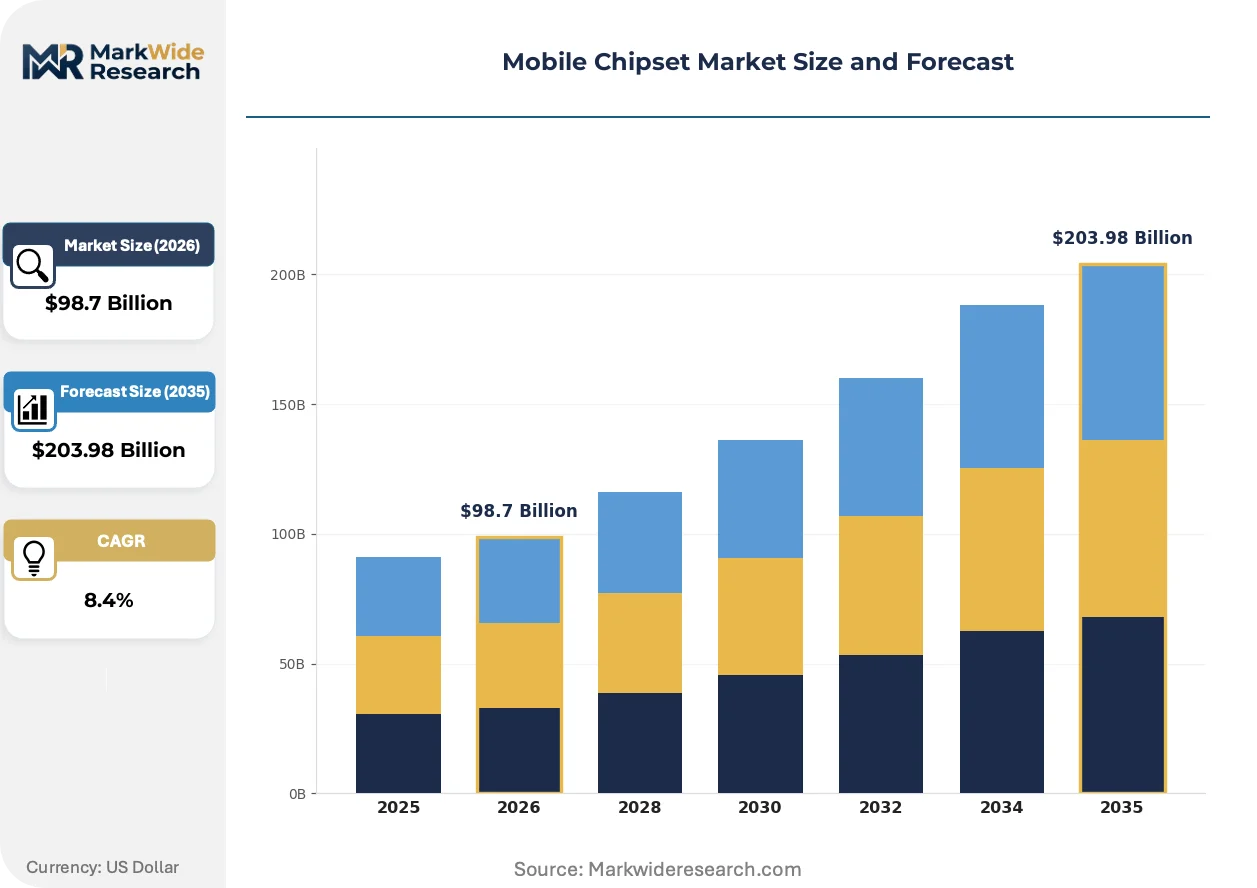
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Application Processors, Modem Chipsets, Power Management ICs, RF Transceivers Technology: 5nm, 7nm, 10nm, 14nm, 28nm Application: Smartphones, Tablets, Wearables, Enhanced Mobile Broadband, IoT Devices End User: OEMs, Tier-1 Providers, Network Equipment Manufacturers, Semiconductor Foundries |
| Companies Covered | Qualcomm Technologies, MediaTek, Samsung Electronics, Apple, Broadcom, Intel Corporation, HiSilicon Technologies, UNISOC Technologies, Skyworks Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Chipset Market Strategic Shifts
Silicon design automation and heterogeneous integration are compressing development cycles while regulatory emissions frameworks and procurement consolidation reshape competitive positioning across the value chain.
Gate-all-around transistor architecture is automating power efficiency gains at 3nm and 2nm nodes by replacing finFET structures with nanosheet stacks that eliminate leakage paths. Smartphone OEMs in the premium tier have adopted this technology since 2022, with mid-range device integration accelerating through 2024. This structural shift is automating the displacement of planar transistor legacy designs and compressing competitive differentiation to packaging and software optimization rather than node leadership alone.
REACH Annex XIV authorization requirements for hexavalent chromium and certain phthalates in substrate plating and conformal coatings are forcing chipset packaging suppliers to qualify alternative chemistries. The industrial consequence is 8-14 month qualification delays for new material sets and elevated testing costs passed to foundry customers. Smartphone OEMs selling into the European Economic Area are responding by consolidating supplier bases to partners with pre-validated green chemistry portfolios.
Direct foundry contracting by smartphone OEMs is displacing traditional merchant chipset procurement through volume commitments and co-development agreements. This pattern concentrates in China where domestic design houses secure priority wafer allocation from local foundries. The structural consequence is margin compression for fabless semiconductor vendors unable to match captive capacity guarantees.
Mobile Chipset Market Segmentation
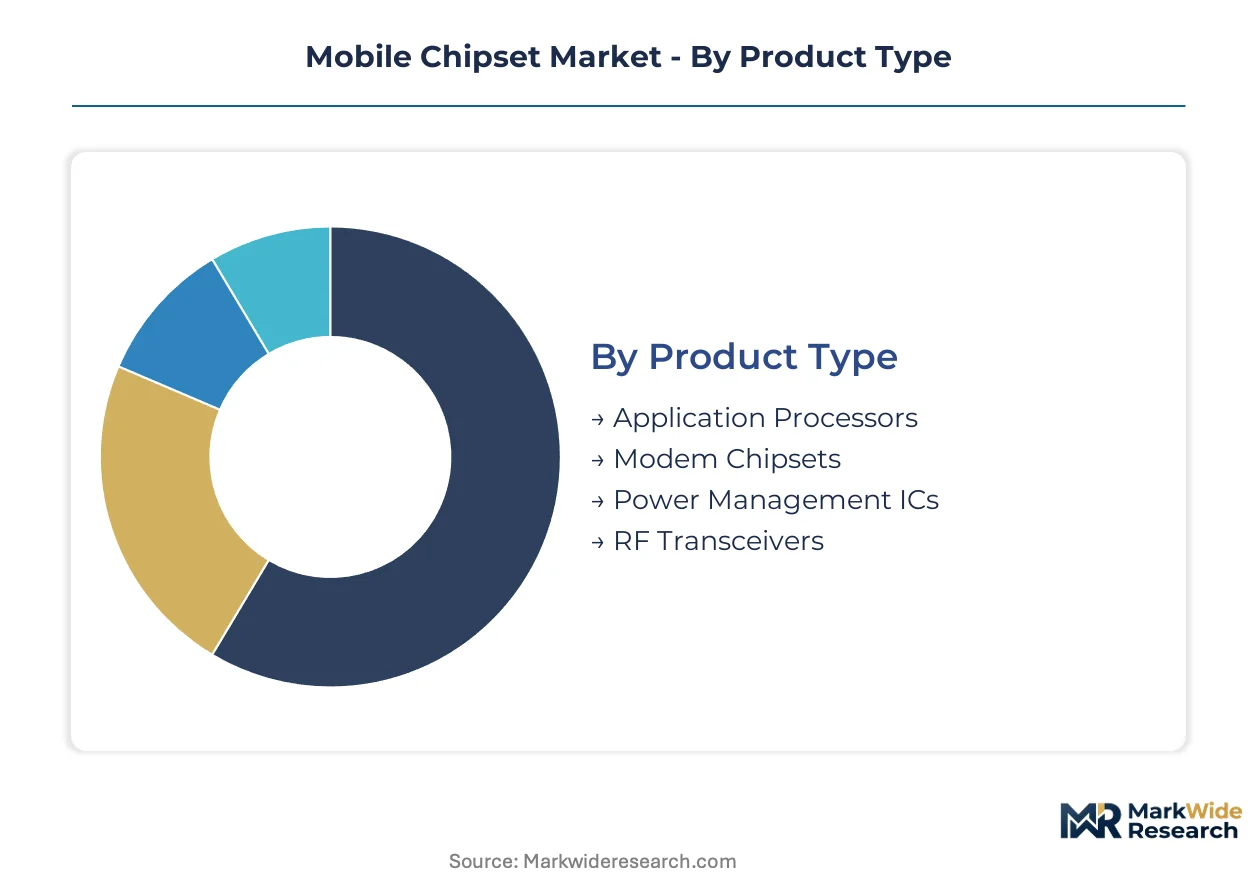
Mobile chipset segmentation reveals how foundry capacity allocation, node migration patterns, and end-use computational requirements create distinct margin pools across the value chain. Understanding these divides exposes where procurement leverage concentrates and where technology transitions unlock pricing power.
Product Type:
Supply concentration at leading-edge foundries disproportionately favors segments requiring EUV lithography, locking in multi-year capacity reservations for the most advanced dies.
- Application Processors:These integrated circuits combine CPU, GPU, and NPU cores onto monolithic silicon dies for primary computational workloads. Smartphone OEMs in China and South Korea anchor demand as on-device AI inference requirements intensify for imaging and voice processing tasks. Supply constraints at 3nm and 5nm nodes force these customers into prepayment structures that reshape procurement economics.
- Modem Chipsets:Baseband processors managing 5G NR, LTE, and legacy cellular protocols require mixed-signal design expertise concentrated among a handful of vendors. 5G standalone deployment in Germany and South Korea accelerates refresh cycles for sub-6 GHz and mmWave variants, with China's MIIT domestic standards shaping regional design requirements.
- Power Management ICs:Voltage regulation and battery charging subsystems fabricated at mature nodes.
- RF Transceivers:Mixed-signal components handling frequency conversion and signal conditioning for cellular and Wi-Fi protocols.
Today's leader: Application Processors. Tomorrow's challenger: Modem Chipsets.
Technology:
Cost tier stratification separates premium smartphone chipsets from mass-market alternatives, with each node commanding distinct equipment depreciation schedules and yield optimization challenges.
- 5nm:Gate-all-around transistor architecture at this node delivers power efficiency gains through nanosheet stacks that eliminate finFET leakage paths. Premium-tier smartphone OEMs have deployed this technology since initial commercialization, with mid-range integration accelerating through recent design cycles. EUV scanner scarcity at this node concentrates foundry bargaining power among three facilities worldwide.
- 7nm:FinFET-based designs balance performance and cost for upper-mid-range device categories. MediaTek anchors volume here through aggressive refresh cycles targeting price-sensitive smartphone markets in India and Southeast Asia. Foundry capacity at this node faces reallocation pressure from AI accelerator demand.
- 10nm:Legacy finFET node serving cost-optimized smartphone segments.
- 14nm:Mature technology for mid-range application processors and IoT chipsets.
- 28nm:Planar transistor designs for entry-level smartphones and basic connectivity modules.
5nm captures the steepest margin expansion trajectory. 7nm defends volume dominance.
Application:
Volume concentration in smartphones creates procurement scale advantages that downstream segments cannot replicate, though specialized form factors command premium pricing for thermal and power constraints.
- Smartphones:The dominant end-use consumes the majority of leading-edge wafer output, with computational demands intensifying for multi-camera image signal processing and neural network inference. China's domestic foundry expansion supports local design houses serving this segment with priority capacity allocation.
- Enhanced Mobile Broadband:Fixed wireless access and mobile hotspot devices require high-throughput modem architectures with extended thermal envelopes. Network operators in Germany and South Korea deploy these for 5G standalone coverage extension where fiber backhaul remains uneconomical.
- Tablets:Larger form factors accommodating higher thermal budgets for application processors.
- Wearables:Ultra-low-power requirements driving specialized process node selection.
- IoT Devices:Cost-optimized connectivity modules for industrial and consumer applications.
Smartphones command absolute volume leadership. Enhanced Mobile Broadband offers the fastest climb in average selling prices.
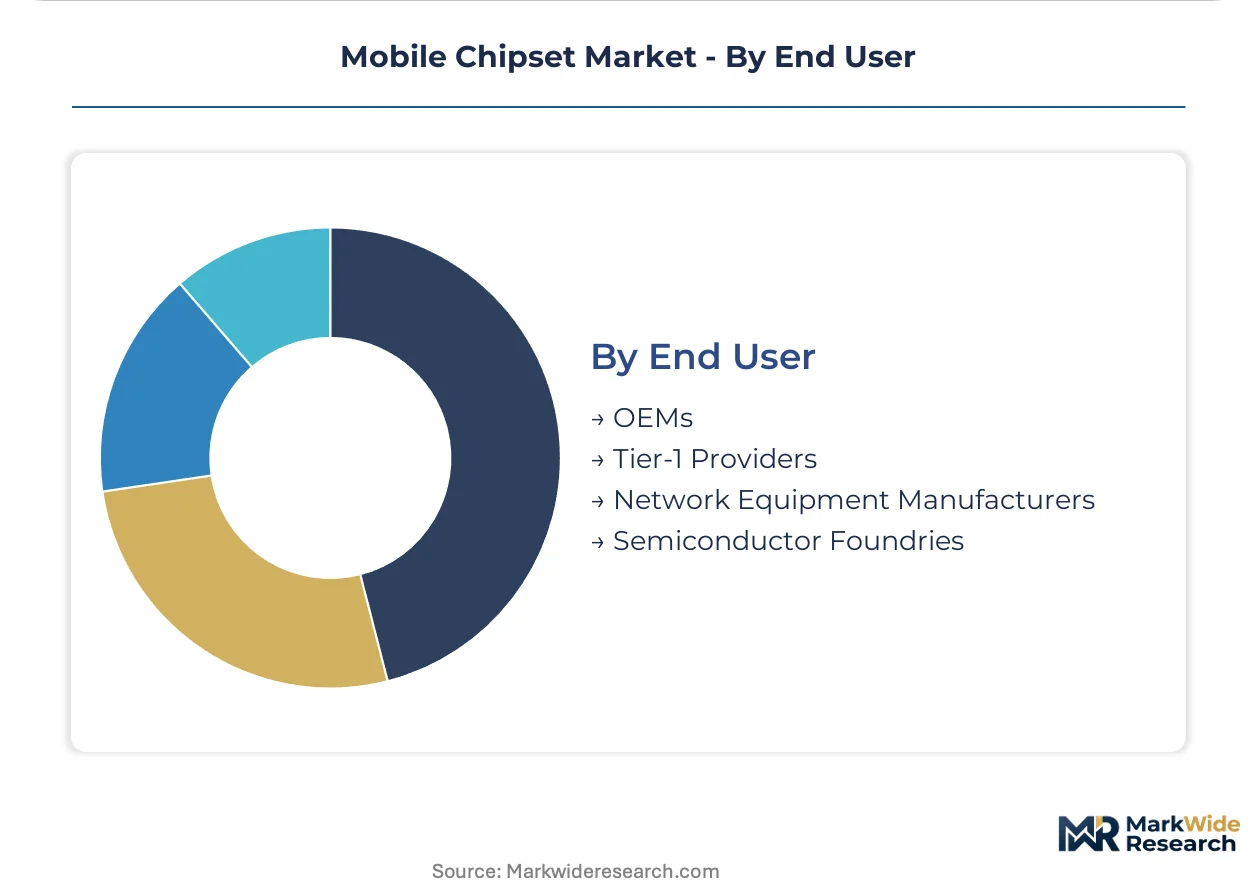
End User:
Customer type determines contract structure, with captive foundry relationships displacing traditional merchant procurement for the largest volume consumers.
- OEMs:Smartphone manufacturers including Apple, Samsung Electronics, and Chinese domestic brands negotiate direct foundry contracts through volume commitments and co-development agreements. This pattern concentrates in China where design houses secure priority wafer allocation, compressing margins for fabless vendors unable to match captive guarantees.
- Semiconductor Foundries:Pure-play and integrated device manufacturers supply wafer fabrication services across node generations. Taiwan, South Korea, and the United States host the concentrated advanced-node capacity that gates overall market output.
- Tier-1 Providers:Subsystem integrators sourcing chipsets for device assembly.
- Network Equipment Manufacturers:Infrastructure vendors procuring modem chipsets for base station and small cell deployment.
OEMs dictate pricing terms through scale. Semiconductor Foundries capture value through node scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile chipset fabrication traces its industrial roots to Taiwan's foundry revolution in the 1980s, when pure-play manufacturing separated from integrated design. This legacy concentrates advanced-node capacity across three facilities worldwide, with demand patterns now fragmenting across multiple national markets.
China
Domestic foundry capacity expansion supports local design houses serving the world's largest smartphone user base. MIIT enforces domestic 5G standards that shape modem architectures for devices sold within this market. Yangtze River Delta clusters around Shanghai host priority wafer allocation agreements between state-backed fabricators and handset manufacturers.
South Korea
Memory-semiconductor infrastructure anchors application processor development for premium-tier devices. MFDS coordinates with industry on materials safety frameworks affecting packaging chemistry selection. Seoul Capital Area foundries compete for external customers beyond captive supply arrangements with domestic electronics conglomerates.
United States
Fabless design houses concentrate in California and Texas, licensing architecture IP while outsourcing fabrication overseas. EPA hazardous substance reporting requirements govern any domestic packaging or testing facilities. Austin and Phoenix host advanced packaging operations that bridge foreign wafer supply with North American device assembly.
Germany
Automotive electronics demand pulls modem chipset qualification toward extended temperature specifications for vehicle telematics. EU REACH compliance timelines force rapid reformulation of substrate materials used in components sold across the European Economic Area. Dresden's silicon cluster hosts EUV-equipped facilities serving both mobile and industrial semiconductor markets.
India
PLI scheme fiscal incentives attract OSAT relocation for display and chipset packaging operations from Greater China. TRAI spectrum allocation decisions shape 5G deployment timelines that drive modem refresh cycles among domestic handset brands. Gujarat and Karnataka host emerging assembly and test facilities serving Southeast Asian export markets.
Mobile Chipset Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where foundry scarcity concentrates bargaining power among three advanced-node facilities worldwide. The vendor base stratifies into captive-integrated conglomerates, pure-play merchant suppliers, and fabless design specialists. Two dominant competitive moves define current positioning: direct foundry contracting through multi-year capacity reservations, and backward integration into RF front-end modules to capture premium-tier margin pools.
Within the fabless design tier, Qualcomm Technologies and MediaTek occupy positions that exemplify divergent market approaches—one leveraging upstream control over modem-RF integration, the other anchoring mid-range volumes through aggressive refresh cycles. Samsung Electronics represents the captive-integrated archetype, supplying internal device portfolios while competing for external foundry business. These three entities collectively illustrate how procurement economics reshape competitive positioning as EUV scanner scarcity forces OEMs into prepayment structures.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| MediaTek |
| Samsung Electronics |
| Apple |
| Broadcom |
| Intel Corporation |
| HiSilicon Technologies |
| UNISOC Technologies |
| Skyworks Solutions |
| Others |
Value Chain & Pricing Dynamics
Premium-tier smartphone OEMs concentrate procurement leverage through multi-year foundry capacity reservations, locking in three-tier pricing stratification across premium, standard, and economy chipset tiers. This buyer-architecture concentrates pricing power among Apple, Samsung Electronics, and Chinese domestic brands while compressing margins for fabless vendors unable to match volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs chipset procurement, with node generation and EUV lithography access as primary differentiation drivers. Price differentiation hinges on gate-all-around transistor availability at 3nm and 5nm nodes versus legacy finFET supply at 7nm and above. Cost compression in mid-range tiers is intensifying because foundry investment diversion toward AI accelerators strains 28nm capacity. Entry-level smartphone OEMs exhibit highest price sensitivity, while premium-tier buyers prioritize performance-per-watt over unit economics.
Supply Chain Analysis
Freight cost escalation for lithography equipment and specialty chemicals amplifies total landed cost for wafers fabricated in Taiwan and South Korea. Geographic supply concentration centers on Taiwan, South Korea, and the United States for EUV-equipped foundry capacity. Raw material dependencies draw from Japanese fluorinated gas suppliers and Korean substrate material providers. Single-source vulnerability for 0.33 NA and 0.55 NA lithography systems creates structural supply risk. Distribution runs through direct foundry contracting with smartphone OEMs displacing traditional merchant procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile chipset economics favor margin expansion through gate-all-around node migration and RF front-end integration, with cost-down drivers from chiplet disaggregation offsetting EUV equipment scarcity premiums.
For Market Incumbents: Anchor leading-edge node leadership through captive EUV capacity reservations at Taiwan and South Korea foundries. Defend against MediaTek's mid-range volume aggression by accelerating 3nm refresh cycles for premium-tier devices. Prioritize backward integration into RF front-end modules to capture modem-antenna margin pools currently contested by Skyworks Solutions and Broadcom. For New Entrants and Emerging Players: Chiplets and 2.5D interposer architectures offer a technology-first wedge into automotive-grade modem segments where extended temperature specifications create qualification barriers for incumbents. Target India's PLI scheme incentives for OSAT relocation as the most penetrable geography. Pursue co-development agreements with domestic Chinese design houses seeking alternative foundry sources beyond state-backed fabricators. For Investors and Strategic Acquirers: Smartphone OEMs are the most active acquirer in this space, consolidating fabless design houses to secure priority wafer allocation. Long-term viability hinges on 5G standalone deployment velocity and on-device AI inference adoption curves. Monitor foundry capital expenditure announcements at 2nm and below as the critical inflection signal for node leadership transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Contracting | Apple and Samsung Electronics secure multi-year EUV capacity reservations that reshape procurement economics. |
| RF Front-End Integration | Qualcomm Technologies leverages upstream control over modem-antenna modules to sustain premium pricing power. |
| Chiplet Architecture Adoption | Disaggregated die designs reduce yield loss and enable foundry node mixing for cost-optimized configurations. |
| India PLI Scheme Participation | Fiscal incentives attract OSAT relocation from Greater China to diversify geographic risk exposure. |
| Automotive-Grade Modem Qualification | Extended temperature specifications for vehicle telematics open premium pricing tiers beyond consumer smartphones. |
Study Parameters
Direct dialogue with foundry operations executives, smartphone OEM procurement directors, RF front-end design engineers, and semiconductor packaging specialists grounded the qualitative foundation. Secondary validation drew from SEC 10-K filings, MIIT 5G standardization documents, ECHA REACH substance registrations, and foundry capacity utilization disclosures. Bottom-up wafer demand modeling triangulated against top-down smartphone shipment forecasts to constrain projection variance.
Segment-level revenue outputs across the analysis window reflect node-specific equipment depreciation schedules, yield optimization curves, and regional foundry pricing differentials. The analytical framework modeled technology node, product type, application segment, and end-user procurement structure as core dimensions. CAGRs were derived from foundry capacity expansion timelines weighted against smartphone OEM design win cycles and 5G standalone network deployment trajectories.
The model holds under sustained EUV scanner delivery schedules and stable fluorinated gas supply; deviation in export licensing friction or substrate material qualification delays would shift effective wafer output assumptions. Stakeholders should weight assumptions against their own operating context and foundry partnership structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
China Microprocessor (MPU) Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Indonesia Data Center Processor Market
Chipset and Processors
Envelope Tracking Chips Market