
 Americas Digital Signal Processor Market | 2026-2036
Americas Digital Signal Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Digital Signal Processor Market Insights
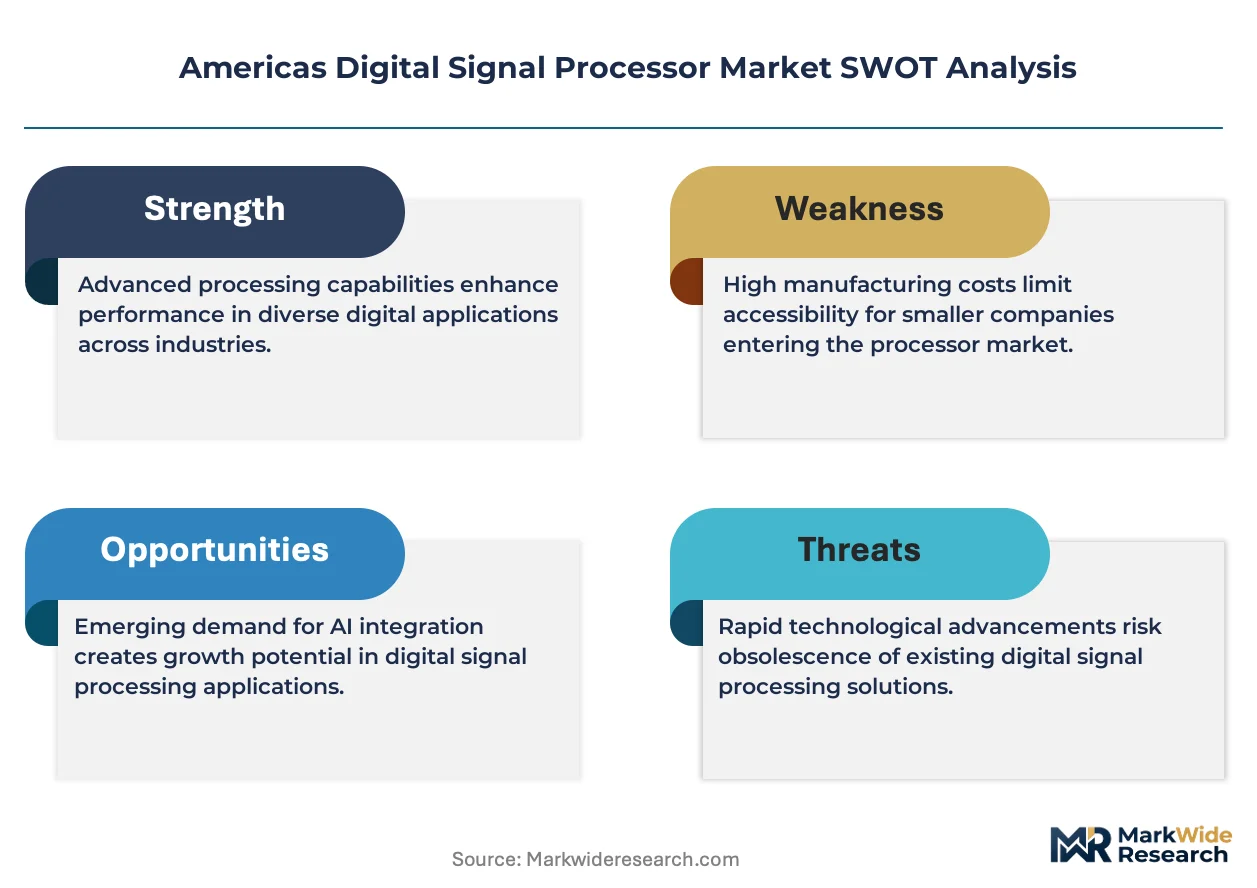
Aftermarket firmware licensing is narrowing as a margin pool as original equipment manufacturers pull DSP tuning capabilities in-house. Texas Instruments Inc. leverages its captive fabrication network to sustain price discipline across industrial automation sockets. Analog Devices Inc. anchors its Americas position through precision converter-DSP integration for automotive radar chains. NXP Semiconductors NV competes aggressively in secure vehicle gateway processors where mixed-signal DSPs handle both protocol translation and real-time threat detection.
A digital signal processor is a specialized microprocessor architecture optimized for high-speed mathematical operations on digitized analog signals, typically executing multiply-accumulate instructions in single clock cycles with fixed-point or floating-point precision. These devices filter, compress, and transform sensor or communication inputs for real-time control in power-constrained environments. Embedded DSPs command the largest revenue footprint across the Americas due to their penetration in motor control and power inverter systems, while wireless DSPs are expanding fastest as 5G baseband processing and software-defined radio architectures displace hardwired modem blocks. Audio DSPs remain mature in consumer electronics, though broadcast companies are upgrading to programmable architectures that support object-based immersive codecs without hardware swaps.
The FCC governs spectrum efficiency mandates that force telecom operators toward more computationally intensive DSP-based beamforming, while the EPA's automotive emissions frameworks push Tier-1 suppliers to adopt faster closed-loop engine control via mixed-signal DSPs. NHTSA safety regulations for advanced driver assistance are expanding the addressable market for automotive DSPs with deterministic latency guarantees. Stakeholders must weigh whether to deepen in-house algorithm development or license optimized DSP libraries as software-defined architectures erode traditional hardware differentiation.
Market Dynamics
The FCC's spectrum reallocation mandates are compressing development cycles for wireless DSP architectures, forcing semiconductor vendors to accelerate programmable beamforming solutions ahead of hardware-defined alternatives.
Growth Catalysts
- Automotive radar integration:NHTSA safety mandates for advanced driver assistance systems are expanding procurement of deterministic-latency DSPs across Tier-1 suppliers in Michigan and Ontario.
- FCC spectrum efficiency rules:Telecom operators in the United States must deploy computationally intensive DSP-based beamforming to satisfy new interference thresholds.
- Mexican electronics manufacturing clusters:Contract manufacturers in Guadalajara and Tijuana are consolidating embedded signal processing procurement for automotive and industrial clients.
Market Restraints
- Wafer capacity concentration:Advanced-node DSP fabrication depends heavily on facilities in Texas and Arizona, creating geographic supply risk during regional disruptions.
- Automotive qualification timelines:AEC-Q100 certification for grade-zero automotive DSPs extends product validation to 18-24 months, freezing design wins.
- FPGA substitution pressure:Field-programmable gate arrays with hardened DSP slices are capturing sockets in software-defined radio applications where reprogrammability outweighs power efficiency.
Strategic Opportunities
- Brazilian industrial automation:Underpenetrated motor control and power inverter installations present white space for embedded DSP vendors serving mining and agriculture equipment makers.
- Software-defined vehicle architectures:Convergence of Ethernet switching and real-time signal processing creates demand for secure gateway processors handling protocol translation alongside sensor fusion.
- Canadian broadcast infrastructure:Public and private broadcasters are upgrading to programmable DSP architectures supporting object-based immersive audio without hardware replacement cycles.
Industry Challenges
- Mixed-signal design talent scarcity:The intersection of precision analog conversion and digital signal processing requires specialized engineers concentrated in Austin, Boston, and Toronto corridors.
- Legacy integration friction:Industrial automation customers in the Midwest and Northeast maintain decades-old control systems, complicating DSP retrofit architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Digital Signal Processor Market |
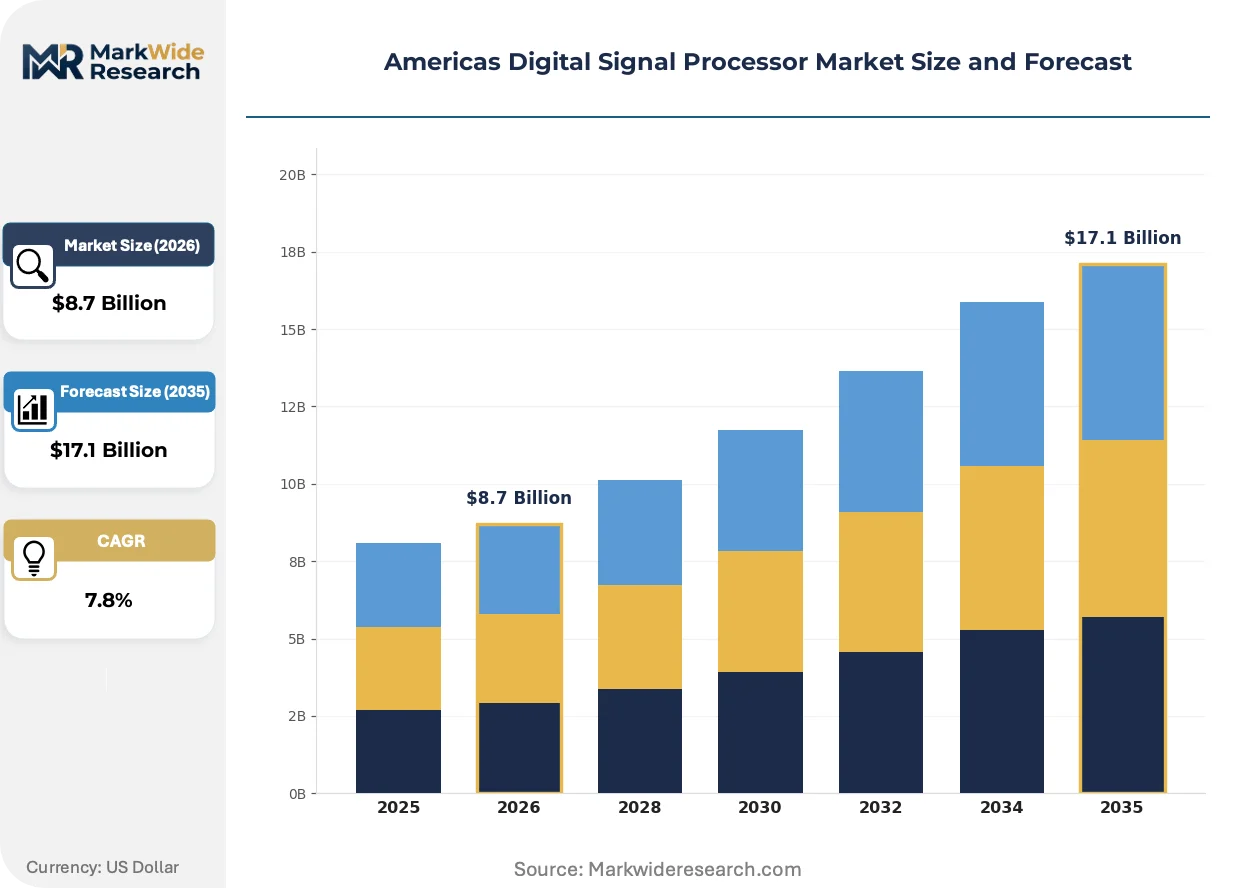
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio DSPs, Video DSPs, Embedded DSPs, Wireless DSPs Application: Consumer Electronics, Automotive Systems, Telecommunications, Industrial Automation End User: OEMs, Tier-1 Suppliers, Broadcast Companies, Telecom Operators Technology: Analog DSPs, Digital DSPs, Mixed-Signal DSPs, Programmable DSPs |
| Companies Covered | Texas Instruments Inc., Analog Devices Inc., NXP Semiconductors NV, Infineon Technologies AG, Intel Corporation, Broadcom Inc., Renesas Electronics Corp., Microchip Technology Inc., Qualcomm Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Digital Signal Processor Market Trends and Innovations
Programmable silicon is displacing fixed-function blocks across wireless infrastructure and automotive sensing chains, compressing the traditional hardware-software boundary in real-time signal processing.
Software-defined radio architectures are collapsing the distinction between baseband modems and general-purpose DSP cores. Tier-1 telecom equipment manufacturers are adopting these platforms for 5G small cell and private network deployments. The shift enables single-chip solutions to absorb multiple air interface standards, compressing bill-of-materials counts and supplier fragmentation.
EPA automotive emissions frameworks are tightening closed-loop engine control requirements. Tier-1 suppliers must deploy faster mixed-signal DSPs to meet real-time combustion optimization mandates. The regulation most acutely affects powertrain control module manufacturers in the Great Lakes automotive corridor, who are accelerating 32-bit floating-point DSP adoption.
Aftermarket firmware licensing is narrowing as original equipment manufacturers internalize DSP tuning capabilities. Automotive and industrial automation buyers now demand source-code access and algorithm ownership as standard contract terms. This behavioral shift is most visible among Detroit-based automakers and their direct Tier-1 relationships, where in-house acoustic and vibration engineering teams are displacing third-party tuning houses.
Americas Digital Signal Processor Market Segmentation
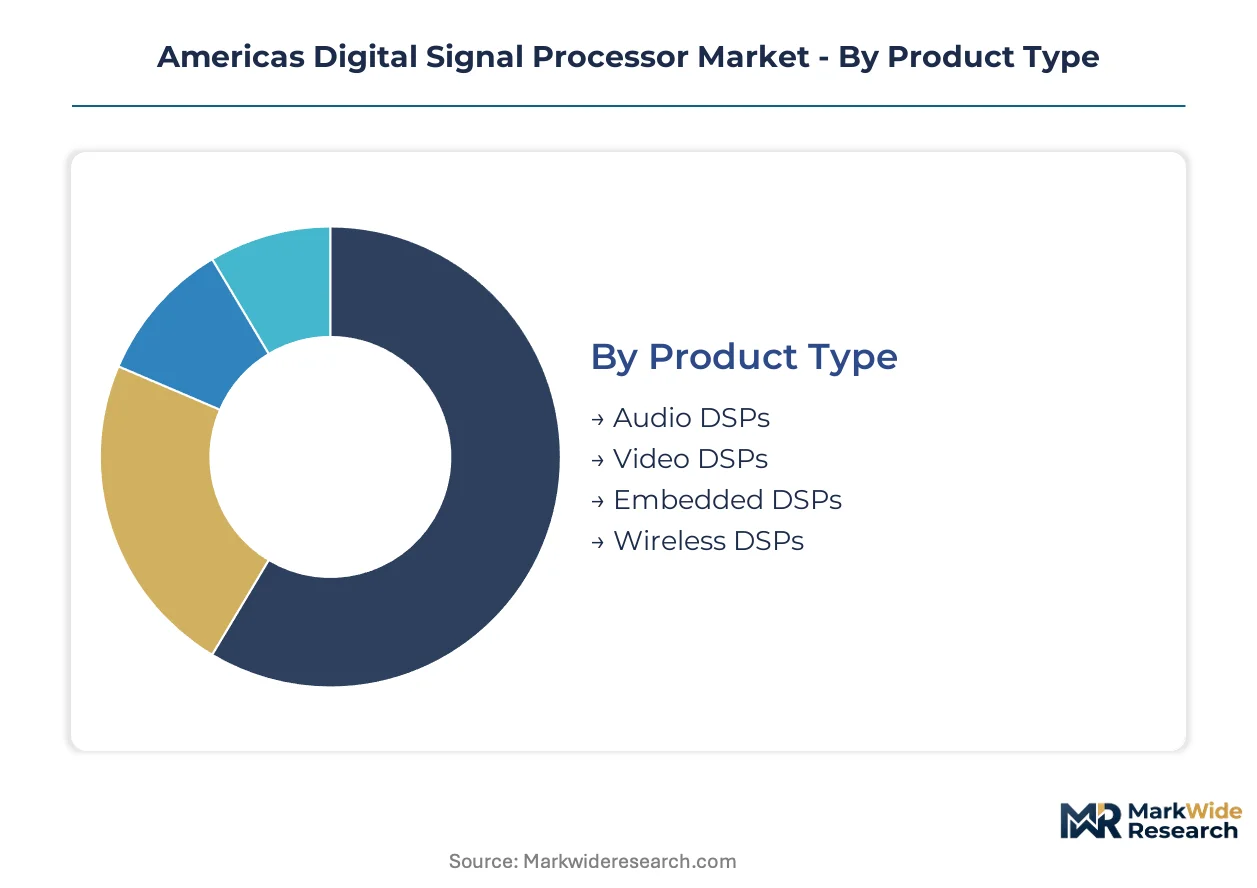
Signal processing architectures diverge sharply across power budgets, latency tolerances, and reprogramming requirements. Understanding these fault lines clarifies why automotive radar chains demand different silicon than broadcast audio pipelines.
Product Type:
The use-case spectrum stretches from milliwatt-constrained wearable audio to kilowatt-class baseband processing in cellular towers.
- Embedded DSPs:These fixed-function architectures execute deterministic control loops with hard real-time guarantees. Demand concentrates in Michigan and Ontario automotive corridors where motor control and power inverter systems require sub-microsecond response times.
- Wireless DSPs:Programmable baseband processors handle orthogonal frequency-division multiplexing and massive MIMO beamforming through vector-optimized instruction sets. FCC spectrum efficiency mandates in the United States are accelerating procurement for 5G small cell and private network deployments.
- Audio DSPs:Mature codecs for consumer electronics.
- Video DSPs:Frame-rate conversion and compression engines.
The dominant share belongs to Embedded DSPs, while Wireless DSPs is closing the gap fastest.
Application:
Cost tiers separate commodity consumer sockets from safety-critical automotive qualification premiums.
- Automotive Systems:Radar signal chains and engine control modules require AEC-Q100 grade-zero certification with deterministic latency bounds. NHTSA advanced driver assistance mandates are expanding procurement across Detroit-based Tier-1 suppliers.
- Telecommunications:Baseband processing for 5G macro cells and software-defined radio infrastructure. FCC reallocation rules force computationally intensive beamforming that favors floating-point precision.
- Industrial Automation:Motor drives and programmable logic controllers.
- Consumer Electronics:Smartphone audio enhancement and smart speaker voice recognition.
Automotive Systems commands the steepest expansion trajectory as electrification multiplies inverter control points per vehicle.
End User:
Customer type dictates contract structures from algorithm ownership to turnkey firmware licensing.
- OEMs:Detroit automakers and Midwest industrial equipment makers increasingly demand source-code access and in-house tuning capabilities. Aftermarket firmware licensing is narrowing as algorithm ownership becomes standard contract terms.
- Tier-1 Suppliers:Powertrain and chassis control module manufacturers in the Great Lakes corridor.
- Telecom Operators:AT&T, Verizon, and T-Mobile procurement for 5G infrastructure.
- Broadcast Companies:Canadian public and private broadcasters upgrading to programmable immersive audio architectures.
OEMs capture the largest procurement volume, though Tier-1 Suppliers are expanding their specification influence fastest.
Technology:
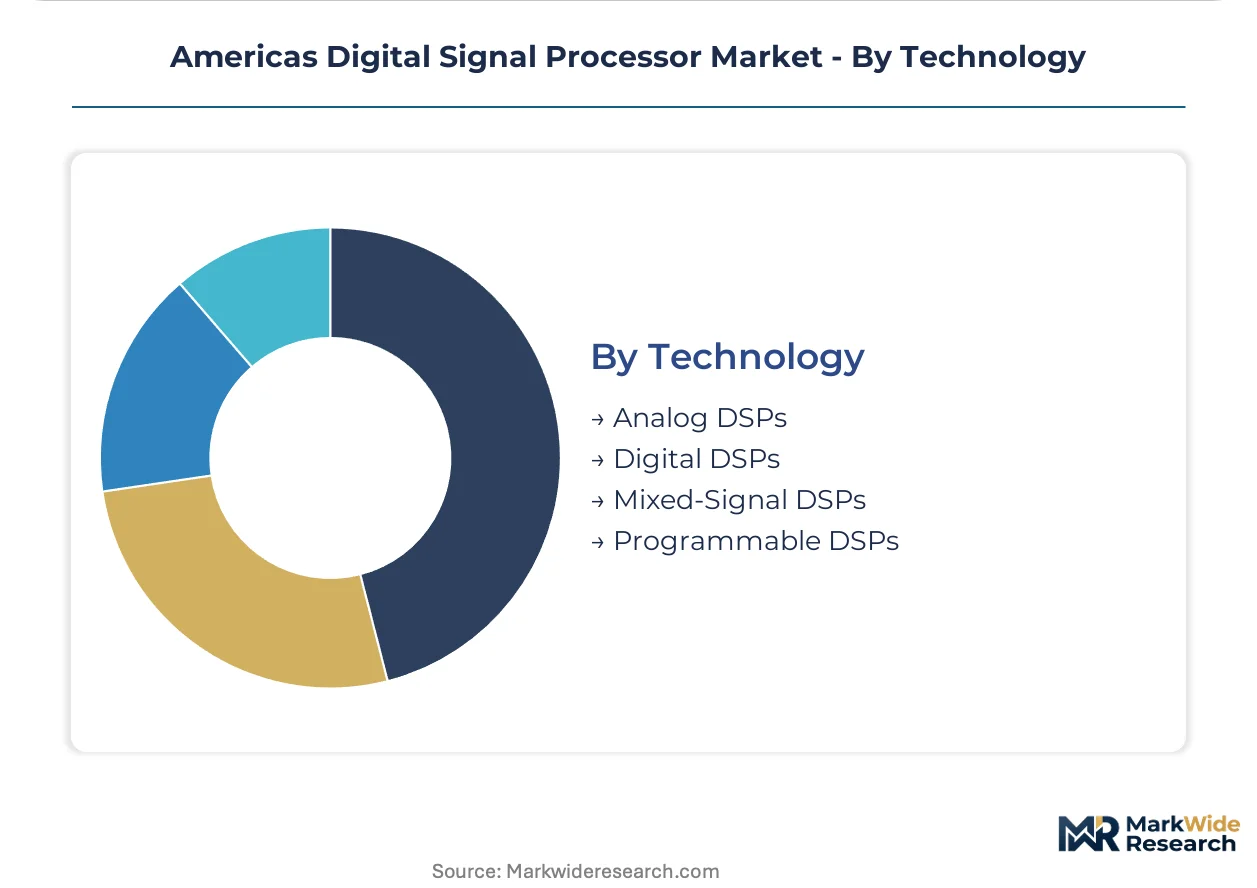
Margin structures favor mixed-signal integration where precision analog conversion commands pricing premiums over pure digital logic.
- Mixed-Signal DSPs:Combine high-resolution analog-to-digital converters with digital filtering on monolithic die. EPA automotive emissions frameworks in the United States push closed-loop engine control that demands real-time combustion optimization.
- Programmable DSPs:Field-updatable instruction sets absorb multiple air interface standards without hardware swaps. FCC spectrum mandates favor these architectures over fixed-function alternatives in telecom infrastructure.
- Digital DSPs:Pure logic implementations for algorithm-intensive processing.
- Analog DSPs:Continuous-time signal processing for specialized sensor interfaces.
Mixed-Signal DSPs holds the revenue concentration, while Programmable DSPs is gaining share fastest as software-defined architectures displace hardwired blocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Americas diverge sharply: the United States drives wireless infrastructure procurement for beamforming architectures, while Mexico and Brazil concentrate embedded DSP demand for automotive and industrial automation.
United States
Telecom operators at AT&T, Verizon, and T-Mobile deploy DSP-based massive MIMO for 5G small cells under FCC spectrum efficiency mandates. The FCC's reallocation rules compress development cycles for programmable beamforming solutions. Semiconductor fabrication clusters in Texas and Arizona are expanding capacity for automotive-grade mixed-signal processors serving Detroit Tier-1 suppliers.
Canada
Broadcast infrastructure upgrades in Toronto and Vancouver are driving procurement of programmable audio DSPs supporting object-based immersive codecs. Health Canada regulates electromagnetic emissions standards for wireless equipment deployed near populated corridors. Precision agriculture equipment manufacturers in Saskatchewan are adopting motor control DSPs for variable-rate seeding and fertilizer systems.
Mexico
Contract manufacturers in Guadalajara and Tijuana are consolidating embedded signal processing procurement for automotive clients exporting to the United States. The Secretariat of Economy's automotive sector incentives attract powertrain control module assembly. Electronics manufacturing clusters in Baja California specialize in software-defined radio components for North American telecom supply chains.
Brazil
Underpenetrated motor control installations in mining and agriculture equipment present expansion opportunities for embedded DSP vendors. ANVISA regulates medical device signal processing standards for diagnostic equipment manufactured in São Paulo state. Industrial automation distributors in Minas Gerais are building technical service capabilities around DSP-based power inverter systems.
Americas Digital Signal Processor Market Competitive Landscape
Capability concentration sits with mixed-signal integration specialists; scale advantage sits with diversified semiconductor conglomerates. The vendor base organizes around three strategic archetypes: captive fabrication networks sustaining price discipline, precision converter-DSP integrators serving automotive radar chains, and secure gateway processor specialists handling protocol translation. Dominant competitive moves include backward integration into analog IP portfolios and geographic expansion into Mexican electronics manufacturing clusters.
Within the captive fabrication tier, Texas Instruments Inc. and Analog Devices Inc. exemplify scale-driven positioning through in-house wafer capacity. NXP Semiconductors NV occupies a position in the secure automotive gateway segment where mixed-signal architectures address real-time threat detection requirements. These three anchors represent divergent bets on whether algorithm ownership or hardware differentiation will capture margin in software-defined vehicle architectures.
| Leading Market Players |
|---|
| Texas Instruments Inc. |
| Analog Devices Inc. |
| NXP Semiconductors NV |
| Infineon Technologies AG |
| Intel Corporation |
| Broadcom Inc. |
| Renesas Electronics Corp. |
| Microchip Technology Inc. |
| Qualcomm Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on advanced-node wafer fabrication in Texas and Arizona determines both pricing tier spreads and supply chain shape across the Americas DSP market. FCC spectrum reallocation deadlines compress procurement timelines for automotive and telecom buyers, amplifying cost premiums for qualified mixed-signal architectures while forcing geographic concentration risks into contract structures.
Pricing Analysis
Long-term offtake agreements dominate procurement between Detroit Tier-1 suppliers and captive fabrication networks, insulating automotive-grade DSPs from spot-market volatility. Three-tier pricing structure across AEC-Q100 grade-zero, grade-one, and industrial-grade certification levels captures qualification cost differentials. Cost compression in consumer audio DSPs stems from algorithm commoditization as OEMs internalize tuning capabilities. Midwest industrial automation buyers exhibit highest price sensitivity due to legacy system retrofit constraints, while telecom operators prioritize latency guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculations for contract manufacturers in Guadalajara and Tijuana serving North American automotive clients. Geographic supply concentration centers on Taiwan for leading-edge logic, South Korea for memory integration, and the United States for automotive-qualified mixed-signal production. Raw material dependencies include silicon wafers, high-purity gases for etching processes, and rare-earth elements for precision analog components. Distribution runs through authorized distributors in the Great Lakes corridor and direct OEM relationships for high-volume telecom deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FPGA substitution with hardened DSP slices threatens fixed-function processor sockets in software-defined radio applications, forcing incumbents to defend through programmable architecture investments and ecosystem lock-in.
For Market Incumbents: Pre-empt FPGA encroachment by accelerating programmable DSP roadmaps for 5G small cell and automotive radar fusion applications. Secure design wins through backward integration into precision analog IP that field-programmable alternatives cannot replicate. Deepen captive fabrication utilization in Texas and Arizona to sustain price discipline against fabless competitors. For New Entrants and Emerging Players: Establish a beachhead in Brazilian motor control installations where mining and agriculture equipment makers remain underpenetrated by established DSP vendors. Target Canadian broadcast infrastructure upgrades for programmable immersive audio architectures as public and private broadcasters phase out fixed-function codecs. Pursue direct technical service partnerships with industrial automation distributors in Minas Gerais to bypass incumbent channel control. For Investors and Strategic Acquirers: NHTSA advanced driver assistance mandates reshape the acquisition landscape toward mixed-signal specialists with deterministic latency capabilities and automotive qualification track records. Long-term viability hinges on exposure to software-defined vehicle architectures where gateway processors merge Ethernet switching with real-time signal processing. Watch for inflection signals in Tier-1 supplier consolidation patterns across the Michigan-Ontario automotive corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Analog IP | Captures margin pools in precision converter-DSP integration for automotive radar chains. |
| Programmable Architecture Roadmap Acceleration | Defends against FPGA substitution in FCC-mandated 5G beamforming deployments. |
| Mexican Manufacturing Cluster Expansion | Positions vendors for Secretariat of Economy automotive sector incentives near Tijuana. |
| Software-Defined Vehicle Gateway Development | Addresses NXP-dominated secure processor segment handling protocol translation. |
| Brazilian Technical Service Partnership | Unlocks white space in mining and agriculture motor control installations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor procurement managers at Detroit Tier-1 suppliers, platform engineers at telecom equipment manufacturers, and broadcast technology directors in Toronto and Vancouver. Secondary validation drew from FCC spectrum allocation filings, EPA automotive emissions framework updates, SEC 10-K disclosures from captive fabrication networks, and NHTSA advanced driver assistance system mandates. Bottom-up unit economics modeling triangulated against top-down market sizing across embedded, wireless, and audio DSP architectures.
Calibration against historical qualification timelines and design-win conversion rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user contract structure, and technology integration level. CAGRs derived from shipment volume trajectories weighted by average selling price trends within each certification tier. Industry-specific forecast inputs incorporated AEC-Q100 grade-zero adoption curves and FCC small cell deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or automotive production volumes would shift the trajectory materially. Forecasts reflect documented assumptions regarding foundry capacity expansion, regulatory compliance timelines, and algorithm ownership trends among OEMs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Connecting Chiplets Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Audio Processor Market