
 Global 3D Nand Flash Memory Market | 2026-2036
Global 3D Nand Flash Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Nand Flash Memory Market Foresight
Korean semiconductor foundries is broadening 3D NAND wafer output to meet cloud storage procurement cycles. Samsung Electronics leverages vertical integration from wafer fabrication to module assembly, sustaining cost advantages across enterprise SSD lines. SK Hynix anchors high-bandwidth memory adjacent to NAND flash, competing for share in AI server configurations.
3D NAND flash memory stacks memory cells vertically in 96-layer to 200-plus-layer architectures, using charge trap or floating gate technologies to achieve terabit-scale density in compact form factors; this design serves data centers, mobile devices, and consumer electronics requiring non-volatile storage with low latency. Triple-level cell and quad-level cell configurations dominate unit shipments due to cost-per-bit efficiency, while single-level cell segments retain margin pools in enterprise caching and industrial applications. Vertical NAND technology leads fabrication roadmaps as planar NAND approaches physical scaling limits.
REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor manufacturing materials, shaping supplier qualification requirements for memory module exporters. South Korea's METI-aligned industrial standards and China's GB standards for electronics safety create divergent compliance pathways that influence factory location decisions. Stakeholders must monitor layer-count transitions and yield economics at leading fabs to anticipate supply availability and pricing inflections.
Market Dynamics
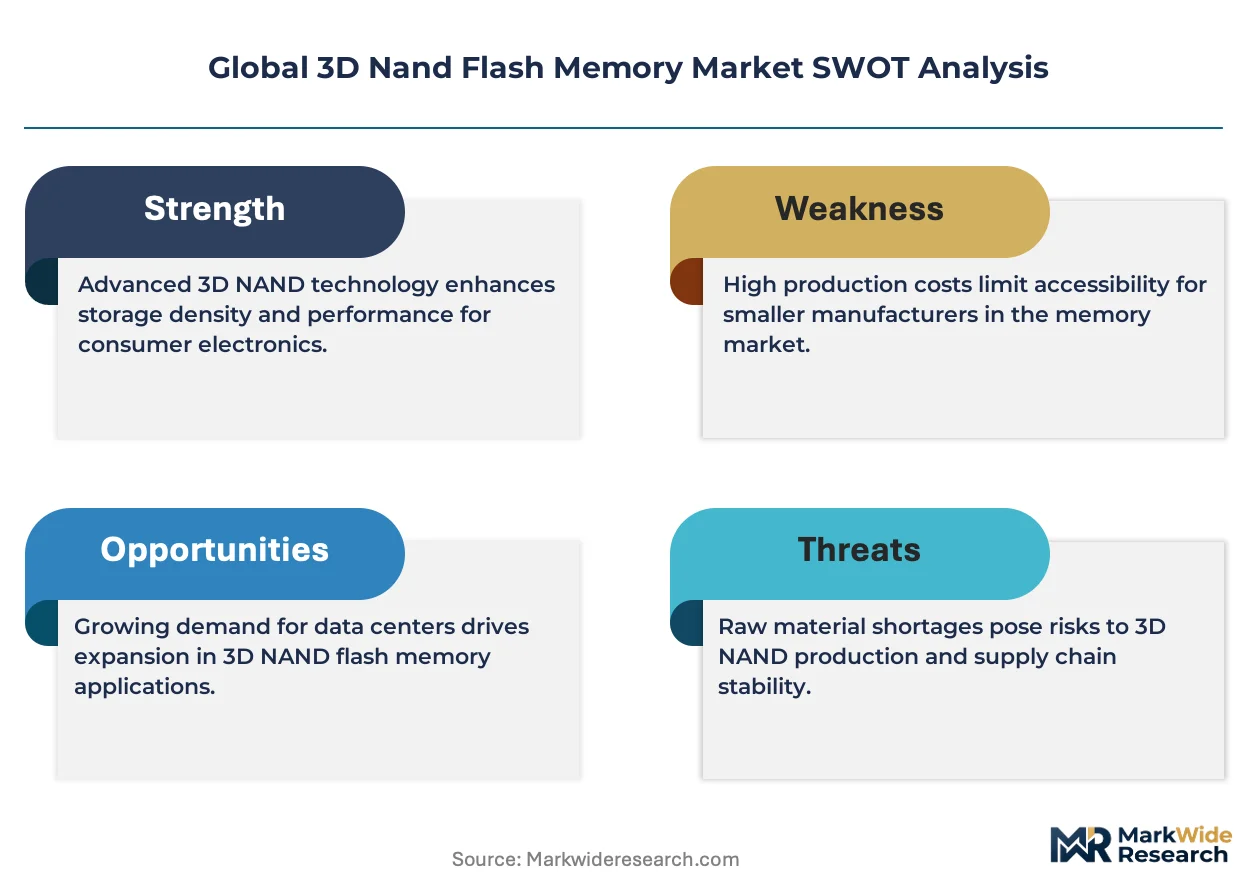
Layer-count transitions at leading fabs are compressing cost-per-bit curves while concentrating supply among vertically integrated manufacturers with captive etch and deposition equipment. This structural force is redrawing competitive boundaries between charge-trap and floating-gate technology camps.
Growth Catalysts
- AI server memory bundling:Data center operators are configuring high-bandwidth memory adjacent to NAND flash in training clusters, creating co-procurement pull-through for dense storage modules.
- China's MIIT localization mandates:Domestic procurement requirements for sensitive infrastructure are redirecting supply chain flows toward qualified Chinese fabs and module assemblers.
- Charge-trap cell architecture:This technology enables higher vertical stacking with improved yield economics, accelerating the transition from 128-layer to 200-plus-layer production ramps.
Market Restraints
- Extreme ultraviolet lithography dependency:Scanner availability from ASML limits fab expansion timelines and concentrates capacity planning among existing high-volume manufacturers.
- Fluorinated gas supply concentration:Etching chemistry inputs face sourcing constraints from Japanese and Korean chemical suppliers, creating input cost volatility during layer-count ramps.
- Planar NAND legacy substitution:Mature-node flash retains cost advantages in low-density applications, delaying full technology displacement in industrial and automotive segments.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor assembly and testing are attracting module packaging investments to serve domestic smartphone and server demand.
- Automotive zonal architecture storage:Edge computing requirements in software-defined vehicles are creating specification pull for industrial-temperature NAND in gateway and sensor fusion modules.
- EU Green Deal material compliance:REACH and RoHS alignment is opening preferential procurement pathways for European data center operators sourcing verified low-carbon memory modules.
Industry Challenges
- Atomic-layer deposition technician scarcity:Specialized process engineering talent for high-aspect-ratio etch control is concentrating at established Korean and Taiwanese fabs, constraining new entrant hiring pipelines.
- Multi-chip packaging integration complexity:Heterogeneous integration of NAND controllers with compute dies requires new thermal and signal-integrity validation protocols, extending product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Nand Flash Memory Market |
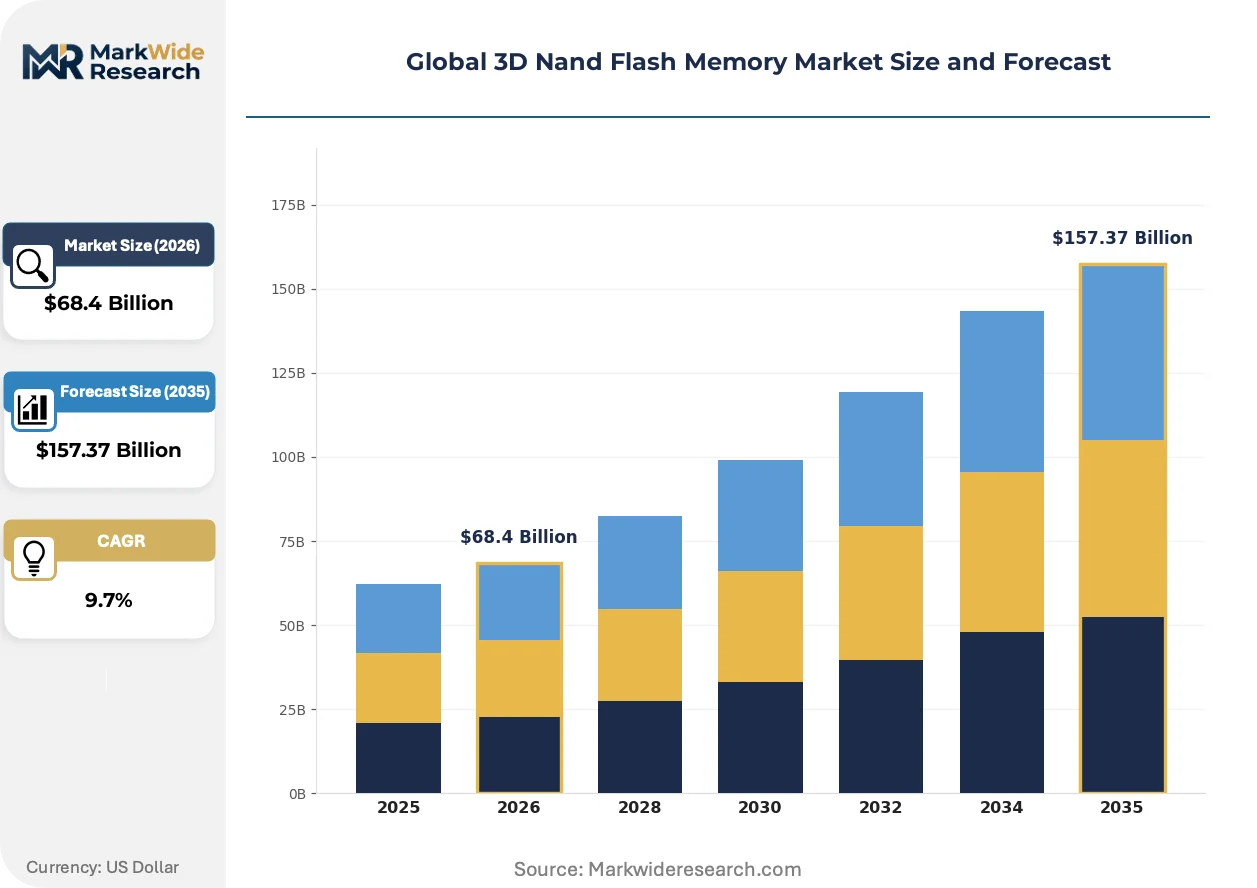
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Level Cell, Multi-Level Cell, Triple-Level Cell, Quad-Level Cell Technology: Charge Trap Flash, Floating Gate, Vertical NAND, Planar NAND Application: Solid State Drives, Mobile Devices, Data Centers, Consumer Electronics End User: Original Equipment Manufacturers, Cloud Data Providers, Telecommunication, High Performance Computing |
| Companies Covered | Samsung Electronics, SK Hynix, Micron Technology, Intel Corporation, Kioxia Corporation, Western Digital Corporation, Yangtze Memory Technologies Company (YMTC), SanDisk Corporation, Transcend Information, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Nand Flash Memory Market Shifts & Advancements
Process technology roadmaps are converging on hybrid bonding and wafer-to-wafer stacking methods that bypass traditional wire-bonding limitations. These shifts are compressing form factors while elevating thermal management requirements.
Charge-trap flash technology is absorbing the majority of new layer-count investments as manufacturers abandon floating-gate architectures beyond 176 layers. Data center SSD procurement teams are specifying this cell type for enterprise workloads requiring sustained write endurance. The technology is absorbing margin pressure from planar NAND by delivering terabit-scale density without proportional die-size expansion.
Europe's REACH framework is restricting per- and polyfluoroalkyl substances in semiconductor wet-processing chemicals, forcing reformulation of cleaning chemistries used in NAND fabrication. Memory module exporters to the EU must now document substance safety data across extended supply chains. Korean and Japanese chemical suppliers are accelerating green chemistry certifications to maintain qualification status with European OEM customers.
Hyperscale buyers are consolidating procurement through direct fab relationships rather than distributor channels, compressing traditional memory module margin structures. Cloud operators in the United States and China are negotiating long-term supply agreements that bypass branded SSD vendors entirely. This disintermediation is most visible in North American data center buildouts where Meta, Amazon, and Microsoft account for concentrated volume commitments.
Global 3D Nand Flash Memory Market Segmentation
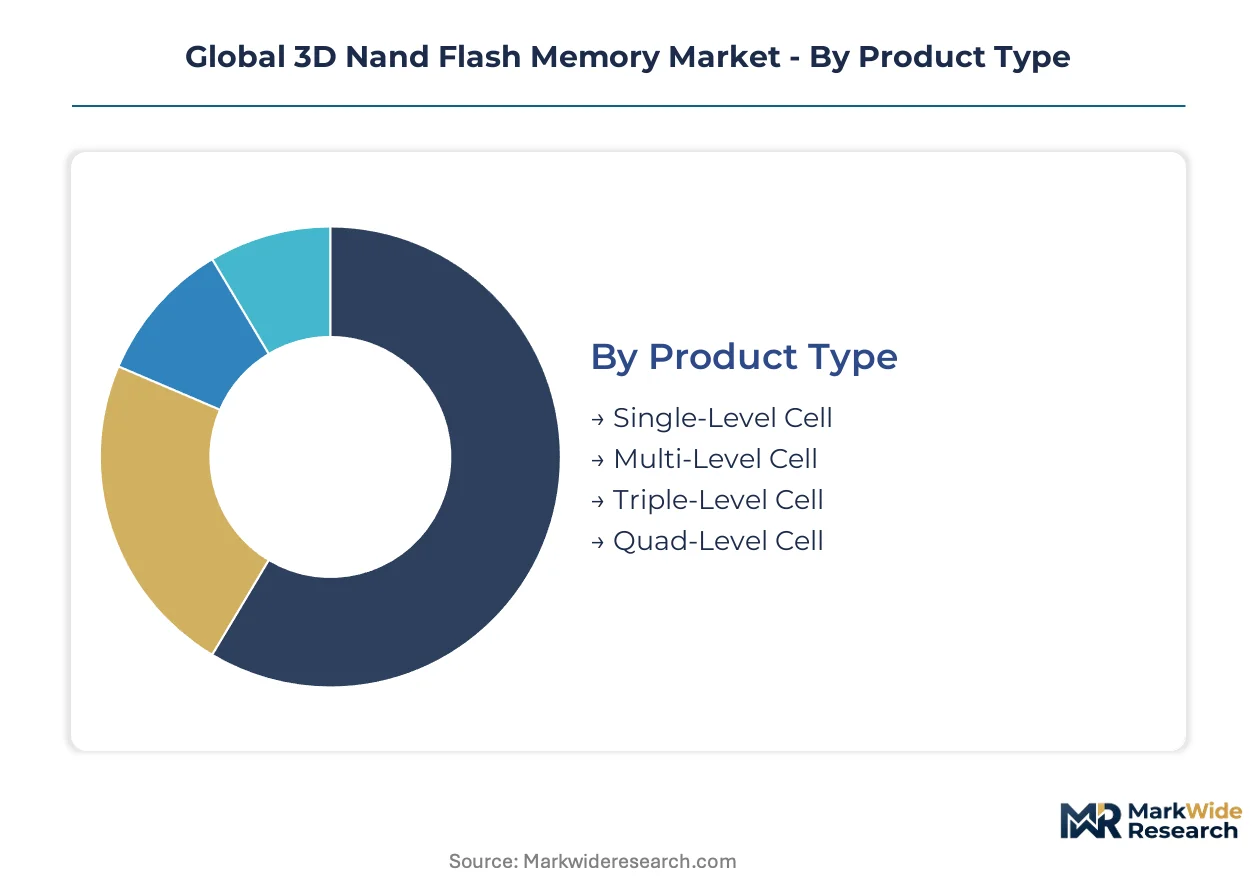
3D NAND flash memory segments diverge sharply between cost-optimized mass storage and premium endurance applications. Understanding these splits illuminates where fabs allocate layer-count investments and which cell architectures command pricing power across enterprise versus consumer procurement cycles.
Product Type:
Volume shipments concentrate in multi-bit cell configurations while single-bit cells retain margin pools in latency-sensitive workloads.
- Single-Level Cell:Each memory cell stores one bit, delivering the highest endurance and lowest latency among NAND configurations. Enterprise caching arrays in financial trading platforms and industrial control systems specify SLC for write-intensive operations where bit-error rates must stay below one per quadrillion.
- Triple-Level Cell:Three bits per cell compress cost-per-bit curves for mainstream storage applications. Data center SSD procurement teams at hyperscale operators in the United States and China specify TLC for warm-tier storage where read-heavy access patterns dominate write cycles.
- Multi-Level Cell:Two-bit cell storage balances endurance against density for mid-range enterprise and prosumer applications.
- Quad-Level Cell:Four-bit cells maximize wafer yield economics for archival and cold storage tiers where access frequency remains minimal.
Mature deployment sits with Multi-Level Cell. Newer deployment is concentrated in Quad-Level Cell.
Technology:
Charge-trap architectures are displacing floating-gate designs as layer counts exceed 176, reshaping fab equipment footprints.
- Charge Trap Flash:Silicon nitride storage layers eliminate inter-cell interference that plagued floating-gate designs at higher vertical stacks. Samsung Electronics and SK Hynix fabs in South Korea's Pyeongtaek cluster have transitioned 200-plus-layer production entirely to this architecture.
- Vertical NAND:Stacked cell strings oriented perpendicular to the wafer surface overcome planar scaling limits. This geometry enables terabit-scale die density without proportional footprint expansion, absorbing the majority of capital expenditure at leading memory foundries.
- Floating Gate:Traditional polysilicon charge storage retains presence in legacy 96-layer and 128-layer production nodes.
- Planar NAND:Horizontal cell arrangement persists in automotive and industrial segments where qualification cycles extend across decade-long supply agreements.
Established production sits with Floating Gate. Expanding deployment is concentrated in Charge Trap Flash.
Application:
Enterprise storage procurement now outpaces consumer electronics in bit-volume terms, inverting historical demand patterns.
- Solid State Drives:Enterprise and client SSD form factors absorb the majority of 3D NAND wafer output. PCIe Gen5 interface adoption in AI training clusters is pulling high-capacity modules from Samsung and SK Hynix fabs.
- Data Centers:Hyperscale storage deployments specify dense NAND modules for object storage and analytics workloads. China's MIIT localization mandates are redirecting supply chain flows toward qualified domestic module assemblers for government cloud infrastructure.
- Mobile Devices:UFS 4.0 storage in flagship smartphones demands compact BGA packages with embedded controllers.
- Consumer Electronics:Gaming consoles and portable media players specify cost-optimized storage with relaxed endurance requirements.
Volume concentration sits with Mobile Devices. Steepest expansion trajectory is concentrated in Data Centers.
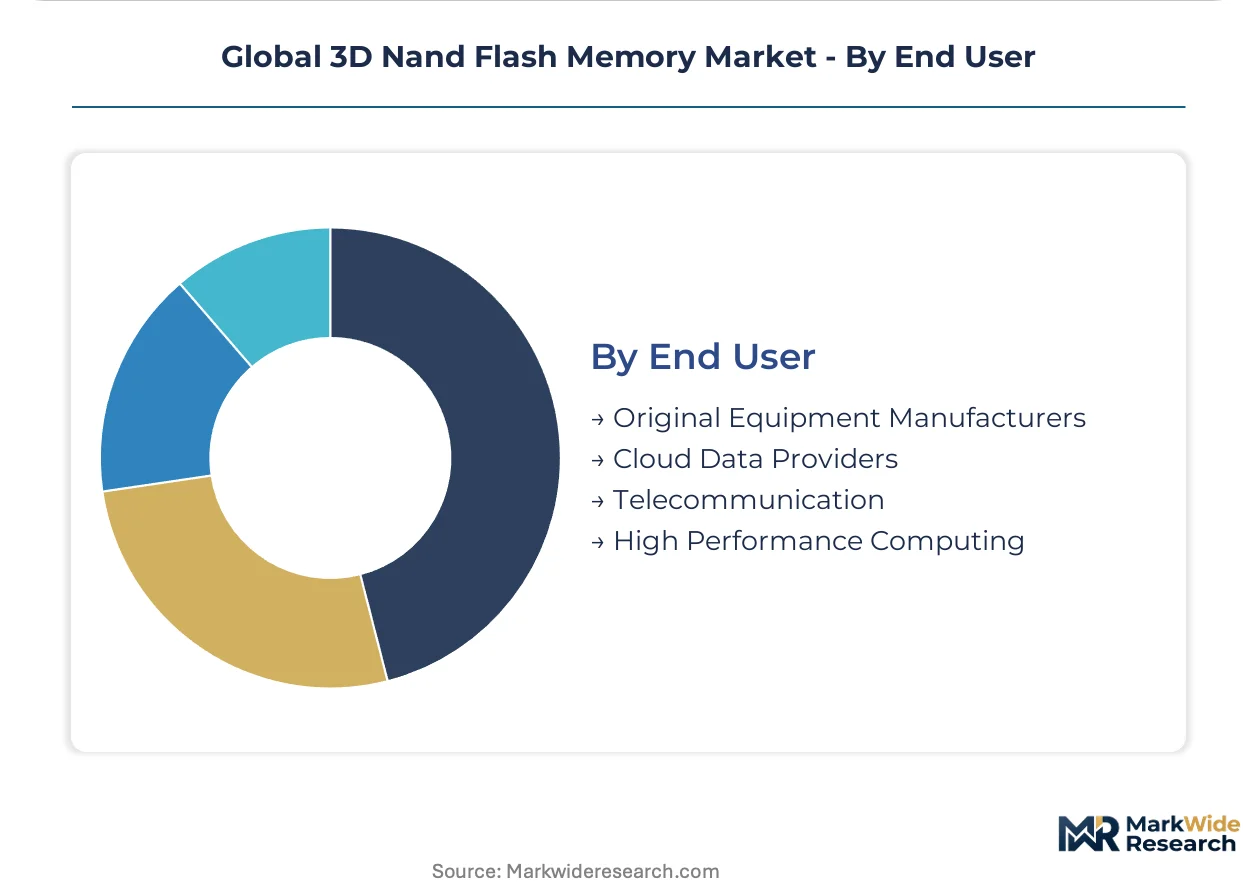
End User:
Direct fab relationships are displacing distributor channels for the largest bit consumers, compressing traditional module vendor margins.
- Cloud Data Providers:Amazon Web Services, Microsoft Azure, and Meta Platforms negotiate long-term supply agreements that bypass branded SSD vendors entirely. These operators specify raw NAND dies and custom controllers for in-house storage server integration.
- Original Equipment Manufacturers:Server and PC manufacturers specify validated NAND modules through qualified vendor lists. Dell Technologies and Hewlett Packard Enterprise maintain multi-source qualification requirements that sustain competition among Samsung, SK Hynix, and Kioxia supply lines.
- Telecommunication:5G baseband and edge computing infrastructure specify industrial-temperature NAND for outdoor deployment.
- High Performance Computing:National laboratories and research consortia procure SLC and enterprise TLC for burst-buffer storage tiers.
Traditional procurement sits with Original Equipment Manufacturers. Disintermediated procurement is concentrated in Cloud Data Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon feedstock from South Korea's Ulsan petrochemical complex anchors Asia-Pacific wafer supply chains. Fluorinated etching gases concentrate in Japanese chemical corridors around Osaka and Kitakyushu. German industrial gas suppliers feed deposition equipment across European fabs.
United States
Hyperscale data center buildouts by Amazon Web Services and Microsoft Azure pull dense NAND modules for AI training clusters. The CHIPS and Science Act directs $52 billion toward domestic semiconductor fabrication, with Micron Technology expanding DRAM and NAND capacity in Idaho and New York. Boise anchors memory design engineering while Albany-Rensselaer hosts advanced packaging research consortia.
South Korea
Pyeongtaek and Hwaseong semiconductor clusters host Samsung Electronics and SK Hynix fabs running 200-plus-layer charge-trap production. METI-aligned industrial standards govern chemical handling protocols for etching processes. The Seoul Capital Area concentrates atomic-layer deposition technician talent pools that constrain rival hiring pipelines.
China
MIIT localization mandates redirect government cloud procurement toward Yangtze Memory Technologies Company and domestic module assemblers. GB standards for electronics safety create divergent qualification pathways from Western OEM requirements. The Yangtze River Delta around Shanghai hosts packaging and testing facilities serving domestic smartphone manufacturers.
Japan
Kitakyushu and Osaka chemical suppliers produce fluorinated gases for high-aspect-ratio etch processes at Korean and Taiwanese fabs. METI coordinates joint research consortia on next-generation memory architectures. Hiroshima hosts Kioxia Corporation floating-gate legacy production serving automotive qualification cycles.
Germany
Industrial gas suppliers Linde and Air Liquide feed deposition equipment across European memory fabs with fluorinated chemistry. REACH and RoHS frameworks restrict hazardous substances in module assembly, shaping exporter qualification requirements. Dresden's Silicon Saxony cluster hosts wafer fabrication research with backward integration into equipment supply chains.
Global 3D Nand Flash Memory Market Competitive Landscape
Global majors compete with regional champions across captive etch equipment and deposition chemistry supply chains. The vendor base concentrates among vertically integrated memory foundries with in-house controller design capabilities. Three archetypes dominate: Korean conglomerates with full-stack integration, American specialists in high-performance enterprise segments, and Chinese state-backed challengers serving domestic procurement mandates. Capacity expansion and strategic partnerships constitute the primary competitive vectors as layer-count ramps compress cost curves.
Within the conglomerate tier, Samsung Electronics and SK Hynix exemplify full-stack integration from wafer fabrication through module assembly. Micron Technology occupies a position among American specialists targeting enterprise and data center procurement channels. Yangtze Memory Technologies Company represents the state-backed challenger archetype, anchoring Chinese domestic supply security objectives.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| Intel Corporation |
| Kioxia Corporation |
| Western Digital Corporation |
| Yangtze Memory Technologies Company (YMTC) |
| SanDisk Corporation |
| Transcend Information |
| Others |
Supply & Pricing Matrix
Hyperscale cloud data providers negotiating direct fab relationships have compressed traditional memory module margin structures and shifted pricing power toward vertically integrated manufacturers with captive etch equipment. This buyer concentration enables long-term contract-based offtake agreements that bypass branded SSD vendors entirely, particularly among operators in the United States and China.
Pricing Analysis
Warranty and endurance-bundling terms separate enterprise-grade SSD procurement from commodity spot purchases, with hyperscale operators typically unbundling after-sales service to optimize total cost of ownership. Three-tier pricing structure across premium SLC, standard TLC, and economy QLC levels reflects cell architecture complexity and write endurance specifications. Cost compression in QLC tiers is intensifying because planar NAND legacy substitution retains cost advantages in low-density industrial applications. Cloud data providers exhibit the highest price sensitivity due to volume scale and direct sourcing leverage, while automotive OEMs remain least sensitive given decade-long qualification cycles and reliability requirements.
Supply Chain Analysis
MIIT localization mandates and India's PLI scheme subsidies are reshaping sourcing patterns, redirecting government cloud procurement toward qualified domestic module assemblers and attracting packaging investments to serve regional smartphone and server demand. Wafer fabrication concentrates in South Korea, Japan, and the United States, with fluorinated etching gases and high-purity silicon feedstock drawing from Japanese chemical corridors and Korean petrochemical complexes. Single-source vulnerability runs through ASML extreme ultraviolet lithography scanner availability, which limits fab expansion timelines among existing high-volume manufacturers. Distribution runs through direct fab relationships for hyperscale buyers and qualified vendor lists for server and PC OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extreme ultraviolet lithography scanner scarcity constrains capacity expansion timelines, propping pricing power among existing high-volume manufacturers with established ASML equipment pipelines and compressing margin pressure on new entrants.
For Market Incumbents: Deepen backward integration into captive etch and deposition equipment supply chains to defend against emerging Chinese state-backed challengers serving MIIT localization mandates. Prioritize atomic-layer deposition technician retention in Seoul Capital Area talent pools, as specialized process engineering scarcity constrains rival hiring pipelines and sustains yield economics at 200-plus-layer production ramps. For New Entrants and Emerging Players: Begin with automotive zonal architecture storage specifications, where industrial-temperature NAND requirements for software-defined vehicles create qualification pull with less entrenched incumbent presence. Target India's electronics manufacturing incentive zones for module assembly and testing investments, leveraging PLI scheme subsidies to establish domestic packaging capabilities serving regional smartphone demand. For Investors and Strategic Acquirers: The window for entry favors deposition chemistry specialists with green chemistry certifications aligned to EU REACH frameworks. Long-term viability hinges on qualification status with European OEM customers reformulating cleaning chemistries for NAND fabrication. Monitor layer-count transition announcements from Pyeongtaek and Hwaseong clusters as inflection indicators for supply availability and pricing trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion at Leading Fabs | Samsung and SK Hynix layer-count ramps absorb capital expenditure and compress cost-per-bit curves. |
| Backward Integration into Etch Equipment | Captive deposition chemistry supply chains reduce fluorinated gas sourcing constraints from Japanese suppliers. |
| Green Chemistry Certification Program | REACH alignment opens preferential procurement pathways for European data center operators. |
| Long-term Supply Agreement Negotiation | Direct fab relationships with AWS and Microsoft Azure bypass traditional memory module margin structures. |
| Joint Venture for Domestic Assembly | India PLI scheme partnerships establish regional packaging capabilities serving smartphone manufacturers. |
Research Methodology
Independent corroboration across semiconductor fabrication executives, data center procurement officers, and deposition equipment engineers underwrites the qualitative findings, validated against customs and trade data, SEC 10-K filings, and hyperscaler capex disclosures. Bottom-up triangulation across wafer output estimates and top-down validation through memory module shipment aggregations anchor the analytical framework.
Comparable-period anchoring to historical layer-count ramp cycles and yield improvement trajectories informs projections across the analysis window, with segmentation modeling across cell architecture type, layer-count tier, application segment, and regional procurement cluster. CAGRs derive from supply-demand balance assessments incorporating fab capacity schedules and technology transition timelines, with AI server memory bundling ratios and MIIT localization compliance rates serving as key forecast inputs.
Underlying measurement precision varies by segment; charge-trap flash production volumes carry tighter precision than floating-gate legacy estimates given disclosure practices at Korean foundries. Forecasts reflect assumptions regarding scanner delivery schedules, etching chemistry supply stability, and regulatory enforcement intensity across divergent compliance pathways. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Powered Storage Devices Market
Data Storage
North America SSD Caching Market
Data Storage
Data Center Storage Solutions Market
Data Storage
Data Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Solid State Array Market
Data Storage
Next Generation Data Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Storage Virtualization Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Global Portable Data Storage Market
Data Storage
Japan Data Center Storage Market
Data Storage
NOR Flash Market
Data Storage
USB Key Market
Data Storage
Hardware Storage Market
Data Storage
Data Storage Devices Market