
 Global Whole Slide Imaging Market | 2026-2036
Global Whole Slide Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Whole Slide Imaging Market Foresight
The capital-intensity divergence between high-throughput scanner manufacturers and software-centric analytics providers is redrawing competitive boundaries in whole slide imaging. Hamamatsu Photonics leverages its photomultiplier tube heritage to dominate fluorescence scanning architectures. Leica Biosystems anchors its position through backward integration into histology workflows and companion staining systems. Visiopharm differentiates via AI-powered quantitative pathology algorithms that command premium pricing from pharmaceutical clients.
Whole slide imaging digitizes glass pathology specimens at sub-micron resolution, typically 20x or 40x optical magnification, producing multi-gigapixel files for diagnostic review and computational analysis. Its primary purpose is enabling remote diagnosis, archival retrieval, and algorithmic tissue quantification that manual microscopy cannot replicate. Brightfield imaging occupies the largest installed base due to routine hematoxylin-and-eosin diagnostic prevalence, while fluorescence imaging captures the fastest expansion as multiplexed biomarker panels proliferate in immuno-oncology trials. Automated slide scanners concentrate margin pools at the hardware layer, though software solutions and image management systems extract recurring revenue through subscription licensing to diagnostic laboratories and contract research organizations.
FDA regulates whole slide imaging systems as Class II or Class III medical devices under 21 CFR requirements, while the EU Medical Device Regulation mandates notified body certification for clinical diagnostic deployment in Europe. ISO 15189 accreditation standards for medical laboratories shape procurement specifications across both jurisdictions. Stakeholders must monitor evolving reimbursement codes for digital pathology services and preemptive compliance with anticipated FDA guidance on AI-assisted diagnostic algorithms.
Market Dynamics
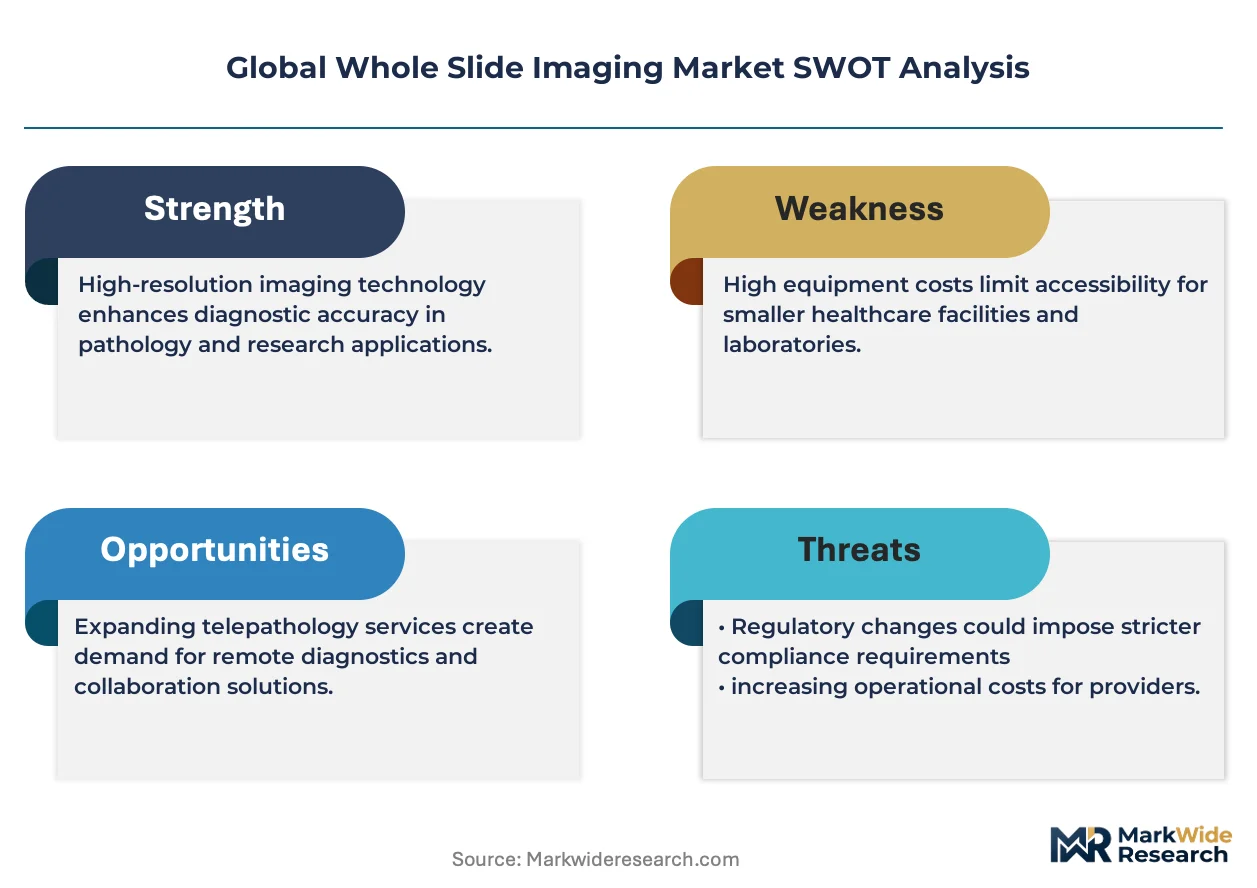
Scanner hardware commoditization is compressing margins at the device layer while AI-powered image analytics extract premium recurring revenue from pharmaceutical and diagnostic laboratory clients.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated premarket notification pathways for digital pathology devices reduce commercial entry timelines in the United States.
- Multiplexed biomarker proliferation:Immuno-oncology trials drive fluorescence imaging adoption for spatial biology applications.
- Centralized laboratory networks:Germany's consolidated diagnostic infrastructure generates procurement volume at scale for high-throughput scanning systems.
Market Restraints
- Capital intensity concentration:High-resolution scanner production requires precision optical component supply chains concentrated in East Asian manufacturing clusters.
- File storage infrastructure costs:Multi-gigapixel whole slide images demand enterprise-grade data architecture investments that constrain mid-sized pathology laboratories.
- Interoperability friction:Proprietary image formats from competing scanner vendors complicate cross-platform diagnostic workflows.
Strategic Opportunities
- AI algorithm reimbursement codes:Anticipated CPT coding expansions for computational pathology services in the United States create recurring revenue potential.
- Remote pathology networks:Academic medical centers in India and Brazil present underpenetrated demand for telepathology consultation infrastructure.
- Cloud-native image management:Subscription-based SaaS platforms displace on-premise storage systems in European contract research organizations.
Industry Challenges
- Computational pathology talent scarcity:Cross-trained professionals possessing both histopathology expertise and machine learning engineering skills command compensation premiums that strain laboratory budgets.
- ISO 15189 accreditation timelines:Medical laboratory certification processes for digital pathology workflows extend 12-18 months in European notified body jurisdictions.
- Legacy microscope integration complexity:Hybrid environments requiring simultaneous analog and digital diagnostic capabilities complicate training protocols and quality assurance standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Whole Slide Imaging Market |
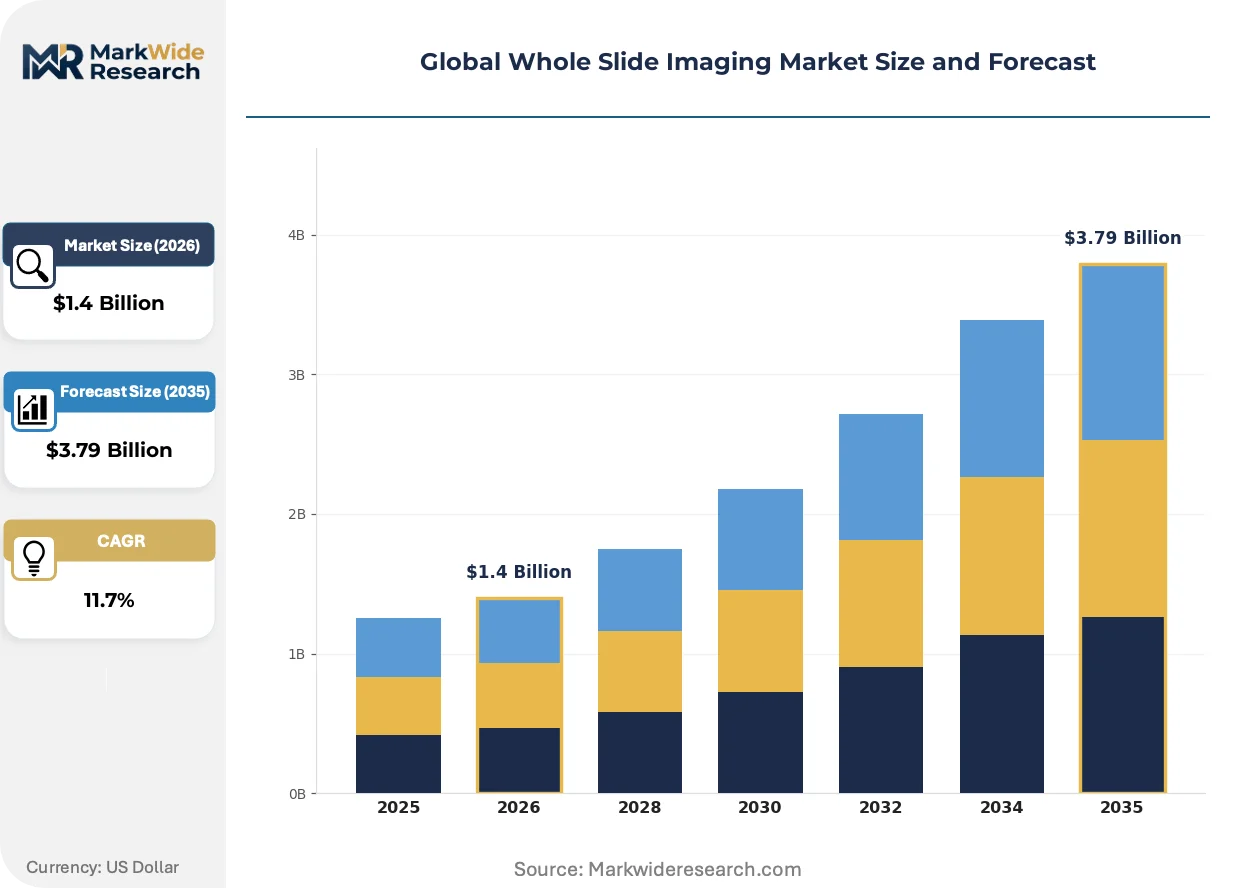
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Brightfield Imaging, Fluorescence Imaging, Confocal Microscopy, Multispectral Imaging, Digital Holography Application: Pathology Diagnosis, Research & Development, Education & Training, Drug Discovery, Biobanking End User: Diagnostic Laboratories, Academic Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Product Type: Automated Slide Scanners, Semi-Automated Slide Scanners, Manual Scanners, Software Solutions, Image Management Systems |
| Companies Covered | 3DHISTECH, Hamamatsu Photonics, Koninklijke Philips, Olympus Corporation, Nikon Corporation, Leica Biosystems, Roche, Visiopharm, Indica Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Whole Slide Imaging Market Shifts & Advancements
Fluorescence multiplexing architectures and cloud-based computational platforms are restructuring how tissue specimens are digitized, analyzed, and reimbursed across diagnostic and research applications.
Multispectral imaging technology is bifurcating the installed base between routine brightfield hematoxylin-and-eosin diagnostics and advanced immuno-oncology biomarker quantification. Pharmaceutical sponsors now require seven-to-nine-plex fluorescence panels for companion diagnostic development, compressing single-channel scanner demand in contract research segments. This capability split is forcing hardware manufacturers to defend position through modular optical upgrades rather than full-system replacement cycles.
EU Medical Device Regulation notified body certification timelines are extending market entry durations for new digital pathology platforms in Europe. Manufacturers must demonstrate clinical validation across multiple pathology subspecialties to satisfy MDR Class IIa requirements. Diagnostic laboratories in France and Germany are responding by consolidating procurement around established vendors with existing CE marking rather than onboarding novel scanner entrants.
Pathology service contracts are unbundling hardware acquisition from image analysis software licensing. Academic medical centers in the United States now favor subscription-based computational pathology platforms with per-slide pricing over capital-intensive scanner purchases. This consumption-pattern shift is most visible in oncology departments where AI-assisted quantification drives reimbursement rather than device ownership.
Global Whole Slide Imaging Market Segmentation
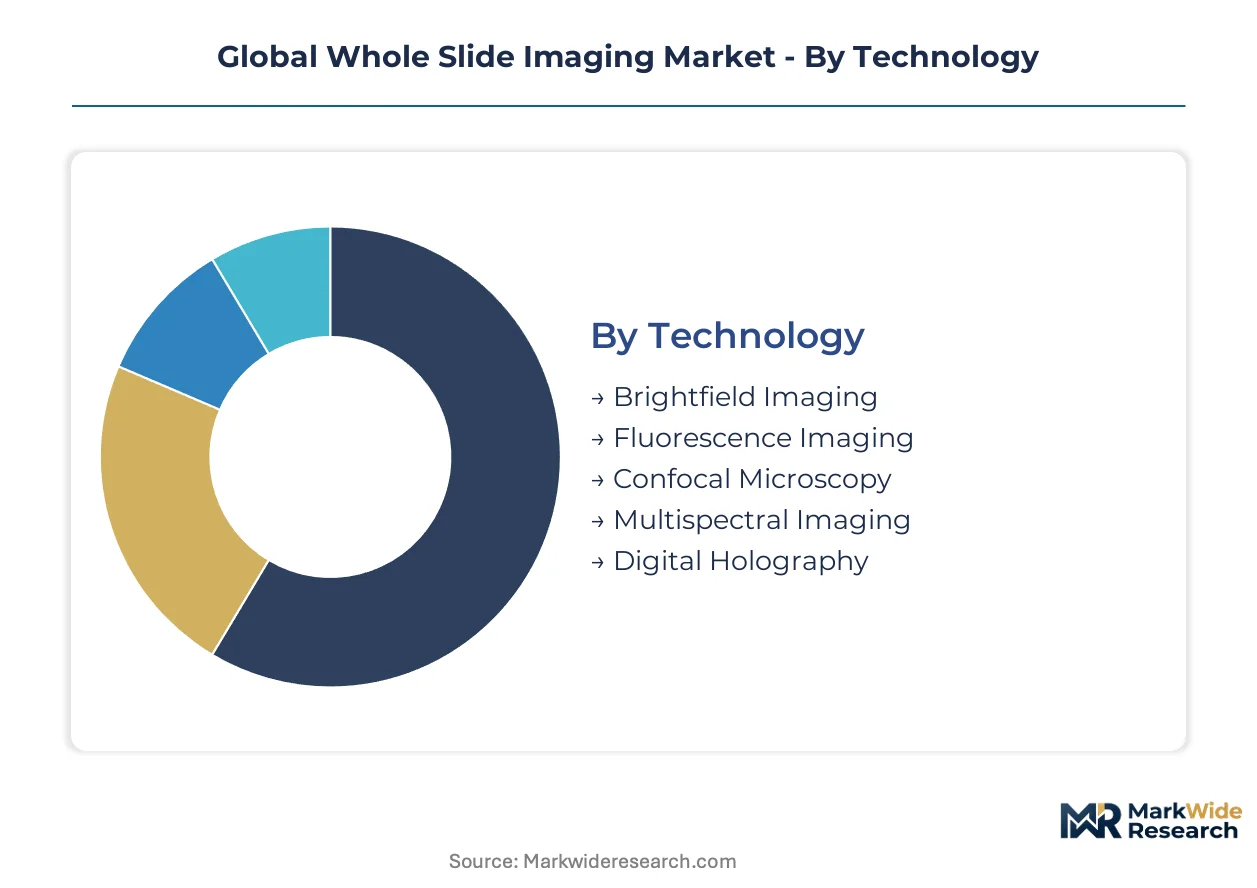
Segmentation in whole slide imaging reveals how value migrates from hardware commoditization toward software-enabled recurring revenue. Technology choice determines optical architecture investments, while end-user concentration shapes go-to-market economics across diagnostic and research channels.
Technology:
Margin pools concentrate in fluorescence architectures serving pharmaceutical multiplexing requirements, while brightfield systems compete on throughput scale.
- Brightfield Imaging:Standard hematoxylin-and-eosin capture at 20x-40x magnification dominates routine diagnostic workflows. Academic medical centers in the United States deploy these systems for high-volume surgical pathology, constrained by storage infrastructure costs for multi-gigapixel files.
- Fluorescence Imaging:Multi-channel excitation enables simultaneous biomarker detection across seven-to-nine-plex panels. Contract research organizations in Germany drive procurement for immuno-oncology companion diagnostic development, where spatial biology quantification commands premium pricing.
- Confocal Microscopy:Optical sectioning eliminates out-of-focus blur for thick tissue specimens.
- Multispectral Imaging:Spectral unmixing separates overlapping fluorophore signals in complex tissue microenvironments.
- Digital Holography:Label-free quantitative phase imaging captures refractive index variations without staining protocols.
The dominant share belongs to Brightfield Imaging, while Fluorescence Imaging is closing the gap fastest.
Application:
Revenue concentration shifts from fee-for-service diagnostics toward pharmaceutical-sponsored research quantification.
- Pathology Diagnosis:Primary diagnostic review of digitized specimens for remote consultation and archival retrieval. Centralized laboratory networks in Germany procure high-throughput systems at scale, though FDA 510(k) clearance timelines delay commercial entry for novel platforms.
- Drug Discovery:AI-powered tissue quantification for efficacy biomarker validation in clinical trials. Biotechnology firms in Switzerland pay subscription premiums for computational pathology algorithms that manual scoring cannot replicate.
- Research & Development:Exploratory tissue analysis in academic and industrial settings.
- Education & Training:Digital slide repositories replacing physical glass collections in medical curricula.
- Biobanking:Longitudinal specimen digitization for retrospective molecular studies.
Pathology Diagnosis holds the largest installed base, yet Drug Discovery is expanding most quickly as pharmaceutical pipelines demand spatial transcriptomics integration.
End User:
Procurement authority fragments between capital-constrained hospital laboratories and research-budget-rich pharmaceutical sponsors.
- Diagnostic Laboratories:High-volume clinical testing facilities requiring ISO 15189 accredited workflows. Consolidated networks in France favor established vendors with existing CE marking under EU Medical Device Regulation, extending procurement cycles.
- Pharmaceutical Companies:Sponsor-driven demand for standardized biomarker quantification across multi-site trials. Firms in the United States unbundle hardware from software, preferring per-slide pricing for AI-assisted analysis over scanner ownership.
- Academic Institutions:Teaching hospitals and research universities with hybrid analog-digital environments.
- Biotechnology Firms:Emerging drug developers outsourcing tissue analytics to specialized providers.
- Contract Research Organizations:Multi-site service providers managing global trial logistics.
Diagnostic Laboratories command the greatest hardware volume, though Pharmaceutical Companies are gaining share fastest through computational pathology subscriptions.
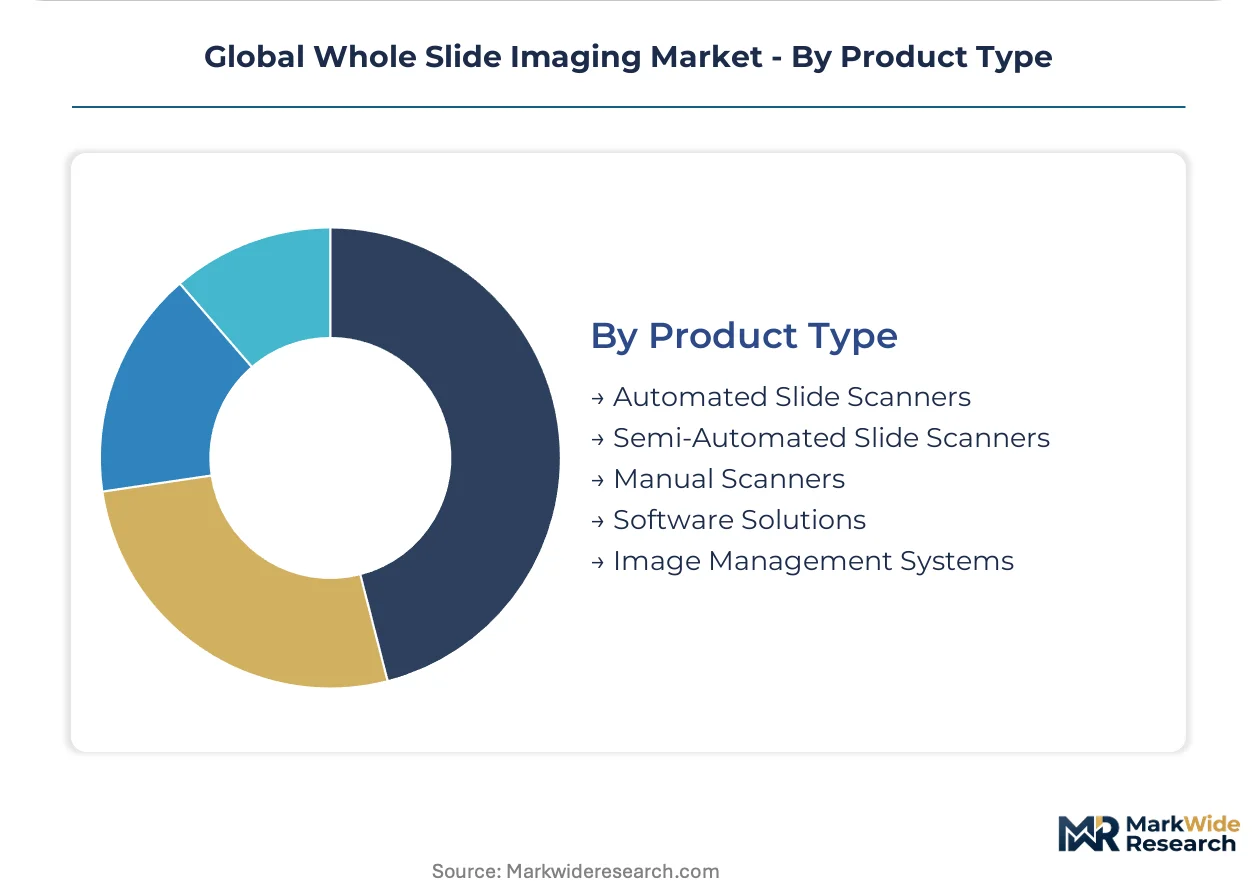
Product Type:
Value capture bifurcates between depreciating scanner assets and recurring software license revenue.
- Software Solutions:AI-powered image analysis platforms with algorithmic quantification capabilities. Cloud-native deployments in European contract research organizations displace on-premise installations, generating subscription renewal streams.
- Automated Slide Scanners:High-throughput hardware with robotic loading and batch processing. Precision optical component supply chains in East Asian manufacturing clusters constrain margin expansion despite volume scale.
- Semi-Automated Slide Scanners:Mid-tier systems balancing throughput with capital expenditure constraints.
- Manual Scanners:Entry-level devices for low-volume or specialized applications.
- Image Management Systems:Enterprise storage and retrieval infrastructure for multi-terabyte archives.
Automated Slide Scanners retain the dominant revenue share, while Software Solutions are climbing the fastest as laboratories prioritize algorithmic capability over hardware acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in whole slide imaging software exports, offsetting scanner hardware import dependence from East Asian optical component clusters. Germany and Switzerland anchor European value capture through precision manufacturing and pharmaceutical software integration. China and India represent the fastest-expanding demand frontiers, though domestic production capabilities remain concentrated in assembly and distribution.
United States
FDA 510(k) clearance pathways for digital pathology devices accelerate commercial entry timelines for scanner manufacturers. Academic medical centers in Boston and Stanford drive procurement for AI-powered image analysis platforms with per-slide pricing models. The Greater Boston corridor concentrates computational pathology talent pools, straining laboratory budgets with cross-trained professional compensation premiums.
Germany
Centralized laboratory networks in Bavaria and North Rhine-Westphalia generate procurement volume at scale for high-throughput scanning systems. EU Medical Device Regulation notified body certification mandates clinical validation across multiple pathology subspecialties, extending market entry durations. The Rhine-Ruhr metropolitan region anchors European demand for fluorescence imaging architectures serving pharmaceutical multiplexing requirements.
China
NMPA medical device registration requirements shape commercial entry pathways for foreign scanner manufacturers seeking domestic market access. Tier-one hospitals in Beijing and Shanghai deploy whole slide imaging for remote pathology consultations across provincial networks. The Yangtze River Delta manufacturing corridor supplies precision optical components to global scanner assembly operations.
India
Academic medical centers in Maharashtra and Karnataka present underpenetrated demand for telepathology consultation infrastructure. CDSCO medical device regulations govern import and distribution of digital pathology platforms for clinical diagnostic deployment. The Hyderabad-Bengaluru corridor concentrates contract research organization activity, driving subscription-based software licensing for pharmaceutical biomarker quantification.
Switzerland
Swissmedic certification requirements for clinical diagnostic devices reinforce procurement consolidation around established vendors with existing quality management systems. Biotechnology firms in Basel pay subscription premiums for computational pathology algorithms that manual scoring cannot replicate. The Basel-Zürich corridor anchors European pharmaceutical-sponsored research quantification demand.
Global Whole Slide Imaging Market Competitive Landscape
Concentration sits with diversified life sciences conglomerates and precision optics specialists rather than pure-play software entrants. The vendor base separates into three strategic tiers: integrated histology workflow providers, photonics heritage manufacturers, and AI-native analytics specialists. M&A activity targets computational pathology algorithm portfolios, while strategic partnerships bridge hardware commoditization with recurring software revenue streams.
Among photonics heritage manufacturers, Hamamatsu Photonics exemplifies optical component backward integration into fluorescence scanning architectures. Leica Biosystems and Roche occupy positions within integrated histology workflow tiers, anchoring competitive positioning through companion staining system control. Visiopharm represents the AI-native analytics archetype, commanding premium positioning from pharmaceutical clients for quantitative pathology algorithms.
| Leading Market Players |
|---|
| 3DHISTECH |
| Hamamatsu Photonics |
| Koninklijke Philips |
| Olympus Corporation |
| Nikon Corporation |
| Leica Biosystems |
| Roche |
| Visiopharm |
| Indica Labs |
| Others |
Supply & Pricing Matrix
Scanner throughput scale in East Asian manufacturing clusters concentrates optical component supply and sets price floors for high-resolution systems. German laboratory networks and United States academic medical centers absorb premium pricing for FDA-cleared and CE-marked devices, while mid-tier buyers face cost compression from file storage infrastructure demands.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing for AI-powered image analysis platforms, separating premium algorithm tiers from standard brightfield scanning packages. Price differentiation rests on FDA 510(k) clearance status and ISO 15189 accreditation level, with pharmaceutical sponsors showing lowest sensitivity to per-slide fees. Cost compression in automated slide scanner hardware intensifies as East Asian optical component suppliers achieve manufacturing scale, while diagnostic laboratories remain most price-constrained by enterprise storage architecture investments.
Supply Chain Analysis
Just-in-time inventory strategies dominate scanner assembly operations, though strategic stockpiling of precision optical components buffers against single-source vulnerability in photomultiplier tube supply. Manufacturing concentrates in Japan, Germany, and China, drawing from specialized glass substrates, high-NA objective lenses, and CMOS sensor arrays. Tariff exposure on East Asian electronic components presents structural risk. Distribution runs through authorized dealer networks serving hospital systems and direct procurement channels for pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-trained professionals commanding histopathology expertise alongside machine learning engineering skills represent the critical bottleneck constraining laboratory expansion and algorithm deployment velocity.
For Market Incumbents: Shield recurring revenue streams in pharmaceutical software subscriptions by deepening backward integration into fluorescence optical architectures. Prioritize modular hardware upgrades over full-system replacement to defend against scanner commoditization. Accelerate FDA 510(k) clearance pipelines for AI-assisted diagnostic algorithms before anticipated CPT coding expansions create competitive gates. For New Entrants and Emerging Players: Anchor in underpenetrated telepathology infrastructure across academic medical centers in Maharashtra and Karnataka, India, where CDSCO regulatory pathways remain less congested than FDA or EU MDR timelines. Target cloud-native image management SaaS for European contract research organizations seeking subscription displacement of on-premise storage systems. Lead with per-slide pricing models that unbundle hardware acquisition from computational pathology capability. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-native analytics specialists serving immuno-oncology trial sponsors with seven-to-nine-plex fluorescence quantification platforms. Long-term viability favors algorithm portfolios with demonstrated pharmaceutical client retention and regulatory validation across multiple pathology subspecialties. Monitor FDA guidance publication timelines on AI-assisted diagnostic algorithms as the signal for reimbursement code expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Regulatory Submission | FDA 510(k) clearance for computational pathology platforms unlocks CPT reimbursement expansion in United States diagnostic networks. |
| Cloud-Native Platform Migration | SaaS image management displaces on-premise storage in European contract research organizations, generating subscription renewal streams. |
| Modular Optical Architecture Upgrade | Fluorescence multiplexing capabilities extend hardware lifecycle for pharmaceutical companion diagnostic development programs. |
| Academic Medical Center Partnership | Telepathology infrastructure deployment in India and Brazil captures underpenetrated remote consultation demand. |
| CE Marking Pathway Investment | EU MDR notified body certification accelerates market entry for digital pathology platforms in consolidated German laboratory networks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with pathology department directors, biomedical engineers, pharmaceutical biomarker scientists, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body certification records, CMS Medicare reimbursement databases, and hospital procurement contracts. Bottom-up scanner shipment tracking and top-down pharmaceutical R&D spend analysis enabled cross-verification.
Across the analysis window, projections integrated technology segmentation by optical architecture, application split between diagnostic and drug discovery channels, and end-user concentration across laboratory networks and pharmaceutical sponsors. CAGRs derived from installed base growth rates and per-unit revenue trajectories, incorporating ISO 15189 accreditation timeline assumptions and anticipated AI algorithm reimbursement code expansions as scenario inputs.
Decision-makers should treat outputs as directional under base assumptions of FDA clearance pathway stability and EU MDR certification timeline continuity; material deviation in either regulatory trajectory would warrant model refresh. Revision becomes warranted when pharmaceutical sponsor unbundling of hardware from software accelerates beyond projected velocity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Photoacoustic Tomography Market
Imaging
Mobile Imaging Services Market
Imaging
Fiducial Markers Market
Imaging
US Near Infrared Imaging Market
Imaging
Frame Grabber Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Semiconductor Microscopes Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Holographic Imaging Market
Imaging
Multi Camera System Market
Imaging
High-Speed Camera Market
Imaging
Light Field Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Global Mobile Image Sensor Market
Imaging
Printed Image Sensors Market