
 Aerosol Printing and Graphics Market | 2026-2036
Aerosol Printing and Graphics Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Printing and Graphics Market Outlook
EU F-Gas Regulation and REACH compliance deadlines are restructuring procurement criteria across European packaging and coating supply chains. Ball Corporation leverages its aluminum aerosol manufacturing scale to dominate North American beverage and personal care can markets. Crown Holdings anchors European demand through specialized metal decorating lines serving premium cosmetic brands. Optomec Inc. differentiates via directed energy deposition systems that enable functional electronics printing on curved aerosol substrates.
Aerosol printing and graphics encompasses the deposition of pigmented or functional materials through pressurized propellant systems onto metal, plastic, glass, or textile surfaces, typically achieving dry film thicknesses of 15–50 microns in single-pass operations. The technology serves industrial marking, decorative finishing, and protective coating applications where substrate geometry or mobility precludes conventional roll-to-roll or screen methods. Functional Coatings command the dominant value share due to anti-corrosion and conductive formulations required in automotive underhood and electronics shielding segments. Specialty Inks represent the fastest-expanding category as conductive and luminescent formulations penetrate smart packaging and printed sensor applications. Decorative Sprays retain volume leadership in home decor and artisan retail channels where color-matching breadth and ease of application sustain repeat purchase behavior.
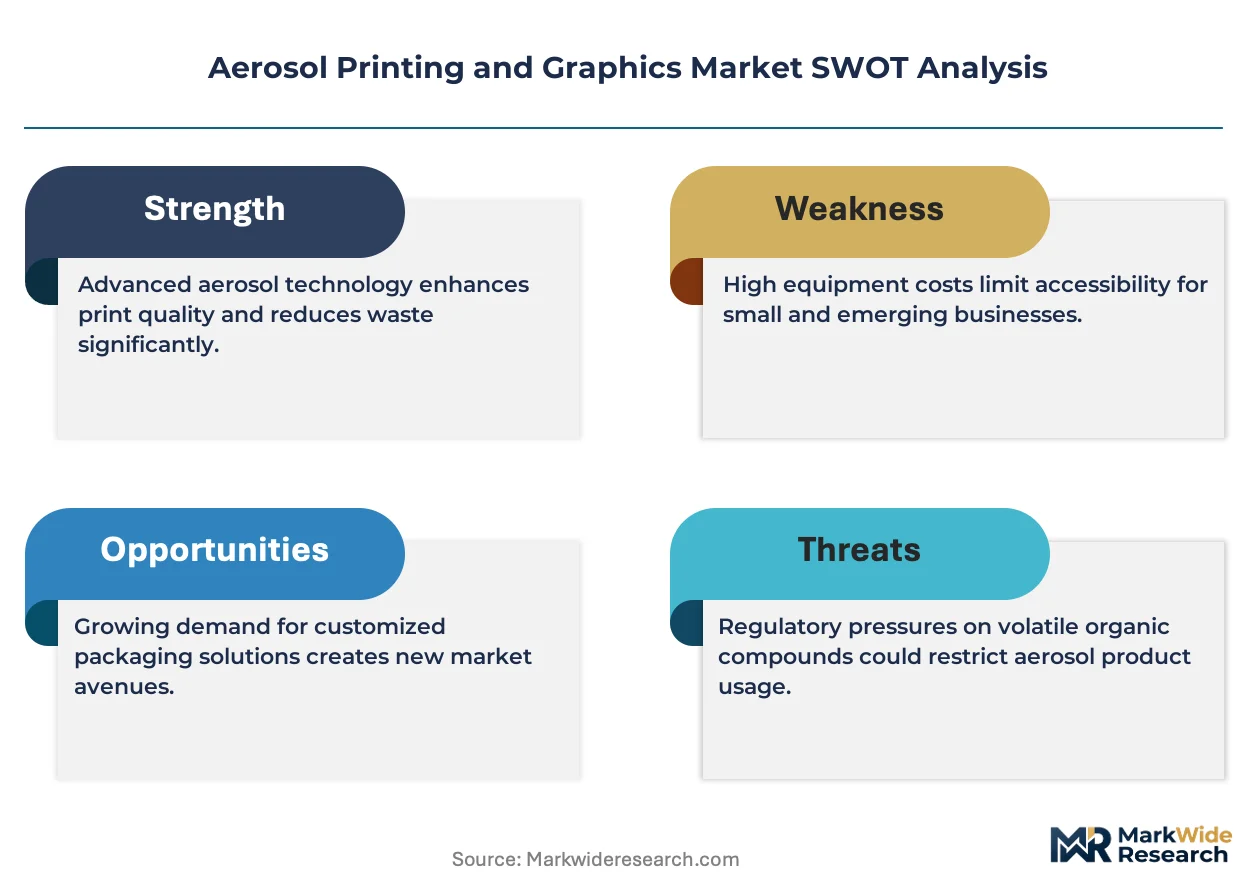
EPA National Emission Standards for Hazardous Air Pollutants and REACH Annex XVII restrictions on volatile organic compounds are forcing reformulation investments across propellant and resin suppliers. FDA indirect food contact regulations and EU Packaging and Packaging Waste Directive shape substrate selection and recyclability claims for aerosol-printed containers. Stakeholders must monitor evolving state-level extended producer responsibility laws and biobased content mandates that will determine which coating chemistries and substrate combinations retain market access across major economies.
Market Dynamics
Waterborne solvent mandates from EPA and REACH are compressing formulation timelines while automotive refinishing shops consolidate purchasing power around OEM-certified coating systems. This regulatory-pressure-plus-buyer-concentration dynamic is redrawing competitive boundaries between commodity suppliers and technical specialists.
Growth Catalysts
- REACH Annex XVII VOC limits:European coating formulators are accelerating low-VOC aerosol development to meet compliance deadlines, creating first-mover advantages for compliant suppliers.
- Automotive refinishing certification tiers:OEM repair standards in Germany and the United States are mandating premium functional coatings for warranty-compliant collision repair.
- Conductive ink formulations:Printed sensor applications in smart packaging are pulling luminescent and conductive specialty inks into high-volume production.
Market Restraints
- Propellant cost volatility:Hydrocarbon and dimethyl ether feedstock prices fluctuate with petrochemical cycles, squeezing margin stability for mid-tier formulators.
- Aluminum can supply concentration:North American beverage and personal care can manufacturing clusters around Ball Corporation's production footprint, creating single-source vulnerability.
- Substrate geometry limits:Deep-drawn or highly curved metal surfaces exceed standard aerosol transfer efficiency thresholds, restricting application range.
Strategic Opportunities
- India industrial coating corridors:Automotive manufacturing clusters in Pune and Chennai remain underpenetrated by premium functional aerosol suppliers.
- Extended producer responsibility mandates:EU Packaging and Packaging Waste Directive recyclability requirements favor aluminum aerosol formats over plastic alternatives.
- Directed energy deposition convergence:Optomec's functional electronics printing systems enable circuit deposition on curved aerosol substrates previously unreachable by screen or inkjet methods.
Industry Challenges
- Formulation chemist scarcity:Low-VOC resin and propellant expertise resides in a narrow talent pool concentrated in German and Swiss industrial coating clusters.
- Dual certification timelines:FDA indirect food contact clearance combined with EPA NESHAP compliance extends product launch cycles for aerosol-printed beverage containers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Printing and Graphics Market |
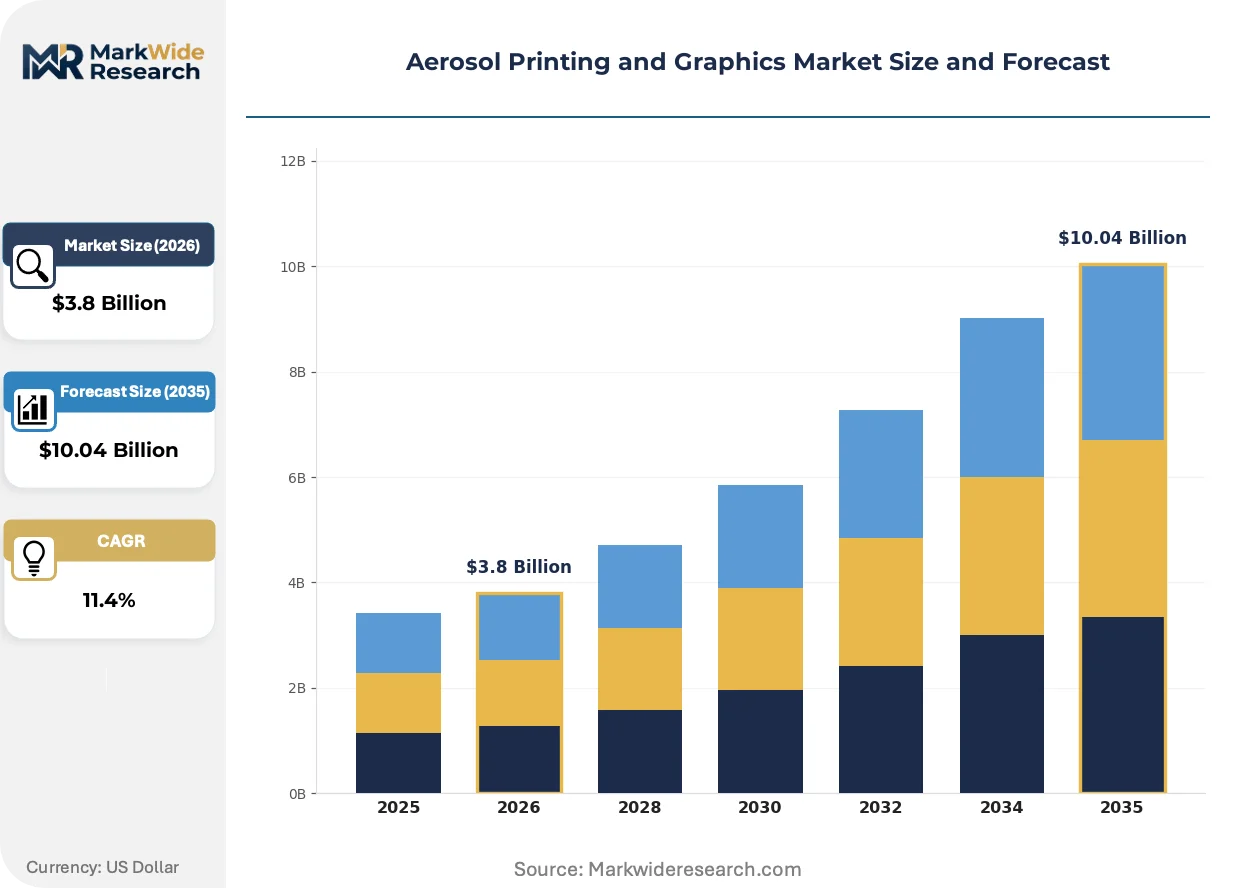
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Sprays, Functional Coatings, Specialty Inks, Transparent Coatings Application: Automotive Finishing, Textile Printing, Industrial Marking, Home Decor End User: Manufacturers, Artists, DIY Enthusiasts, Retail Brands Technology: Electrostatic Spray, Conventional Spray, Airless Spray, Air-Assisted Spray |
| Companies Covered | Amcor, Ball Corporation, Crown Holdings, CCL Industries, WestRock, Ardagh Group, Optomec Inc., Montebello Packaging, EXAL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Printing and Graphics Market Strategic Shifts
Formulation chemistry, regulatory compliance architecture, and buyer procurement models are simultaneously transforming how aerosol printing systems reach end-use markets. These shifts favor suppliers capable of integrating technical service with regulatory navigation.
Waterborne polyurethane-acrylic hybrid resins are absorbing the functional requirements previously met by solvent-borne alkyd systems in automotive underhood applications. Tier-1 automotive suppliers in Stuttgart and Detroit are qualifying these formulations for corrosion-resistant marking. The technology is absorbing market share from conventional solvent systems by delivering equivalent salt-spray performance at sub-250 g/L VOC content.
EPA National Emission Standards for Hazardous Air Pollutants are forcing capital deployment into enclosed spray booth and recovery systems across North American refinishing operations. Collision repair chains face equipment retrofit costs or facility relocation to meet ambient air monitoring thresholds. The regulatory burden falls heaviest on independent refinishing shops in California and Texas, many of which are consolidating into MSO networks to amortize compliance infrastructure.
Refinishing shop procurement has consolidated around single-source coating agreements tied to OEM certification status. Large multi-shop operators in Germany and the United States now specify approved supplier lists that exclude non-certified formulators regardless of price position. This behavioral shift is most visible in the German KBA certification framework, where uncertified suppliers have lost access to Volkswagen and BMW authorized repair networks.
Aerosol Printing and Graphics Market Segmentation
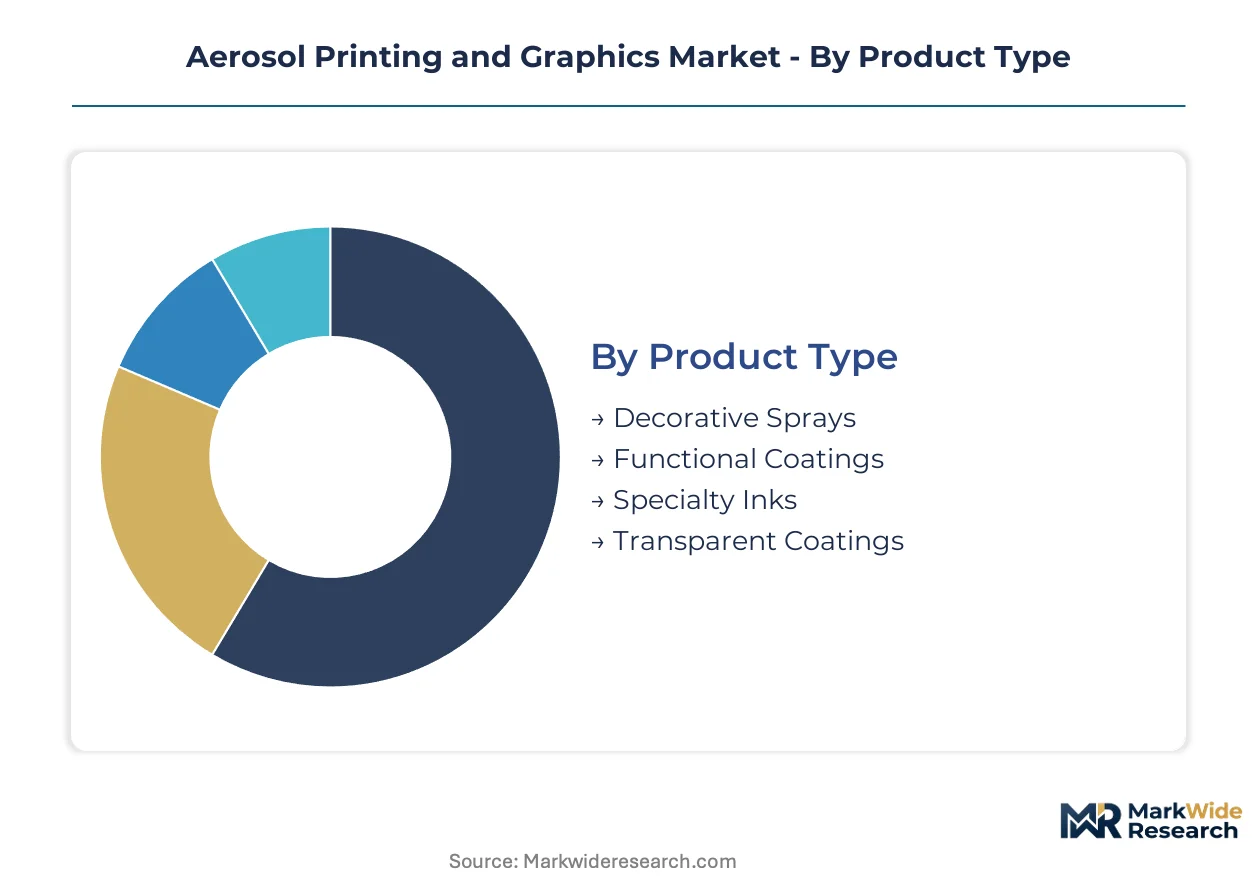
Segmentation in aerosol printing and graphics reveals how formulation chemistry, substrate compatibility, and regulatory compliance intersect to determine supplier profitability. Buyers sort across product types by VOC tolerance thresholds and across applications by geometry complexity and durability requirements.
Product Type:
Supply concentration in low-VOC resin manufacturing concentrates procurement leverage among German and Swiss formulators capable of REACH-compliant hybrid systems.
- Functional Coatings:Anti-corrosion and conductive formulations based on waterborne polyurethane-acrylic hybrids deliver salt-spray resistance for automotive underhood and electronics shielding. Demand concentrates in Stuttgart and Detroit automotive clusters where OEM certification mandates premium specifications.
- Specialty Inks:Luminescent and conductive formulations enable printed sensor applications in smart packaging and curved electronics substrates. Smart packaging converters in Germany and the United States are pulling these formulations into high-volume production.
- Decorative Sprays:Pigmented alkyd and acrylic systems serve home decor and artisan retail channels where color-matching breadth sustains repeat purchase behavior.
- Transparent Coatings:Protective clearcoats for metal, glass, and plastic substrates prioritize UV resistance and scratch durability in industrial and consumer applications.
Functional Coatings absorb the bulk of installed capacity; Specialty Inks are expanding most quickly.
Application:
Cost tier differentiation separates premium OEM-certified refinishing from commodity decorative applications, with certification status determining margin capture.
- Automotive Finishing:Collision repair and refinishing operations require corrosion-resistant marking and color-matched coatings meeting KBA and manufacturer certification standards. German and United States multi-shop operators now specify approved supplier lists that exclude non-certified formulators.
- Industrial Marking:Durable identification and safety labeling on metal, plastic, and glass surfaces demands chemical and abrasion resistance for manufacturing and logistics environments.
- Textile Printing:Fabric-compatible aerosol formulations enable direct-to-garment applications where substrate flexibility and wash durability compete with screen and digital alternatives.
- Home Decor:Consumer-facing decorative finishing for furniture, fixtures, and craft applications prioritizes ease of application and color variety over industrial performance specifications.
Automotive Finishing commands the highest value per liter; Industrial Marking offers the steadiest volume baseline.
End User:
Volume concentration among large manufacturers contrasts with fragmentation across artists and DIY enthusiasts, reshaping distribution channel economics.
- Manufacturers:Tier-1 automotive suppliers and industrial coating operations purchase through certified distributor networks with technical service requirements.
- Retail Brands:Private-label and co-manufacturing arrangements for beverage, personal care, and cosmetic aerosol containers.
- DIY Enthusiasts:Home improvement and craft hobbyists purchasing through mass retail and e-commerce channels.
- Artists:Professional and amateur creators requiring specialized color ranges and substrate compatibility for fine art and commercial projects.
Manufacturers generate the largest order values; Retail Brands are consolidating purchasing around sustainability-certified suppliers.
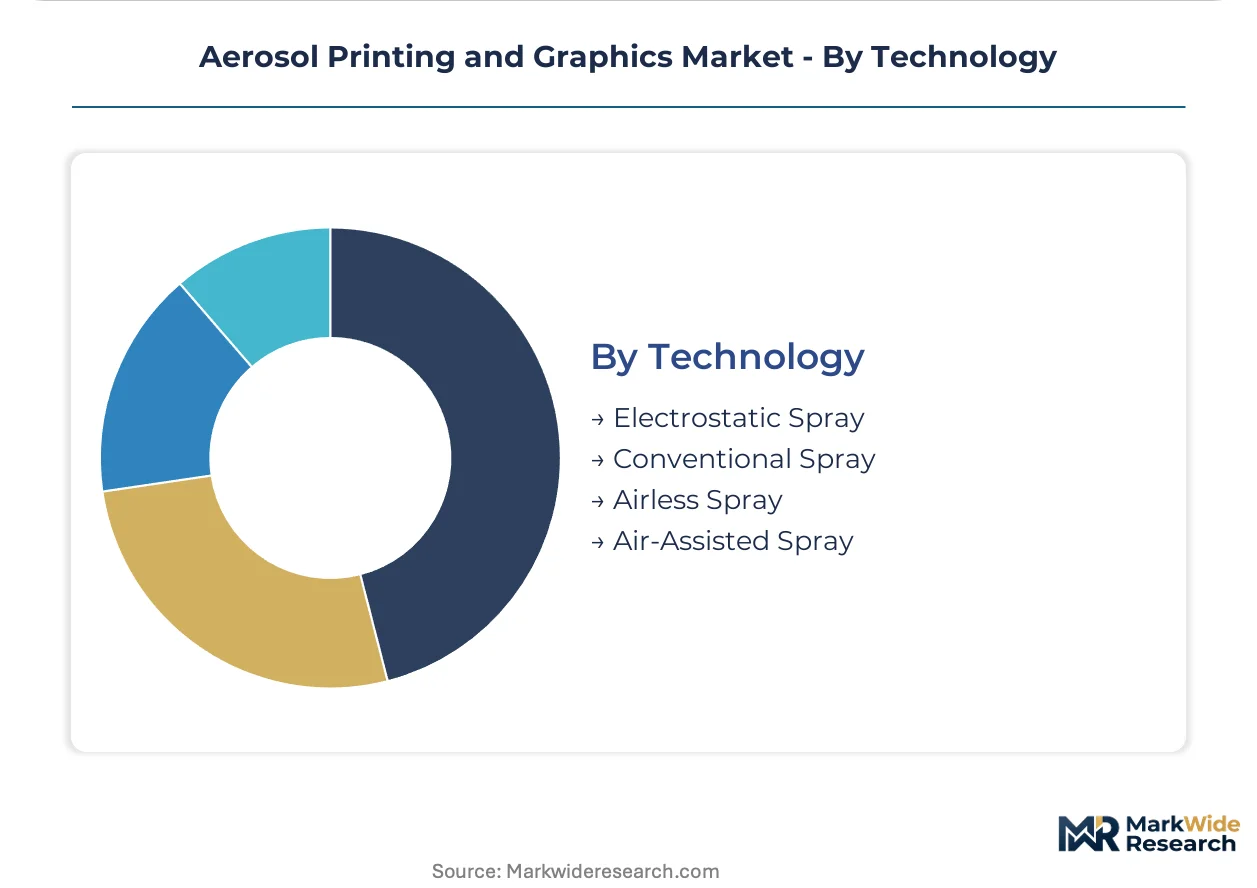
Technology:
Maturity gradients separate established conventional spray from emerging electrostatic systems, with transfer efficiency thresholds determining adoption boundaries.
- Conventional Spray:Compressed air atomization systems dominate existing installed base across refinishing and industrial marking applications.
- Electrostatic Spray:Charged particle deposition achieves wraparound coverage on complex geometries with reduced overspray, qualifying for EPA NESHAP compliance in enclosed booth configurations.
- Airless Spray:High-pressure hydraulic atomization for high-build industrial coatings where film thickness requirements exceed conventional system capabilities.
- Air-Assisted Spray:Hybrid systems combining compressed air and hydraulic pressure for mid-viscosity formulations requiring finer atomization than pure airless methods.
Conventional Spray retains the largest installed base; Electrostatic Spray is gaining share fastest in regulatory-constrained environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European functional coating demand through its automotive supplier density and KBA certification infrastructure. Industrial clusters in Germany, the United States, China, India, and Japan concentrate divergent growth vectors across regulatory, scale, and technology dimensions.
United States
Automotive refinishing chains in Texas and California consolidate purchasing around EPA NESHAP-compliant coating systems. The EPA National Emission Standards for Hazardous Air Pollutants force collision repair networks into enclosed spray booth investments. Detroit's Tier-1 supplier corridor qualifies waterborne polyurethane-acrylic hybrids for underhood corrosion marking.
Germany
KBA certification frameworks exclude non-compliant formulators from Volkswagen and BMW authorized repair networks. REACH Annex XVII VOC limits accelerate low-VOC aerosol development among Stuttgart and Munich industrial coating clusters. Bavarian formulators dominate hybrid resin supply for premium functional specifications.
China
Automotive manufacturing scale in Shanghai and Guangzhou pulls imported functional coating formulations into domestic assembly plants. The Ministry of Ecology and Environment enforces dual carbon goals that favor waterborne systems in coastal industrial zones. Yangtze River Delta packaging converters trial conductive inks for smart packaging exports.
India
Automotive clusters in Pune and Chennai remain underpenetrated by premium functional aerosol suppliers serving warranty-compliant repair. The Bureau of Indian Standards implements phased VOC limits that favor early low-VOC adopters. Tamil Nadu industrial coating demand concentrates around electronics manufacturing and automotive component exports.
Japan
Precision electronics manufacturers in Osaka and Nagoya require conductive and luminescent formulations for curved substrate applications. METI industrial standards shape propellant and resin specifications for domestic appliance and automotive markets. Kanto region packaging innovators test aerosol-printed sensor integration for consumer electronics.
Aerosol Printing and Graphics Market Competitive Environment
The competitive structure tilts toward packaging conglomerates with captive aluminum aerosol capacity. Ball Corporation and Crown Holdings anchor North American and European can supply respectively, while specialized metal decorators and directed energy deposition specialists occupy adjacent technology tiers. Consolidation around OEM-certified coating systems and REACH-compliant formulation capabilities defines the current competitive frontier. Strategic moves concentrate on aluminum supply security and regulatory certification acquisition.
Among packaging-focused conglomerates, Ball Corporation, Crown Holdings, and CCL Industries occupy positions spanning beverage, personal care, and industrial aerosol container markets. Optomec Inc. sits within the functional electronics printing tier, representing directed energy deposition capabilities for curved substrate applications. Amcor and Ardagh Group exemplify diversified packaging structures with cross-regional aerosol exposure. WestRock and Montebello Packaging anchor North American metal decorating and specialty container segments respectively.
| Leading Market Players |
|---|
| Amcor |
| Ball Corporation |
| Crown Holdings |
| CCL Industries |
| WestRock |
| Ardagh Group |
| Optomec Inc. |
| Montebello Packaging |
| EXAL Corporation |
| Others |
Value Chain & Pricing Dynamics
Automotive refinishing shop consolidation around OEM-certified coating systems concentrates procurement leverage among multi-shop operators in Germany and the United States, compressing margin capture for non-certified suppliers and forcing tiered pricing structures that separate KBA-compliant premiums from uncertified commodity tiers.
Pricing Analysis
Value-based pricing anchored to OEM certification status and warranty compliance outcomes dominates the automotive refinishing segment, where KBA and manufacturer-approved supplier lists create steep premiums for certified formulations. Price differentiation separates Volkswagen- and BMW-authorized tiers from independent shop alternatives, with certification grade and volume scale as primary drivers. Cost compression in the commodity decorative spray tier intensifies because hydrocarbon propellant volatility squeezes mid-tier formulators. DIY enthusiasts and artisan retail channels exhibit highest price sensitivity, while Tier-1 automotive suppliers demonstrate lowest sensitivity due to warranty liability exposure.
Supply Chain Analysis
Direct-to-OEM channels handle certified coating demand from Stuttgart and Detroit automotive clusters, while mass retail distribution serves decorative spray volumes. Geographic supply concentration centers on Germany, Switzerland, and the United States for low-VOC resin manufacturing, with aluminum can feedstock drawing from Ball Corporation's North American production footprint. Raw material dependencies include hydrocarbon propellants, waterborne polyurethane-acrylic hybrid resins, and specialty conductive pigments. Single-source vulnerability in aluminum aerosol can supply creates structural risk for beverage and personal care container markets. Distribution runs through certified technical distributor networks for industrial buyers and big-box retail for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as REACH Annex XVII compliance deadlines and EPA NESHAP enforcement eliminate sub-scale formulators lacking reformulation capital.
For Market Incumbents: To counter propellant cost volatility and buyer consolidation, deepen captive supply of waterborne resin systems through backward integration into German and Swiss industrial coating clusters, while securing KBA and OEM certification lock-in through technical service investments at multi-shop operator headquarters. For New Entrants and Emerging Players: Begin with underpenetrated automotive refinishing corridors in Pune and Chennai, where Bureau of Indian Standards phased VOC limits favor early low-VOC adopters lacking established certification hierarchies; lead with conductive ink formulations for smart packaging converters seeking alternatives to German supply concentration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier formulators with stranded solvent-borne capacity in California and Texas facing EPA NESHAP retrofit costs, where equipment and certification assets can be repositioned for compliant waterborne production. Long-term viability hinges on regulatory certification moats rather than commodity scale; watch for state-level extended producer responsibility law passage as inflection signal for aluminum format preference over plastic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Captive supply of REACH-compliant waterborne polyurethane-acrylic hybrids secures margin control against German formulator concentration. |
| OEM Certification Acquisition | KBA and Volkswagen-approved supplier status unlocks warranty-compliant collision repair networks in Stuttgart automotive clusters. |
| Conductive Ink Platform Launch | Luminescent and conductive formulations penetrate smart packaging demand from Yangtze River Delta export converters. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu production capacity addresses Bureau of Indian Standards compliance windows in underpenetrated Pune and Chennai corridors. |
| Long-term Supply Agreement with Aluminum Can Producer | Ball Corporation volume commitments reduce single-source vulnerability for beverage and personal care container markets. |
Study Parameters
Multi-period observation of EPA enforcement patterns, REACH compliance timelines, and automotive refinishing shop consolidation rates anchored the trend analysis, supplemented by interviews with coating formulator R&D directors, Tier-1 automotive supplier procurement managers, collision repair chain operations heads, and aluminum can manufacturing executives. Secondary validation drew from EPA NESHAP regulatory filings, ECHA REACH registration databases, SEC 10-K disclosures from packaging conglomerates, and automotive production data from Stuttgart and Detroit clusters. Bottom-up volume modeling across product types and applications triangulated against top-down macroeconomic drivers.
Segment-weighting applied differential growth coefficients across the analysis window, with Functional Coatings, Specialty Inks, Decorative Sprays, and Transparent Coatings as product type dimensions; Automotive Finishing, Industrial Marking, Textile Printing, and Home Decor as application dimensions; and Manufacturers, Retail Brands, DIY Enthusiasts, and Artists as end user dimensions. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points, incorporating propellant feedstock price indices and OEM certification penetration rates as industry-specific forecast inputs.
Underlying measurement precision varies by segment; Functional Coatings and Automotive Finishing carry tighter precision due to concentrated buyer reporting, while Decorative Sprays and DIY channels exhibit higher variance due to retail fragmentation. Forecasts reflect assumptions regarding EPA and REACH enforcement continuity, aluminum supply stability, and hydrocarbon propellant price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Inkjet Printers Market
Printers
India Inkjet Printer Market
Printers
Printer Ribbons Market
Printers
Electrophotographic Printing Market
Printers
Global Thermal Printing Market
Printers
Refurbished Printers Market
Printers
Production Printer Market
Printers
Ink Tank Printer Market
Printers
Copier, MFP and Printer Market
Printers
A3 and A4 Multi-Function Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Indonesia Thermal Printer Market
Printers
Dot Matrix Printer Market
Printers
Global Printer Market
Printers
Global UV LED Printers Market