
 USB Retimer Market | 2026-2036
USB Retimer Market Size, Share, and Industry Trends Forecast 2026-2036
USB Retimer Market Analytics
Multi-source procurement is restructuring how OEMs secure USB retimer supply, with tier-one device makers diversifying beyond captive silicon to merchant vendors. Astera Labs specializes in high-performance PCIe and USB signal integrity solutions for cloud infrastructure. Texas Instruments leverages its analog foundry network to sustain broad availability across industrial and automotive grades. Parade Technologies anchors display and connectivity retimer supply to notebook and peripheral OEMs.
A USB retimer is a mixed-signal integrated circuit that recovers clock and data from degraded high-speed serial streams, typically operating at USB4's 40 Gbps or Thunderbolt 4 signaling rates, to restore eye diagram margins and ensure protocol-compliant transmission across PCB traces and cables. The device compensates for channel loss, jitter accumulation, and crosstalk in copper interconnects between hosts, hubs, and endpoints. Dual port and multi port product types occupy the highest volume tiers as docking stations and monitors multiply retimer counts per device. Signal conditioning technology leads in revenue contribution due to its integration complexity and premium positioning in enterprise computing platforms.
FCC equipment authorization rules in the United States govern electromagnetic emissions from retimer-equipped systems, while CE marking under the EU's Radio Equipment Directive shapes product access across European markets. China's GB standards and MIIT certification requirements for information technology equipment create a parallel compliance pathway for domestic and export-bound production. Stakeholders must monitor protocol roadmap evolution from the USB Implementers Forum and Intel's Thunderbolt specification releases to align retimer development cycles with next-generation bandwidth thresholds.
Market Dynamics
USB4 and Thunderbolt 4 protocol proliferation is compressing retimer qualification cycles, forcing vendors to synchronize silicon roadmaps with Intel's specification cadence and USB-IF certification windows. This temporal compression rewards foundry-scale players with parallel validation resources.
Growth Catalysts
- Data center interconnect density:Hyperscale server deployments in China require multi-port retimer configurations to maintain signal integrity across backplane and cable assemblies at 40 Gbps lane rates.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in cooling systems accelerate liquid-cooled rack designs, increasing copper trace lengths that demand active signal conditioning.
- Thunderbolt 4 docking proliferation:Enterprise IT refresh cycles are standardizing on universal docking stations, each embedding two to four retimer channels for downstream USB-C port expansion.
Market Restraints
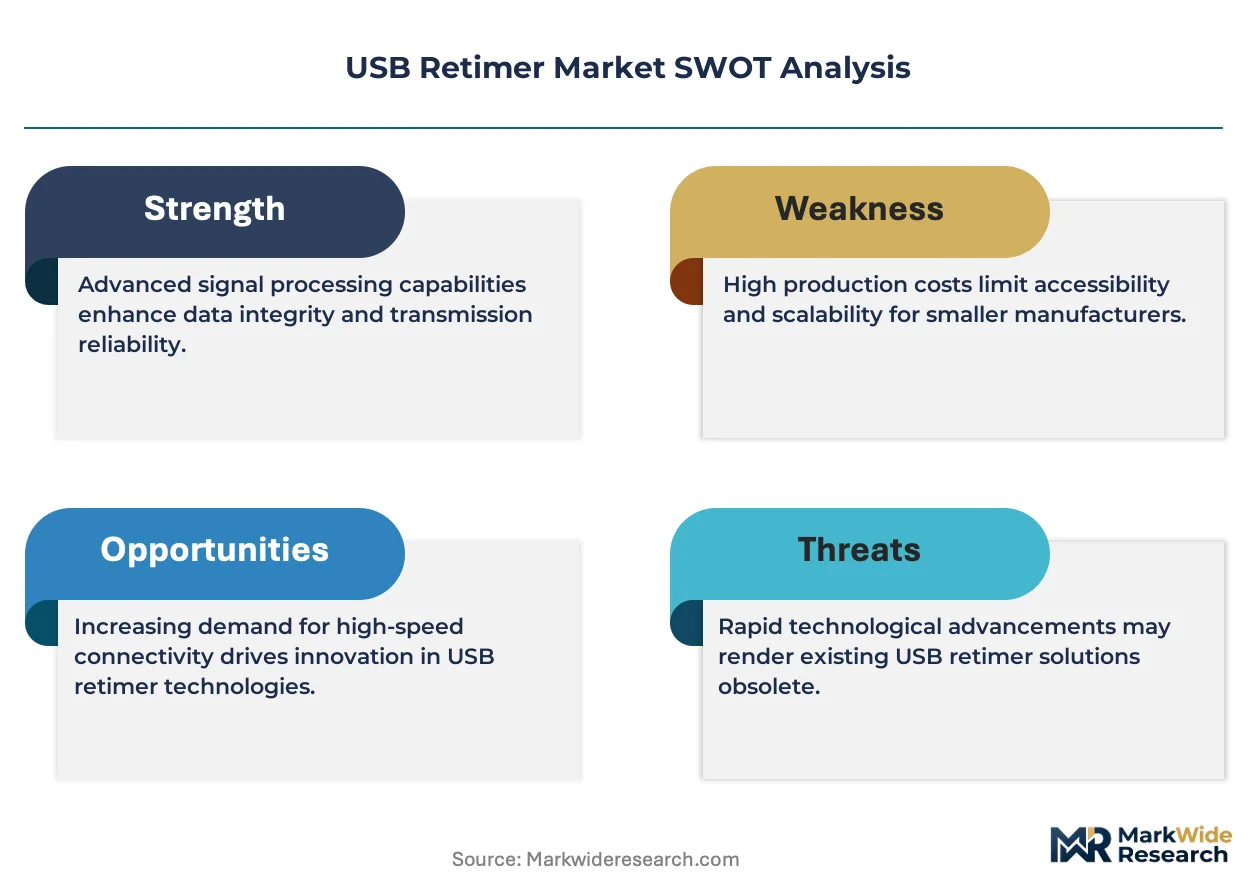
- Advanced CMOS node allocation:Retimer PHY designs compete for 7nm and 5nm foundry capacity against AI accelerators and smartphone SoCs, constraining supply elasticity.
- MIIT certification timelines:China's mandatory information technology equipment approval processes extend product launch windows by 8-14 weeks versus comparable FCC procedures.
- Passive copper alternatives:Improved twin-axial cable constructions with integrated equalization are displacing retimers in sub-1-meter internal chassis links.
Strategic Opportunities
- Automotive USB-C consolidation:Infotainment and charging port unification in electric vehicles creates retimer demand for 15-watt and 100-watt power-delivery signal paths.
- India PLI scheme localization:Production-linked incentives for IT hardware manufacturing are attracting retimer packaging and test operations to Chennai and Noida electronics clusters.
- USB4 Version 2.0 readiness:80 Gbps asymmetric mode support positions early-mover vendors for 2025-2026 platform design wins.
Industry Challenges
- SerDes verification expertise scarcity:Mixed-signal IC design talent capable of optimizing jitter tolerance and equalization algorithms commands premium compensation, constraining mid-tier vendor expansion.
- Protocol compliance test burden:USB-IF and Intel Thunderbolt certification suites require six-figure equipment investments and 12-16 week validation cycles per SKU derivative.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Retimer Market |
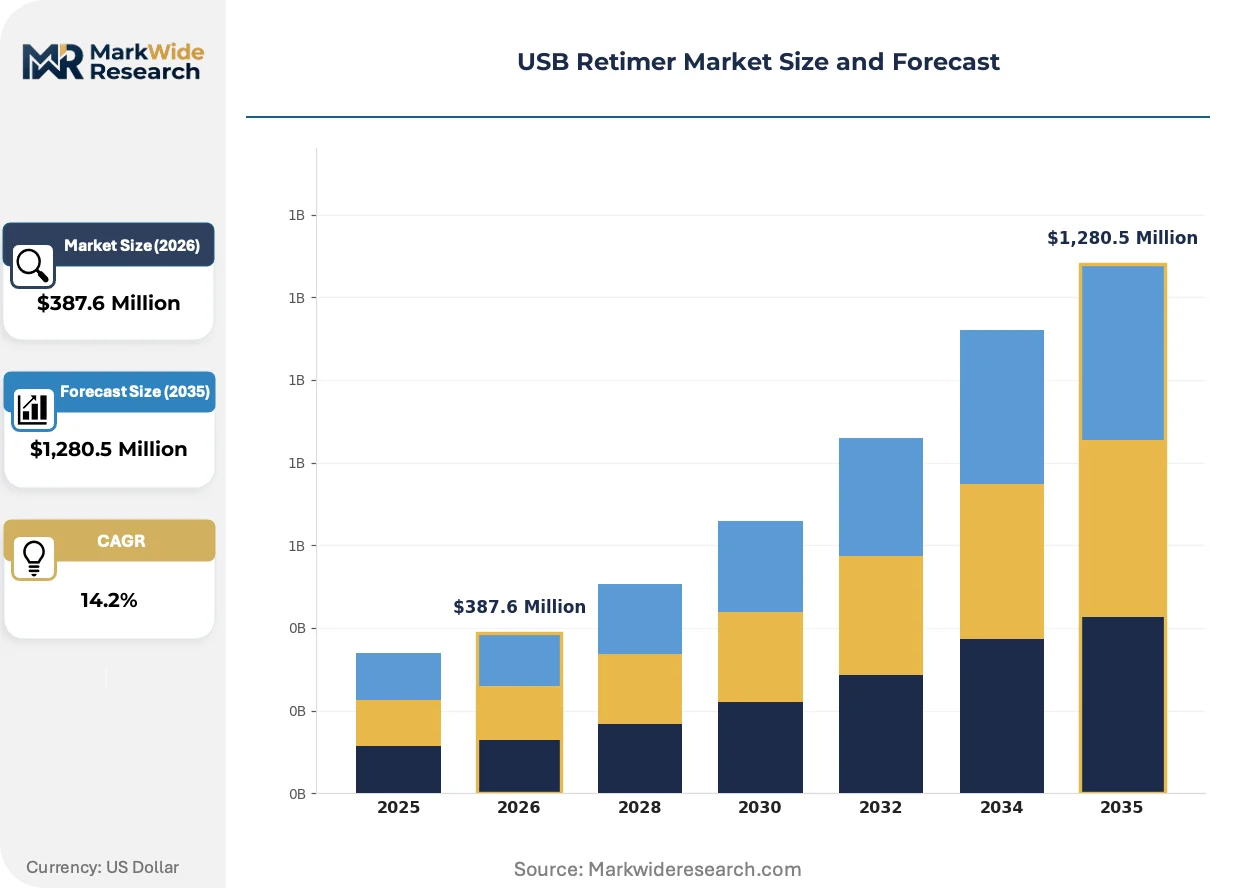
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Port, Dual Port, Multi Port, Integrated Technology: Signal Conditioning, Repeater, Equalization, Redriver End User: Consumer Electronics, Computing, Automotive, Industrial Automation Deployment Model: On-Premise, Cloud-Based, Hybrid, Dedicated |
| Companies Covered | Astera Labs, Parade Technologies, Texas Instruments, Intel, Analogix, Montage Technology, Diodes Incorporated, NXP Semiconductors, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Retimer Market Evolving Landscape
Active signal conditioning architectures are converging with power-delivery controllers, collapsing discrete component counts while raising thermal and electromagnetic compatibility design complexity. This integration wave favors semiconductor vendors with analog-digital co-design capabilities.
Multi-protocol retimer silicon is consolidating USB4, DisplayPort 2.1, and PCIe 4.0/5.0 redrivers into single-die implementations. Notebook OEMs are adopting these unified devices to reduce motherboard layer counts and simplify procurement. The structural consequence is compressing merchant vendor margins as functionality commoditizes across protocol boundaries.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic emission limits for retimer-equipped docking stations and monitors. Manufacturers are responding with enhanced shielding designs and spread-spectrum clocking techniques. Enterprise computing platforms with multi-port configurations face the steepest compliance cost escalation.
Direct sourcing from merchant retimer vendors is displacing traditional distribution for tier-one PC and server OEMs. Volume commitments now flow through quarterly master purchase agreements rather than authorized distributor stock programs. This pattern is most visible in Taiwan and China, where ODMs maintain captive procurement teams at Astera Labs and Parade Technologies.
USB Retimer Market Segmentation

USB retimer procurement patterns diverge sharply across port configurations, signal processing architectures, and end-use environments. Understanding these divides reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
System designers select port counts based on dock complexity and motherboard routing density rather than per-unit cost optimization.
- Dual Port:Dominates notebook and docking station implementations where two downstream USB-C ports require independent clock recovery. Hyperscale server backplanes in China specify dual-port retimers to maintain 40 Gbps signal integrity across mid-plane interconnects. Volume sits with Dual Port; growth tilts toward Multi Port.
- Multi Port:Integrates four to eight independent SerDes channels for monitor hubs and enterprise docking stations. Liquid-cooled rack designs extending copper trace lengths amplify demand for multi-port configurations compensating aggregate channel loss.
- Single Port:Addresses peripheral endpoint applications with minimal board space and power budgets. Embedded controllers in industrial sensors adopt single-port retimers for isolated high-speed links.
- Integrated:Combines retimer functionality with USB4 hub controllers or power-delivery managers in single-die implementations. Notebook OEMs pursuing layer-count reduction drive qualification activity.
Dual Port shipments dominate current revenue; Multi Port configurations are climbing the fastest as dock complexity escalates.
Technology:
Signal restoration methodologies differentiate by jitter tolerance thresholds and equalization algorithm sophistication.
- Signal Conditioning:Encompasses continuous-time linear equalization and decision-feedback equalization blocks recovering eye diagrams at 40 Gbps lane rates. Enterprise computing platforms in Taiwan and China specify signal conditioning retimers for Thunderbolt 4 compliance, absorbing six-figure certification investments per SKU.
- Equalization:Deploys adaptive equalization engines dynamically tuning to cable and PCB loss profiles. Automotive USB-C consolidation for infotainment backbones creates demand for temperature-stable equalization architectures.
- Repeater:Provides basic amplification without clock data recovery, occupying cost-sensitive peripheral applications below 20 Gbps signaling.
- Redriver:Offers fixed equalization without CDR, serving short-reach internal chassis links where protocol compliance requirements relax.
Signal Conditioning commands the steepest pricing; Equalization is expanding most quickly in automotive qualification pipelines.
End User:
Application environments dictate thermal envelopes, vibration tolerance, and certification stringency.
- Computing:Encompasses servers, workstations, and client PCs requiring USB4 and Thunderbolt 4 signal integrity. Data center interconnect density in China drives multi-port retimer procurement for backplane and cable assembly vendors.
- Consumer Electronics:Covers monitors, docking stations, and peripheral hubs where cost compression competes with port multiplication. Thunderbolt 4 docking standardization in enterprise IT refresh cycles embeds two to four retimer channels per unit.
- Automotive:Demands AEC-Q100 qualification and -40°C to 105°C operating ranges for infotainment and charging port consolidation. Electric vehicle platforms unifying 15-watt and 100-watt power-delivery paths create new signal conditioning requirements.
- Industrial Automation:Requires extended temperature operation and enhanced electromagnetic immunity for factory floor connectivity. Machine vision systems adopting USB3 Vision standards drive isolated retimer adoption.
Computing absorbs the highest absolute volume; Automotive presents the steepest expansion trajectory as port unification accelerates.
Deployment Model:
Infrastructure ownership structures determine retimer specification authority and procurement cycle timing.
- On-Premise:Enterprise data centers and corporate IT departments specify retimer configurations directly for server and workstation deployments. Direct sourcing from merchant vendors through quarterly master purchase agreements displaces traditional distribution channels.
- Cloud-Based:Hyperscale operators design custom server architectures with captive retimer specifications. Cloud infrastructure expansion in China concentrates procurement volume with domestic ODMs.
- Hybrid:Blends edge computing nodes with centralized cloud resources, requiring retimers supporting diverse cable lengths and environmental conditions.
- Dedicated:Specialized high-performance computing and test equipment deployments with unique signal integrity requirements and extended product lifecycles.
On-Premise retains the largest installed base; Cloud-Based procurement is gaining share fastest as hyperscale capex scales.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors retimer supply geography, while end-use demand clusters in China, the United States, Germany, and Japan where data center buildouts and PC manufacturing concentrate procurement volume.
China
Hyperscale cloud operators in Beijing and Shanghai drive multi-port retimer procurement for 40 Gbps backplane interconnects. MIIT certification requirements for information technology equipment extend product launch windows versus comparable FCC procedures. Shenzhen and Suzhou electronics clusters host domestic ODMs maintaining captive procurement teams at merchant retimer vendors.
United States
Enterprise IT refresh cycles standardizing on Thunderbolt 4 docking stations embed two to four retimer channels per unit. FCC equipment authorization rules govern electromagnetic emissions from retimer-equipped systems. Texas maintains analog foundry operations sustaining broad availability across industrial and automotive grades.
Germany
Automotive OEMs in Stuttgart and Munich specify AEC-Q100 qualified retimers for infotainment USB-C consolidation in electric vehicle platforms. CE marking under the EU's Radio Equipment Directive tightens electromagnetic emission limits for docking stations. Bavaria-based suppliers face compliance cost escalation for multi-port enterprise configurations.
Japan
Precision equipment manufacturers in Nagoya and Osaka adopt retimers for machine vision systems using USB3 Vision standards. METI industrial policy supports domestic semiconductor packaging capabilities for high-speed signal conditioning devices. Kyushu electronics clusters specialize in automotive-grade retimer test operations.
South Korea
Display panel makers in Gyeonggi Province integrate retimers for monitor hubs supporting USB4 and DisplayPort 2.1 convergence. The country's national information technology regulator enforces electromagnetic compatibility standards for consumer electronics exports. Seoul-based ODMs direct-source from merchant vendors through quarterly master purchase agreements.
USB Retimer Market Competitive Landscape
Multi-source procurement dominates the current landscape as tier-one device makers diversify beyond captive silicon. The vendor base organizes into three tiers: foundry-scale analog specialists with parallel validation resources, fabless signal integrity architects focused on cloud infrastructure, and diversified semiconductor conglomerates with broad distribution networks. Strategic archetypes include protocol certification leaders, automotive qualification specialists, and multi-protocol integration architects. Portfolio diversification and direct OEM sourcing agreements constitute the dominant competitive moves reshaping channel structures.
Among fabless signal integrity specialists, Astera Labs and Parade Technologies exemplify the cloud-focused archetype, while Texas Instruments represents the foundry-scale diversified tier. Astera Labs occupies a position within high-performance PCIe and USB signal integrity solutions. Parade Technologies anchors display and connectivity retimer supply relationships with notebook OEMs. Texas Instruments leverages analog foundry network breadth to sustain availability across industrial and automotive qualification grades.
| Leading Market Players |
|---|
| Astera Labs |
| Parade Technologies |
| Texas Instruments |
| Intel |
| Analogix |
| Montage Technology |
| Diodes Incorporated |
| NXP Semiconductors |
| Microchip Technology |
| Others |
Value Network & Pricing Analysis
Tier-one notebook and server OEMs concentrating procurement through quarterly master purchase agreements enforce contract-based long-term offtake pricing with embedded volume discounts. This buyer concentration shifts pricing power toward merchants capable of parallel validation resources and MIIT certification readiness.
Pricing Analysis
Extended warranty and certification support bundles separate premium signal conditioning retimers from unbundled economy-tier redrivers. Pricing stratifies across premium, standard, and economy tiers based on USB-IF certification grade and analog-digital co-design complexity. Cost compression in the redriver segment intensifies as passive copper alternatives displace active components in sub-1-meter chassis links. Cloud hyperscalers exhibit lowest price sensitivity due to signal integrity requirements, while peripheral OEMs prioritize per-unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Taiwan and South Korea anchor hub-and-spoke patterns serving Shenzhen and Suzhou electronics clusters. Foundry-scale supply concentrates in Taiwan, South Korea, and the United States, drawing from advanced CMOS wafer starts and analog packaging capabilities. Single-source vulnerability in 7nm and 5nm node allocation creates structural risk as AI accelerators compete for capacity. Distribution runs through direct OEM procurement teams rather than authorized distributor stock programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USB retimer qualification operates as a cost-of-compliance story where USB-IF and Intel Thunderbolt certification suites erect barrier-to-entry moats favoring vendors with six-figure equipment investments and 12-16 week validation cycles.
For Market Incumbents: Anticipate margin compression from multi-protocol integration commoditizing functionality across USB4, DisplayPort 2.1, and PCIe boundaries. Defensive moves center on deepening analog-digital co-design capabilities and securing captive procurement relationships with Taiwan-based ODMs. Threat emergence from fabless signal integrity specialists demands accelerated USB4 Version 2.0 readiness investments. For New Entrants and Emerging Players: Enter via automotive USB-C consolidation where AEC-Q100 qualification requirements filter out generalist competitors. White-space targets include electric vehicle infotainment backbones and 100-watt power-delivery signal paths in Stuttgart and Munich manufacturing clusters. Go-to-market leverage rests on temperature-stable equalization architectures addressing -40°C to 105°C operating ranges. For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless signal integrity architects with MIIT certification pipelines in China over foundry-dependent analog generalists. Long-term viability across the projection horizon hinges on protocol roadmap synchronization with Intel specification cadence. Acquisition target archetype: vendors with validated USB4 Version 2.0 silicon and existing hyperscale cloud operator relationships. Signal to monitor: Intel Thunderbolt specification release timing and USB-IF certification window announcements.| Strategic Initiative | Industry Significance |
|---|---|
| USB4 Version 2.0 Silicon Readiness | Early-mover vendors secure 80 Gbps design wins with Intel platform releases. |
| Automotive AEC-Q100 Qualification | Electric vehicle OEMs in Germany specify temperature-stable architectures for infotainment consolidation. |
| Multi-Protocol Single-Die Integration | Notebook OEMs reduce motherboard layer counts through USB4 and DisplayPort 2.1 convergence. |
| Direct OEM Procurement Agreements | Taiwan-based ODMs displace distributor channels with quarterly master purchase commitments. |
| MIIT Certification Pipeline Investment | China market access requires 8-14 week approval timelines versus comparable FCC procedures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with SerDes verification engineers, ODM procurement managers, and analog IC design directors combined with USB-IF certification databases and Intel Thunderbolt specification releases. Secondary sources encompassed MIIT equipment approval records, FCC equipment authorization filings, and EU CE marking directives. Bottom-up retimer shipment estimates and top-down semiconductor consumption models underwent triangulation validation.
Data-stream reconciliation across foundry utilization reports, hyperscaler capex disclosures, and ODM production schedules informed the analytical framework. Segmentation dimensions modeled encompassed port configuration, signal processing architecture, end-use environment, and deployment model across the projection horizon. CAGRs derived from protocol adoption curves and replacement cycle analysis. Industry-specific forecast inputs included USB4 Version 2.0 specification timing and liquid-cooled rack deployment trajectories in China.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry node allocation competition and Thunderbolt specification revision timing. Outputs reflect assumptions regarding Intel's roadmap cadence and USB-IF certification window stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Operational Amplifier Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Speaker Membranes Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Efuse Market
Electronic Components
United States MLCC Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
North America USB Retimer Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Loudspeaker Market
Electronic Components
Europe Water Cooled Capacitors Market
Electronic Components
Docking Station Market
Electronic Components
Microspeaker Market