
 AC Adapter Market | 2026-2036
AC Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
AC Adapter Market Outlook
Aftermarket service revenue for adapter refurbishment and warranty extensions is rewriting margin capture across the supply chain. Delta Electronics leverages captive manufacturing in Taiwan and China to sustain cost leadership in high-wattage laptop adapters. Chicony Power Technology anchors global notebook OEM supply through direct integration with brands like HP and Dell. Lite-On Technology competes aggressively in GaN-based USB-C fast charging modules for premium consumer segments.
An AC adapter converts alternating current from wall outlets to direct current at specified voltage and current levels, typically employing switching-mode power supply topologies operating at 50 kHz to above 1 MHz to minimize transformer size and thermal losses. Wall charger and USB charger segments dominate unit volume, while GaN technology commands premium positioning due to reduced form factors and higher power density in mobile device applications. Switching adapters lead industrial and telecommunications deployments where efficiency certifications determine procurement eligibility, and linear designs persist only in cost-sensitive medical device niches requiring minimal electromagnetic interference.
The US Department of Energy enforces minimum efficiency standards under Level VI that disqualify low-tier adapters from federal procurement, while the EU Ecodesign Directive mandates standby power below 0.15W and drives redesign cycles across export-oriented manufacturers. China's GB standards, administered by SAMR, require CCC certification that filters non-compliant suppliers from domestic retail channels. Stakeholders must monitor regulatory divergence between efficiency tiers as GaN adoption accelerates and certification costs reshape competitive barriers for mid-scale producers.
Market Dynamics
GaN-based switching technology is compressing adapter form factors while the US Department of Energy Level VI standards and EU Ecodesign Directive eliminate inefficient legacy designs from commercial channels. Contract manufacturing clusters in Shenzhen and Dongguan now dictate cost benchmarks and certification velocity for global OEM procurement.
Growth Catalysts
- EU Ecodesign Directive standby power mandates:The 0.15W ceiling forces redesign cycles across export-oriented manufacturers, accelerating GaN adoption in premium consumer segments.
- USB-C Power Delivery standardization:Universal connector convergence across laptops, tablets, and mobile devices consolidates adapter SKUs and expands addressable market per unit.
- Shenzhen-Dongguan manufacturing concentration:Vertical integration from semiconductor packaging to final assembly compresses lead times and enables rapid prototyping for fast-charging modules.
Market Restraints
- Silicon carbide and GaN wafer supply constraints:Limited foundry capacity for wide-bandgap semiconductors creates input cost volatility and allocation rationing for mid-tier producers.
- CCC certification timeline friction:China's SAMR-administered GB standards require 8-12 week testing cycles that filter non-compliant suppliers from domestic retail channels.
- Linear adapter persistence in medical devices:Electromagnetic interference requirements in diagnostic equipment sustain demand for obsolete transformer-based designs that undercut switching adapter margins.
Strategic Opportunities
- India BIS certification expansion:Mandatory ISI marking for electronic goods creates first-mover advantage for adapters meeting Bureau of Indian Standards efficiency grades.
- Aftermarket refurbishment services:Warranty extension and adapter trade-in programs capture margin from circular economy mandates in EU member states.
- GaN-silicon hybrid topologies:Convergence of cost-optimized silicon controllers with GaN power stages bridges price-performance gaps in mid-wattage industrial applications.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized magnetics design and thermal management expertise concentrates in Taiwan and mainland China, constraining R&D expansion elsewhere.
- Multi-jurisdictional certification parallelism:Simultaneous UL, CE, CCC, and PSE testing requirements extend product launch timelines and inflate compliance overhead.
- Legacy inventory obsolescence:Rapid efficiency tier escalation strands silicon-based adapter stockpiles that fail emerging standby power benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Adapter Market |
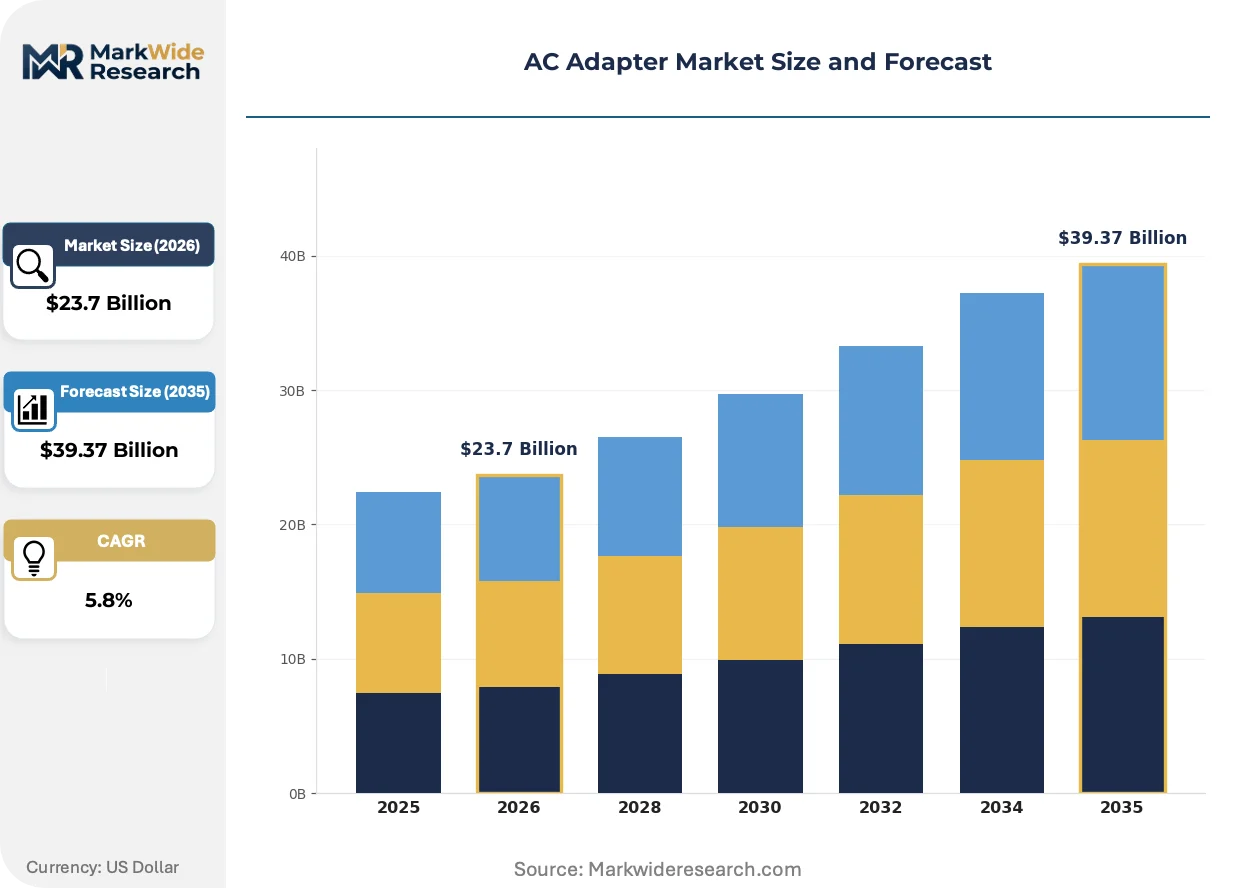
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Charger, Car Charger, Power Bank, USB Charger Technology: Linear, Switching, Smart, GaN End User: Consumer Electronics, Industrial Equipment, Medical Devices, Telecommunications Application: Mobile Devices, Laptops, Home Appliances, Automotive |
| Companies Covered | Delta Electronics, Chicony Power Technology, Lite-On Technology, Mean Well, FSP Group, AcBel Polytech, Huntkey, TDK-Lambda, Bel Power Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Adapter Market Strategic Shifts
Active power factor correction and wide-bandgap semiconductors are redefining thermal design limits while regulatory efficiency tiers accelerate product turnover. The competitive frontier now centers on power density metrics and certification velocity rather than unit cost alone.
Gallium nitride high-electron-mobility transistors operate at switching frequencies above 1 MHz, enabling transformer miniaturization that reduces adapter volume by 40-50% versus silicon MOSFET equivalents. Premium laptop OEMs and mobile device brands now specify GaN-based USB-C modules as standard configuration. This frequency scaling is rendering obsolete traditional ferrite core designs that dominated 65W and below applications for three decades.
The US Department of Energy Level VI efficiency standards disqualify adapters below 88% active-mode efficiency from federal procurement channels, compressing viable supplier pools to certified tier-1 manufacturers. Industrial and telecommunications buyers now require Level VI compliance as a baseline qualification, not a differentiator. Data center power distribution and network infrastructure deployments face the tightest procurement eligibility constraints under this framework.
Enterprise IT procurement teams now consolidate adapter sourcing through direct OEM contracts rather than distributor channels, compressing margin capture for independent component suppliers. This concentration shifts volume toward captive manufacturing arrangements with Delta Electronics and Chicony Power Technology. North American and Western European enterprise segments exhibit the most pronounced channel consolidation, with distributor share of wallet declining in commercial notebook deployments.
AC Adapter Market Segmentation
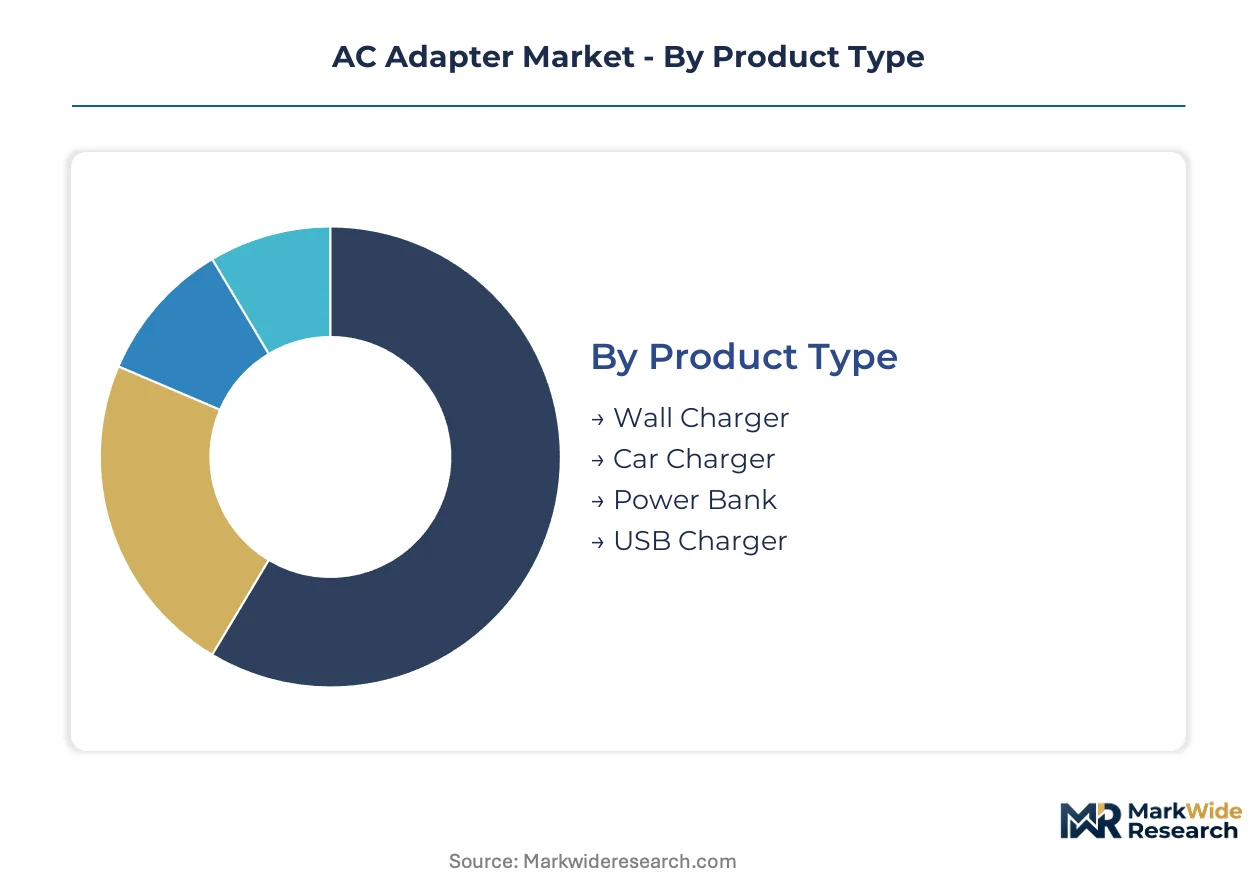
Adapter segmentation reveals divergent replacement cycles across product categories, with mobile-facing segments refreshing every 18-24 months while industrial installations persist for 7-10 years. Technology and end-user splits determine margin structure, procurement channel, and certification burden.
Product Type:
Wall chargers and USB chargers turn inventory fastest through consumer electronics channels, while car chargers and power banks exhibit longer replacement intervals tied to vehicle ownership cycles and battery degradation rates.
- Wall Charger:Fixed-installation units dominate residential and commercial building infrastructure. Demand concentrates in China's export manufacturing corridors serving North American and European retail channels, with GaN modules displacing silicon in premium tiers.
- USB Charger:Universal connector convergence under USB-C Power Delivery consolidates adapter SKUs across laptop, tablet, and mobile device categories. North American enterprise procurement teams now specify these as standard notebook fleet configurations.
- Car Charger:Cigarette-lighter and USB-PD variants serve aftermarket automotive accessories. Electrification of vehicle cabins expands addressable sockets per automobile.
- Power Bank:Portable battery packs with integrated charging circuitry address mobility gaps. Lithium-ion cell supply constraints and airline transport restrictions shape distribution logistics.
Wall chargers anchor the volume base while USB chargers gain share at the steepest rate.
Technology:
Cost tiers separate legacy silicon designs from premium wide-bandgap implementations, with procurement eligibility tightening around efficiency certifications that filter non-compliant suppliers.
- GaN:Gallium nitride high-electron-mobility transistors switch above 1 MHz, enabling 40-50% volume reduction versus silicon equivalents. Premium laptop OEMs specify these modules as standard configuration.
- Switching:Silicon MOSFET-based designs at 50 kHz-500 kHz serve industrial and telecommunications deployments where US Department of Energy Level VI compliance determines procurement eligibility.
- Smart:Microcontroller-managed adapters adjust output dynamically per device handshake protocols. USB-PD and Qualcomm Quick Charge integration drives specification complexity.
- Linear:Transformer-based designs persist in medical diagnostic equipment where electromagnetic interference minimization outweighs efficiency penalties. Diagnostic imaging OEMs in Germany and Switzerland sustain residual demand.
Switching adapters anchor the volume base while GaN implementations expand most quickly.
End User:
Application-specific certification requirements create divergent margin profiles, with medical and telecommunications buyers demanding documentation that consumer segments disregard.
- Consumer Electronics:Mobile device and laptop OEM procurement concentrates volume through direct contracts with Delta Electronics and Chicony Power Technology. Retail channel fragmentation competes on price.
- Telecommunications:Network infrastructure and data center power distribution face stringent efficiency benchmarks. Level VI compliance operates as baseline qualification, not differentiation.
- Industrial Equipment:Factory automation and process control systems require ruggedized thermal designs. India's BIS certification expansion creates first-mover advantage for efficiency-graded suppliers.
- Medical Devices:Diagnostic and patient monitoring equipment sustains demand for linear designs despite obsolescence elsewhere. Electromagnetic compatibility requirements override cost optimization.
Consumer electronics anchors the volume base while telecommunications climbs the fastest on infrastructure buildouts.
Application:
Power density requirements scale with device wattage, separating sub-30W mobile applications from 100W+ laptop and appliance segments that drive GaN adoption.
- Laptops:45W-100W adapters face enterprise procurement consolidation through direct OEM contracts. North American distributor share of wallet declines as IT sourcing centralizes.
- Mobile Devices:Smartphones and tablets drive highest unit volumes at sub-30W specifications. Shenzhen-Dongguan manufacturing clusters compress lead times for fast-charging module prototyping.
- Home Appliances:White goods and small electronics employ lower-wattage adapters with extended replacement cycles. EU Ecodesign Directive standby power mandates force redesign cycles.
- Automotive:In-cabin charging and electric vehicle auxiliary systems expand addressable wattage ranges. Integration with vehicle power management systems raises qualification barriers.
Mobile devices anchors the volume base while laptop applications show steepest expansion trajectory on enterprise fleet refreshes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States demonstrate minimal price elasticity for certified adapters, while retail consumers in India and Southeast Asia drive volume through extreme cost sensitivity. This demand bifurcation shapes divergent go-to-market strategies across geographies.
United States
Federal procurement channels under US Department of Energy Level VI standards filter non-compliant suppliers from enterprise IT contracts. The EPA administers efficiency benchmarking that determines eligibility for data center and telecommunications infrastructure deployments. California's Silicon Valley anchors premium laptop OEM procurement concentration, with direct contracts displacing distributor channels.
Germany
Industrial automation and medical diagnostic equipment sustain demand for both high-efficiency switching designs and legacy linear adapters. The EU Ecodesign Directive's 0.15W standby power ceiling accelerates redesign cycles among export-oriented manufacturers serving German OEMs. Bavaria's precision electronics cluster around Munich hosts certification laboratories that validate adapter compliance for pan-European distribution.
China
Shenzhen and Dongguan manufacturing corridors compress lead times from semiconductor packaging through final assembly for global consumer electronics brands. SAMR-administered CCC certification creates 8-12 week testing friction that filters non-compliant suppliers from domestic retail channels. The MIIT's GB standards enforcement tightens efficiency benchmarks for adapters sold through e-commerce platforms.
India
Bureau of Indian Standards mandatory ISI marking for electronic goods creates first-mover advantage for adapters meeting efficiency grades in industrial and consumer segments. The CEA's power quality regulations drive replacement of obsolete transformer-based designs in commercial buildings. Maharashtra's Pune-Aurangabad corridor concentrates contract manufacturing for domestic mobile device brands.
Japan
Telecommunications infrastructure and precision electronics sustain premium positioning for high-reliability adapters in network equipment and factory automation. METI's Top Runner program establishes efficiency benchmarks that exceed international minimums, compressing viable supplier pools. The Kanto region around Tokyo anchors procurement decision-making for pan-Asian OEM supply chains.
AC Adapter Market Competitive Environment
Capability concentration sits with tier-1 integrated manufacturers possessing captive semiconductor packaging and magnetics design expertise; scale advantage sits with contract manufacturers in Shenzhen-Dongguan corridors serving global OEM procurement teams. The market structures around three archetypes: vertically integrated power electronics specialists, pure-play contract manufacturers, and diversified electronics conglomerates with adapter divisions. Consolidation pressures intensify as certification costs and GaN technology licensing fees reshape competitive barriers. Dominant competitive moves include backward integration into wide-bandgap semiconductor sourcing and geographic expansion into India BIS certification channels.
Among Taiwan-based integrated manufacturers, Delta Electronics and Chicony Power Technology exemplify the capability-concentrated tier with captive production networks spanning Taiwan and mainland China. Lite-On Technology occupies a position within the diversified conglomerate archetype, competing through GaN-based module development for premium consumer segments. These three anchors represent distinct strategic postures: Delta Electronics through high-wattage laptop adapter scale, Chicony Power Technology through direct OEM integration, and Lite-On Technology through fast-charging technology positioning.
| Leading Market Players |
|---|
| Delta Electronics |
| Chicony Power Technology |
| Lite-On Technology |
| Mean Well |
| FSP Group |
| AcBel Polytech |
| Huntkey |
| TDK-Lambda |
| Bel Power Solutions |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in wide-bandgap semiconductor foundries drives supplier allocation discipline and sustains premium pricing for GaN-based modules even as silicon adapter margins compress. Contract manufacturers in Shenzhen and Dongguan exploit captive magnetics capacity to defend pricing power in high-wattage segments while absorbing efficiency certification costs into long-term OEM agreements.
Pricing Analysis
Aftermarket refurbishment and warranty extension revenue streams now drive lifetime value capture across adapter portfolios. Three-tier pricing structure across premium GaN, certified switching, and residual linear tiers reflects certification grade and thermal performance density. Pricing pressure stems from enterprise procurement consolidation through direct OEM contracts that eliminate distributor markups. Retail consumers in India and Southeast Asia exhibit extreme price sensitivity, while North American IT procurement teams demonstrate minimal elasticity for Level VI-certified adapters.
Supply Chain Analysis
Supplier-financing facilities extended by Shenzhen-Dongguan contract manufacturers enable 90-120 day payment terms that lock in volume commitments from mid-tier brands. Supply concentrates in China, Taiwan, and South Korea for semiconductor packaging and ferrite core magnetics. Raw material dependencies include gallium nitride wafers, copper litz wire, and high-frequency ferrite cores. Single-source vulnerability in GaN-on-silicon epitaxy creates allocation risk during demand spikes. Distribution runs through direct OEM contracts for enterprise segments and e-commerce platforms for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward enterprise IT procurement teams consolidating adapter sourcing through direct contracts with tier-1 manufacturers, fragmenting independent supplier margins.
For Market Incumbents: Entrench GaN controller design expertise through captive semiconductor partnerships that secure allocation priority during wafer supply constraints. Expand CCC and BIS certification coverage to filter mid-tier competitors from China and India retail channels. Defend against silicon carbide substitution threats in industrial segments by anchoring high-frequency magnetics capabilities in Taiwan engineering centers. For New Entrants and Emerging Players: India's underpenetrated BIS certification landscape offers first-mover positioning among efficiency-graded industrial adapters before mandatory ISI marking fully phases in. Target Maharashtra's Pune-Aurangabad manufacturing corridor for domestic mobile brand supply relationships. Pursue GaN-silicon hybrid topology development for mid-wattage price-performance gaps in factory automation applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among adapter OEMs with direct integration into laptop and telecommunications infrastructure procurement channels. Five-to-ten year viability favors vertically integrated manufacturers possessing captive magnetics design and wide-bandgap semiconductor sourcing relationships. Monitor GaN wafer foundry expansion announcements as inflection signals for input cost normalization and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Semiconductor Sourcing | Captive wafer supply secures allocation priority during foundry capacity constraints. |
| India BIS Certification Pre-positioning | Early ISI marking compliance filters competitors from mandatory marking expansion. |
| GaN-Silicon Hybrid Topology Development | Cost-optimized switching bridges price-performance gaps in industrial segments. |
| Aftermarket Refurbishment Service Launch | Warranty extension programs capture circular economy margin in EU member states. |
| Direct OEM Contract Consolidation | Enterprise IT procurement centralization displaces distributor channel volume. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with power electronics engineers, OEM procurement managers, contract manufacturing executives, and thermal design specialists. Secondary validation drew from US Department of Energy efficiency filings, EU Ecodesign Directive compliance databases, China SAMR CCC certification registries, and Bureau of Indian Standards ISI marking records. Bottom-up unit demand modeling and top-down value triangulation were cross-referenced against customs trade data and enterprise IT procurement disclosures.
Calibration against historical efficiency tier transitions and GaN adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, switching technology, end-user application, and regional regulatory cluster. CAGRs were derived from iterative convergence between supply-side capacity expansion schedules and demand-side replacement cycle analysis. Forecast inputs incorporated wide-bandgap semiconductor foundry utilization rates and multi-jurisdictional certification timeline friction.
Practitioners should monitor GaN wafer supply allocation shifts and standby power regulation tier escalations for early signals of competitive repositioning. Forecasts reflect documented assumptions on efficiency standard enforcement timing and OEM procurement centralization velocity. Macroeconomic demand contraction, regulatory divergence on electromagnetic compatibility requirements, or breakthrough silicon carbide cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Coin Battery Holder Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Encoder Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
VPX SBC Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Flexible Heater Market
Electronic Components
China Data Converter Market
Electronic Components
Screw Washer Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Conductive Polymer Capacitor Market