
 Structure Tester Market | 2026-2036
Structure Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Structure Tester Market Outlook
Buyer concentration across civil engineering contractors is restructuring procurement patterns for structural testing equipment, with larger infrastructure conglomerates consolidating vendor relationships and demanding integrated service contracts. Instron leverages its R&D intensity to maintain technology leadership in dynamic load simulation systems. MTS Systems anchors its position through geographic dominance in North American transportation infrastructure testing. ZwickRoell differentiates via product specialization in high-force universal testing machines for composite materials.
A structure tester is a mechanical or electromechanical device engineered to apply controlled static, dynamic, or impact loads to materials and assemblies, typically achieving force capacities from kilonewtons to meganewtons with displacement resolution down to micrometers, primarily to verify compliance with design specifications and safety codes. Universal testing machines command the largest installed base across quality control laboratories, though digital technology platforms are displacing mechanical systems as contractors prioritize automated data acquisition and real-time compliance reporting. Construction applications sustain the deepest demand pool, while aerospace testing requirements generate the highest per-unit margins due to stringent fatigue-cycle validation protocols.
FAA airworthiness directives, OSHA workplace safety mandates, and ISO 7500-1 calibration standards collectively shape equipment specifications, testing frequencies, and market access requirements across jurisdictions. China's SAMR enforces GB standards that mandate periodic structural verification for public buildings, directly expanding replacement demand for certified testing systems. Stakeholders must monitor how evolving building energy codes and climate-adaptation requirements will expand testing scope beyond traditional load-bearing parameters into thermal-cycling and moisture-ingress validation.
Market Dynamics
Digital testing platforms are compressing replacement cycles for mechanical systems as civil engineering contractors face mandatory compliance deadlines under China's updated GB standards and India's infrastructure quality mandates.
Growth Catalysts
- Seismic Resilience Certification:Asia-Pacific contractors are expanding testing protocols to meet stricter building codes for earthquake-prone zones, directly expanding equipment procurement in quality control laboratories.
- GB Standards Modernization:China's SAMR enforcement of updated structural safety regulations is compelling domestic manufacturers to abandon mechanical systems for digital platforms with automated reporting.
- High-Rise Commercial Development:India's infrastructure corridor projects are generating concentrated demand for load-bearing verification systems as quality control laboratories face mounting pressure from developers.
Market Restraints
- Sensor Component Concentration:Precision load cell manufacturing concentrates among specialized suppliers in Germany and Japan, creating vulnerability for equipment assemblers during supply disruptions.
- Calibration Infrastructure Gaps:ISO 7500-1 traceability requirements demand accredited facilities that remain scarce in emerging infrastructure markets, delaying equipment deployment.
- Capital Intensity Barrier:High-force universal testing machines require substantial upfront investment that fragments procurement authority among regional construction conglomerates rather than centralizing it.
Strategic Opportunities
- Composite Materials Testing:Aerospace fatigue-cycle validation protocols are creating premium-margin demand for specialized high-force systems as commercial aviation expands manufacturing capacity.
- Integrated Service Contracts:Large infrastructure conglomerates are consolidating vendor relationships and demanding bundled maintenance, calibration, and compliance reporting rather than equipment-only transactions.
- Climate-Adaptation Testing Scope:Evolving building energy codes are expanding validation requirements beyond load-bearing parameters into thermal-cycling and moisture-ingress protocols for envelope systems.
Industry Challenges
- Metrology Talent Scarcity:Equipment operators with expertise in dynamic load simulation and micrometer-resolution displacement measurement command premium compensation that strains laboratory operating budgets.
- Legacy System Integration:Contractors with installed mechanical testing platforms face complex retrofit requirements to achieve digital data acquisition compatibility without full replacement.
- Multi-Jurisdiction Certification:FAA airworthiness directives, OSHA workplace mandates, and ISO standards create overlapping compliance timelines that extend sales cycles for multinational equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structure Tester Market |
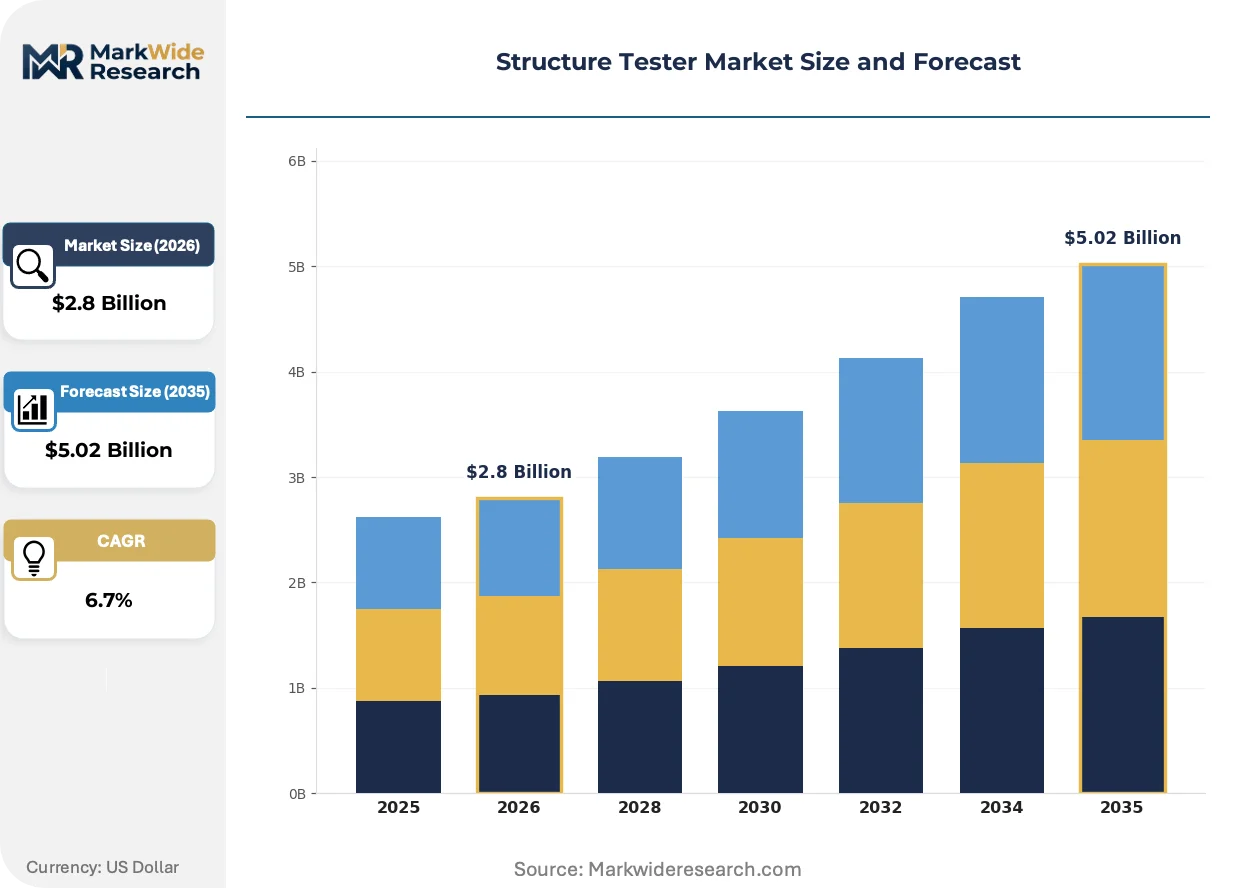
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Load Testers, Dynamic Load Testers, Impact Testers, Universal Testing Machines Application: Construction, Aerospace, Automotive, Manufacturing End User: Contractors, Engineers, Architects, Quality Control Laboratories Technology: Mechanical, Digital, Hydraulic, Pneumatic |
| Companies Covered | Instron, MTS Systems, ZwickRoell, Shimadzu Corporation, Ametek, Illinois Tool Works Inc., Controls S.p.A., Olson Instruments Inc., Humboldt Mfg. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structure Tester Market Strategic Shifts
Real-time compliance reporting capabilities are redefining competitive differentiation as buyers prioritize automated data acquisition over raw force capacity specifications in procurement decisions.
Electromechanical actuation with closed-loop digital control is integrating servo-hydraulic precision into compact universal testing platforms. Mid-sized civil engineering laboratories in India and Southeast Asia are adopting these systems at accelerating pace. This convergence is integrating fatigue testing and static load verification into single-platform workflows, compressing capital expenditure requirements for diversified service providers.
China's SAMR enforcement of updated GB standards for structural safety is mandating periodic verification protocols for public buildings. Equipment specifications now require traceable calibration chains and automated documentation that mechanical systems cannot satisfy. Domestic Chinese manufacturers are responding by accelerating partnerships with European sensor suppliers to achieve certification compliance before enforcement deadlines.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into discrete calibration, software subscription, and remote diagnostic components. Large infrastructure conglomerates in North America and Asia-Pacific are driving this shift to optimize operational expenditure recognition. This restructuring is most visible in India's quality control laboratory sector, where contractors now procure testing capacity as metered services rather than capital assets.
Structure Tester Market Segmentation
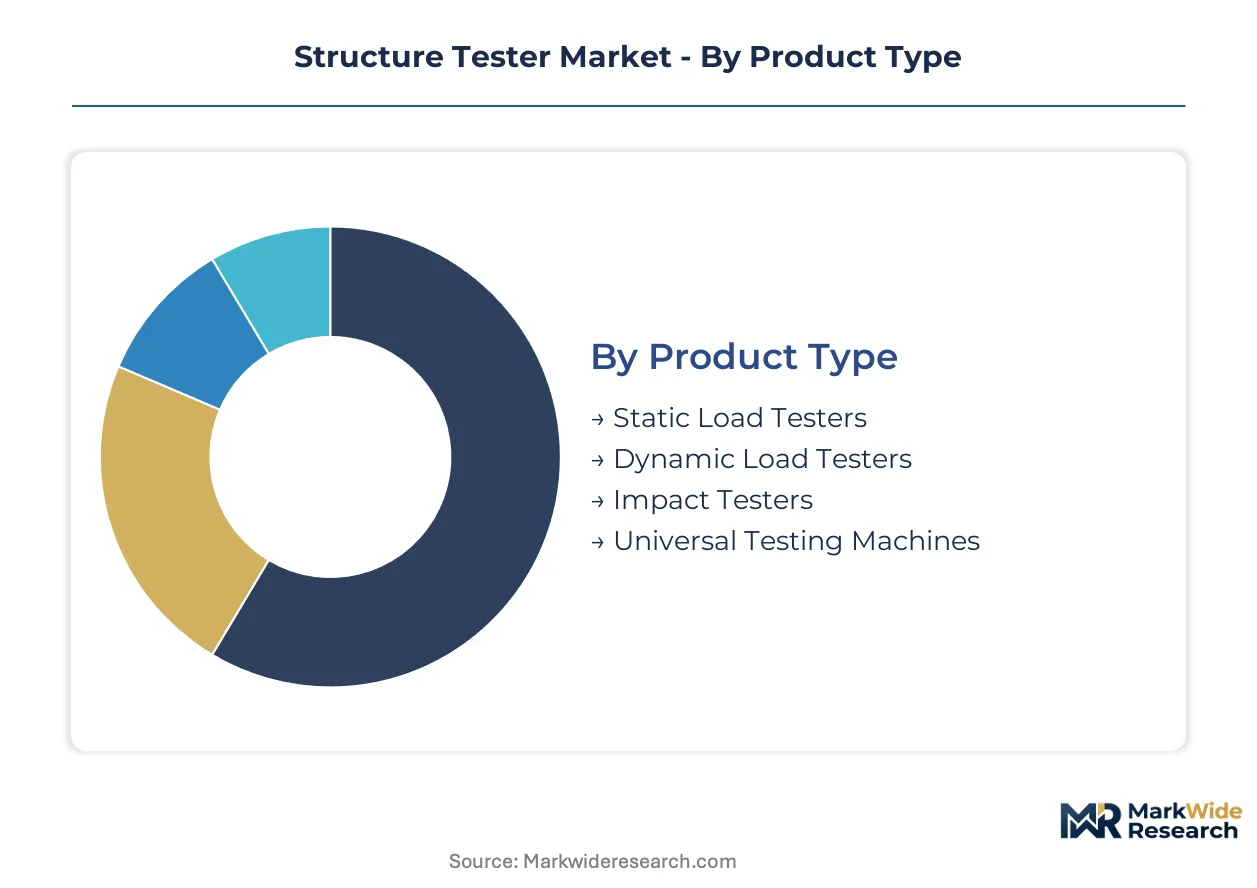
Equipment specification varies sharply across buyer workflows, with seismic certification mandates in Asia-Pacific and FAA airworthiness protocols creating divergent performance requirements. Segmentation reveals where procurement authority concentrates and which technology platforms capture replacement cycles.
Product Type:
Buyers differentiate primarily by force capacity requirements and automation needs rather than base mechanical function.
- Universal Testing Machines:Electromechanical platforms with closed-loop digital control integrate static, dynamic, and fatigue testing into single-platform workflows. India's quality control laboratories are adopting these systems at accelerating pace to compress capital expenditure across diversified service portfolios.
- Dynamic Load Testers:Servo-hydraulic and electromechanical actuation systems achieve precise cyclic loading for seismic resilience certification. Civil engineering contractors across China face SAMR-mandated replacement deadlines that favor digital platforms with automated GB standards compliance reporting.
- Static Load Testers:Conventional mechanical and hydraulic systems for compression and tensile verification.
- Impact Testers:Pendulum and drop-weight configurations for fracture toughness and material behavior analysis.
Universal testing machines lead volumes today; dynamic load testers are gaining share fastest.
Application:
Margin structure separates this category more than unit volume, with validation stringency determining pricing power.
- Construction:Load-bearing verification for high-rise commercial developments and infrastructure corridors dominates absolute equipment demand. India's quality control laboratories face mounting pressure from developers to certify structural integrity under updated national building codes.
- Aerospace:Fatigue-cycle validation protocols for airframe components and engine assemblies command premium per-unit margins. FAA airworthiness directives mandate specific testing frequencies and documentation standards that only specialized dynamic simulation systems satisfy.
- Automotive:Crashworthiness simulation and component durability testing for vehicle safety certification.
- Manufacturing:Incoming material verification and production-line quality assurance for industrial components.
Construction applications anchor procurement volumes; aerospace generates the steepest expansion trajectory in revenue per installation.
End User:
Procurement authority fragmentation across this category is restructuring vendor relationships toward integrated service contracts.
- Contractors:Large infrastructure conglomerates in Asia-Pacific are consolidating vendor relationships and demanding bundled maintenance, calibration, and compliance reporting rather than equipment-only transactions.
- Quality Control Laboratories:Independent testing facilities face ISO 7500-1 traceability requirements that strain operating budgets amid metrology talent scarcity.
- Engineers:Design validation and forensic analysis requirements for structural consulting practices.
- Architects:Specification development and performance verification for building envelope systems.
Contractors lead volumes today; quality control laboratories are expanding procurement fastest as third-party certification mandates proliferate.
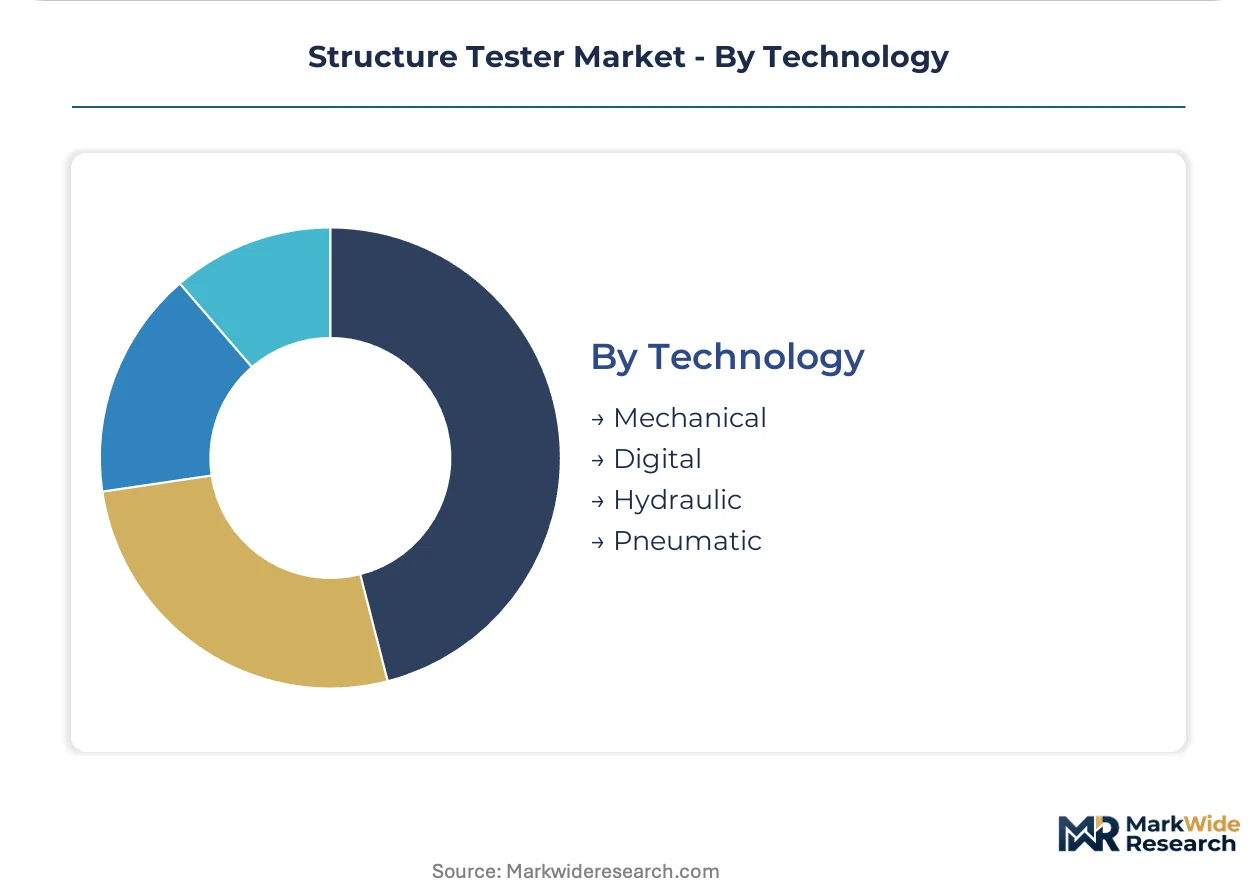
Technology:
Platform displacement is compressing replacement cycles as compliance deadlines favor automated data acquisition over legacy mechanical reliability.
- Digital:Closed-loop control with real-time compliance reporting and automated documentation satisfies China's GB standards modernization and India's infrastructure quality mandates. Domestic Chinese manufacturers are accelerating partnerships with European sensor suppliers to achieve SAMR certification before enforcement deadlines.
- Hydraulic:High-force applications in seismic simulation and aerospace fatigue testing maintain installed base where electromechanical alternatives lack force capacity.
- Mechanical:Legacy installations face complex retrofit requirements to achieve digital data acquisition compatibility without full replacement.
- Pneumatic:Lower-force applications in manufacturing quality assurance and rapid-cycle testing environments.
Mechanical systems retain the largest installed base; digital platforms are climbing the fastest as mandatory compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforcement of updated GB standards is compressing replacement cycles faster than India's infrastructure corridor expansion, creating divergent equipment procurement timelines across Asia-Pacific quality control networks.
China
Domestic manufacturers face mandatory migration from mechanical to digital testing platforms under SAMR's structural safety verification protocols. GB standards modernization mandates automated documentation chains for public buildings. Equipment assemblers in Shanghai and Jiangsu province are accelerating partnerships with European sensor suppliers to meet certification deadlines.
India
Quality control laboratories in Mumbai and Delhi-NCR face mounting pressure from high-rise commercial developers to certify load-bearing capacity. National building code updates require third-party structural verification for infrastructure corridor projects. Maharashtra and Gujarat states concentrate procurement authority among regional construction conglomerates consolidating vendor relationships.
United States
FAA airworthiness directives sustain premium-margin demand for fatigue-cycle validation systems in aerospace manufacturing clusters. OSHA workplace safety mandates shape equipment specifications for civil engineering contractors. Seattle and Wichita metropolitan areas anchor specialized testing service providers serving commercial aviation supply chains.
Germany
Precision load cell manufacturing concentrates among specialized suppliers serving equipment assemblers across Europe. REACH and CE marking requirements influence sensor component specifications for export-oriented testing platforms. Bavaria and Baden-Württemberg host metrology calibration facilities addressing ISO 7500-1 traceability gaps.
Japan
METI industrial standards enforcement maintains stringent displacement resolution requirements for materials testing equipment. JIS certification protocols shape procurement specifications for domestic quality control laboratories. Tokyo and Osaka metropolitan areas concentrate R&D-intensive manufacturers developing electromechanical actuation systems.
Structure Tester Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment categories, with universal testing machines showing higher consolidation than dynamic load simulation systems. The vendor base separates into three strategic archetypes: technology-intensive R&D leaders, geographic stronghold defenders, and product specialization niche players. M&A activity concentrates among sensor component suppliers, while strategic partnerships dominate between domestic Chinese manufacturers and European calibration technology providers.
Among technology-intensive specialists, Instron exemplifies R&D-driven positioning in dynamic load simulation, while MTS Systems anchors North American transportation infrastructure testing relationships. ZwickRoell occupies the product specialization tier for high-force universal testing applications. These three companies represent distinct competitive vectors—R&D intensity, geographic dominance, and technical focus—that structure procurement decisions among large infrastructure conglomerates.
| Leading Market Players |
|---|
| Instron |
| MTS Systems |
| ZwickRoell |
| Shimadzu Corporation |
| Ametek |
| Illinois Tool Works Inc. |
| Controls S.p.A. |
| Olson Instruments Inc. |
| Humboldt Mfg. Co. |
| Others |
Value Chain & Pricing Dynamics
Steel price indices and rare-earth magnet costs cascade through structure tester manufacturing, compressing margins for mechanical-system assemblers while digital-platform vendors capture premium pricing through sensor-integrated differentiation.
Pricing Analysis
Capacity additions in China are reshaping price floors for entry-level universal testing machines as domestic manufacturers achieve SAMR certification. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade fatigue systems from construction verification equipment. Price differentiation hinges on ISO 7500-1 calibration tier and after-sales service bundling. Cost compression in economy-tier mechanical systems is intensifying because European sensor suppliers command fixed component pricing.
Supply Chain Analysis
Dual-sourcing requirements for precision load cells are forcing equipment assemblers to qualify secondary suppliers beyond Germany and Japan. Component manufacturing concentrates in China, Germany, and Japan for electromechanical actuation systems. Raw material dependencies include high-grade steel alloys, rare-earth permanent magnets, and strain-gauge substrates. Single-source vulnerability in displacement sensor technology creates exposure during trade disruption scenarios. Distribution runs through authorized service networks with integrated calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in structure testing equipment rests on the shift from capital-sale models to metered-service contracts, capturing recurring revenue streams from quality control laboratories facing talent scarcity.
For Market Incumbents: Anchor technology leadership through backward integration into sensor calibration capabilities, insulating against European supplier concentration. Defensive consolidation should prioritize acquiring regional service networks in India's infrastructure corridor states. Threat from domestic Chinese manufacturers with SAMR-certified platforms demands accelerated R&D in climate-adaptation testing protocols. For New Entrants and Emerging Players: Begin with white-space targeting of mid-tier quality control laboratories in Southeast Asia seeking electromechanical platforms without full servo-hydraulic investment. India's Maharashtra and Gujarat states offer the most penetrable geography given fragmented procurement authority among regional construction conglomerates. Go-to-market angle should emphasize metered-service contracting to bypass capital-intensity barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with precision sensor suppliers achieving dual qualification across Chinese and European equipment assemblers. Long-term viability favors targets with captive calibration infrastructure addressing ISO 7500-1 traceability gaps. Watch for inflection in China's GB standards enforcement timelines accelerating replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Partnership | Domestic Chinese manufacturers accelerate European supplier alliances to meet SAMR certification deadlines. |
| Integrated Service Contract Expansion | Large infrastructure conglomerates consolidate vendor relationships around bundled maintenance and compliance reporting. |
| Climate-Adaptation Protocol Development | Equipment specifications expand beyond load-bearing into thermal-cycling validation for building envelope systems. |
| Calibration Infrastructure Investment | Quality control laboratories address ISO 7500-1 traceability gaps through accredited facility partnerships. |
| Electromechanical Platform Convergence | Mid-sized laboratories adopt closed-loop digital systems integrating fatigue and static testing workflows. |
Study Parameters
Direct dialogue with equipment procurement managers at civil engineering contractors, quality control laboratory directors, metrology calibration specialists, and aftermarket service heads grounded the demand-side assessment. Secondary validation drew from SAMR regulatory filings, BIS building code updates, FAA airworthiness directives, ISO 7500-1 accreditation databases, and customs trade records for testing equipment imports. Bottom-up equipment deployment estimates triangulated against top-down infrastructure spending projections.
Segment-level outputs across the modeling period reflect product type, application stringency, end-user procurement authority, and technology platform displacement velocity. CAGRs derived from equipment replacement cycle compression under mandatory compliance deadlines, aerospace manufacturing capacity expansion, and third-party certification proliferation. Industry-specific inputs included seismic resilience certification adoption curves and GB standards enforcement timelines.
Caveats apply where SAMR enforcement delays or sensor supply disruptions could materially shift the outlook. Deviation in India's infrastructure corridor completion schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
Roughness Tester Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Digital Comparators Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Ultrasonic Thickness Gauge Market