
 IF Digital Attenuator Market | 2026-2036
IF Digital Attenuator Market Size, Share, and Industry Trends Forecast 2026-2036
IF Digital Attenuator Market Foresight
Software-defined attenuation is expanding as a service layer that vendors bundle with field-programmable gate arrays and API-accessible calibration routines. Analog Devices, Inc leverages its mixed-signal portfolio to anchor high-precision programmable attenuator lines for instrumentation customers. Qorvo, Inc competes through GaN technology leadership in defense-grade variable attenuators with extended temperature ranges.
An IF digital attenuator is a solid-state RF component that adjusts signal amplitude in intermediate frequency stages through digitally controlled switching networks, typically operating from 1 MHz to 3 GHz with 0.25 dB to 1 dB step resolution for receiver gain control and transmitter power leveling. Programmable attenuators command premium positioning because test equipment manufacturers require repeatable calibration cycles across automated measurement systems. CMOS-based designs occupy cost-sensitive telecommunications infrastructure while RF MEMS variants sustain niche adoption in aerospace applications demanding minimal insertion loss.
FCC Part 15 emissions standards and ITAR export controls from the United States shape product architectures by mandating shielding performance tiers and restricting GaN technology transfers. EAR dual-use classification reviews from the Bureau of Industry and Security further complicate cross-border sales for defense-relevant attenuator specifications. Stakeholders must monitor evolving semiconductor export restrictions and frequency reallocation proceedings to anticipate which attenuator bandwidth and linearity specifications will carry regulatory premiums.
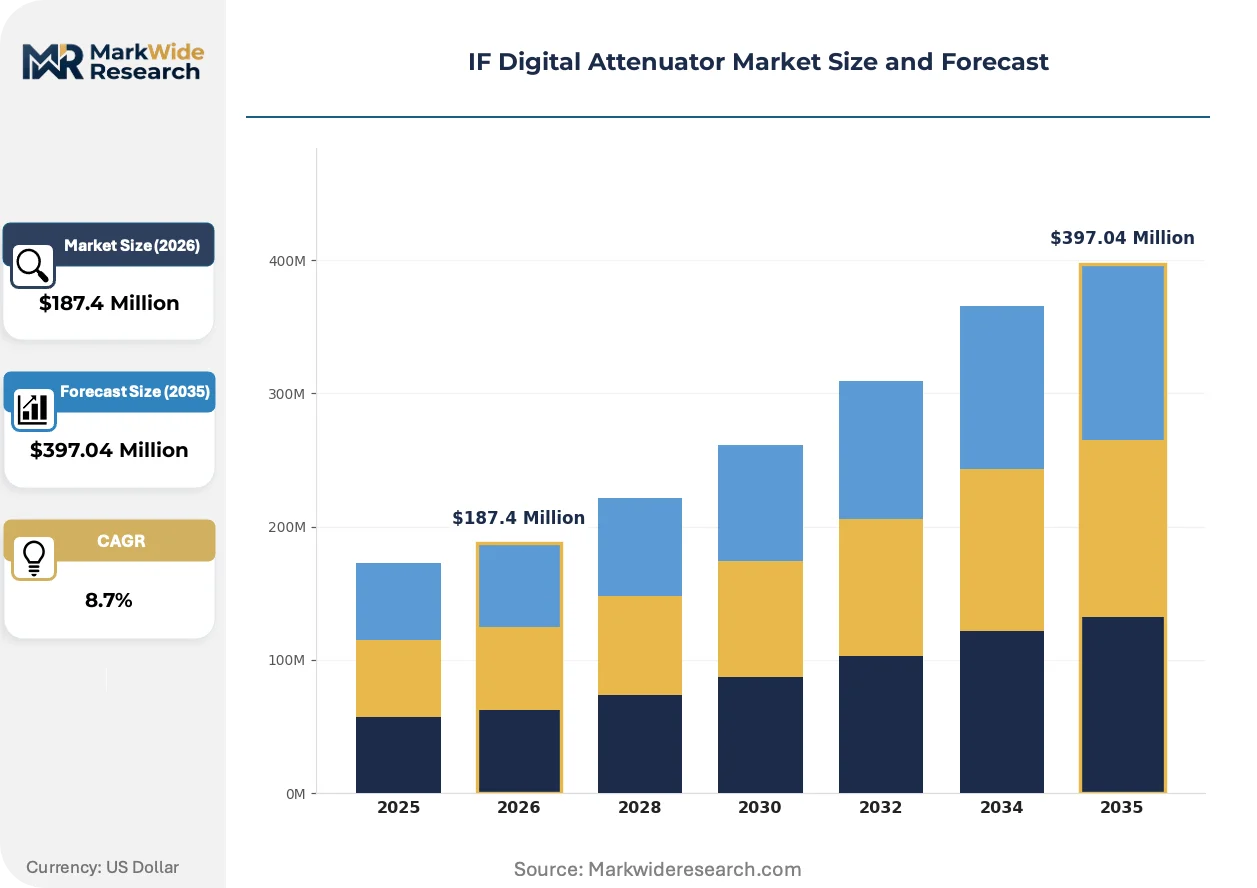
Market Dynamics
Defense procurement cycles and GaN-on-SiC process maturation are compressing design timelines while elevating performance thresholds for programmable attenuators across radar and test instrumentation sectors.
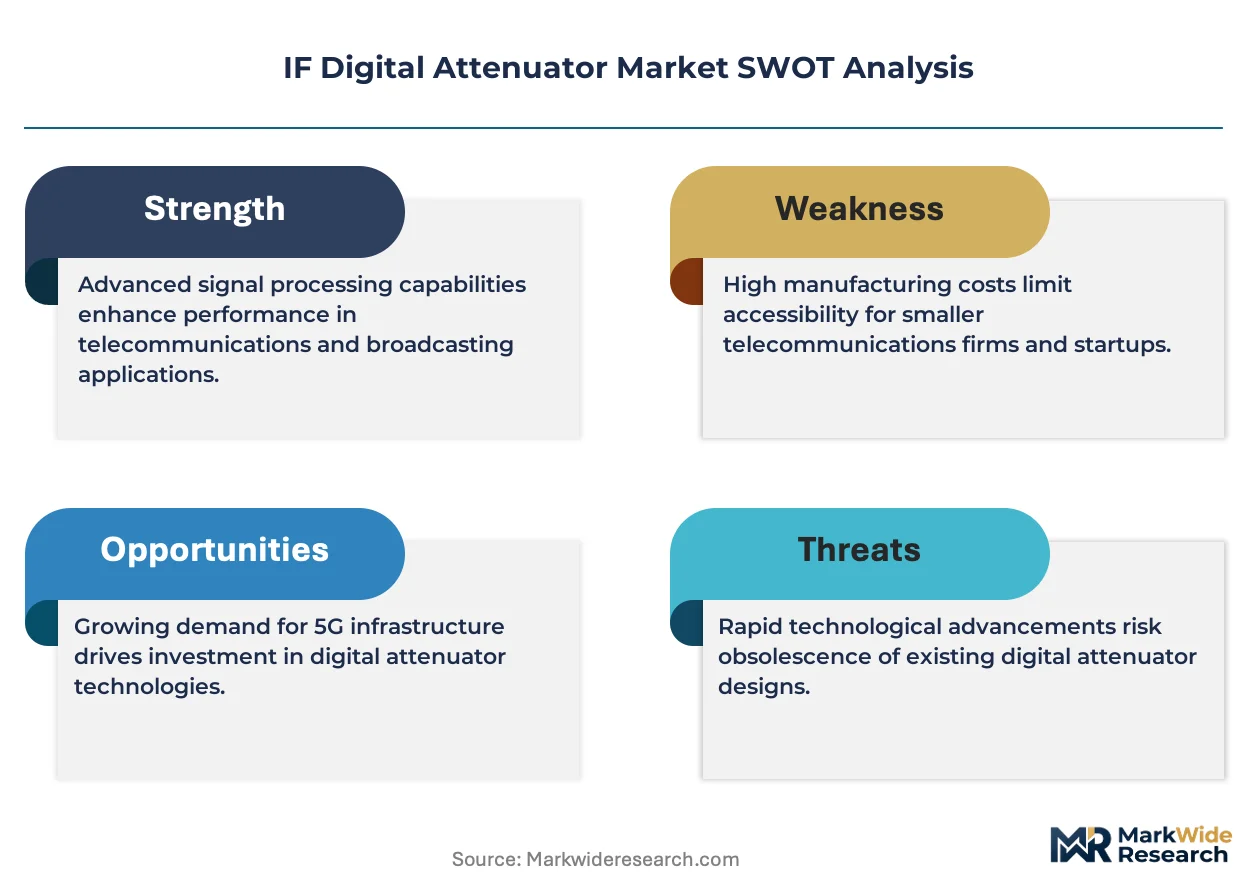
Growth Catalysts
- ITAR-controlled defense programs:United States military modernization mandates precision RF components for electronic warfare suites, creating captive demand for temperature-hardened programmable attenuators.
- 5G infrastructure densification:Base station deployments in China and Germany require stepped attenuators for transmitter power leveling across sub-6 GHz bands.
- GaN-on-SiC epitaxy advances:Foundry process improvements from Japan and the United States are extending linearity margins and thermal handling in compact form factors.
Market Restraints
- Gallium nitride substrate costs:SiC wafer supply concentration in limited foundry locations elevates bill-of-materials volatility for high-linearity variants.
- EAR dual-use classification:Bureau of Industry and Security reviews impose documentation burdens and shipment delays on defense-relevant attenuator specifications.
- RF MEMS reliability ceilings:Mechanical switching fatigue limits operational lifespan in high-cycle aerospace applications despite superior insertion loss performance.
Strategic Opportunities
- API-integrated calibration services:Software-defined attenuation layers bundled with FPGA control logic open recurring revenue streams in automated test equipment.
- India telecom infrastructure:TRAI-mandated spectrum auctions and rural network expansion create demand for cost-optimized CMOS-based attenuator volumes.
- Space-qualified component gaps:Low-Earth orbit satellite constellations require radiation-tolerant programmable attenuators with extended temperature ranges.
Industry Challenges
- MMIC design talent scarcity:Mixed-signal RF engineering expertise concentrates in established defense hubs, constraining foundry capacity expansion.
- FCC Part 15 shielding certification:Emissions compliance testing extends product qualification timelines for instrumentation customers requiring rapid calibration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IF Digital Attenuator Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Attenuators, Programmable Attenuators, Variable Attenuators, Novel Design Attenuators Technology: GaN, CMOS, RF MEMS, Analog Devices Application: Telecommunications, Aerospace, Defense, Research Laboratories End User: Telecom Providers, Equipment Manufacturers, Research Institutions, Government Agencies |
| Companies Covered | Analog Devices, Inc, Qorvo, Inc, MACOM Technology, NXP Semiconductors, Renesas Electronics, Keysight Technologies, Inc., Peregrine Semiconductor, Cobham plc, API Technologies Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IF Digital Attenuator Market Shifts & Advancements
Silicon carbide substrate integration and software-defined control architectures are redefining performance benchmarks while regulatory export frameworks reshape competitive access.
GaN-on-SiC monolithic microwave integrated circuits are overtaking legacy GaAs-based attenuators in defense and instrumentation applications. Radar system integrators in the United States and Germany are specifying these devices for transmit-receive modules requiring simultaneous high power handling and precision step resolution. The technology is compressing form factor requirements while extending operational bandwidths beyond 3 GHz.
REACH substance restrictions and EU RoHS compliance deadlines are forcing material substitutions in packaging and metallization layers. Attenuator manufacturers serving European telecommunications and aerospace customers must reformulate solder compositions and surface finishes to maintain market access. German test equipment vendors are accelerating qualification cycles to meet 2024-2025 substance threshold deadlines.
Automated calibration routines accessed through vendor APIs are displacing manual bench-top configuration in high-volume manufacturing test environments. Contract manufacturers in China and Mexico are integrating these software interfaces into production lines for consumer electronics RF modules. Semiconductor test houses now specify attenuator procurement based on Python and LabVIEW library compatibility rather than standalone hardware specifications.
IF Digital Attenuator Market Segmentation
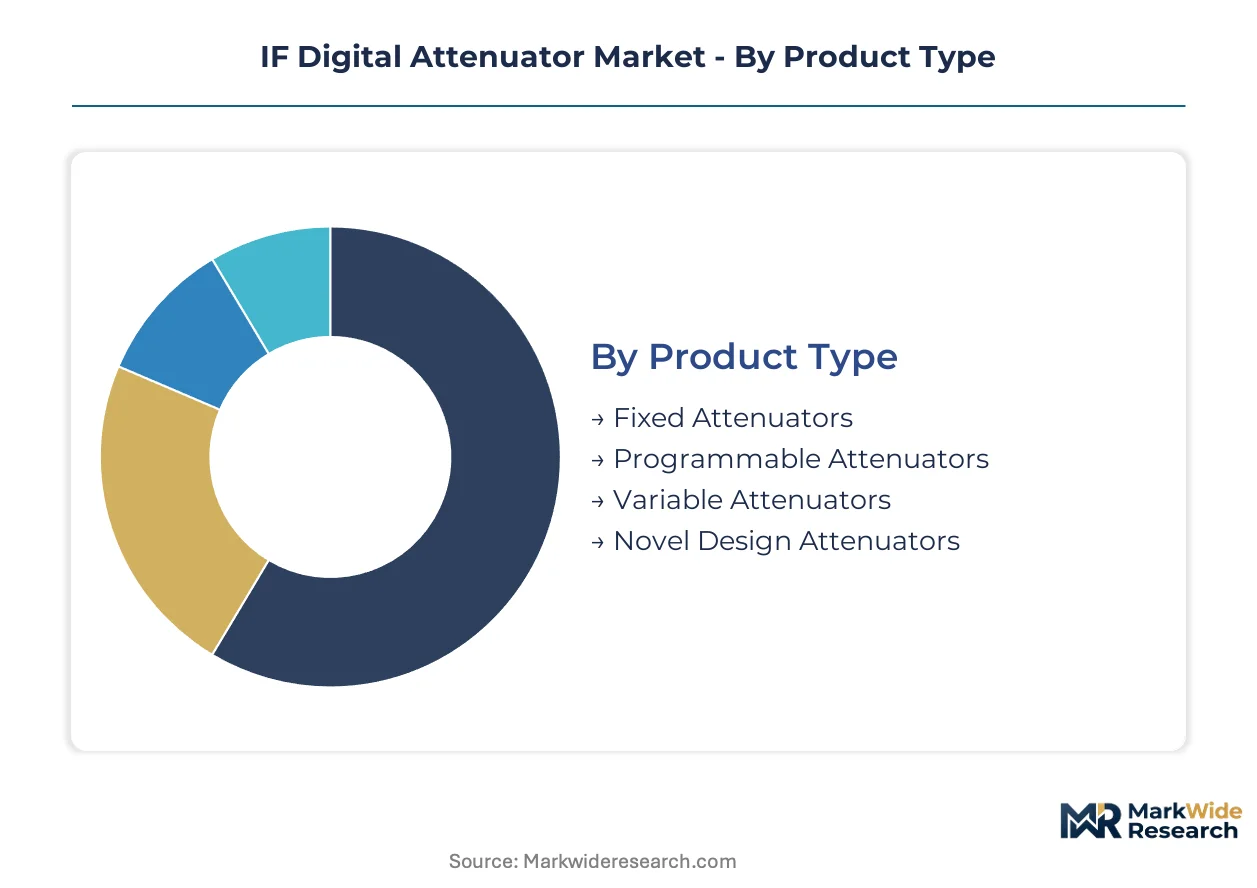
IF digital attenuator procurement patterns diverge sharply across product architectures and control interfaces, with defense programs favoring programmable precision while telecommunications infrastructure prioritizes cost-optimized fixed attenuation volumes.
Product Type:
Supply concentration in high-linearity variants tilts manufacturing capacity toward programmable and variable architectures, leaving fixed attenuator production fragmented across commodity foundries.
- Fixed Attenuators:Passive resistive networks deliver predetermined attenuation levels from 0 dB to 30 dB without active control circuitry. Chinese base station OEMs in Shenzhen and Chengdu absorb volume shipments for 5G transmitter power leveling where calibration tolerance requirements remain loose.
- Programmable Attenuators:Digitally switched PIN diode or FET networks enable 0.25 dB step resolution under SPI or I2C command. United States defense contractors in Massachusetts and California specify these for electronic warfare receiver gain control where temperature stability across -55°C to +125°C is mandatory.
- Variable Attenuators:Continuously adjustable analog control suits instrumentation applications requiring smooth amplitude transitions. Test equipment manufacturers in Germany integrate these for automated calibration cycles.
- Novel Design Attenuators:Emerging topologies including distributed MEMS and metamaterial structures address niche aerospace insertion loss requirements. Satellite constellation builders in Colorado and Toulouse evaluate prototypes for low-Earth orbit signal conditioning.
Today's leader: Programmable Attenuators. Tomorrow's challenger: Novel Design Attenuators.
Technology:
Process node economics separate premium GaN-on-SiC fabrication from high-volume CMOS integration, with RF MEMS occupying a narrow reliability-constrained middle tier.
- GaN:Gallium nitride on silicon carbide substrates delivers 40+ dBm power handling and superior linearity for radar transmit-receive modules. Foundries in Japan and the United States control epitaxial supply, restricting access for non-ITAR customers.
- CMOS:Silicon-based designs leverage mature 180nm to 65nm nodes for sub-6 GHz telecommunications infrastructure. Indian telecom providers under TRAI-mandated rural expansion programs drive cost-sensitive procurement.
- RF MEMS:Microelectromechanical switches achieve sub-0.5 dB insertion loss through capacitive or ohmic contact mechanisms. Mechanical fatigue limits operational lifespan below 100 million cycles despite aerospace demand for minimal signal degradation.
- Analog Devices:Proprietary mixed-signal architectures combine attenuation cells with integrated ADCs for self-calibrating instrumentation channels. Semiconductor test houses specify these for Python-automated measurement workflows.
GaN commands the premium tier. CMOS scales fastest.
Application:
End-use performance thresholds stratify procurement specifications, with defense and aerospace mandating extended temperature ranges that telecommunications infrastructure can disregard.
- Telecommunications:Base station deployments across sub-6 GHz bands require stepped attenuation for transmitter power control and receiver dynamic range management. China's MIIT spectrum allocations and Germany's BNetzA licensing frameworks shape regional specification clusters.
- Aerospace:Satellite payload designers prioritize radiation tolerance and thermal cycling resilience over cost metrics. Low-Earth orbit constellation operators in the United States and France specify qualified attenuators for phased array antennas.
- Defense:Electronic warfare and radar systems demand programmable attenuators with microsecond switching speed and MIL-STD-883 qualification. EAR classification from the United States Bureau of Industry and Security restricts technology transfer.
- Research Laboratories:Metrology-grade instrumentation requires 0.1 dB absolute accuracy and traceable calibration certificates. National standards institutes in Germany and Japan anchor demand.
Defense anchors premium pricing. Telecommunications drives volume scale.
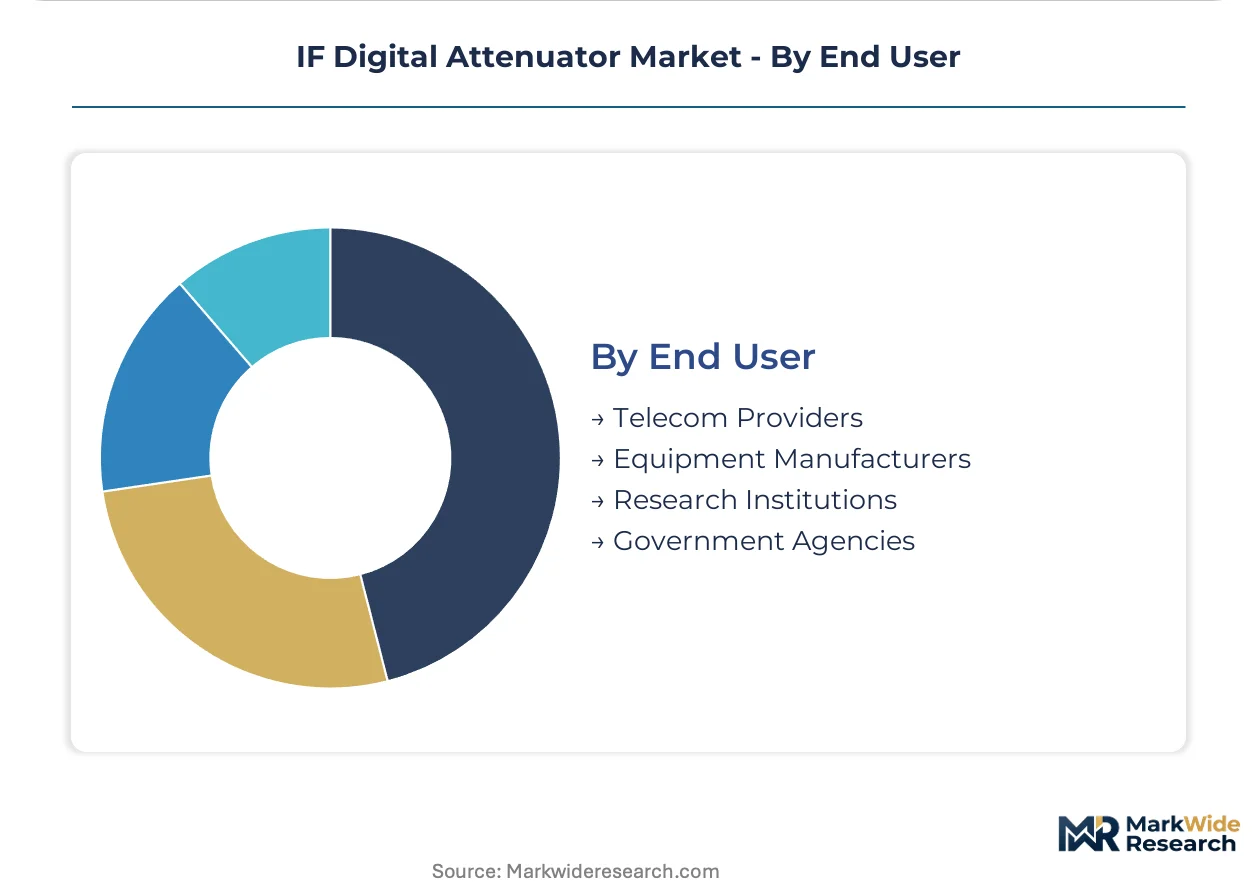
End User:
Procurement authority concentration differs across institutional buyers, with government agencies exercising ITAR-constrained sole-source authority while equipment manufacturers compete on total cost of ownership.
- Telecom Providers:Network operators in China, Germany, and India specify attenuators through RF subsystem vendors rather than direct component procurement. TRAI-mandated rural coverage obligations expand addressable volume.
- Equipment Manufacturers:Base station OEMs and test instrument builders integrate attenuators into higher-level assemblies. FCC Part 15 emissions certification burdens fall on these integrators rather than component suppliers.
- Research Institutions:Universities and national laboratories procure attenuators through grant-funded acquisition channels with extended qualification timelines. Python and LabVIEW library compatibility now dominates technical evaluation criteria.
- Government Agencies:United States Department of Defense programs mandate domestic source qualification under ITAR and Buy American provisions. Bureau of Industry and Security EAR reviews complicate cross-border procurement.
Equipment Manufacturers intermediate today's volume. Government Agencies dictate tomorrow's specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with lower compliance burdens for dual-use RF components, while defense procurement concentration keeps design expertise anchored in ITAR-controlled territories.
United States
Department of Defense electronic warfare modernization and radar transmit-receive module upgrades drive precision attenuator demand. ITAR export controls from the Bureau of Industry and Security restrict technology transfer and create captive domestic sourcing requirements. Massachusetts and California defense contractors specify temperature-hardened programmable attenuators for MIL-STD-883 qualified systems.
China
MIIT-mandated 5G base station densification across sub-6 GHz bands requires stepped attenuators for transmitter power control. GB standards compliance and domestic semiconductor substitution policies favor local CMOS-based foundry capacity. Shenzhen and Chengdu OEMs absorb volume shipments for telecommunications infrastructure buildouts.
Germany
BNetzA spectrum licensing frameworks and test equipment manufacturer demand anchor precision attenuator procurement. REACH substance restrictions and RoHS compliance deadlines force packaging material substitutions. Munich and Stuttgart instrumentation vendors accelerate qualification cycles for automated calibration systems.
Japan
METI-supported GaN-on-SiC epitaxy advances extend linearity margins for radar and satellite applications. JIS standards certification and foundry process improvements concentrate high-linearity fabrication capacity. Tokyo and Osaka foundries supply monolithic microwave integrated circuits to defense and aerospace integrators.
India
TRAI-mandated rural network expansion and spectrum auctions create demand for cost-optimized attenuator volumes. PLI scheme incentives for telecommunications equipment manufacturing attract component sourcing shifts. Bangalore and Hyderabad telecom providers specify CMOS-based designs for sub-6 GHz infrastructure.
IF Digital Attenuator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense-grade programmable attenuators consolidating around ITAR-qualified domestic sources while telecommunications infrastructure fragments across cost-optimized foundries. Three archetypes dominate: GaN-on-SiC technology leaders serving radar integrators, CMOS-scale specialists capturing base station volumes, and mixed-signal instrumentation anchors bundling software-defined control layers. M&A activity concentrates on GaN epitaxy capacity acquisitions and API-integrated calibration service rollups.
Within the mixed-signal instrumentation tier, Analog Devices, Inc occupies a position exemplifying precision programmable architectures, while Qorvo, Inc represents GaN technology leadership for defense-grade variable attenuators. Among RF semiconductor specialists, MACOM Technology and NXP Semiconductors sit within the scale-driven segment serving telecommunications infrastructure with cost-optimized CMOS and GaAs alternatives.
| Leading Market Players |
|---|
| Analog Devices, Inc |
| Qorvo, Inc |
| MACOM Technology |
| NXP Semiconductors |
| Renesas Electronics |
| Keysight Technologies, Inc. |
| Peregrine Semiconductor |
| Cobham plc |
| API Technologies Corp |
| Others |
Supply & Pricing Matrix
SiC wafer substrate costs cascade through three distinct pricing tiers, with Japanese and United States foundry premiums compressing margins for defense-grade GaN-on-SiC programmable attenuators while Chinese CMOS foundries anchor economy positioning for telecommunications infrastructure.
Pricing Analysis
Distributor margins of 15-25% separate direct-to-OEM contract pricing from catalog distribution for instrumentation customers. Pricing stratifies across ITAR-qualified precision tiers, RoHS-compliant mid-range offerings, and cost-optimized CMOS volumes for Indian and Chinese telecom deployments. Cost compression in the CMOS tier is intensifying because TRAI-mandated rural network expansion demands sub-dollar component economics. Research institutions exhibit lowest price sensitivity due to grant-funded procurement cycles, while contract manufacturers in Mexico and China face acute margin pressure on consumer electronics RF modules.
Supply Chain Analysis
United States ITAR domestic-content mandates and India's PLI scheme incentives are reshaping sourcing patterns away from pure cost optimization toward compliance-weighted supplier selection. Epitaxial supply concentrates in Japan, the United States, and Taiwan for GaN-on-SiC wafers, while CMOS fabrication rests on mature nodes in China, Taiwan, and India. Raw material dependencies include high-purity SiC substrates, gallium metal feedstock, and specialized ceramic packaging compounds. Single-source vulnerability runs through Japanese foundry capacity for defense-qualified epitaxy. Distribution runs through authorized distributors serving test equipment OEMs and direct foundry relationships for defense prime contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are compressing toward premium programmable architectures as electronic warfare specifications harden temperature and linearity requirements beyond commodity CMOS capabilities.
For Market Incumbents: Deepen backward integration into SiC substrate supply through long-term offtake agreements with Japanese and United States foundries to defend against gallium nitride cost volatility. Anchor certification investment in MIL-STD-883 and EAR dual-use compliance to maintain ITAR-captive positioning against emerging GaAs substitute threats from Chinese vendors.
For New Entrants and Emerging Players: India's PLI scheme for telecommunications equipment manufacturing opens a window for cost-optimized CMOS attenuator volumes serving TRAI-mandated rural base station expansion. Target the Mexico-based contract manufacturing test environment segment through Python and LabVIEW library compatibility as the most penetrable white-space channel, with API-integrated calibration services as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Consolidation pressure builds where GaN epitaxy capacity scarcity meets defense procurement concentration in Massachusetts and California corridors. Five-to-ten year viability favors vertically integrated specialists with captive SiC substrate access and ITAR-qualified domestic fabrication. Watch Bureau of Industry and Security export restriction expansions as the critical inflection signal for premium tier repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Epitaxy Capacity Expansion | Japanese foundry investments extend linearity margins for radar transmit-receive modules. |
| API-Integrated Calibration Service Rollup | Software-defined attenuation layers capture recurring revenue from semiconductor test houses. |
| ITAR-Qualified Domestic Sourcing | Massachusetts and California defense contractors mandate captive supply chains. |
| RoHS Compliance Material Substitution | German test equipment vendors accelerate qualification for REACH substance deadlines. |
| CMOS Scale Manufacturing Partnership | Indian PLI incentives attract cost-optimized attenuator production for sub-6 GHz infrastructure. |
Research Methodology
Bottom-up defense and telecommunications infrastructure modeling reconciled against top-down GaN and CMOS foundry capacity tracking forms the analytical core of this study. Primary interviews with RF subsystem procurement managers, MMIC design engineers, test equipment product managers, and Bureau of Industry and Security compliance officers combined with secondary validation from FCC Part 15 filings, EAR classification databases, SEC 10-K disclosures from listed semiconductor vendors, and METI-supported GaN epitaxy research publications. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map attenuator demand across product architecture, technology node, application performance threshold, and end-user procurement authority dimensions over the projection horizon. CAGRs derive from segment-level unit economics calibrated to foundry capacity expansion announcements and defense procurement budget trajectories. Forecast inputs include GaN-on-SiC wafer pricing indices and TRAI spectrum auction timelines for Indian telecommunications infrastructure.
Revisions become necessary when Bureau of Industry and Security export restrictions expand, SiC substrate supply disruptions materialize, or defense procurement cycles shift from modernization to sustainment phases. Forecasts reflect documented assumptions regarding foundry yield improvements and regulatory compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Primary Charge Roller Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
GPIO Expanders Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Data Bus Market
Electronic Components
Industrial Relays Market
Electronic Components
Trackpad Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Power Inductors Market
Electronic Components
Timing Relay Market
Electronic Components
Battery Holders Market
Electronic Components
Metal Oxide Varistor (MOV) Market
Electronic Components
Screw Washer Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Global Tantalum Capacitors Market