
 Rugged Display Market | 2026-2036
Rugged Display Market Size, Share, and Industry Trends Forecast 2026-2036
Rugged Display Market Analysis
Software-defined brightness calibration and remote fleet management is expanding as a recurring-revenue layer that shifts rugged display transactions from hardware-only sales to subscription-augmented contracts. Panasonic Corporation leverages its vertical integration into LCD panel fabrication to sustain cost discipline across military and industrial product lines. Getac Technology Corporation specializes in thermal-engineered chassis designs that dominate field-service and public-safety channels in Asia-Pacific.
A rugged display is a hardened electronic screen engineered to operate across extended temperature ranges, typically -20°C to 60°C, with ingress protection ratings of IP65 or higher and resistance to shock, vibration, and electromagnetic interference; manufacturers bond chemically strengthened cover glass to optically matched touch sensors to preserve readability under direct sunlight and through gloved-hand operation. LCD technology occupies the largest installed base due to mature supply chains and lower unit costs, while OLED is displacing legacy panels in avionics and night-vision-compatible applications where contrast ratio and power efficiency determine procurement decisions. Embedded installation formats are capturing margin pools in armored vehicle and maritime bridge retrofits, as integrators demand sealed units that bolt directly into existing console architectures without external cabling.
FAA airworthiness directives and MIL-STD-461 electromagnetic compatibility standards constrain design freedom for suppliers targeting aerospace and defense contracts, forcing multi-year qualification cycles that lock out unproven entrants. ECHA REACH restrictions on flame-retardant additives and heavy metals in electronics are reshaping material-selection protocols for European industrial customers. Stakeholders must monitor how NHTSA commercial-vehicle safety mandates and emerging EU Green Deal circularity requirements alter total-cost-of-ownership calculations for fleet operators evaluating rugged display refreshes.
Market Dynamics
MIL-STD-810 shock and vibration certification requirements are tightening qualification standards across defense supply chains, forcing manufacturers to redesign thermal-engineered chassis and bonding processes for chemically strengthened cover glass.
Growth Catalysts
- Battlefield Command Modernization:Military end users in the United States are expanding hardened display procurement for armored vehicle retrofits and maritime bridge installations, driving embedded-format demand.
- Factory-Floor Automation:Germany's industrial automation corridor concentrates tablet deployments that resist chemical exposure and thermal cycling, sustaining replacement cycles for IP65-rated panels.
- REACH Compliance Adaptation:ECHA restrictions on flame-retardant additives are accelerating material-selection protocol updates, creating first-mover advantages for suppliers with validated alternative chemistries.
Market Restraints
- Input Cost Volatility:Optical-grade indium tin oxide and chemically strengthened aluminosilicate glass face supply concentration from specialty chemical producers, compressing gross margins on mid-tier product lines.
- Qualification Cycle Lockout:FAA airworthiness directives and MIL-STD-461 electromagnetic compatibility standards enforce multi-year certification timelines that exclude unproven entrants from aerospace and defense contracts.
- Technology Substitution:OLED panels are displacing legacy LCD in avionics and night-vision-compatible applications where contrast ratio and power efficiency determine procurement decisions.
Strategic Opportunities
- Software-Defined Fleet Management:Remote brightness calibration and subscription-augmented contracts are shifting transactions from hardware-only sales to recurring-revenue models in field-service channels.
- EU Green Deal Circularity:Emerging circularity requirements for electronics are altering total-cost-of-ownership calculations for fleet operators evaluating display refreshes across European logistics networks.
- Asia-Pacific Public Safety:Thermal-engineered chassis designs are penetrating police and emergency-response vehicle installations in markets with limited incumbent presence.
Industry Challenges
- Multi-Domain Certification Complexity:Simultaneous compliance with MIL-STD-810, MIL-STD-461, and FAA directives requires specialized testing infrastructure that extends product development timelines.
- Optical Bonding Skill Scarcity:Manufacturing engineers capable of executing vacuum-bonded optically matched touch sensors with zero-defect yields remain concentrated at a small number of display integration facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugged Display Market |
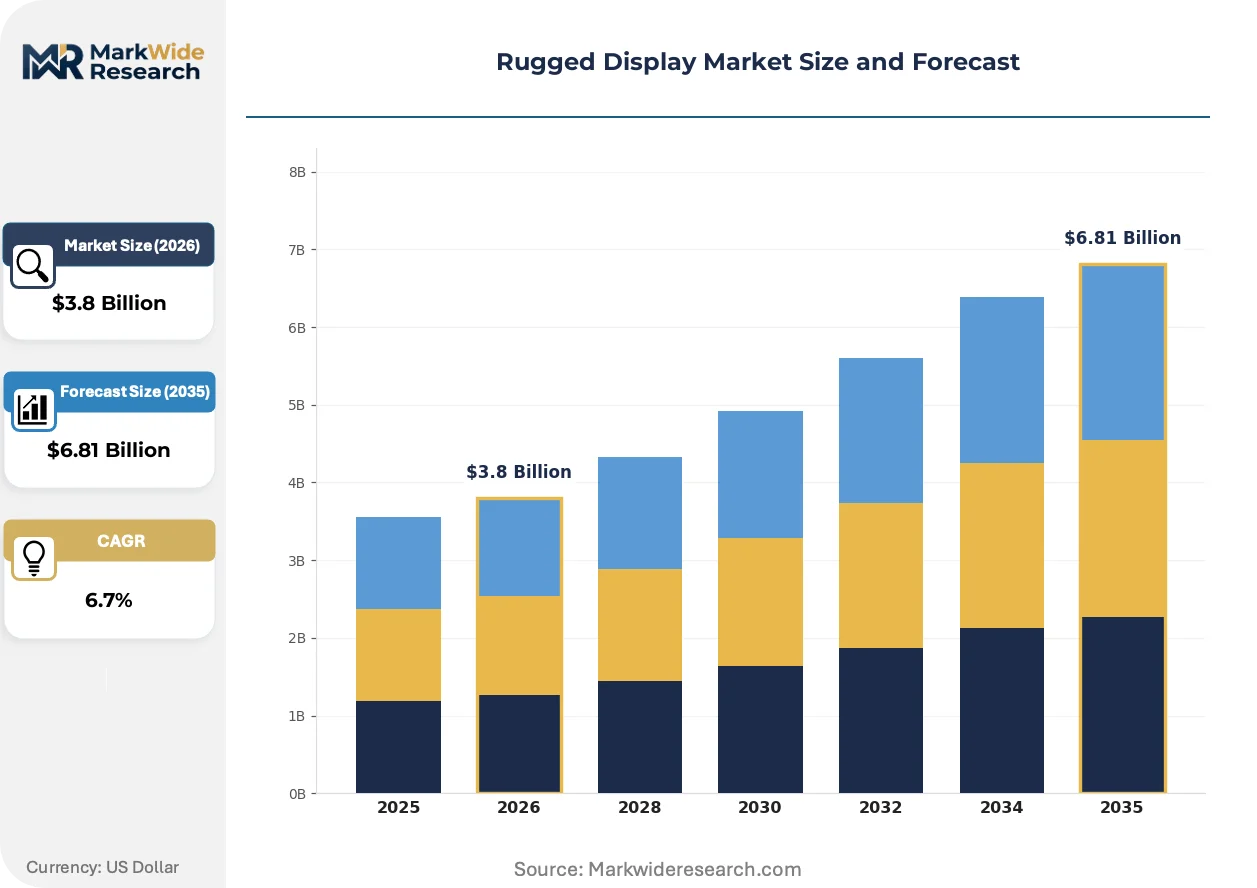
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Monitor, Smartphone, Display Module Technology: LCD, OLED, LED, E-Ink End User: Aerospace, Industrial, Military, Transportation Installation: Wall-Mounted, Portable, Embedded, Rack-Mounted |
| Companies Covered | Zebra Technologies Corporation, Panasonic Corporation, Dell Technologies Inc., Getac Technology Corporation, General Dynamics Corporation, Curtiss-Wright Corporation, L3Harris Technologies Inc., Kyocera Corporation, EIZO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugged Display Market Emerging Trajectories
Active-matrix OLED technology is converging with legacy LCD supply chains, reshaping how integrators specify contrast performance and power budgets for mission-critical applications.
AMOLED displays with circular polarizer stacks eliminate washout under direct sunlight while maintaining night-vision compatibility. Avionics integrators are adopting these panels for cockpit retrofit programs at accelerated replacement cycles. The technology is converging with existing MIL-STD-461 qualification pathways, compressing the time-to-certification for new display architectures.
EU Green Deal circularity requirements are mandating end-of-life material recovery and restricted substance documentation for electronics deployed in member-state defense and transport fleets. Industrial customers must now validate supply-chain traceability for flame-retardant additives and heavy metals. German automotive and automation buyers are responding by pre-qualifying suppliers with established recycling partnerships and full material disclosure databases.
Buyers are unbundling after-sales service from hardware acquisition, negotiating standalone software-defined brightness calibration subscriptions for deployed fleets. System integrators and fleet operators are displacing traditional warranty-plus-repair contracts with usage-based monitoring agreements. This pattern is most visible in United States military and public-safety verticals where remote diagnostics reduce field-service dispatch costs.
Rugged Display Market Segmentation
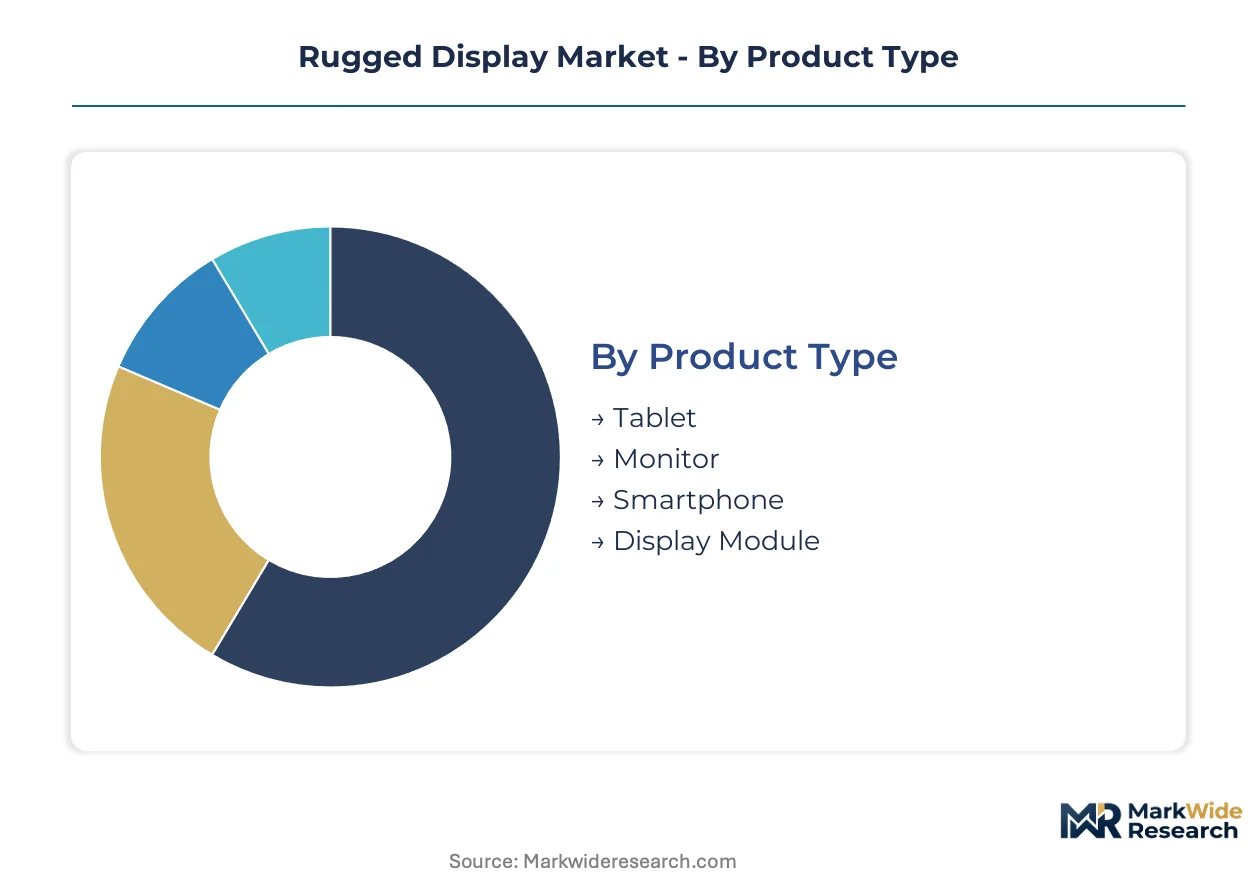
Rugged display procurement patterns diverge sharply across product formats and deployment contexts. Capital allocation, certification requirements, and replacement cycles vary by segment, forcing suppliers to maintain parallel qualification tracks.
Product Type:
Capital intensity peaks in display modules requiring custom optical bonding and MIL-STD-810 chassis engineering, while tablets and smartphones leverage shared component platforms.
- Display Module:Custom optical bonding of chemically strengthened cover glass to matched touch sensors demands vacuum-bonding infrastructure with zero-defect yield requirements. Demand concentrates in United States armored vehicle retrofits and maritime bridge installations where embedded formats bolt directly into existing console architectures.
- Tablet:Factory-floor deployments in Germany's industrial automation corridor resist chemical exposure and thermal cycling through IP65-rated sealed enclosures. Panasonic Corporation sustains cost discipline through captive LCD panel fabrication.
- Monitor:Rack-mounted configurations dominate control room and command center installations.
- Smartphone:Field-service and public-safety channels in Asia-Pacific favor thermal-engineered chassis designs.
Most installed capacity flows through Tablet. Expansion is steepest in Display Module.
Technology:
Application requirements dictate technology selection, with night-vision compatibility and power efficiency driving specification divergence.
- LCD:Mature supply chains and lower unit costs sustain the largest installed base across industrial and transportation verticals. Germany's automotive and automation buyers pre-qualify suppliers with established recycling partnerships under EU Green Deal circularity requirements.
- OLED:Active-matrix architectures with circular polarizer stacks eliminate washout under direct sunlight while maintaining night-vision compatibility. Avionics integrators accelerate cockpit retrofit programs.
- LED:High-brightness configurations serve outdoor digital signage and extreme ambient light environments.
- E-Ink:Ultra-low power consumption supports extended field deployments without recharging infrastructure.
Volume concentration remains in LCD. Technology substitution is climbing the fastest in OLED.
End User:
Certification burden and procurement timeline length vary by vertical, with defense and aerospace imposing multi-year qualification cycles.
- Military:MIL-STD-461 electromagnetic compatibility and MIL-STD-810 shock and vibration standards enforce specialized testing infrastructure. United States battlefield command modernization expands hardened display procurement.
- Aerospace:FAA airworthiness directives constrain design freedom and extend development timelines. AMOLED panels compress time-to-certification through convergence with existing qualification pathways.
- Industrial:ECHA REACH restrictions on flame-retardant additives reshape material-selection protocols.
- Transportation:NHTSA commercial-vehicle safety mandates alter total-cost-of-ownership calculations for fleet operators.
Procurement value concentrates in Military. Regulatory adaptation is expanding most quickly in Industrial.
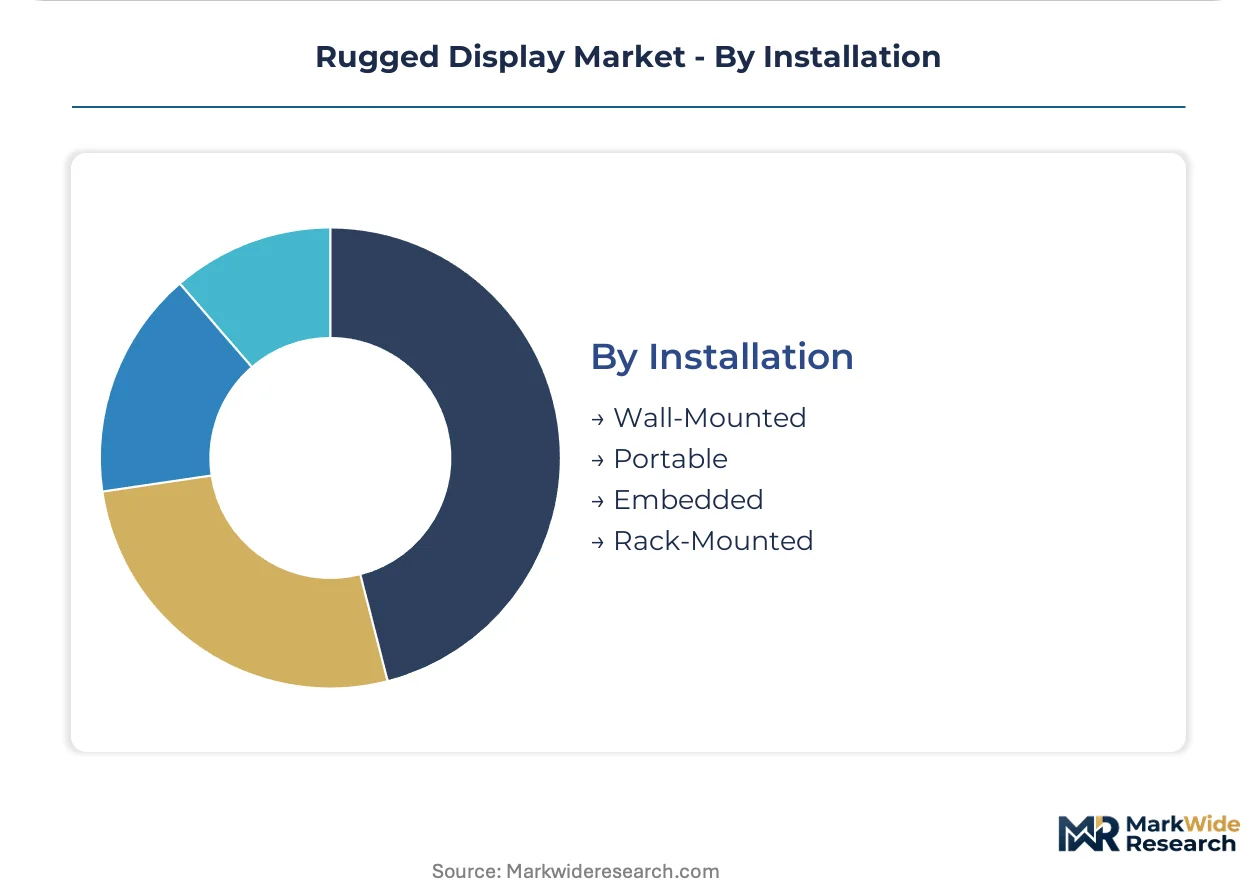
Installation:
Integration complexity and cabling requirements separate embedded formats from portable alternatives.
- Embedded:Sealed units bolt directly into armored vehicle and maritime console architectures without external cabling. Margin pools concentrate in retrofit programs.
- Portable:Field-service dispatch costs drive demand for remote diagnostics and software-defined brightness calibration subscriptions.
- Wall-Mounted:Fixed installations serve control room and facility monitoring applications.
- Rack-Mounted:Standardized form factors integrate into server and communications infrastructure.
Deployment share favors Portable. Integration value is gaining share fastest in Embedded.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States military procurement outpaces German industrial automation in absolute value, though both markets tighten certification standards that extend supplier qualification timelines.
United States
Battlefield command modernization drives hardened display procurement for armored vehicle retrofits and maritime bridge installations. FAA airworthiness directives and MIL-STD-461 electromagnetic compatibility standards enforce multi-year certification cycles that exclude unproven entrants. Defense procurement concentrates around Washington DC corridor contractors and Southwest assembly facilities serving military aerospace programs.
Germany
Factory-floor tablet deployments resist chemical exposure and thermal cycling through IP65-rated sealed enclosures in automotive and automation sectors. ECHA REACH restrictions on flame-retardant additives accelerate material-selection protocol updates, creating first-mover advantages for suppliers with validated alternative chemistries. Industrial demand clusters in Stuttgart and Munich automation corridors where pre-qualified suppliers maintain established recycling partnerships.
Japan
Avionics integrators accelerate cockpit retrofit programs using AMOLED panels with circular polarizer stacks that eliminate washout under direct sunlight. METI industrial standards and JIS certification requirements shape procurement specifications for mission-critical applications. Display integration expertise concentrates in Nagoya aerospace manufacturing belt and Tokyo metropolitan electronics clusters.
China
Domestic industrial automation and transportation infrastructure expansion sustains demand for LCD panels with mature supply chain cost structures. MIIT equipment standards and GB certification protocols govern product qualification for state-sponsored manufacturing modernization programs. Production gravity centers on Yangtze River Delta panel fabrication facilities and Pearl River Delta system integration hubs.
South Korea
OLED technology leadership supports premium-tier positioning in night-vision-compatible and high-contrast defense applications. MFDS equipment regulations and national strategic technology initiatives channel R&D investment toward next-generation display architectures. Seoul Capital Area hosts concentrated display research facilities and defense contractor engineering centers.
Rugged Display Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense-aerospace channels favoring vertically integrated suppliers and industrial verticals tolerating broader sourcing pools. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with captive panel fabrication, pure-play rugged specialists with thermal-engineering competencies, and defense contractors with classified program access. Consolidation pressure operates through M&A activity targeting optical bonding capabilities and strategic partnerships securing MIL-STD qualification pathways.
Among diversified technology conglomerates, Panasonic Corporation exemplifies the captive-supply archetype through in-house LCD panel production, while Dell Technologies Inc. occupies a position bridging enterprise computing with ruggedized extensions. Getac Technology Corporation represents the pure-play specialist model with concentrated thermal-engineered chassis expertise. These three anchors illustrate how competitive positioning diverges between cost-disciplined volume players and qualification-heavy defense suppliers.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Panasonic Corporation |
| Dell Technologies Inc. |
| Getac Technology Corporation |
| General Dynamics Corporation |
| Curtiss-Wright Corporation |
| L3Harris Technologies Inc. |
| Kyocera Corporation |
| EIZO Corporation |
| Others |
Supply Flow & Price Mechanics
Optical-grade indium tin oxide spot pricing volatility cascades through display module fabrication into three-tier pricing stratification across premium MIL-STD-certified, standard industrial-grade, and economy commercial-rugged tiers. German automotive buyers and United States defense contractors face divergent cost pass-through structures based on volume scale and qualification burden.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for OLED panel substrates while LCD supply discipline from Japanese and Taiwanese fabs sustains mid-tier stability. Pricing stratifies across premium, standard, and economy tiers based on MIL-STD-810 certification level and optical bonding yield rates. Cost compression in mid-tier product lines intensifies because specialty chemical producers concentrate supply of aluminosilicate cover glass. Fleet operators in field-service channels exhibit highest price sensitivity, while aerospace integrators tolerate premium positioning for FAA-qualified architectures.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean specialty chemical producers dominating optical-grade indium tin oxide and vacuum-bonding equipment. Raw material flows draw from Chinese rare earth processing for phosphor coatings, German engineered polymers for thermal chassis, and United States aluminosilicate glass for cover lens applications. Tariff exposure on Chinese-processed rare earth elements presents structural risk for European industrial display assemblers. Distribution runs through direct defense contractor relationships in Washington DC corridor and tiered distribution networks serving German automation corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software-defined fleet management subscriptions displacing hardware-only transactions. OLED technology substitution in avionics creates premium-tier pricing power for qualified suppliers.
For Market Incumbents: Cement qualification moats by accelerating MIL-STD-461 certification convergence for AMOLED architectures before technology substitution erodes LCD margins. Deepen backward integration into optical bonding capabilities to defend against emerging Asian specialists with thermal-engineering competencies. Lock in recycling partnerships with German automotive buyers ahead of EU Green Deal circularity enforcement. For New Entrants and Emerging Players: Begin with Asia-Pacific public-safety vehicle installations where thermal-engineered chassis demand outruns incumbent capacity. Police and emergency-response fleets in Southeast Asian markets present the most penetrable white space. Pursue software-defined brightness calibration subscriptions as the primary go-to-market angle to bypass capital-intensive hardware qualification cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play rugged specialists possessing captive optical bonding facilities and established MIL-STD qualification pathways. Long-term viability favors suppliers with demonstrated compliance across multi-domain certification requirements spanning shock, vibration, and electromagnetic standards. Monitor AMOLED certification timeline compression as the critical inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-461 Certification Convergence | AMOLED qualification pathway compression accelerates avionics retrofit procurement cycles. |
| Software-Defined Fleet Management Launch | Subscription revenue layers transform hardware transactions into recurring contracts for United States military channels. |
| Optical Bonding Capability Acquisition | Zero-defect vacuum-bonding expertise concentrates at limited integration facilities in Japan and Germany. |
| EU Green Deal Recycling Partnership | German automotive and automation buyers pre-qualify suppliers with established material recovery databases. |
| Thermal Chassis Engineering Expansion | Asia-Pacific public-safety demand for field-service tablets outstrips incumbent production capacity. |
Methodological Framework
Multiple input streams — primary interviews with defense procurement officers, avionics integration engineers, and industrial automation buyers; secondary validation through MIL-STD qualification databases, FAA airworthiness directives, and ECHA REACH substance restrictions; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned Washington DC corridor contractors, Stuttgart automation procurement leads, and Nagoya aerospace manufacturing clusters. Secondary sources included SEC filings from display technology conglomerates, METI industrial standards documentation, and EU regulatory implementation timelines.
Historical shipment patterns were cross-referenced against panel input from supply chain participants to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product format, display technology, end-user vertical, installation type, and regional regulatory cluster. CAGRs were derived from demand elasticity analysis against qualification timeline constraints and technology substitution curves. Industry-specific forecast inputs incorporated OLED yield improvement trajectories and software subscription attach rate assumptions.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to MIL-STD-810 shock standards, geopolitical disruption to rare earth supply chains, and breakthrough advances in flexible display architectures. Forecasts reflect documented assumptions regarding certification timeline stability and material cost pass-through mechanisms. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Display Panel Market
Display Technologies
3D Display Module Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Display Port Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Automotive LCD Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global Transparent Display Market
Display Technologies
Volumetric Display Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Industrial Display Market
Display Technologies
IGZO Display Market
Display Technologies
Capacitive Touch Screen Market