

1,8-Dinitroanthraquinone Market Size, Share, and Industry Trends Forecast 2026-2036
1,8-Dinitroanthraquinone Market Insights
Multi-source procurement of nitrated anthraquinone intermediates is restructuring supply relationships across specialty chemical value chains. Qingdao Haiwan Specialty Chemicals leverages coastal logistics infrastructure to serve dye and pigment formulators throughout Shandong Province. Zhejiang Tesin Chemical sustains captive nitration capacity that anchors its position in fine chemical supply networks. Merck differentiates through ISO-certified reference material production that serves analytical laboratories requiring exacting purity specifications.
1,8-Dinitroanthraquinone is a regioisomeric nitration product of anthraquinone, characterized by nitro substituents at the peri positions that confer high electron deficiency and strong chromophoric properties; manufacturers typically produce it through mixed-acid nitration of anthraquinone followed by fractional crystallization to isolate the 1,8-isomer from other nitration products. The compound functions primarily as an intermediate in vat dye synthesis and as a precursor to aminoanthraquinone derivatives used in high-performance pigments. Fine chemicals and intermediate compounds command the deepest margin pools due to pharmaceutical and agrochemical offtake requiring custom synthesis and toll manufacturing arrangements. Powder and crystal forms dominate shipment volumes, though granule demand is gaining traction among textile manufacturers seeking dust-free handling characteristics for automated dosing systems.
EPA hazardous waste regulations and OSHA process safety management standards govern nitration facility operations in the United States, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for import and manufacture above threshold tonnages. China's MEE enforces emission controls on nitration acid recovery systems that directly affect production economics for domestic suppliers like Hubei Qifei Pharmaceutical Chemical. Stakeholders must monitor evolving nitroaromatic substance restrictions under the EU CLP regulation and assess backward integration into anthraquinone feedstock production as a buffer against raw material volatility.
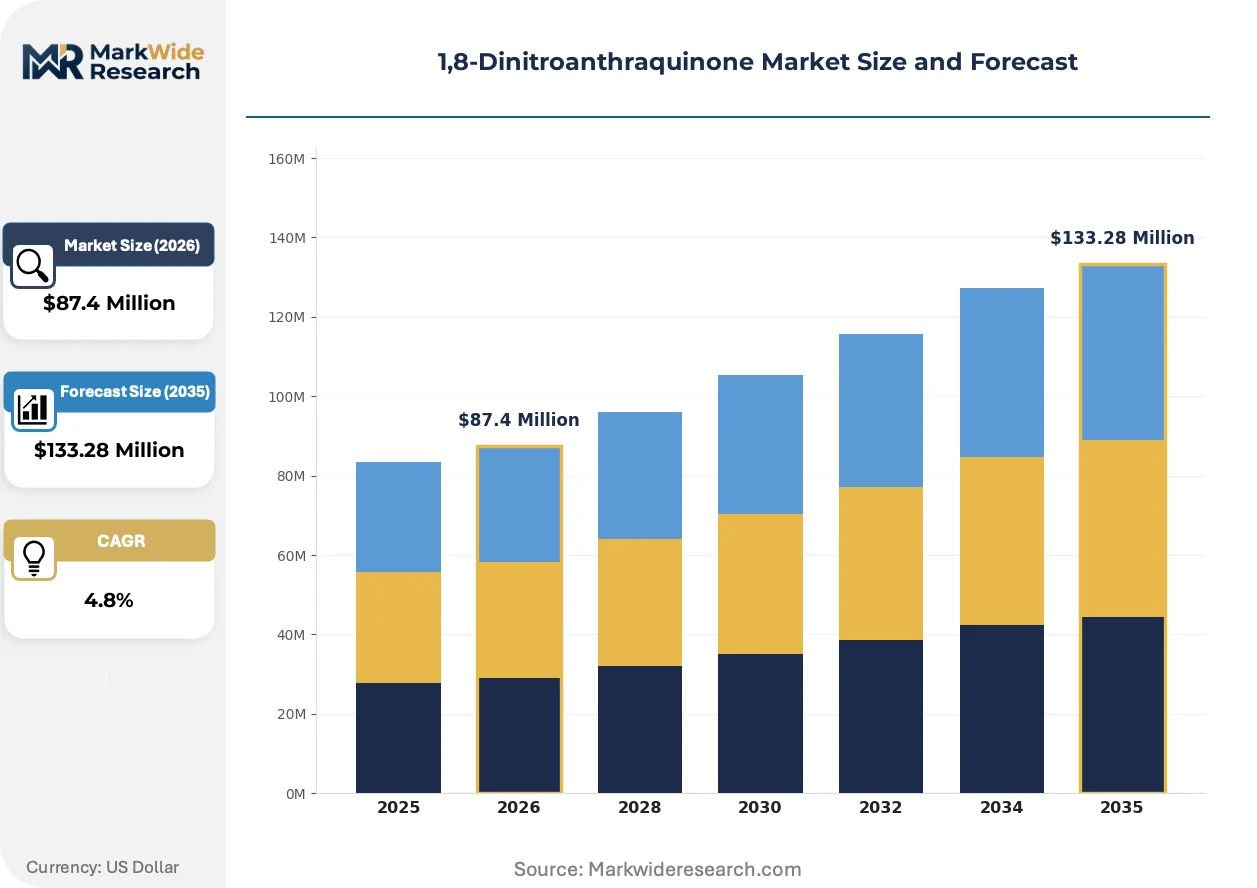
Market Dynamics
Specialty dye manufacturers in China and India are restructuring procurement relationships around nitrated anthraquinone intermediates, while REACH compliance and EPA emission standards are compressing supplier margins through elevated purity requirements and acid recovery mandates.
Growth Catalysts
- Vat dye synthesis expansion:Textile formulators in East Asian chemical clusters are scaling anthraquinone-based pigment production for high-performance fabric applications.
- REACH registration thresholds:European import mandates above one-tonne annual volumes are consolidating qualified supplier pools and rewarding compliant manufacturers with preferential offtake terms.
- Automated dosing adoption:Granule formulations with dust-free handling characteristics are penetrating textile manufacturing facilities seeking process automation compatibility.
Market Restraints
- Anthraquinone feedstock volatility:Crude oil derivative pricing swings directly compress nitration facility operating margins and destabilize intermediate compound cost structures.
- East Asian supply concentration:Production gravity around Shanghai and Osaka chemical synthesis clusters creates single-region dependency risk for international dye formulators.
- Mixed-acid nitration limitations:Conventional fractional crystallization yields impose technical ceilings on 1,8-isomer isolation efficiency versus competing regioisomeric products.
Strategic Opportunities
- Indian specialty chemical expansion:Domestic nitration capacity investments under PLI scheme incentives are opening captive intermediate supply for agrochemical and pharmaceutical offtake.
- Aminoanthraquinone derivative demand:High-performance pigment precursors for automotive coatings and industrial plastics represent underexploited application verticals beyond traditional textile dyes.
- ISO-certified reference materials:Analytical laboratory segments requiring exacting purity specifications offer premium-margin positioning distinct from commodity intermediate sales.
Industry Challenges
- Process safety management compliance:OSHA standards for nitration facility operations mandate capital-intensive engineering controls and trained personnel retention that strain mid-scale producers.
- ECHA dossier preparation timelines:REACH toxicological registration requirements demand 18-24 month compliance cycles that delay market entry for new manufacturing entrants.
- Legacy acid recovery system integration:China's MEE emission controls on nitration effluent require retrofit investments that disrupt continuous production schedules at established facilities.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,8-Dinitroanthraquinone Market Trends and Innovations
Continuous flow nitration technology is displacing batch processing in anthraquinone derivative manufacturing, while regulatory transparency mandates and buyer consolidation are compressing traditional supply chain intermediation layers.
Continuous flow reactor systems for mixed-acid nitration are modularizing production economics for 1,8-dinitroanthraquinone manufacturers. Specialty chemical producers in Zhejiang and Shandong provinces are piloting these platforms to reduce acid consumption and improve isomer selectivity. The technology is modularizing capital deployment patterns, enabling smaller-scale entrants to achieve yields previously requiring integrated petrochemical complexes.
REACH registration requirements under ECHA oversight are mandating substance identity verification and toxicological endpoint documentation for nitroaromatic imports into European customs territories. Dye formulators dependent on Asian intermediate supply are demanding supplier-provided dossier completeness to avoid border detention risks. Fine chemical distributors serving analytical laboratories are most affected, pivoting toward ISO-certified reference material partnerships that preempt regulatory scrutiny.
Direct procurement relationships between dye manufacturers and nitration facilities are displacing layered chemical trading networks in East Asian supply chains. Textile conglomerates in Osaka and Shanghai chemical clusters are negotiating volume commitments with captive nitration operators to secure isomer-specific supply assurances. This pattern is most visible in vat dye synthesis verticals where purity consistency directly determines finished pigment chromophoric performance.
1,8-Dinitroanthraquinone Market Segmentation
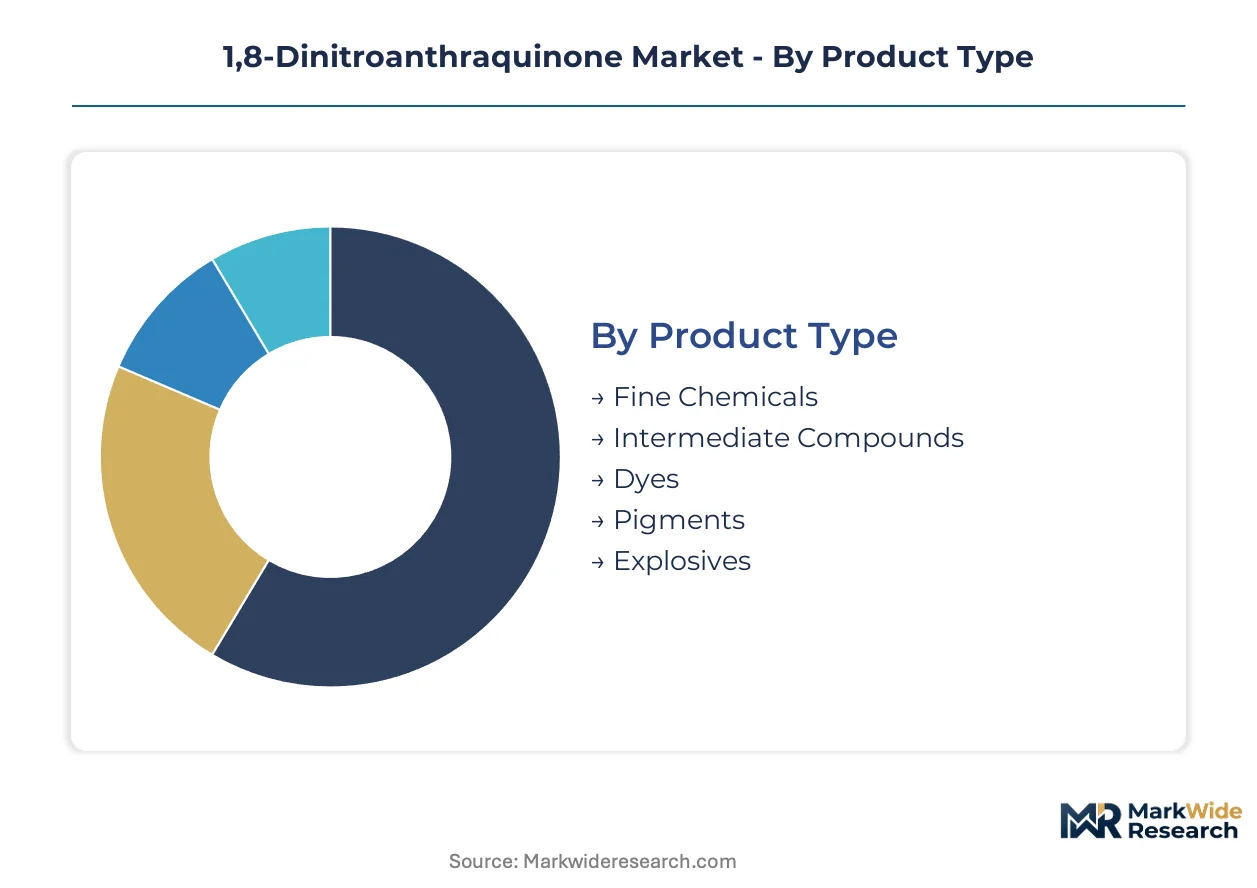
Segmentation in 1,8-dinitroanthraquinone markets reflects divergent purity requirements and handling specifications across dye synthesis, analytical chemistry, and specialty manufacturing verticals. Formulators select product grades and physical forms based on automated dosing compatibility, regulatory compliance burdens, and downstream process integration constraints.
Product Type:
Volume applications dominate tonnage flows while premium-margin segments concentrate in pharmaceutical and agrochemical offtake requiring toll manufacturing arrangements.
- Fine Chemicals:High-purity grades serve analytical laboratories and pharmaceutical synthesis requiring exacting specification control. Demand concentrates in ISO-certified reference material supply chains where Merck maintains differentiated positioning through certified production protocols.
- Intermediate Compounds:Captive nitration output feeds vat dye synthesis and aminoanthraquinone derivative production for high-performance pigments. Zhejiang Tesin Chemical leverages in-house capacity to anchor supply relationships with textile formulators in Shanghai chemical clusters.
- Dyes:Anthraquinone-based chromophores for textile applications requiring peri-nitrated precursor supply.
- Pigments:High-performance colorants for automotive coatings and industrial plastics derived from reduced nitroaromatic intermediates.
- Explosives:Nitroaromatic compound applications in specialty energetic materials with stringent handling protocols.
Today's leader: Intermediate Compounds. Tomorrow's challenger: Fine Chemicals.
Form:
Physical form selection directly determines dust exposure controls, automated dosing compatibility, and transportation classification costs across nitrated anthraquinone supply chains.
- Powder:Standard micronized material for batch chemical synthesis and laboratory-scale reactions. Powder shipments dominate existing textile manufacturing installations lacking automated handling infrastructure.
- Crystals:Fractional crystallization isolates regioisomer-specific products from mixed-acid nitration output. Crystal purity levels satisfy REACH registration thresholds for European import volumes above one-tonne annual quantities.
- Granules:Dust-free formulations penetrate textile facilities seeking process automation compatibility with reduced respiratory exposure controls. Qingdao Haiwan Specialty Chemicals serves Shandong Province dye formulators with coastal logistics-optimized granule supply.
- Flakes:Intermediate bulk density format for specialty chemical distributors managing multi-step synthesis workflows.
Granules are gaining share fastest in East Asian textile manufacturing clusters where OSHA process safety management standards influence facility upgrade decisions.
End Use Industry:
Application segmentation tracks divergent purity specifications and procurement scale across commodity textile production versus specialized electronics and agrochemical synthesis.
- Textile Manufacturing:Vat dye synthesis for high-performance fabric applications anchors baseline demand. Osaka and Shanghai chemical clusters concentrate anthraquinone-based pigment production capacity serving global textile supply chains.
- Chemical Synthesis:Custom manufacturing and toll arrangements for pharmaceutical and agrochemical intermediates command premium margin pools. Hubei Qifei Pharmaceutical Chemical navigates China's MEE emission controls on nitration acid recovery systems affecting production economics.
- Electronics Assembly:Specialty polymer and coating applications requiring high-purity nitroaromatic precursors.
- Agriculture:Agrochemical intermediate demand under India's PLI scheme incentives is opening captive supply for domestic formulators.
Chemical Synthesis offers the steepest expansion trajectory as pharmaceutical toll manufacturing deepens procurement relationships with qualified nitration facilities.
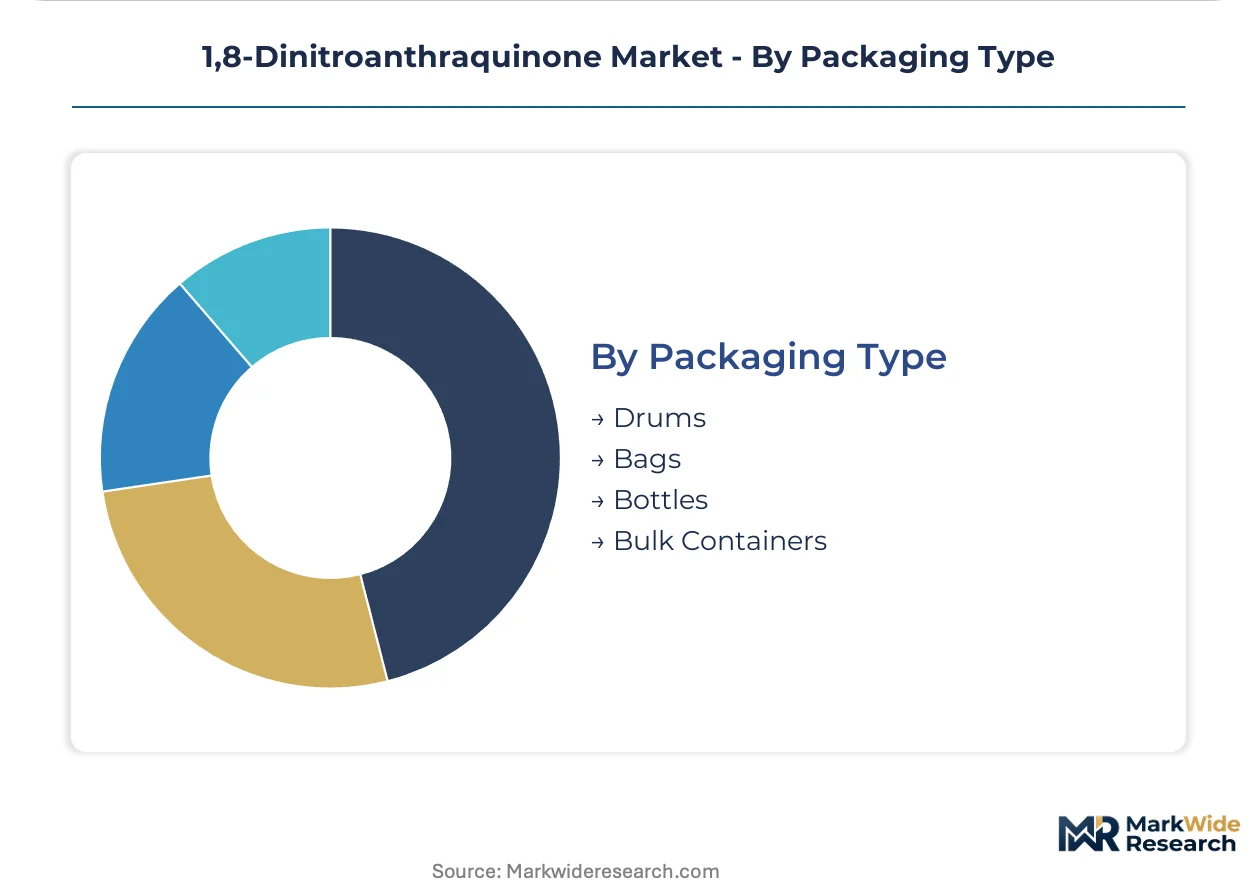
Packaging Type:
Packaging selection balances hazardous material classification requirements, inventory turnover velocity, and customer receiving infrastructure across differentiated end-use segments.
- Drums:Standard steel and fiber containers for intermediate compound shipments to chemical synthesis facilities. Drum specifications must satisfy EPA hazardous waste regulations governing nitrated aromatic transport and storage.
- Bulk Containers:Intermediate bulk totes for high-volume textile manufacturing customers with automated dosing systems and established material handling protocols.
- Bags:Multi-layer laminated packaging for powder and granule forms requiring moisture barrier protection.
- Bottles:Laboratory-scale containers for fine chemical and reference material distribution to analytical end-users.
Drums retain volume leadership in established dye manufacturing supply chains. Bulk Containers represent the fastest-climbing format as direct procurement relationships consolidate order quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai chemical synthesis clusters concentrate the dominant share of 1,8-dinitroanthraquinone manufacturing capacity, with procurement relationships restructuring around direct nitration facility partnerships rather than layered trading networks.
China
Textile formulators in Shandong and Zhejiang provinces drive captive nitration capacity expansion for vat dye synthesis. MEE emission controls on acid recovery systems elevate compliance costs for domestic producers. Qingdao Haiwan Specialty Chemicals leverages coastal logistics infrastructure to serve dye manufacturers throughout Shandong Province with granule-optimized supply chains.
India
Agrochemical and pharmaceutical intermediate demand accelerates domestic nitration investments under PLI scheme incentives. CDSCO registration requirements for pharmaceutical-grade imports mandate supplier qualification protocols. Gujarat and Maharashtra chemical clusters host emerging specialty chemical producers seeking captive supply integration with global dye formulators.
United States
EPA hazardous waste regulations and OSHA process safety management standards govern nitration facility operations with stringent engineering control mandates. Analytical laboratory demand for ISO-certified reference materials supports premium-margin import positioning. Texas and Louisiana Gulf Coast chemical infrastructure handles specialty nitroaromatic distribution to domestic dye manufacturers.
Germany
REACH registration thresholds above one-tonne annual volumes consolidate qualified supplier pools for European dye formulators. ECHA toxicological dossier requirements extend compliance timelines for new market entrants. BASF-Ludwigshafen chemical complex and Leverkusen industrial clusters maintain legacy anthraquinone derivative processing relationships with textile customers.
Japan
Osaka chemical synthesis clusters anchor high-performance pigment production for automotive coating applications. METI industrial chemical regulations enforce process safety standards for nitration operations at specialty manufacturers. Kansai region textile chemical producers maintain integrated supply relationships with aminoanthraquinone derivative formulators.
1,8-Dinitroanthraquinone Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular continuous flow technology and regional compliance specialization. The supplier base stratifies across integrated petrochemical complexes, captive nitration operators, and ISO-certified reference material specialists. Three archetypes dominate: coastal logistics-optimized manufacturers serving textile clusters, pharmaceutical-grade purity specialists, and toll manufacturing intermediaries. Capacity expansion and direct procurement relationship consolidation represent the dominant competitive vectors reshaping supply chain intermediation.
Within the coastal logistics tier, Qingdao Haiwan Specialty Chemicals exemplifies Shandong Province positioning optimized for granule shipment to dye formulators. Zhejiang Tesin Chemical occupies the captive nitration archetype with integrated capacity serving Shanghai chemical cluster demand. Merck represents the analytical-grade reference material specialist segment where ISO-certified production protocols command premium positioning distinct from commodity intermediate sales.
| Leading Market Players |
|---|
| Qingdao Haiwan Specialty Chemicals |
| Zhejiang Tesin Chemical |
| Hubei Qifei Pharmaceutical Chemical |
| Sigma-Aldrich |
| TCI |
| Toronto Research Chemicals |
| Spectrum Chemical Manufacturing |
| Alfa Aesar |
| Merck |
| Others |
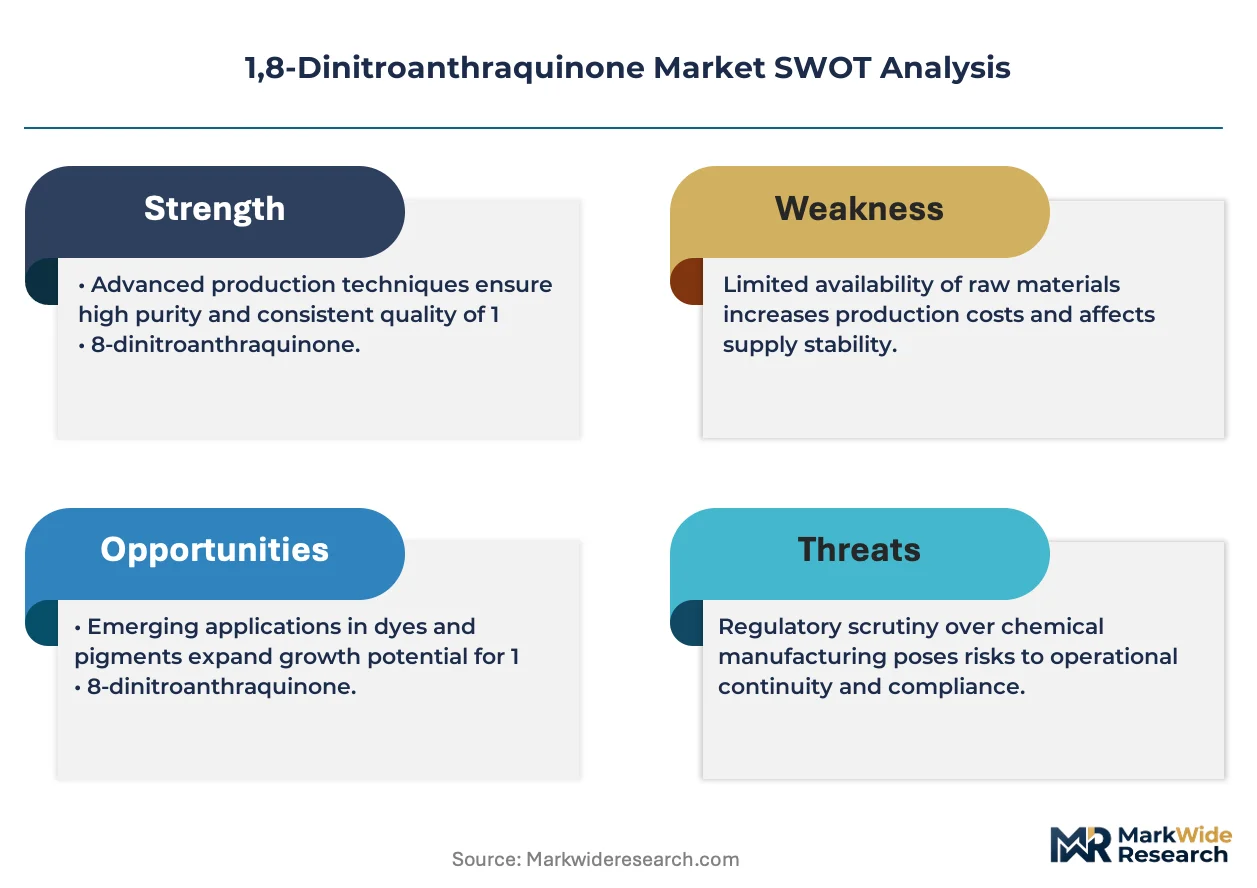
Pricing and Supply Chain Analysis
Captive nitration capacity in Zhejiang and Shandong provinces anchors both supply security and pricing power for established manufacturers serving Shanghai chemical cluster demand. China's MEE emission controls on acid recovery systems and REACH registration dossier requirements in Europe create tiered compliance costs that stratify supplier positioning across premium and standard grades.
Pricing Analysis
Anthraquinone feedstock volatility passes directly into intermediate compound pricing through crude oil derivative cost swings that compress nitration facility operating margins. Three-tier pricing structure across premium, standard, and economy levels reflects purity grades, ISO certification status, and volume scale commitments from textile formulators. Cost compression in standard-grade powder shipments is intensifying because of acid recovery retrofit investments at legacy facilities. Small-scale analytical laboratories show highest price sensitivity, while pharmaceutical toll manufacturers prioritize specification consistency over unit economics.
Supply Chain Analysis
India's PLI scheme incentives for domestic specialty chemical production are reshaping sourcing patterns for agrochemical intermediate demand that previously drew from Chinese nitration output. Manufacturing gravity centers on China, India, and Japan, with supply chains feeding from anthraquinone feedstock, mixed-acid nitration reagents, and fractional crystallization equipment. Single-region dependency risk concentrates around Shanghai and Osaka chemical synthesis clusters. Distribution runs through direct procurement relationships between dye manufacturers and captive nitration operators that displace layered trading networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade fine chemicals where ISO-certified reference material production commands premium positioning distinct from commodity intermediate sales. Continuous flow nitration technology reduces acid consumption and improves isomer selectivity, lowering unit production costs for qualified adopters.
For Market Incumbents: Extend captive nitration capacity into downstream aminoanthraquinone derivative production to capture pigment precursor value that currently leaks to specialized formulators. Integrate continuous flow reactor systems at Zhejiang and Shandong facilities to defend against modular entrants achieving comparable yields with smaller capital footprints. Strengthen REACH dossier completeness to preempt border detention risks facing European dye formulators dependent on Asian intermediate supply.
For New Entrants and Emerging Players: Analytical laboratories requiring exacting purity specifications represent an underserved buyer archetype with premium-margin tolerance and fragmented incumbent supply. Enter through ISO-certified reference material partnerships that preempt regulatory scrutiny and establish qualification credentials for subsequent pharmaceutical toll manufacturing expansion. Target Indian agrochemical intermediate demand under PLI scheme incentives where domestic nitration capacity gaps persist.
For Investors and Strategic Acquirers: Roll-up economics work for regional nitration specialists with captive anthraquinone feedstock relationships because East Asian supply concentration creates scarcity value for qualified European and North American offtake. Focus acquisition screening on mid-scale Chinese producers with MEE-compliant acid recovery systems and existing REACH registration progress. Watch ECHA substance restriction proposals under EU CLP regulation as the critical inflection signal for nitroaromatic intermediate demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anthraquinone Feedstock | Upstream control over crude oil derivative costs buffers margin compression from nitration acid price swings. |
| Continuous Flow Nitration Technology Deployment | Modular reactor platforms reduce acid consumption and improve 1,8-isomer selectivity versus batch processing. |
| REACH Registration Dossier Completion | ECHA-compliant toxicological documentation secures preferential offtake terms from European dye formulators above one-tonne thresholds. |
| Granule Formulation Capacity Addition | Dust-free handling characteristics penetrate textile facilities seeking automated dosing compatibility with reduced respiratory controls. |
| Long-term Supply Agreement with Pharmaceutical Toll Manufacturers | Custom synthesis arrangements for aminoanthraquinone derivatives command premium margins distinct from commodity pigment precursor sales. |
Research Methodology
Direct dialogue with plant managers at nitration facilities, procurement leads at downstream dye manufacturers, distribution channel partners serving analytical laboratories, and technical R&D directors at specialty chemical firms grounded qualitative assessment. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed chemical producers, and ECHA registration dossiers. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation from textile, pharmaceutical, and agrochemical end-use industries.
Bottom-up modeling tracked grade tier, end-use industry, packaging format, and regional production hub dimensions across the analysis window. Value outputs reflected price realization by purity specification and form factor, with CAGRs derived from segment-level demand elasticity and capacity expansion timelines. Forecast inputs incorporated MEE emission control compliance costs, PLI scheme incentive trajectories, and ECHA regulatory proposal advancement.
Underlying measurement precision varies by segment; fine chemical and reference material categories carry tighter precision than commodity intermediate compounds given disclosed contract pricing and certification audit trails. Forecasts reflect assumptions around continuous flow technology adoption rates, REACH registration timeline adherence, and anthraquinone feedstock price correlation with crude oil derivatives. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.