
 Granulated Tapioca Market | 2026-2036
Granulated Tapioca Market Size, Share, and Industry Trends Forecast 2026-2036
Granulated Tapioca Market Foresight
Thai cassava processors is shifting capacity toward higher-value modified starches, tightening native granule availability for international buyers. Cargill, Incorporated leverages its integrated supply chain from Southeast Asian farms to North American food manufacturers. Tate & Lyle PLC anchors European demand through its specialty starch distribution network. PT Budi Starch & Sweetener Tbk dominates Indonesian output with vertically controlled processing facilities.
Granulated tapioca consists of dried, mechanically milled cassava root particles typically ranging from 180 to 500 microns in mesh size, valued for neutral flavor and high amylopectin content that delivers clear, stable gels under thermal processing. The material serves as a clean-label thickener and texturizer across food systems requiring freeze-thaw stability. Flour and starch product types command the deepest margin pools due to their indispensability in industrial bakery and sauce formulations. Pearls retain strong volume in bubble tea channel demand, while biodegradable packaging applications represent the fastest-growing application segment as brand owners phase out petroleum-derived films.
Thailand's Ministry of Industry enforces Good Manufacturing Practice standards for cassava starch exports, while the FDA governs food-grade granule purity and allergen labeling for U.S.-bound shipments. REACH compliance in Europe restricts residual cyanogenic compound levels, forcing processors to validate detoxification protocols. Stakeholders must monitor how diverging national sustainability certifications reshape sourcing eligibility and contract terms across major import corridors.
Market Dynamics
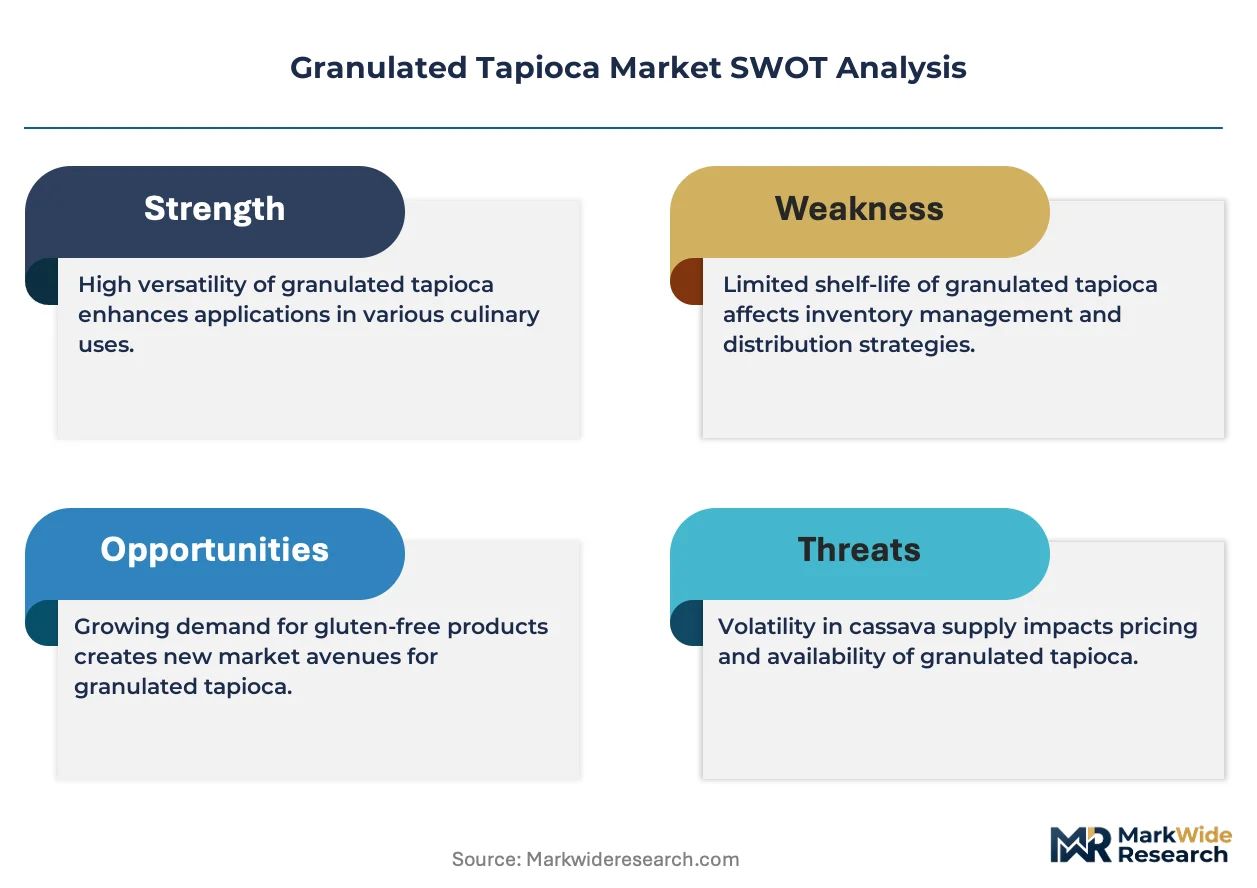
Thai cassava processors are redirecting capacity toward modified starches, tightening native granule supply for international buyers while EU Green Deal sustainability mandates reshape import eligibility criteria.
Growth Catalysts
- EU Green Deal compliance:Certified sourcing requirements are pushing European food manufacturers toward verified sustainable suppliers, creating premium contract opportunities for compliant Thai and Indonesian processors.
- Gluten-free bakery expansion:Commercial bakers across North America and Europe are reformulating wheat-dependent products, absorbing larger volumes of granulated tapioca as a clean-label texturizer with neutral flavor profiles.
- Bubble tea channel maturation:Pearls remain indispensable in beverage applications, with dedicated supply chains now established from Southeast Asian processing clusters to North American and European retail networks.
Market Restraints
- Cassava root price volatility:Weather-driven yield fluctuations in Thailand and Indonesia create input cost instability that compresses margins for native starch processors without long-term farm contracts.
- REACH cyanogenic compound limits:European detoxification validation requirements add compliance costs and technical barriers for smaller processors lacking in-house laboratory certification capabilities.
- Potato and corn starch substitution:Established alternative starches with deeper distribution infrastructure and lower price points threaten tapioca's position in cost-sensitive sauce and soup applications.
Strategic Opportunities
- Biodegradable packaging films:Brand owners phasing out petroleum-derived materials represent an emerging demand vertical for tapioca-based barrier coatings and thermoformed trays.
- Clean-label sauce thickeners:Consumer preference for ingredient lists without chemical modifiers is opening formulation opportunities in premium retail condiment segments.
- Indian food processing expansion:Domestic bakery and convenience food manufacturing growth offers a white-space geography for granulated tapioca suppliers currently concentrated on Atlantic trade corridors.
Industry Challenges
- Detoxification protocol standardization:Validating cyanogenic compound reduction methods that satisfy divergent FDA, REACH, and Thai Ministry of Industry requirements demands specialized analytical chemistry expertise that smaller processors struggle to retain.
- Modified starch capex barriers:Transitioning from native granule production to higher-value chemically or physically modified starches requires significant reactor and drying equipment investments that strain balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granulated Tapioca Market |
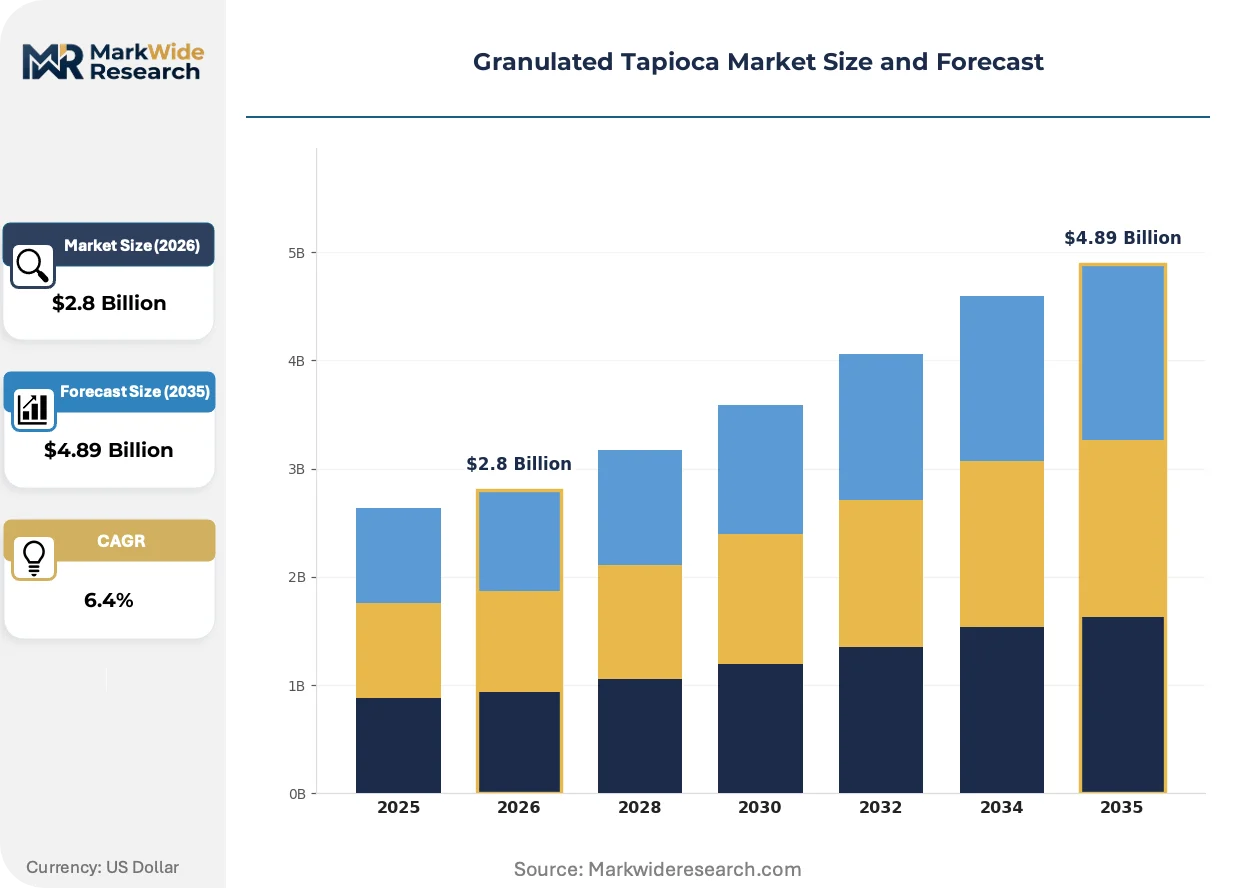
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Starch, Pearls, Pudding Mix End Use: Beverages, Snacks, Bakery, Pharmaceuticals Distribution Channel: Online, Retail, Wholesale, Export Application: Food Industry, Personal Care, Textile, Biodegradable Packaging |
| Companies Covered | Tate & Lyle PLC, Royal Avebe U.A., Archer Daniels Midland Company, PT Budi Starch & Sweetener Tbk, Thai Wah Public Company Limited, Cargill, Incorporated, Roquette Frères, Grain Processing Corporation, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granulated Tapioca Market Shifts & Advancements
Processing technology and regulatory frameworks are converging to reshape how cassava derivatives move from Southeast Asian farms to end-use formulations, with sustainability verification emerging as a competitive differentiator.
Advanced optical sorting and near-infrared spectroscopy is automating quality control in Thai processing facilities, reducing manual inspection labor and enabling real-time moisture and purity verification. Large-scale exporters are adopting these systems fastest, compressing quality variation in export-grade shipments and raising baseline standards for contract eligibility.
REACH residual cyanogenic compound restrictions are forcing processors to document detoxification protocols with third-party laboratory validation. European-bound shipments now require batch-level testing certificates, increasing per-unit compliance costs but creating segmentation between certified and uncertified supply tiers. Small and mid-scale Indonesian processors face the steepest adaptation burden.
Direct procurement relationships between North American food manufacturers and Thai processing cooperatives are displacing traditional trading house intermediaries. Large bakery and sauce formulators are negotiating multi-year volume contracts with named farms and processing clusters, shifting price discovery from spot markets to structured agreements with sustainability riders.
Granulated Tapioca Market Segmentation
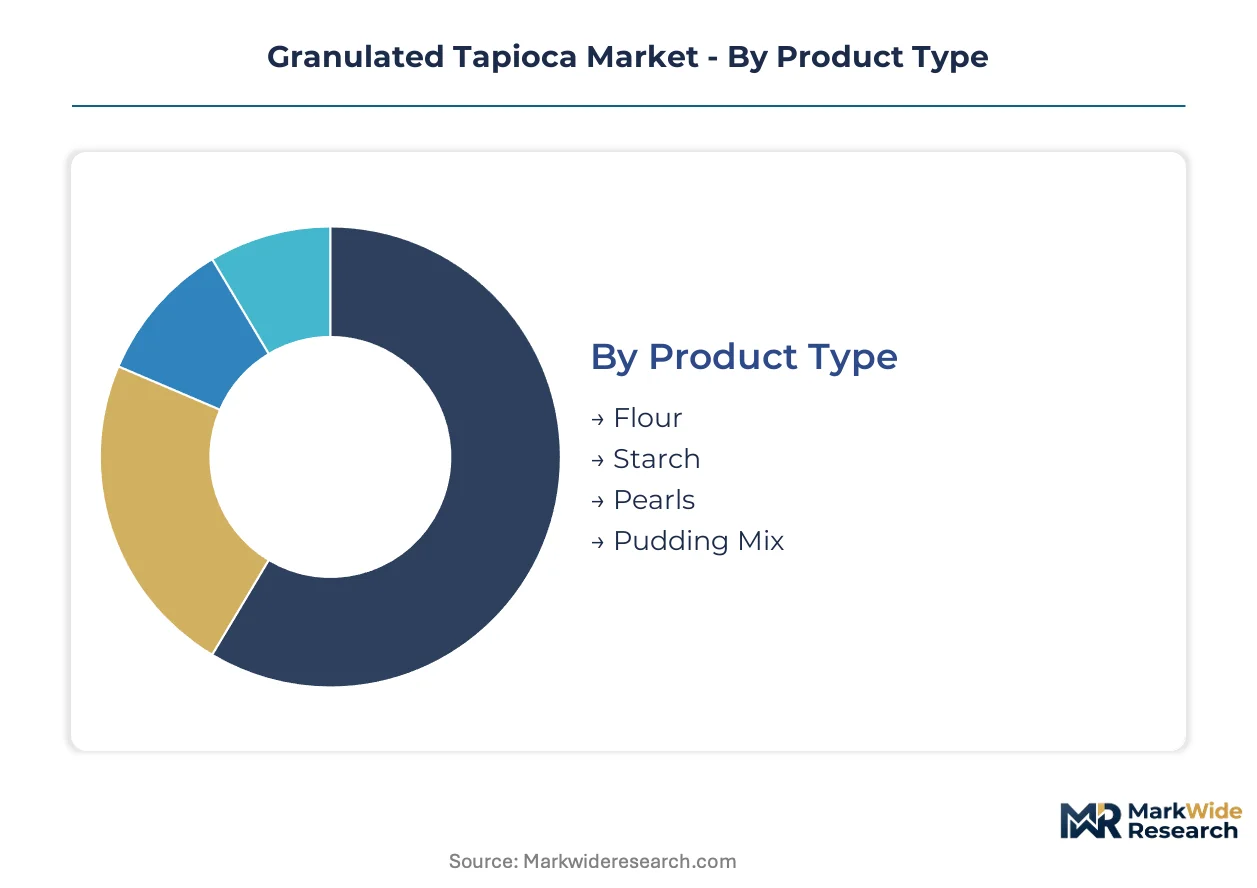
Granulated tapioca's commercial value hinges on particle specification, end-use processing requirements, and channel access. Segmentation reveals where margin pools concentrate and which product forms command formulation premiums across food and industrial applications.
Product Type:
Volume concentrates in commodity-grade native starches, while premium margins attach to modified and specialty formats with enhanced functional properties.
- Flour:Coarsely milled cassava root particles retaining fiber content, prized in traditional Latin American and African flatbread formulations. Brazilian and Nigerian processors absorb the largest export volumes for pão de queijo and garri substitutes as clean-label wheat alternatives gain traction.
- Starch:Purified amylopectin-rich extract delivering transparent, freeze-thaw stable gels. Industrial sauce and soup manufacturers in Germany and the United States specify high-grade native starch for viscosity control without chemical modifiers.
- Pearls:Spheroidized tapioca starch formed through extrusion and drying, sized for beverage suspension.
- Pudding Mix:Pre-gelatinized blends with added stabilizers for instant reconstitution.
Today's leader: Starch. Tomorrow's challenger: Pearls.
End Use:
Application maturity varies sharply, with established food channels competing against emerging pharmaceutical specifications for high-purity grades.
- Beverages:Bubble tea chains and specialty coffee operators drive pearl consumption through dedicated supply contracts from Thai processing clusters to North American retail networks.
- Snacks:Extruded and puffed applications leverage tapioca's neutral flavor carrier properties.
- Bakery:Gluten-free bread and cake formulations absorb expanding volumes as commercial bakers reformulate wheat-dependent products for allergen-sensitive consumers.
- Pharmaceuticals:High-purity grades serve as tablet binders and capsule fillers, with excipient-grade specifications commanding quality premiums over food-grade equivalents.
Bakery applications are expanding most quickly; pharmaceutical qualification timelines constrain near-term volume.
Distribution Channel:
Channel selection determines price realization and customer access, with direct procurement relationships displacing traditional trading intermediaries.
- Online:E-commerce platforms serve specialty food retailers and small-scale food manufacturers seeking smaller lot sizes with rapid delivery.
- Retail:Supermarket and specialty store channels move consumer-packaged flour and pearl formats.
- Wholesale:Foodservice distributors supply restaurant and bakery operations with bulk packaging.
- Export:Containerized shipments from Thai and Indonesian ports reach industrial processors under multi-year volume contracts with sustainability riders.
Export contracts anchor volume; online channels are gaining share fastest among smaller buyers.
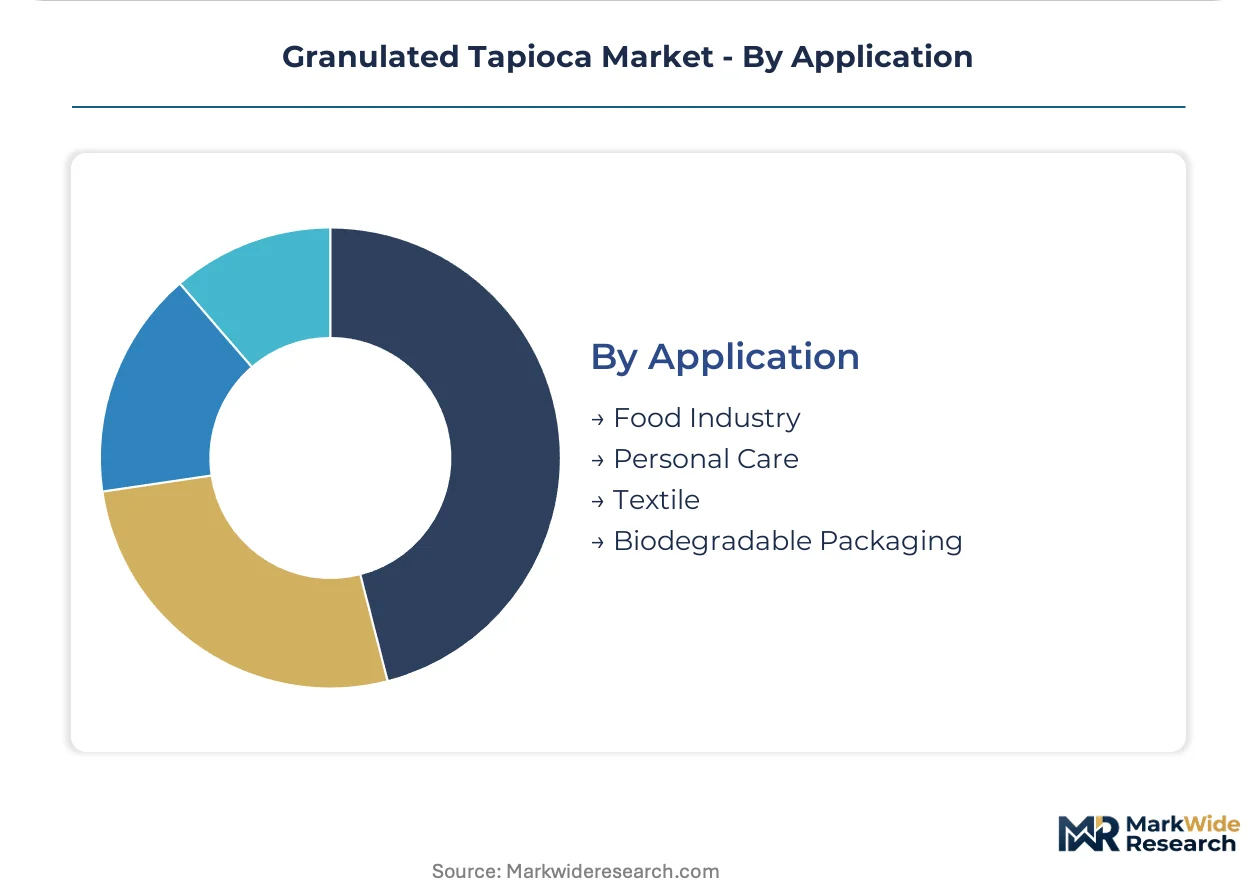
Application:
Industrial diversification beyond food uses is reshaping capacity allocation as biodegradable material specifications mature.
- Food Industry:Thickening, gelling, and texturizing functions across sauces, soups, and baked goods constitute the foundational demand base.
- Personal Care:Tapioca starch serves as absorbent powder and natural texturizer in cosmetic formulations.
- Textile:Sizing and finishing applications in fabric processing utilize modified starch derivatives.
- Biodegradable Packaging:Thermoformed trays and barrier coatings represent the steepest expansion trajectory as brand owners phase out petroleum-derived films.
Food Industry dominates current offtake; Biodegradable Packaging represents the fastest-climbing demand vertical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as processors migrate toward jurisdictions with lower compliance burdens for native starch exports, while sustainability mandates in import markets force simultaneous certification upgrades.
Thailand
Industrial bakery demand from North American and European customers absorbs the largest export volumes of native granules. The Ministry of Industry enforces Good Manufacturing Practice standards that batch-test cyanogenic compound levels for food-grade certification. Processing clusters around Nakhon Ratchasima and Kanchanaburi provinces supply the bulk of Asia-Pacific's export-grade output, with cooperatives now negotiating direct procurement contracts that bypass traditional trading houses.
Indonesia
Domestic bubble tea chain expansion and regional snack manufacturing drive pearl and flour consumption across Southeast Asian markets. The national food safety regulator mandates residual toxin documentation for cross-border shipments, aligning with import-country requirements. Facilities in Lampung and East Java concentrate capacity for international buyers, though smaller processors face steep adaptation costs for laboratory certification capabilities.
United States
Gluten-free bakery reformulation and clean-label sauce thickening applications absorb expanding volumes of high-purity native starch. The FDA governs food-grade granule purity and allergen labeling requirements for domestic distribution and re-export processing. Industrial food manufacturers in the Midwest and Southeast regions are establishing multi-year volume contracts with named Thai farm clusters, embedding sustainability riders into procurement agreements.
Germany
Sauce and soup manufacturers specify high-grade native starch for viscosity control in premium retail condiment segments. REACH compliance restricts residual cyanogenic compound levels, forcing processors to validate detoxification protocols with third-party laboratory documentation. The Rhine-Ruhr industrial corridor hosts formulation facilities that source through certified supply tiers, creating segmentation between validated and uncertified import channels.
Brazil
Traditional flatbread formulations and emerging gluten-free bakery applications drive demand for coarsely milled flour with retained fiber content. The national health surveillance agency oversees food-grade starch safety standards for domestic manufacturing and Mercosur trade. Processing facilities in Minas Gerais and São Paulo states supply pão de queijo manufacturers while exploring export opportunities for clean-label wheat alternatives in African markets.
Granulated Tapioca Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable packaging and pharmaceutical-grade specifications as differentiation vectors. The supplier base organizes around three maturity levels: multinational agribusiness conglomerates with integrated Southeast Asian supply chains, regional processors with vertically controlled facilities, and specialty distributors anchoring European formulation networks. Strategic moves concentrate on backward integration into farm-level sourcing and capacity reallocation from native granules toward higher-margin modified starches.
Within the integrated agribusiness tier, Cargill, Incorporated and Tate & Lyle PLC exemplify divergent geographic anchoring strategies—one leveraging North American manufacturing presence with Southeast Asian farm relationships, the other occupying European specialty distribution networks. PT Budi Starch & Sweetener Tbk represents the vertically controlled regional archetype, with Indonesian processing facilities supplying domestic and export channels. These three entities illustrate how scale, geography, and supply chain configuration define competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Royal Avebe U.A. |
| Archer Daniels Midland Company |
| PT Budi Starch & Sweetener Tbk |
| Thai Wah Public Company Limited |
| Cargill, Incorporated |
| Roquette Frères |
| Grain Processing Corporation |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
Industrial bakery and sauce manufacturers in North America and Europe anchor contract pricing through multi-year offtake agreements with named Thai processing clusters, embedding sustainability certification premiums that stratify supply tiers.
Pricing Analysis
Distributor margins compress as direct procurement relationships between North American food manufacturers and Thai farm cooperatives displace traditional trading house intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified export grades from domestic foodservice tiers and commodity spot lots. Price erosion runs through standard-grade native starch as potato and corn alternatives capture cost-sensitive soup applications. Smaller Indonesian processors face the steepest buyer price sensitivity due to laboratory certification gaps that exclude them from premium European contracts.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore serve as consolidation hubs for containerized shipments from Nakhon Ratchasima and Kanchanaburi processing clusters. Supply concentrates in Thailand and Indonesia, with Lampung and East Java facilities feeding Southeast Asian bubble tea chains. Cassava root, processing enzymes, and detoxification chemicals constitute the critical input stack. Single-source vulnerability around Thai export-grade native granule supply intensifies as processors redirect capacity toward modified starches. Distribution runs through multi-year volume contracts with sustainability riders that bypass spot market volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal functions as a regulatory compounder, tightening certified sourcing requirements that restructure procurement eligibility and contract premiums across Atlantic trade corridors.
For Market Incumbents: Extend backward integration into named Thai farm clusters to secure cyanogenic compound documentation that satisfies divergent FDA and REACH requirements. Lock multi-year volume contracts with industrial bakery customers before modified starch capex barriers strand native granule capacity. Potato starch substitution in cost-sensitive sauce applications represents the priority threat demanding formulation partnership defenses.
For New Entrants and Emerging Players: Foodservice distributors serving bubble tea chains offer the most penetrable channel partner type for pearl supply entry without laboratory certification burdens. Target Indian bakery and convenience food manufacturing as white-space geography currently underserved by Atlantic-focused suppliers. Pursue biodegradable packaging film specifications as the fastest-climbing demand vertical with limited incumbent specialization.
For Investors and Strategic Acquirers: Integrated agribusiness conglomerates with Southeast Asian farm relationships are the most active acquirer in this space, consolidating processing capacity to capture modified starch value migration. Vertically controlled regional processors with in-house detoxification validation capabilities represent the priority acquisition archetype. Monitor REACH batch-level testing certificate adoption rates among Indonesian processors as the inflection signal distinguishing certified from uncertified supply tier viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Clusters | Cargill and Tate & Lyle anchor supply security through named Thai cooperative relationships that embed sustainability riders. |
| Detoxification Protocol Certification | REACH compliance investments separate European-export processors from domestic-only competitors in laboratory capability tiers. |
| Modified Starch Capacity Reallocation | Thai Wah redirects reactor investments toward higher-margin chemically altered derivatives that command formulation premiums. |
| Direct Procurement Contract Structuring | Midwest bakery manufacturers negotiate multi-year offtake agreements that displace traditional trading house intermediaries. |
| Biodegradable Packaging Film Development | Brand owner phase-out of petroleum-derived films creates thermoformed tray demand for tapioca-based barrier coatings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Thai cassava processing executives, European sauce manufacturer procurement leads, Indonesian farm cooperative managers, and FDA regulatory affairs specialists with secondary validation from Thai Ministry of Industry export certifications, REACH compliance documentation, customs trade data, and SEC filings from listed starch processors. Bottom-up volume modeling across product type, end use, and distribution channel segments triangulated against top-down macroeconomic anchors.
Historical reference periods anchored the projection horizon to documented capacity utilization and export volume trajectories without year-specific attribution. Segmentation dimensions modeled include product form, application maturity, and regional regulatory cluster complexity. CAGRs derived from slope-consistent growth assumptions applied across the modeling period. Cassava root price volatility indices and sustainability certification adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement timelines, modified starch technology substitution rates, and bubble tea channel saturation patterns. Forecasts reflect documented assumptions about processing capacity reallocation and regulatory harmonization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Global Sodium Starch Glycolate Market
Food Additives and Ingredients
Powdered Fats Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Beverage Encapsulants Market