
 Antimicrobial Packaging Ingredients for Food Packaging Market | 2026-2036
Antimicrobial Packaging Ingredients for Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Packaging Ingredients for Food Packaging Market Outlook
Specialized polymer chemists and food safety toxicologists are reorganizing how antimicrobial packaging scales from pilot formulations to commercial film extrusion. DSM leverages its nutrition science heritage to anchor positions in natural extract barriers for protein applications. BASF competes through backward integration into organic acid precursors, sustaining cost advantages across European dairy supply chains.
Antimicrobial packaging ingredients for food packaging comprise bioactive compounds—silver nanoparticles, essential oils, organic acids, and natural extracts—dispersed within polymer matrices or coated onto substrates to inhibit microbial proliferation through controlled release mechanisms. These ingredients typically function at concentrations between 0.1% and 5% by weight, with release kinetics tuned to target organisms such as Listeria monocytogenes or Aspergillus flavus over defined shelf-life windows. Active packaging formulations now lead ingredient type deployment for meat products, where oxygen-scavenging and antimicrobial functions combine to address anaerobic pathogen risks. Essential oils represent the fastest-expanding natural segment, though margin pools remain concentrated in silver nanoparticle systems where manufacturing scale and regulatory dossier depth create defensive moats.
FDA food contact notification requirements and EPA antimicrobial pesticide registrations govern product entry in the United States, while EFSA and REACH frameworks in Europe impose migration limit validations and substance authorization protocols that extend development timelines. These regulatory architectures directly shape R&D allocation, favoring companies with dedicated regulatory affairs capacity and existing food contact substance dossiers. Stakeholders must monitor evolving definitions of active versus passive packaging under emerging circular economy rules, as recyclability mandates could force reformulation of multi-layer antimicrobial structures.
Market Dynamics
Migration limit tightening under EU REACH and the EU Green Deal is forcing reformulation of synthetic biocide systems, accelerating R&D redirection toward natural extract barriers and controlled-release polymer architectures.
Growth Catalysts
- REACH Compliance Deadlines:ECHA substance authorization protocols are compelling fresh produce distributors to adopt active packaging films, creating immediate demand pull for compliant antimicrobial systems.
- Centralized Retail Procurement:German retail chains now mandate extended shelf-life standards for packaged proteins, concentrating volume commitments among film converters with validated barrier technologies.
- Silver Nanoparticle Manufacturing Scale:Defensive moats from regulatory dossier depth and production capacity are consolidating supply relationships with dairy and meat processors seeking pathogen inhibition guarantees.
Market Restraints
- Essential Oil Input Volatility:Agricultural supply fluctuations for thyme, oregano, and citrus extracts create margin compression for natural antimicrobial formulators.
- Multi-Layer Structure Recyclability Mandates:Emerging circular economy rules under EU Green Deal implementation threaten existing multi-layer antimicrobial film architectures with forced redesign costs.
- EFSA Migration Validation Timelines:Extended substance authorization protocols delay commercialization of novel bioactive compounds by 18-36 months.
Strategic Opportunities
- Fresh Produce Export Corridors:Spain and Italy present underpenetrated demand for active packaging targeting Aspergillus flavus suppression in stone fruit and leafy green shipments.
- Oxygen-Scavenging Antimicrobial Convergence:Dual-function formulations combining anaerobic pathogen inhibition with oxygen control offer premium positioning in vacuum-packed protein segments.
- Biodegradable Polymer Matrices:PLA and PHA substrate compatibility with natural extracts aligns with France's national plastic packaging reduction targets.
Industry Challenges
- Polymer-Food Safety Interface Expertise:Scarce talent pools combining polymer chemistry and toxicology training constrain pilot-to-production scaling timelines.
- Food Contact Notification Capital Burden:FDA dossier preparation and EPA antimicrobial pesticide registration require sustained investment without guaranteed approval outcomes.
- Release Kinetics Standardization:Absence of harmonized test methods for controlled-release validation creates customer qualification friction across European dairy supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Packaging Ingredients for Food Packaging Market |
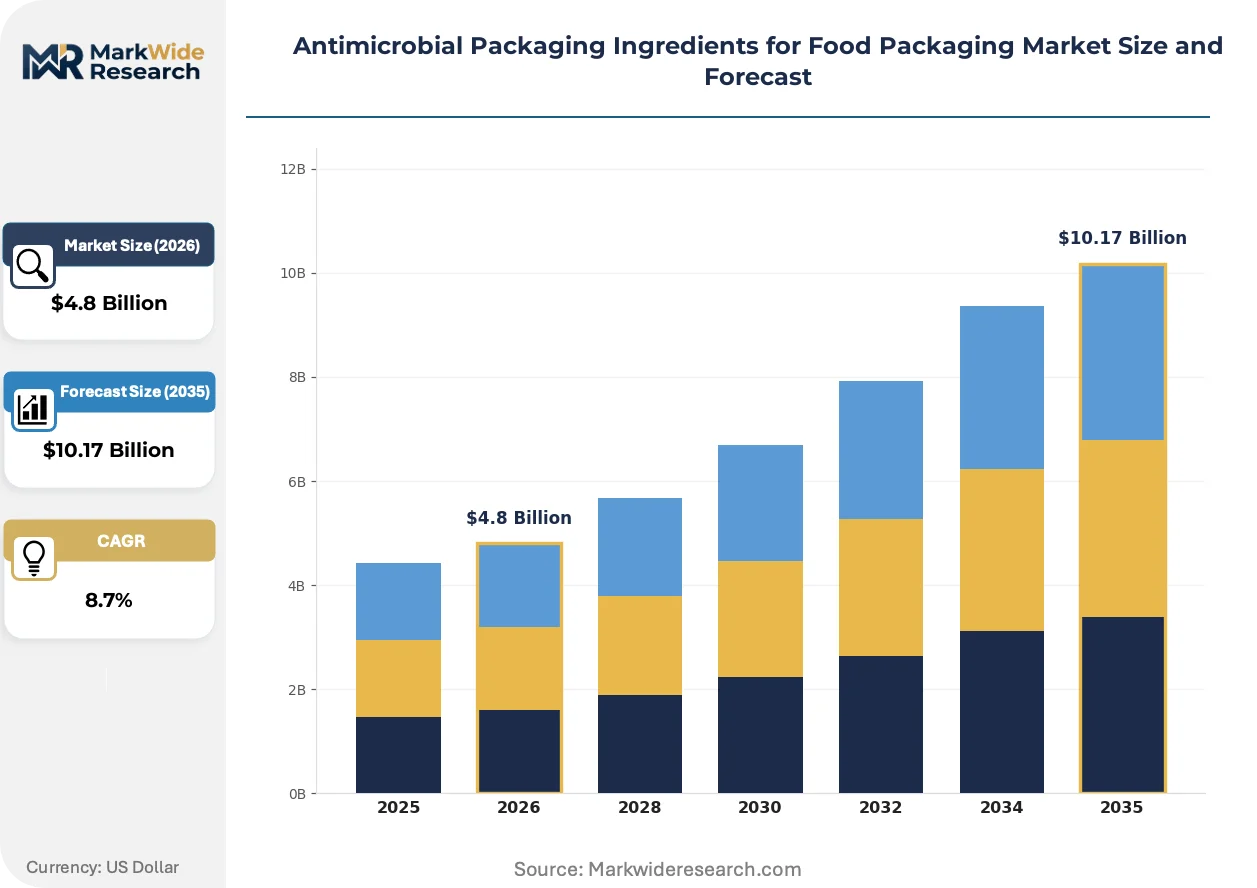
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Natural Extracts, Silver Nanoparticles, Essential Oils, Organic Acids Application: Meat Products, Dairy Products, Bakery Goods, Fresh Produce Formulation Type: Active Packaging, Passive Packaging, Modified Atmosphere, Smart Packaging End User: Food Manufacturers, Retailers, Food Service Providers, Packaging Companies |
| Companies Covered | DSM, Microban, BASF, Corbion, Mondi, Dow Chemical, BioCote, Kerry Group, Mitsubishi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Packaging Ingredients for Food Packaging Market Strategic Shifts
Formulation science is pivoting from broad-spectrum synthetic biocides toward targeted natural extract systems with tunable release profiles. This shift reconfigures competitive advantage around regulatory dossier depth rather than chemical manufacturing scale alone.
Chitosan-cinnamon oil nanocomposite films are displacing conventional silver-based systems in premium organic meat applications. Dutch protein processors have accelerated qualification timelines from 24 months to 8 months for these formulations. The technology is displacing legacy synthetic barriers by satisfying dual requirements for antimicrobial efficacy and clean-label positioning.
EFSA's evolving guidance on active versus passive packaging classification is forcing converters to restructure regulatory submission strategies. Manufacturers must now demonstrate that antimicrobial migration remains intentional and controlled rather than incidental. German film extruders are responding by segregating production lines and building dedicated food contact substance dossiers ahead of 2027 compliance checkpoints.
Buyer consolidation among European retail chains has compressed supplier qualification cycles and shifted contracting toward multi-year performance guarantees. French and Belgian distributors now require documented shelf-life extension metrics with penalty clauses for microbial exceedance. This procurement evolution favors ingredient suppliers with in-house microbiology testing capabilities and established relationships with centralized retail technical teams.
Antimicrobial Packaging Ingredients for Food Packaging Market Segmentation
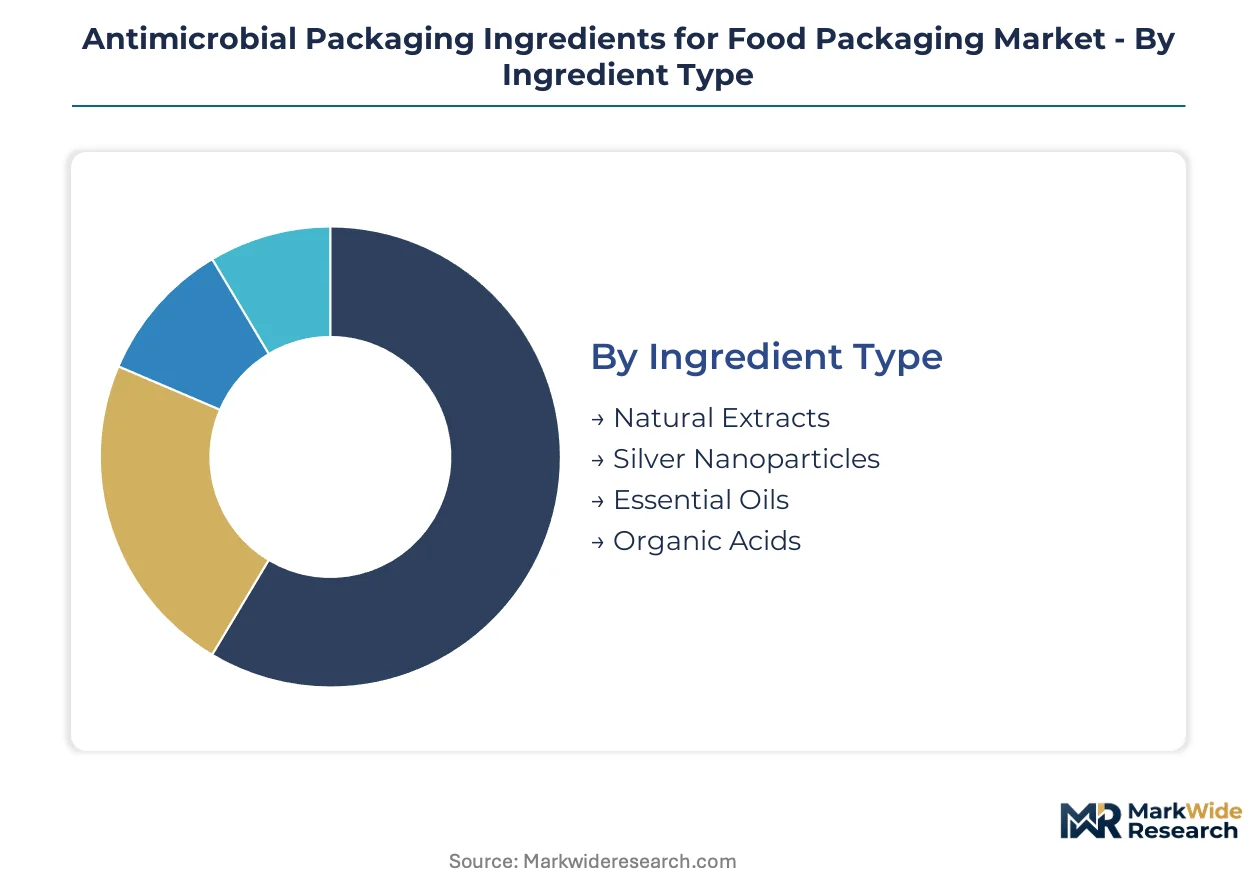
Antimicrobial packaging ingredient suppliers must align R&D and commercial resources against distinct performance requirements across biocide chemistry, food substrate sensitivity, and regulatory compliance pathways. Segmentation reveals where formulation investments translate into defendable margin positions versus commodity competition.
Ingredient Type:
Margin pools concentrate in synthetic biocide systems with validated regulatory dossiers, though natural alternatives are capturing premium positioning in clean-label channels.
- Natural Extracts:Chitosan, nisin, and plant-derived polyphenols function at 0.5-2% loading in protein matrices. German organic meat processors have compressed supplier qualification from 24 months to 8 months for these formulations, driven by EFSA clean-label positioning requirements and retail procurement mandates.
- Silver Nanoparticles:Metallic silver systems at 10-100 ppm concentrations deliver broad-spectrum efficacy through ionic release mechanisms. Manufacturing scale and REACH dossier depth create defensive supply relationships with dairy processors in Bavaria and Lower Saxony seeking Listeria monocytogenes inhibition guarantees.
- Essential Oils:Thymol, carvacrol, and citrus terpenes provide antifungal activity against Aspergillus flavus in fresh produce applications.
- Organic Acids:Sorbic, benzoic, and propionic acid derivatives remain cost-competitive in bakery preservation despite tightening EU migration limits.
The dominant share belongs to silver nanoparticles, while natural extracts are closing the gap fastest.
Application:
Volume concentration tracks protein sector procurement consolidation, with centralized retail chains dictating shelf-life specifications that cascade to ingredient suppliers.
- Meat Products:Vacuum-packed and modified-atmosphere formats combine oxygen-scavenging with antimicrobial functions to address anaerobic pathogen risks. Active packaging films incorporating organic acids or natural extracts now lead deployment in German retail chain supply chains mandating extended durability standards.
- Dairy Products:Fresh cheese and yogurt applications require fungal and Gram-positive bacterial inhibition without sensory impact. BASF's backward integration into organic acid precursors sustains cost advantages across European dairy supply chains serving discounter private-label programs.
- Bakery Goods:Mold inhibition in sliced bread and pastries drives demand for propionate-based systems and emerging essential oil barriers.
- Fresh Produce:Stone fruit and leafy green distributors in Spain and Italy are expanding adoption of active packaging to combat spoilage during export corridors.
Meat products command the largest volume commitment, though fresh produce applications are expanding most quickly.
Formulation Type:
Technology maturity separates validated commercial systems from developmental architectures facing circular economy compliance headwinds.
- Active Packaging:Intentional release systems with tunable kinetics dominate commercial deployment. EFSA's evolving guidance now requires demonstration that antimicrobial migration remains controlled rather than incidental, forcing German film extruders to segregate production lines ahead of 2027 compliance checkpoints.
- Passive Packaging:Surface-bound biocides without intentional release face simpler regulatory pathways but limited efficacy duration.
- Modified Atmosphere:Gas composition control combined with antimicrobial liners addresses respiration dynamics in fresh produce shipments.
- Smart Packaging:Indicator-integrated systems with antimicrobial functions remain pre-commercial due to multi-layer recyclability mandate conflicts under EU Green Deal implementation.
Active packaging holds the established revenue base, while smart packaging faces steepest regulatory redesign costs.
End User:
Procurement authority concentration determines contract structure, with retail technical teams displacing manufacturer R&D as the primary qualification gatekeeper.
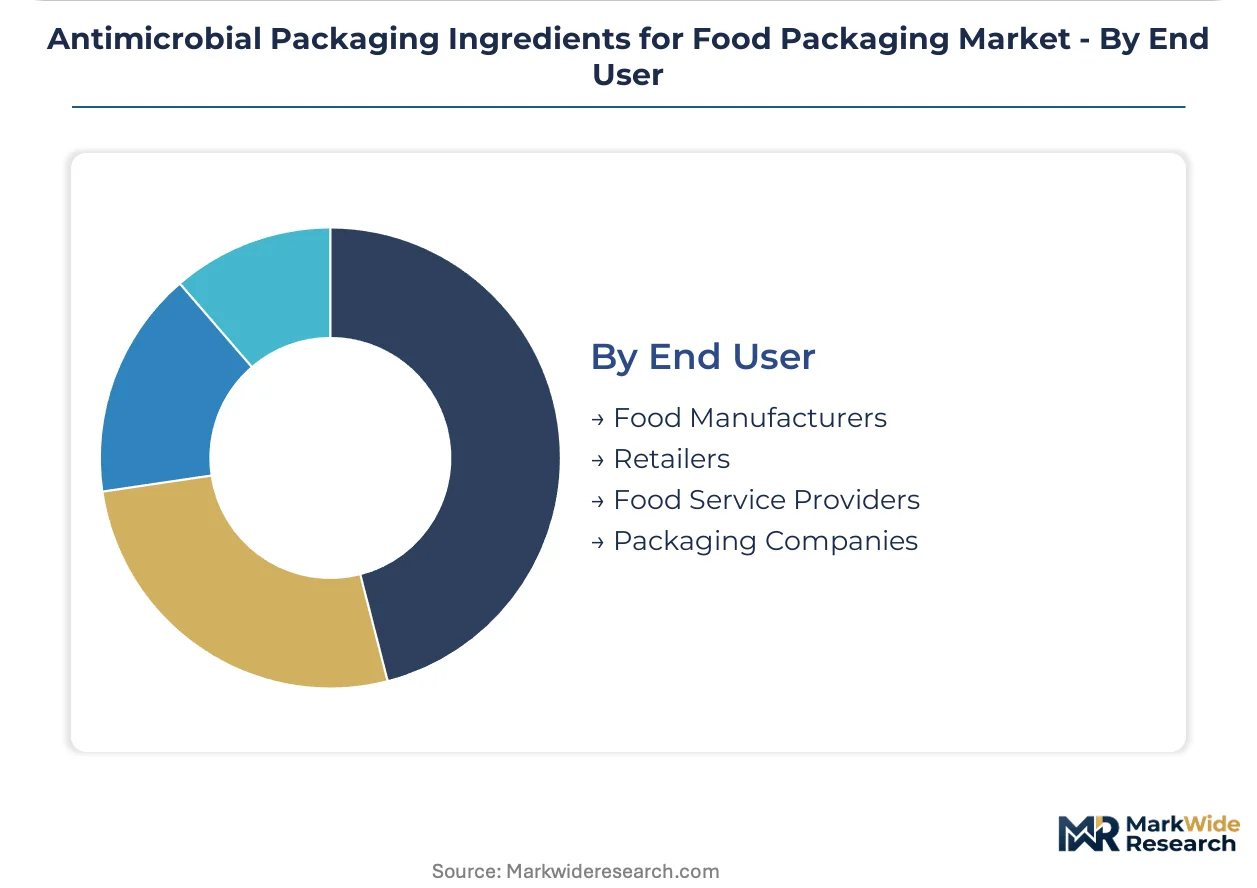
- Food Manufacturers:Branded protein and dairy processors specify antimicrobial barriers during packaging line retrofits. French and Belgian distributors now require documented shelf-life extension metrics with penalty clauses for microbial exceedance, favoring ingredient suppliers with in-house microbiology testing capabilities.
- Retailers:Centralized technical procurement at German chains mandates barrier performance standards that film converters must validate through multi-year performance guarantees.
- Food Service Providers:Prepared meal and catering segments drive demand for portion-control packaging with antimicrobial liners.
- Packaging Companies:Film extruders and converters face qualification cycle compression as buyer consolidation reduces supplier slots.
Food manufacturers retain the deepest technical relationships, while retailers are capturing specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA substance authorization protocols and REACH migration limits anchor European regulatory gravity for antimicrobial packaging ingredients. Fresh produce export corridors and centralized retail procurement across multiple jurisdictions concentrate formulation demand in specific national markets.
Germany
Centralized retail chains mandate extended shelf-life standards for packaged proteins, driving film converter validation requirements. ECHA authorization timelines compress supplier qualification cycles for active packaging systems. Bavarian and Lower Saxony dairy processors concentrate procurement relationships with REACH-dossier-compliant ingredient suppliers.
United States
FDA food contact notifications and EPA antimicrobial pesticide registrations govern market entry for silver nanoparticle and organic acid systems. Branded protein processors specify barrier technologies during packaging line retrofits. Midwest meatpacking clusters and California fresh produce distributors anchor demand concentration for controlled-release formulations.
France
National plastic packaging reduction targets accelerate biodegradable polymer matrix adoption for natural extract barriers. ANSM and DGCCRF enforcement of migration limits favors suppliers with established food contact substance dossiers. Paris Basin retail technical teams displace manufacturer R&D as primary qualification gatekeepers for antimicrobial film specifications.
Spain
Stone fruit and leafy green export corridors to Northern Europe drive active packaging adoption for Aspergillus flavus suppression. Spanish Ministry of Health coordination with EFSA guidance shapes controlled-release validation requirements. Valencia and Murcia agricultural clusters expand procurement of oxygen-scavenging antimicrobial liners for extended shipping durations.
Italy
Premium organic meat applications accelerate chitosan-cinnamon oil nanocomposite qualification timelines. Italian Ministry of Health enforcement of EU Green Deal circular economy rules threatens multi-layer structure recyclability. Emilia-Romagna and Lombardy protein processing clusters prioritize clean-label positioning in retail private-label programs.
Antimicrobial Packaging Ingredients for Food Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in antimicrobial packaging ingredients. Consolidation around regulatory dossier depth and manufacturing scale separates defensive supply relationships from commodity positioning. Three archetypes dominate: nutrition-science heritage companies leveraging natural extract barriers, chemical majors with backward integration into organic acid precursors, and surface-treatment specialists with antimicrobial additive expertise. Competitive moves concentrate on multi-year performance guarantee contracting and dedicated food contact substance dossier construction ahead of 2027 compliance checkpoints.
Within the integrated chemical tier, DSM and BASF exemplify divergent strategic anchors. DSM represents the nutrition-science heritage archetype, while BASF occupies the backward-integrated precursor position. Among surface-treatment specialists, Microban sits within the antimicrobial additive expertise cluster. These three companies illustrate how regulatory capacity and manufacturing scale separate tier positions in European protein and dairy supply chains.
| Leading Market Players |
|---|
| DSM |
| Microban |
| BASF |
| Corbion |
| Mondi |
| Dow Chemical |
| BioCote |
| Kerry Group |
| Mitsubishi Chemical |
| Others |
Value Chain & Pricing Dynamics
REACH authorization protocols gate both supplier qualification cycles and price differentiation tiers simultaneously, compressing margins for non-compliant formulators while rewarding dossier-heavy incumbents with premium positioning. Natural extract suppliers face agricultural input volatility that feeds back into contract structure redesign, forcing multi-year offtake negotiations to stabilize cost bases.
Pricing Analysis
German and French buyers command 15-25% price spreads over Spanish and Italian procurement for equivalent antimicrobial barrier specifications. Three-tier pricing structure across premium, standard, and economy levels separates REACH-validated silver nanoparticle systems from essential oil alternatives and commodity organic acid derivatives. Price differentiation hinges on EFSA migration validation status and volume scale commitments. Cost compression in the essential oil tier is intensifying because thyme and oregano harvest variability transfers directly to formulator margins. Discounter private-label programs in dairy applications show highest price sensitivity, while organic meat processors in the Netherlands and Belgium demonstrate lowest sensitivity due to clean-label premium capture.
Supply Chain Analysis
Germany and the Netherlands anchor polymer matrix production and film extrusion capacity for active packaging systems serving European protein supply chains. Raw material flows draw from Spanish citrus terpene extraction, Indian chitosan processing, and domestic German organic acid precursor manufacturing. Single-source vulnerability concentrates in silver nanoparticle feedstock, where three specialized chemical producers control REACH-compliant output. Distribution runs through centralized retail technical procurement teams that have displaced manufacturer-direct relationships, particularly in Bavarian and Lower Saxony dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal circular economy implementation disrupts incumbent multi-layer film architectures, creating a 36-month window where biodegradable matrix compatibility separates winners from forced reformulators. This regulatory inflection compresses qualification timelines and concentrates procurement authority among converters with pre-built food contact substance dossiers.
For Market Incumbents: Compound regulatory dossier depth through dedicated EFSA submission teams ahead of 2027 compliance checkpoints, defending against chitosan-cinnamon nanocomposite substitutes that threaten silver nanoparticle positioning in premium organic segments. Backward integration into essential oil agricultural contracting secures margin stability against input volatility that erodes natural extract formulators.
For New Entrants and Emerging Players: Lead with fresh produce export corridors in Spain and Italy, where Aspergillus flavus suppression demand runs ahead of qualified supplier capacity. Stone fruit and leafy green distributors present the most penetrable entry point, with oxygen-scavenging antimicrobial convergence offering differentiation against legacy passive barriers. Target microbiology testing capabilities as the go-to-market anchor, satisfying French and Belgian distributor penalty-clause requirements that incumbents struggle to meet at speed.
For Investors and Strategic Acquirers: EFSA's evolving active versus passive packaging classification reshapes the acquisition landscape toward film extruders with segregated production lines and pre-validated release kinetics. Five-to-ten-year viability favors targets combining polymer chemistry expertise with in-house toxicology capacity, scarce talent pools that constrain scaling timelines. Watch German retail chain procurement consolidation velocity as the inflection signal, accelerating multi-year performance guarantee contracting that locks in supplier relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Construction | EFSA validation timelines compress competitive windows for compliant suppliers. |
| Biodegradable Matrix R&D | PLA and PHA compatibility aligns with France's national plastic reduction mandates. |
| Agricultural Input Contracting | Thyme and oregano offtake agreements stabilize essential oil formulator margins. |
| Microbiology Testing Capability Buildout | In-house validation satisfies retailer penalty-clause requirements in Belgian procurement. |
| Production Line Segregation | Dedicated active packaging extrusion separates compliant from incidental migration systems. |
Study Parameters
Operator-level perspectives from polymer chemists, food safety toxicologists, film extrusion plant managers, and retail technical procurement directors anchored the qualitative base for this study. Primary fieldwork combined structured interviews across German, Dutch, French, and Spanish supply chain nodes with secondary validation from EFSA guidance documents, ECHA substance authorization databases, EU Green Deal implementation trackers, and customs trade flow records. Bottom-up ingredient demand modeling triangulated against top-down packaging film production estimates.
Sensitivity analysis tested forecast outputs across scenarios varying REACH migration limit enforcement intensity, essential oil agricultural yield fluctuations, and retail procurement consolidation velocity. Segmentation dimensions modeled include biocide chemistry tier, food substrate sensitivity, formulation release mechanism, and regional regulatory cluster. CAGRs derived from anchored endpoint validation against historical adoption curves in comparable active packaging transitions. Industry-specific inputs incorporated film converter qualification cycle compression data and EFSA substance authorization pipeline status.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation, stable agricultural supply for natural extracts, or continued retail procurement authority concentration would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and buyer consolidation trajectory. Recalibration cycles align with material shifts in EFSA guidance interpretation and centralized retail technical team specification evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market