
 Clean Labelled Food Additives Market | 2026-2036
Clean Labelled Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Labelled Food Additives Market Analysis
Food science talent is rotating toward natural preservation and plant-derived stabilization, constraining legacy synthetic additive pipelines. Cargill, Incorporated leverages its integrated supply chain from farm to formulation to dominate clean-label sweetener and texturizer supply. Kerry Group plc anchors European beverage and dairy clean-label programs through specialized taste modulation technologies. ADM competes aggressively in non-GMO emulsifier development across North American bakery applications.
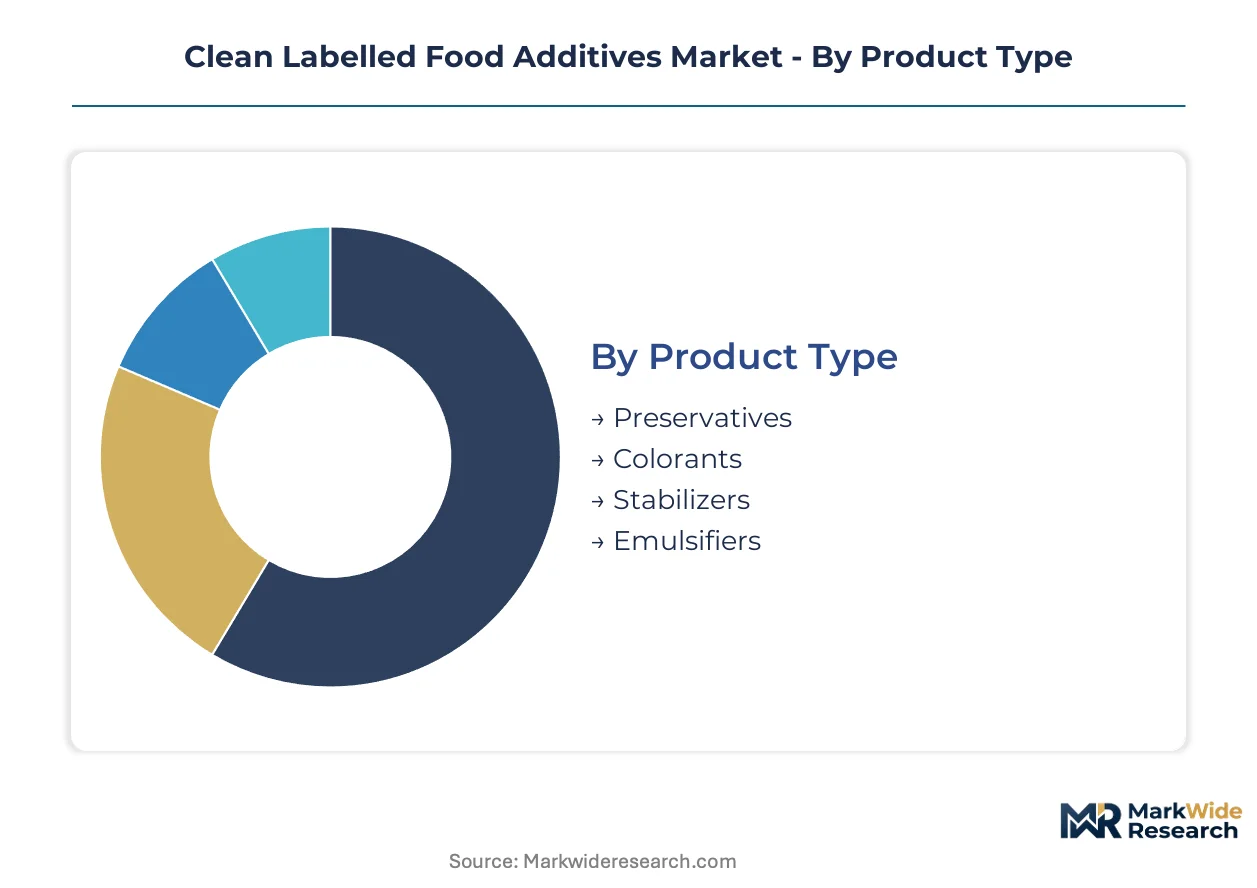
Clean labelled food additives comprise functional ingredients derived from natural sources such as plant extracts, fermentation metabolites, and minimally processed minerals, replacing synthetic counterparts while maintaining shelf stability, texture, and sensory performance in finished foods. Preservatives lead product type revenue owing to vinegar-based and cultured dextrose solutions displacing benzoates in shelf-stable beverages, while emulsifiers represent the fastest-expanding category as lecithin and acacia gum formulations penetrate clean-label bakery and snack segments. Food manufacturers command the dominant end-user share as reformulation mandates cascade from retail private-label specifications, with beverages and dairy products absorbing disproportionate volumes of colorant and stabilizer innovation.
FDA natural claim guidance, EFSA clean-label evaluations under the EU Green Deal framework, and USDA organic certification requirements collectively restrict permissible additive nomenclature and sourcing documentation. These standards compel suppliers to invest in traceability infrastructure and substantiation dossiers that smaller additive producers cannot readily assemble. Stakeholders must monitor evolving enzyme-classified processing aids and fermentation-derived ingredients as the next regulatory frontier where clean-label definitions remain contested.
Market Dynamics
Retail chain clean-label mandates are compressing reformulation timelines for packaged food manufacturers, forcing additive suppliers to accelerate natural preservation and texturizer development cycles.
Growth Catalysts
- EU Green Deal additive classifications:EFSA clean-label evaluations are compelling manufacturers to source plant-derived alternatives, expanding addressable demand for fermentation-based preservatives.
- Beverage sector reformulation:Shelf-stable drink producers are displacing benzoates with vinegar-based and cultured dextrose solutions, pulling through high-margin natural preservative volumes.
- Germany:Discounter and supermarket private-label specifications now require recognizable ingredient declarations, concentrating procurement among domestic clean-label suppliers.
Market Restraints
- Natural extract input volatility:Acacia gum and lecithin raw material costs fluctuate with African and South American harvest cycles, compressing emulsifier margin stability.
- Traceability infrastructure capex:USDA organic certification and EFSA substantiation dossiers require multi-year documentation investments that exclude smaller fermentation-derived ingredient producers.
- Performance gaps in high-moisture applications:Plant-derived stabilizers still exhibit shorter efficacy windows than synthetic alternatives in ambient dairy beverages.
Strategic Opportunities
- France:Premium bakery and patisserie channels remain underpenetrated for clean-label emulsifiers, offering first-mover positioning for lecithin-alternative suppliers.
- Fermentation-derived processing aids:Enzyme-classified ingredients occupy regulatory gray zones where clean-label definitions remain contested, creating white-space positioning.
- Direct-to-manufacturer digital platforms:Ingredient marketplaces are disintermediating traditional distribution, enabling smaller natural extract suppliers to reach mid-tier food processors.
Industry Challenges
- Food science talent scarcity:Natural preservation and plant-derived stabilization expertise is rotating away from legacy synthetic additive pipelines, constraining R&D throughput.
- Reformulation integration complexity:Clean-label ingredient swaps require sensory retesting and shelf-life validation that extends product development cycles by 12-18 months.
- Dual certification timelines:Simultaneous FDA natural claim documentation and EU organic equivalence approvals create parallel compliance burdens for multinational launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Labelled Food Additives Market |
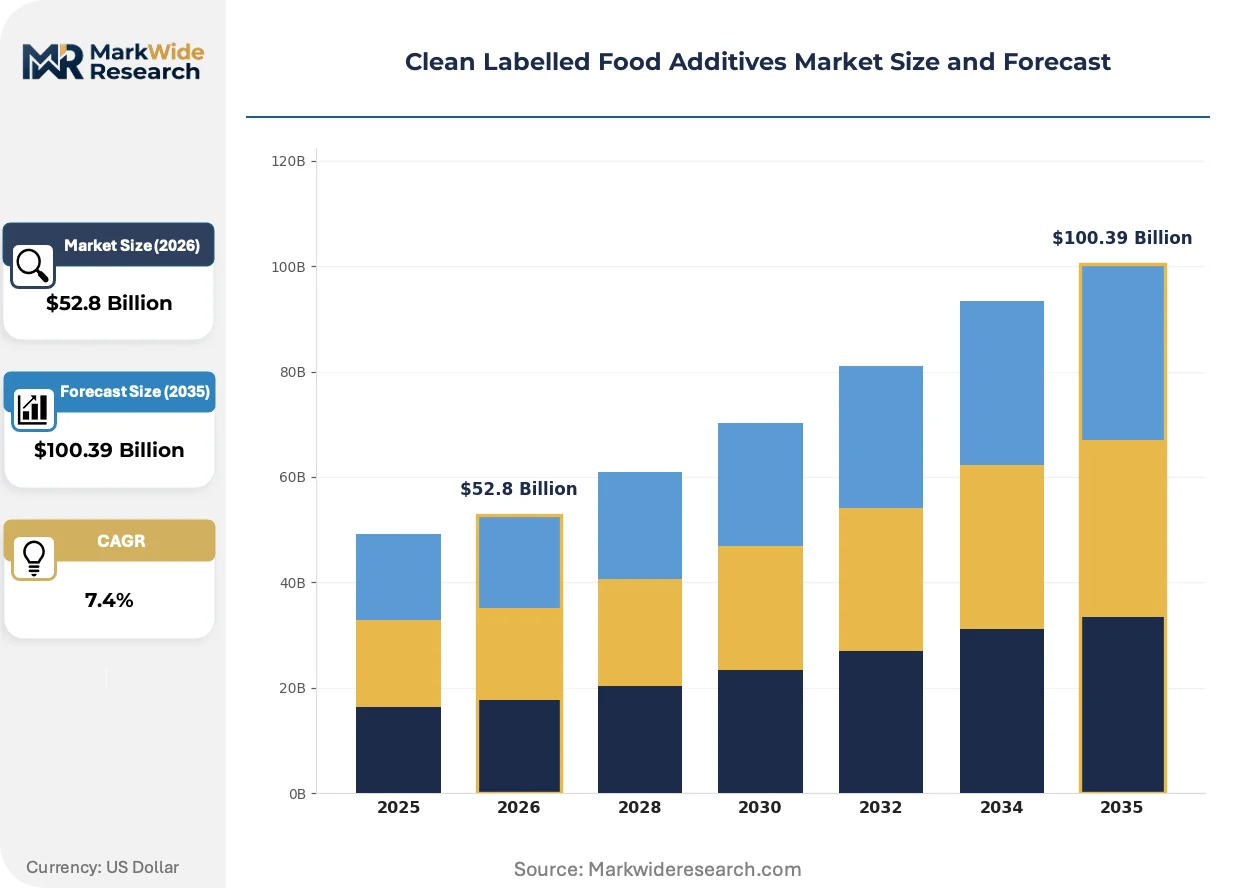
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $100.39 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Colorants, Stabilizers, Emulsifiers Application: Beverages, Dairy Products, Bakery, Snacks End User: Food Manufacturers, Retailers, Restaurants, Caterers Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Cargill, Incorporated, ADM, Kerry Group plc, Ingredion Incorporated, Tate & Lyle, DSM, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Labelled Food Additives Market Emerging Trajectories
Clean-label additive development is pivoting toward precision fermentation and enzymatic processing, compressing the performance gap between natural and synthetic functional ingredients.
Precision fermentation metabolites are miniaturizing production footprints for natural preservatives. Biotech suppliers are deploying modular fermentation systems near food manufacturing clusters in Germany and France. This distributed production model is compressing cold-chain requirements and enabling just-in-time delivery of cultured dextrose and vinegar derivatives to beverage processors.
REACH substance restrictions under ECHA evaluation are tightening residual solvent limits for plant extract processing. European flavor and colorant suppliers are investing in supercritical CO2 extraction infrastructure to maintain market access. Bakery and confectionery segments are absorbing the highest compliance costs as reformulation deadlines accelerate.
Ingredient declaration transparency is compressing switching cycles for private-label procurement. Retail chains in the United States are unbundling traditional supplier relationships in favor of direct clean-label additive sourcing. This disintermediation is most visible in the natural colorant category, where supermarket buyers now specify anthocyanin and beetroot extract grades independently of finished sauce manufacturers.
Clean Labelled Food Additives Market Segmentation
Clean-label additive procurement flows through distinct channel hierarchies that reshape supplier relationships. Food manufacturers direct bulk formulation decisions while retail chains increasingly specify ingredient grades independently.
Product Type:
Channel concentration varies sharply across functional categories, with beverage processors pulling preservatives through direct contracts and bakery channels sourcing emulsifiers via distributor networks.
- Preservatives:Vinegar-based solutions and cultured dextrose formulations displace benzoates in shelf-stable beverages. Demand concentrates in Germany and the United States where retail chains enforce additive transparency mandates, compressing reformulation timelines for suppliers.
- Emulsifiers:Lecithin and acacia gum formulations penetrate clean-label bakery and snack applications. France's premium patisserie channels absorb disproportionate volumes as EFSA evaluations tighten permissible classifications under the EU Green Deal.
- Colorants:Anthocyanin and beetroot extracts specified directly by supermarket buyers.
- Stabilizers:Plant-derived alternatives with shorter efficacy windows in ambient dairy.
By volume, preservatives lead procurement. By expansion trajectory, emulsifiers are climbing the fastest.
Application:
Cost tier stratification separates premium reformulation budgets from mass-market compliance-driven switches.
- Beverages:Shelf-stable drink producers drive vinegar-based preservative volumes through high-margin direct sourcing. Germany's discounter specifications cascade into manufacturer mandates, accelerating natural colorant adoption.
- Dairy Products:Ambient dairy beverages absorb disproportionate stabilizer innovation despite performance gaps against synthetic alternatives. EFSA substantiation dossiers constrain supplier participation to integrated players with traceability infrastructure.
- Bakery:Premium French patisserie channels underpenetrated for clean-label emulsifiers.
- Snacks:Acacia gum and lecithin formulations penetrating clean-label positioning.
By revenue scale, beverages dominate. By reformulation urgency, dairy is gaining share fastest.
End User:
Customer-type concentration shifts procurement power toward retail specification authority.
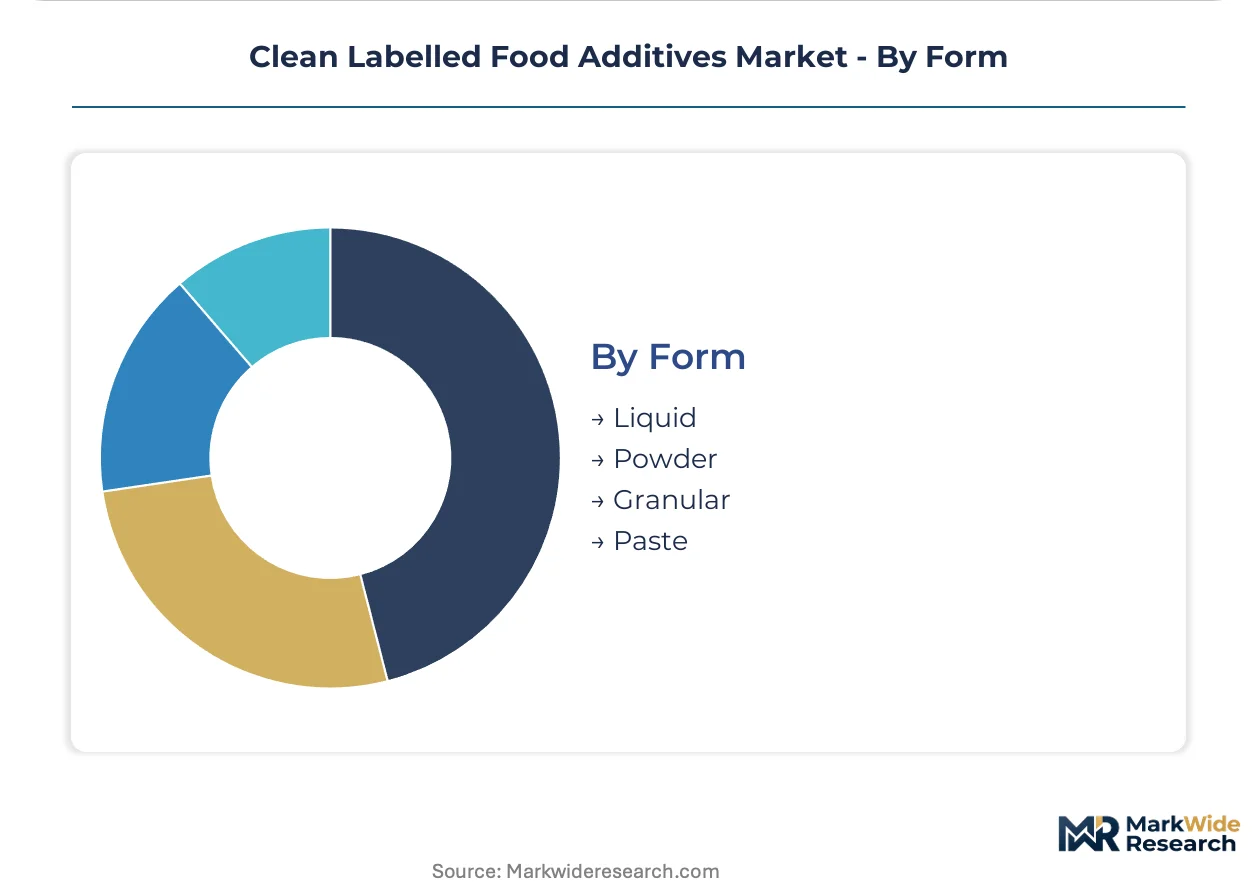
- Food Manufacturers:Command dominant share as reformulation mandates cascade from retail private-label specifications. Integrated suppliers like Cargill and Kerry Group anchor long-term formulation partnerships across North American and European beverage programs.
- Retailers:Unbundle traditional supplier relationships in favor of direct clean-label additive sourcing, particularly visible in natural colorant categories where supermarket buyers now specify extract grades independently.
- Restaurants:Limited volume but premium positioning for fermentation-derived ingredients.
- Caterers:Cost-sensitive procurement through distributor channels.
By contract value, food manufacturers lead. By specification authority growth, retailers are expanding most quickly.
Form:
Supply concentration in African acacia gum and South American lecithin harvests dictates form availability by geography.
- Liquid:Vinegar derivatives and fermentation metabolites delivered via modular systems near German and French manufacturing clusters, compressing cold-chain requirements for beverage processors.
- Powder:Cultured dextrose and spray-dried plant extracts serving bakery and dry-mix applications with extended shelf stability.
- Granular:Minimal processing formats for organic certification compliance.
- Paste:Concentrated stabilization systems for high-moisture dairy applications.
By logistics efficiency, liquid leads. By certification alignment, granular shows steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States drive preservative-heavy procurement for shelf-stable beverages, while France concentrates emulsifier demand in premium bakery channels. This consumption-mix differential shapes supplier investment patterns across developed markets.
United States
Retail chains enforce clean-label shelf standards that cascade into manufacturer reformulation mandates. FDA guidance on natural claims tightens permissible additive classifications, compelling traceability infrastructure investments. Chicago and Minneapolis-St. Paul host beverage manufacturing clusters where vinegar-based preservatives displace synthetic alternatives.
Germany
Discounter private-label specifications demand recognizable ingredient declarations, accelerating natural colorant adoption. EU Green Deal additive classifications through EFSA evaluations expand fermentation-based preservative addressable demand. Bavaria and North Rhine-Westphalia concentrate dairy processing facilities absorbing disproportionate stabilizer volumes.
France
Premium bakery and patisserie channels remain underpenetrated for clean-label emulsifiers, offering first-mover positioning opportunities. REACH substance restrictions under ECHA evaluation tighten residual solvent limits for plant extract processing. The Paris Basin and Lyon corridor anchor flavor and colorant supplier supercritical CO2 extraction infrastructure.
United Kingdom
Supermarket buyers unbundle traditional supplier relationships in favor of direct clean-label additive sourcing for private-label programs. FSA alignment with EFSA clean-label evaluations constrains permissible nomenclature and sourcing documentation. The Midlands and Greater London host ingredient marketplace platforms disintermediating traditional distribution channels.
Netherlands
Integrated supply chain players leverage Rotterdam port logistics for acacia gum and lecithin raw material throughput. EU organic certification equivalence requirements create parallel compliance burdens for multinational launches. The Randstad cluster concentrates fermentation-derived processing aid development facilities.
Clean Labelled Food Additives Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational agribusiness conglomerates controlling sweetener and texturizer supply against regional fermentation technology specialists. The market structure rewards backward integration into raw material sourcing and captive production of plant-derived stabilizers. Three archetypes dominate: farm-to-formulation integrators, taste modulation technology specialists, and non-GMO emulsifier developers. Competitive moves concentrate on modular fermentation system deployment near manufacturing clusters and direct-to-manufacturer digital platform establishment.
Within the integrated agribusiness tier, Cargill, Incorporated and ADM exemplify supply chain control strategies, while Kerry Group plc occupies a position in European taste modulation specialization. These anchors represent divergent paths to clean-label additive market positioning—upstream raw material dominance versus downstream formulation partnership depth.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM |
| Kerry Group plc |
| Ingredion Incorporated |
| Tate & Lyle |
| DSM |
| International Flavors & Fragrances Inc. |
| Sensient Technologies Corporation |
| Corbion |
| Others |
Supply Flow & Price Mechanics
Vinegar-based and cultured dextrose preservative solutions displacing benzoates simultaneously redraw supply geography toward fermentation hubs in Germany and France while compressing pricing premiums for legacy synthetic alternatives. This substitution dynamic concentrates procurement power among beverage manufacturers with direct contract leverage, eroding distributor margins on conventional preservative portfolios.
Pricing Analysis
Long-term offtake agreements anchor pricing for integrated suppliers like Cargill and Kerry Group, locking in volume commitments from major beverage processors across North American and European manufacturing clusters. Price differentiation separates USDA organic-certified fermentation metabolites from conventional plant extracts, with EFSA substantiation dossiers adding certification premiums. Cost compression in standard-grade acacia gum intensifies because African harvest volatility feeds raw material uncertainty. Mass-market bakery channels exhibit highest price sensitivity, while premium French patisserie buyers absorb organic certification premiums without volume elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate among German beverage processors deploying modular fermentation systems near manufacturing clusters, compressing cold-chain requirements for cultured dextrose delivery. Supply concentrates in South African acacia gum harvests, Brazilian and Argentinian lecithin production, and German precision fermentation capacity. Raw material dependencies include African gum arabic, South American soy and sunflower lecithin, and European fermentation feedstocks. Single-source vulnerability in African gum supply creates structural exposure to climate-driven harvest shortfalls. Distribution runs through direct manufacturer contracts for preservatives, with emulsifiers and colorants flowing via distributor networks to mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat environment where regulatory entrenchment creates substantial switching costs for food manufacturers reformulating around EFSA and FDA clean-label classifications. Incumbents benefit from multi-year substantiation dossiers that smaller competitors cannot readily replicate.
For Market Incumbents: Shield formulation partnerships by embedding taste modulation and stabilization expertise directly into customer R&D workflows, raising switching costs for beverage and dairy processors. Deepen backward integration into fermentation capacity near German and French manufacturing clusters to capture just-in-time delivery premiums. Counter emerging biotech fermentation specialists by accelerating enzyme-classified processing aid development before clean-label definitions solidify. For New Entrants and Emerging Players: Lead with white-space positioning in France's premium bakery emulsifier segment, where lecithin-alternative demand outstrips specialized supply. Target direct-to-manufacturer digital platforms as disintermediation channels, enabling mid-tier food processors to bypass traditional distributor markups on natural colorants and stabilizers. Anchor initial commercial traction through fermentation-derived processing aids occupying contested regulatory classification zones. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation technology specialists holding modular production platforms but lacking integrated formulation partnerships. Five-to-ten-year viability hinges on regulatory classification clarity for enzyme-derived ingredients and traceability infrastructure scalability. Watch EFSA clean-label evaluation timelines as the inflection signal determining which fermentation metabolite categories achieve permissible additive status.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fermentation Capacity Expansion | Compresses cold-chain logistics for cultured dextrose delivery to German beverage clusters. |
| Direct-to-Manufacturer Digital Platform Launch | Disintermediates distributor markups for natural colorant procurement by US retail chains. |
| EFSA Substantiation Dossier Investment | Secures clean-label additive classification under EU Green Deal framework for fermentation metabolites. |
| Backward Integration into Acacia Gum Sourcing | Stabilizes emulsifier margins against African harvest volatility through captive supply agreements. |
| Taste Modulation Technology Partnership | Locks in long-term formulation relationships with European dairy processors facing reformulation mandates. |
Methodological Framework
Initial hypotheses were tested against primary input from food science R&D directors, procurement leads at beverage manufacturers, regulatory affairs specialists, and retail category buyers, then refined through secondary validation. FDA guidance documents, EFSA scientific opinions under the EU Green Deal, USDA organic certification databases, and trade customs data for acacia gum and lecithin flows provided foundational secondary sources. Bottom-up volume modeling across preservative, emulsifier, colorant, and stabilizer categories triangulated against top-down market sizing from integrated supplier disclosures.
Variance decomposition across the projection horizon isolates volume drivers by application segment, with beverage and dairy reformulation urgency weighted separately from bakery and snack adoption curves. Segmentation dimensions include product type, application channel, end-user concentration, and form factor logistics. CAGRs derive from iterative convergence of demand-pull estimates from retail specification trends and supply-push capacity buildouts in fermentation infrastructure. Forecast inputs incorporate EFSA evaluation timelines and FDA natural claim guidance evolution as regulatory scenario variables.
Underlying assumptions cover sustained EU Green Deal implementation, stable FDA enforcement posture on natural claims, and continued retail chain clean-label mandate expansion, with deviation risk concentrated in regulatory classification delays for enzyme-derived processing aids and African gum supply disruptions. Revision becomes warranted when EFSA clean-label evaluation throughput crosses thresholds that accelerate or delay fermentation metabolite market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Baking Enzymes Market