
 Powdered Fats Market | 2026-2036
Powdered Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Powdered Fats Market Analytics
EU F-Gas Regulation is repositioning cold-chain economics for fat processors, raising compliance costs for manufacturers reliant on temperature-controlled spray drying. Kerry Group plc leverages captive dairy sourcing across Ireland and the Netherlands to insulate margin structures. Cargill anchors North American oilseed processing through backward integration into refined vegetable oil streams. Bunge Loders Croklaan specializes in tailored fat fractions for chocolate and confectionery, competing on crystallization control rather than commodity volume.
Powdered fats are lipid-based dry ingredients produced via spray drying, microencapsulation, or drum drying of oils and fats with carrier matrices such as maltodextrin or milk proteins, yielding free-flowing powders with fat contents ranging from 30% to 80% for shelf-stable incorporation into dry mixes and processed foods. Vegetable fat powder leads volume in emerging-market bakery applications where cost stability trumps dairy provenance, while cream powder commands premium positioning in European confectionery where Protected Designation of Origin credentials support price architecture. Dairy fat powder occupies a narrowing mid-tier as plant-based alternatives displace conventional butter powders in industrial sauce formulations.
FDA GRAS self-determination governs U.S. fat powder formulations for food use, while EFSA novel food assessments constrain entry of emerging lipid sources into European formulations; China's SAMR enforces GB standards on trans fat labeling that directly reformulate product specifications for export-oriented manufacturers. Stakeholders must monitor divergence between EU Green Deal methane targets and U.S. biofuel policy incentives for oilseed diversion, as these competing regulatory vectors will determine feedstock availability and regional cost premiums.
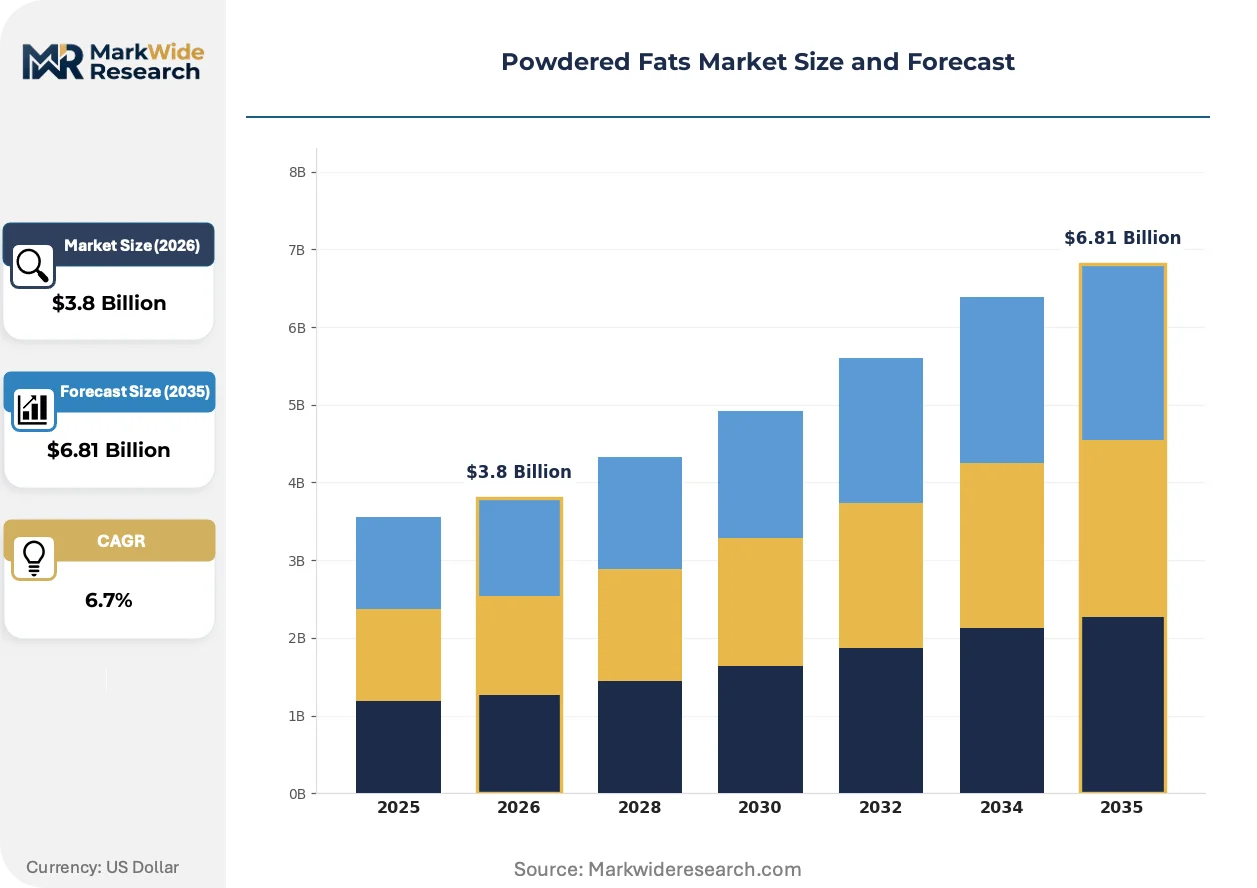
Market Dynamics
EU F-Gas Regulation compliance costs are restructuring cold-chain economics for temperature-controlled spray drying operations, forcing processors to absorb capital outlays or relocate production to jurisdictions with lighter refrigerant restrictions.
Growth Catalysts
- Plant-based bakery demand:Commercial kitchens across Germany and the Netherlands are accelerating uptake of vegetable fat powders as cost-stable alternatives to dairy-derived formulations in industrial bread and pastry production.
- REACH-aligned lipid innovation:EFSA novel food assessments for emerging oil sources are creating compliant pathways for algae and microbial lipid powders to enter European confectionery applications.
- Microencapsulation advances:Spray drying equipment manufacturers in Italy are delivering higher-throughput systems that reduce carrier matrix ratios while preserving oxidative stability in finished powders.
Market Restraints
- Palm oil price volatility:Malaysian and Indonesian export duty fluctuations transmit directly into vegetable fat powder cost structures, compressing margins for processors without captive upstream supply.
- Refrigerant compliance burden:EU F-Gas Regulation phase-down schedules for hydrofluorocarbons are raising retrofit costs for existing spray drying facilities in France and Poland.
- Dairy fat substitution ceiling:Cream powder retains functional advantages in chocolate tempering applications that plant-based alternatives cannot replicate at equivalent crystallization kinetics.
Strategic Opportunities
- India industrial bakery expansion:FSSAI-aligned trans fat labeling rules are creating formulation windows for domestic fat powder producers to displace imported shortenings in biscuit and cracker manufacturing.
- Sports nutrition convergence:MCT oil powders combining with protein isolates are penetrating ready-to-mix beverage formats as ketogenic diet adherence expands in North American and Australian markets.
- SAMR export pathway:China's GB standards on trans fat disclosure are compelling reformulation of fat powders destined for Chinese food manufacturers, favoring suppliers with in-house analytical certification capabilities.
Industry Challenges
- Spray drying engineering talent scarcity:Specialized process engineers capable of optimizing nozzle configurations for high-fat-content emulsions are concentrated among a handful of equipment vendors in Denmark and Germany.
- Novel food authorization timelines:EFSA assessment durations for emerging lipid sources stretch 18-24 months, delaying market entry for fermentation-derived fat powders even after technical validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powdered Fats Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter Powder, Vegetable Fat Powder, Cream Powder, Dairy Fat Powder Application: Baking, Confectionery, Dairy Products, Sauces End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Animal Feed Packaging Type: Box, Pouch, Drum, Bulk |
| Companies Covered | Kerry Group plc, Royal FrieslandCampina N.V., Cargill, Archer Daniels Midland (ADM), Bunge Loders Croklaan, Fonterra Co-operative Group Limited, Aarkay Food Products Ltd., Zeon Lifesciences Ltd., Barry Callebaut AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powdered Fats Market Evolving Landscape
Processing technology and regulatory chemistry are converging to redefine what fat powders can deliver functionally, with crystallization control and clean-label positioning now separating viable suppliers from commodity players.
Cold-spray agglomeration is rewriting powder engineering possibilities for heat-sensitive lipid systems. Specialty chocolate manufacturers in Belgium and Switzerland are adopting these units to preserve volatile flavor compounds in cocoa butter alternatives. The technology is compressing the performance gap between premium dairy fats and refined vegetable substitutes in tempering applications.
EU Green Deal methane targets are redirecting Irish and Dutch dairy processors toward biogas capture investments that offset carbon intensity metrics for exported cream powders. German industrial bakers are now requesting batch-level carbon footprint documentation as a procurement gate. This is forcing suppliers to integrate lifecycle assessment capabilities or exit premium contract tiers.
Clean-label procurement patterns are consolidating buyer preference around single-ingredient carrier matrices. North American plant-based meat formulators are rejecting maltodextrin-heavy powders in favor of tapioca or pea protein carriers that align with grain-free positioning. The shift is most visible in California and Pacific Northwest alternative protein clusters where ingredient statement transparency commands price premiums.
Powdered Fats Market Segmentation
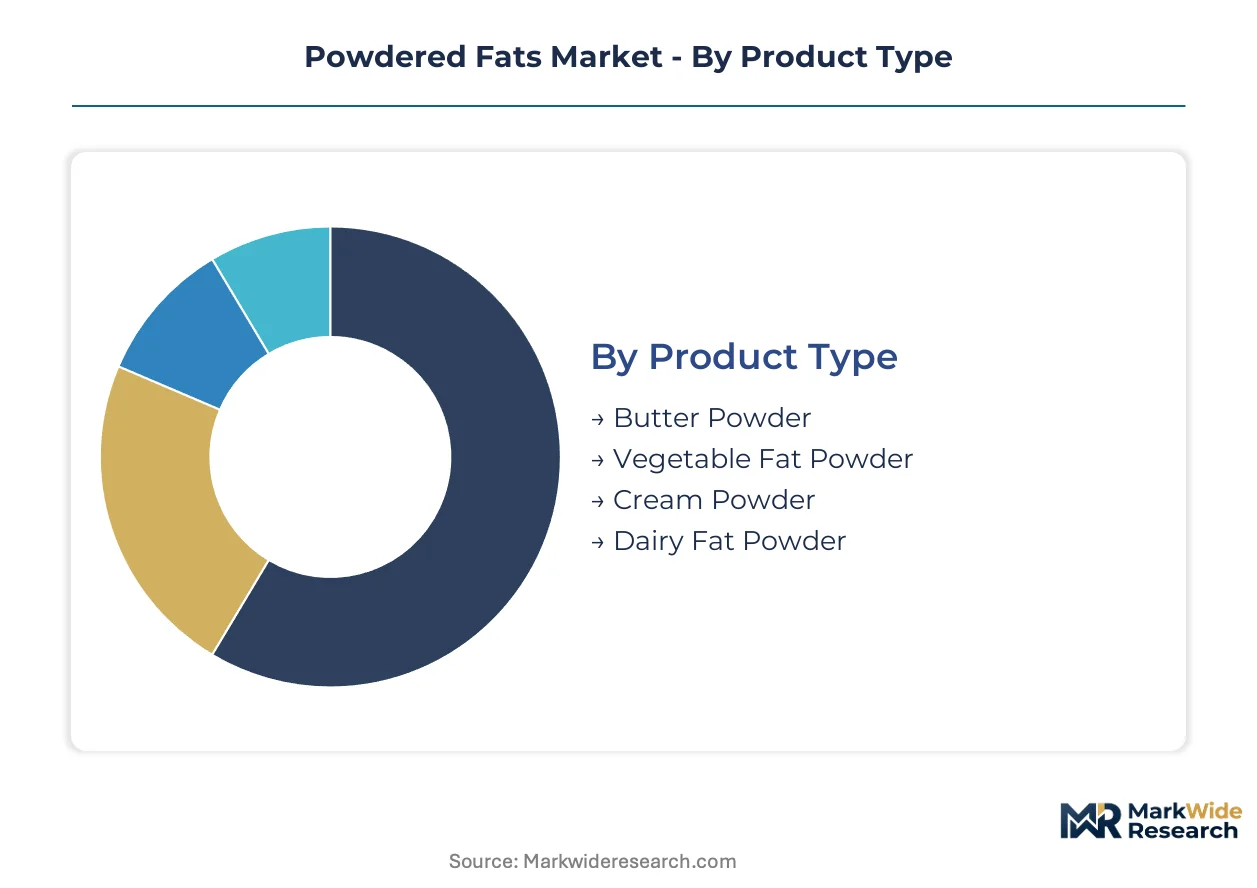
Powdered fats serve divergent functional requirements across temperature-sensitive, shelf-stable, and controlled-release applications. Segment boundaries reflect raw material sourcing economics, processing complexity, and end-use performance specifications rather than interchangeable commodity logic.
Product Type:
Supply concentration for lipid feedstocks and carrier matrices determines competitive positioning within each product category.
- Vegetable Fat Powder:Refined palm, coconut, and shea fractions spray-dried with maltodextrin or modified starch carriers yield fat contents of 50-80%. German industrial bakeries and Dutch bread manufacturers are displacing dairy shortenings as EU dairy price volatility compresses margin predictability in contract baking.
- Cream Powder:Anhydrous milk fat microencapsulated in milk protein or lactose matrices preserves emulsification properties for chocolate tempering and premium confectionery. Belgian and Swiss chocolate manufacturers maintain procurement preference here despite plant-based alternatives, as crystallization kinetics in cocoa butter equivalents remain unmatched.
- Butter Powder:Salted or unsalted butter oils dried onto carbohydrate carriers for flavor-dense bakery and sauce applications.
- Dairy Fat Powder:Blended milk fat systems occupying mid-tier positioning between cream powder purity and vegetable fat cost efficiency.
Vegetable fat powder absorbs the bulk of installed capacity; cream powder is expanding most quickly in premium confectionery channels.
Application:
Processing temperature requirements and fat crystallization behavior segment demand by technical performance thresholds.
- Baking:Powdered fats enable precise fat distribution in dry mixes without cold-chain dependency. Industrial bread and pastry operations in Germany's Ruhr corridor and the Netherlands' Gelderland province are standardizing on vegetable fat powders for laminated dough consistency.
- Confectionery:Tempering stability and mouthfeel precision demand tightly controlled fat crystal polymorphism. Belgian praline manufacturers and Swiss chocolate processors specify cream powder or specialized cocoa butter alternatives with defined melting profiles.
- Dairy Products:Reconstituted fat systems for ice cream mixes and processed cheese applications.
- Sauces:Cold-water dispersible fat powders for instant sauce and soup bases requiring emulsion stability without heating.
Baking commands the largest volume allocation; confectionery carries the steepest expansion trajectory as premium chocolate consumption climbs.
End Use Industry:
Regulatory scrutiny intensity and formulation complexity separate commercial viability across downstream sectors.
- Food & Beverage:Dominant demand channel spanning bakery, confectionery, and prepared foods. FDA GRAS self-determination in the U.S. and EFSA novel food assessments in Europe govern ingredient approval pathways, with China's SAMR trans fat labeling rules increasingly shaping export-oriented specifications.
- Cosmetics:Powdered shea and cocoa butter fractions for solid formulation skincare. ECHA REACH compliance for cosmetic-grade lipid powders constrains supplier qualification in European personal care manufacturing.
- Pharmaceuticals:Excipient-grade fat powders for controlled-release tablet coatings and lipid-based drug delivery systems.
- Animal Feed:Energy-dense fat supplementation for aquaculture and livestock nutrition.
Food and beverage absorbs dominant capacity; pharmaceuticals is climbing the fastest as lipid-based drug delivery expands.
Packaging Type:
Moisture protection requirements and handling automation compatibility drive format selection.
- Bulk:Tanker or silo delivery for high-volume industrial users with integrated pneumatic handling systems. German and Polish industrial bakeries with continuous mixing operations specify bulk to minimize packaging waste and labor.
- Drum:Steel or fiber drums with nitrogen flushing for mid-scale processors requiring batch traceability. French and Italian confectionery manufacturers favor this format for controlled atmosphere preservation during seasonal production cycles.
- Pouch:Multi-layer laminated bags for moisture and oxygen barrier in smaller commercial kitchens.
- Box:Cartoned retail or foodservice formats for direct-to-operator distribution.
Bulk packaging holds the majority of tonnage movement; pouch formats are gaining share fastest in artisanal and small-batch foodservice channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial baking corridors and Dutch food processing zones concentrate European powdered fats demand through tax-advantaged logistics hubs near Rotterdam and Hamburg.
Germany
Industrial bread and pastry manufacturers in North Rhine-Westphalia's Ruhr corridor standardize on vegetable fat powders for laminated dough consistency. The EU F-Gas Regulation forces retrofit investments in temperature-controlled spray drying facilities across the region. Cologne-based processors absorb compliance costs while expanding capacity for export-oriented confectionery clients.
Netherlands
Dairy fat powder exports from Gelderland province serve Belgian chocolate tempering applications where crystallization precision commands premium positioning. EFSA novel food assessments constrain entry of algae-derived lipid alternatives into European formulations. Rotterdam's port-centric logistics infrastructure enables just-in-time delivery to German industrial bakeries.
United States
North American oilseed processing anchors vegetable fat powder supply through backward integration into refined oil streams. FDA GRAS self-determination governs formulation approvals for foodservice dry mixes. Chicago-area commercial bakeries displace dairy shortenings with plant-based alternatives as cost volatility compresses margin predictability.
China
SAMR-enforced GB standards on trans fat labeling compel reformulation of export-bound fat powders for domestic biscuit manufacturers. Yangtze River Delta food processors request batch-level carbon documentation under tightening procurement protocols. Shanghai-based analytical certification providers capture value from compliance-driven supplier qualification.
India
FSSAI-aligned trans fat rules create formulation windows for domestic producers to displace imported shortenings in cracker manufacturing. Maharashtra's industrial bakery clusters near Mumbai expand capacity for regional quick-service restaurant chains. Gujarat-based oilseed processors invest in spray drying equipment to capture share from Malaysian palm oil dependencies.
Powdered Fats Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated agribusiness operators with captive oilseed supply, dairy cooperatives leveraging milk fat provenance, and equipment-anchored technology licensors. Consolidation pressure concentrates among mid-scale European processors facing refrigerant compliance burdens. Dominant competitive moves include geographic relocation to lighter-regulation jurisdictions and portfolio diversification into microencapsulation services.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland occupy positions defined by upstream control over North American and South American oilseed streams. Kerry Group plc exemplifies the dairy-provenance archetype through Ireland and Netherlands-based milk fat sourcing. Bunge Loders Croklaan anchors the specialty fractionation segment with crystallization-control capabilities for chocolate applications. These three represent divergent margin-defense strategies against feedstock volatility and regulatory compliance cost inflation.
| Leading Market Players |
|---|
| Kerry Group plc |
| Royal FrieslandCampina N.V. |
| Cargill |
| Archer Daniels Midland (ADM) |
| Bunge Loders Croklaan |
| Fonterra Co-operative Group Limited |
| Aarkay Food Products Ltd. |
| Zeon Lifesciences Ltd. |
| Barry Callebaut AG |
| Others |
Value Network & Pricing Analysis
German industrial bakeries and Dutch bread manufacturers command pricing leverage through consolidated procurement consortia, extracting volume discounts that compress margins for mid-tier vegetable fat powder suppliers without captive oilseed supply.
Pricing Analysis
Short lead-time premiums reward suppliers with Rotterdam and Hamburg port-adjacent warehousing, while spot inventory discounts clear excess carrier-matrix stocks during seasonal demand troughs. Contract-based long-term offtake dominates, with price differentiation hinging on EFSA novel food certification tier and carbon footprint documentation grade. Cost compression in standard-grade vegetable fat powders intensifies as Malaysian palm oil duty volatility transmits downstream. Artisanal confectionery manufacturers show least price sensitivity, prioritizing crystallization control over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from Belgian chocolate manufacturers and French sauce processors require qualified backup suppliers for both lipid feedstocks and carrier matrices, lengthening vendor qualification cycles. Supply concentrates in Malaysia and Indonesia for palm fractions, the Netherlands for dairy fat systems, and Germany for spray drying equipment. Raw material dependencies span refined vegetable oils, milk protein isolates, and maltodextrin carriers. Single-source vulnerability persists in specialized nozzle engineering talent concentrated among Danish and German equipment vendors. Distribution runs through Rotterdam's port-centric logistics hubs for just-in-time delivery to Ruhr corridor industrial bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation erects a cost-of-compliance moat that favors incumbents with capital reserves for refrigerant retrofit investments, disadvantaging prospective entrants lacking established cold-chain infrastructure.
For Market Incumbents: Cement market position by acquiring distressed mid-scale spray drying facilities in Poland and France facing compliance-driven exit pressure. Prioritize backward integration into refined vegetable oil streams to insulate margin structures from Malaysian export duty volatility. Defensive consolidation around microencapsulation service capabilities preserves premium tier access as clean-label carrier matrix demands intensify.
For New Entrants and Emerging Players: Launch via private-label supply agreements with Maharashtra-based industrial bakeries serving India's quick-service restaurant expansion. Target white-space in sports nutrition MCT oil powders for North American ketogenic beverage formats. Exploit the 18-24 month EFSA novel food assessment gap by securing early-mover position in algae-derived lipid powders before regulatory pathways mature.
For Investors and Strategic Acquirers: The window for entry favors equipment-anchored technology licensors with proprietary cold-spray agglomeration capabilities. Long-term viability rests on crystallization-control IP rather than commodity volume positioning. Watch for inflection when batch-level carbon documentation becomes mandatory procurement gate across German industrial baking contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Retrofit Investment | EU F-Gas Regulation compliance preserves operational licenses for temperature-controlled spray drying in France and Poland. |
| Backward Integration into Oilseed Processing | Cargill's captive supply model insulates margin structures from Malaysian and Indonesian export duty fluctuations. |
| Microencapsulation Service Expansion | Bunge Loders Croklaan's crystallization-control capabilities command premium positioning in Belgian chocolate tempering applications. |
| Clean-Label Carrier Matrix Development | Tapioca and pea protein alternatives displace maltodextrin in California alternative protein cluster formulations. |
| Carbon Footprint Documentation Capability | German industrial bakers now require batch-level lifecycle assessment for premium contract tier access. |
Research Methodology
Independent corroboration across spray drying equipment manufacturers, lipid feedstock procurement directors, and confectionery formulation scientists underwrites the qualitative findings. Primary interviews with plant managers at German and Dutch industrial bakeries, regulatory affairs leads navigating EFSA novel food pathways, and technical R&D directors at carrier matrix suppliers combined with secondary validation. Trade data from Eurostat customs records, SEC filings from diversified agribusiness operators, and FAO oilseed production statistics anchored supply-side assessments. Bottom-up capacity utilization estimates triangulated against top-down demand projections from foodservice dry mix consumption patterns.
Comparable-period anchoring referenced pre-pandemic baseline volumes to calibrate recovery trajectories across the projection horizon. The analytical framework modeled segmentation across product type, application, and end-use industry dimensions, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from slope-consistency checks against historical price-volume elasticities in vegetable fat powder markets. Forecast inputs included EU Green Deal methane target stringency and SAMR trans fat labeling enforcement intensity as scenario-weighted demand modifiers.
The model assumes a particular technology adoption path; alternative pathways for cold-spray agglomeration equipment penetration would alter the outlook for premium cocoa butter substitute displacement. Forecasts reflect documented assumptions on refrigerant phase-down schedules and palm oil duty regime stability. Deviation in EFSA novel food assessment duration or F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Distilled Monoglycerides Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
India Food Colorants Market