
 Lycopene Food Colors Market | 2026-2036
Lycopene Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Lycopene Food Colors Market Foresight
Pharmaceutical-grade lycopene specifications is redrawing competitive boundaries in natural colorants. Lycored leverages vertical integration from tomato cultivation to extraction, sustaining cost advantages across European supply chains. BASF SE anchors its position through synthetic biology investments that broaden fermentation-derived lycopene output. Divi's Laboratories competes on fermentation scale, occupying a specialized niche in Asia-Pacific pharmaceutical and food-grade supply.
Lycopene food colors are carotenoid pigments extracted primarily from tomatoes or produced via microbial fermentation, delivering red-orange hues with specified E160d color index designation and thermal stability up to 180°C in pH-neutral matrices; manufacturers deploy these pigments to replace synthetic azo dyes in transparent ingredient declarations. Powder formats lead current volume owing to extended shelf stability and ease of dry-blending into seasoning and bakery premixes, while liquid concentrates represent the fastest-expanding category as beverage processors seek pumpable, meterable dosing systems. Gel and extract segments command premium positioning in artisanal confectionery and clean-label dairy applications where visual intensity and minimal processing claims support margin pools.
EMA and FDA frameworks govern colorant safety assessments, with EFSA establishing acceptable daily intake thresholds that directly shape formulation ceilings and product access across the European Union. REACH compliance and FSSC 22000 certification requirements further filter supplier eligibility, elevating documentation burdens for smaller extractors. Stakeholders must monitor evolving synthetic dye prohibition timelines and fermentation-derived lycopene Novel Food approval pathways to secure formulation pipelines ahead of regulatory displacement waves.
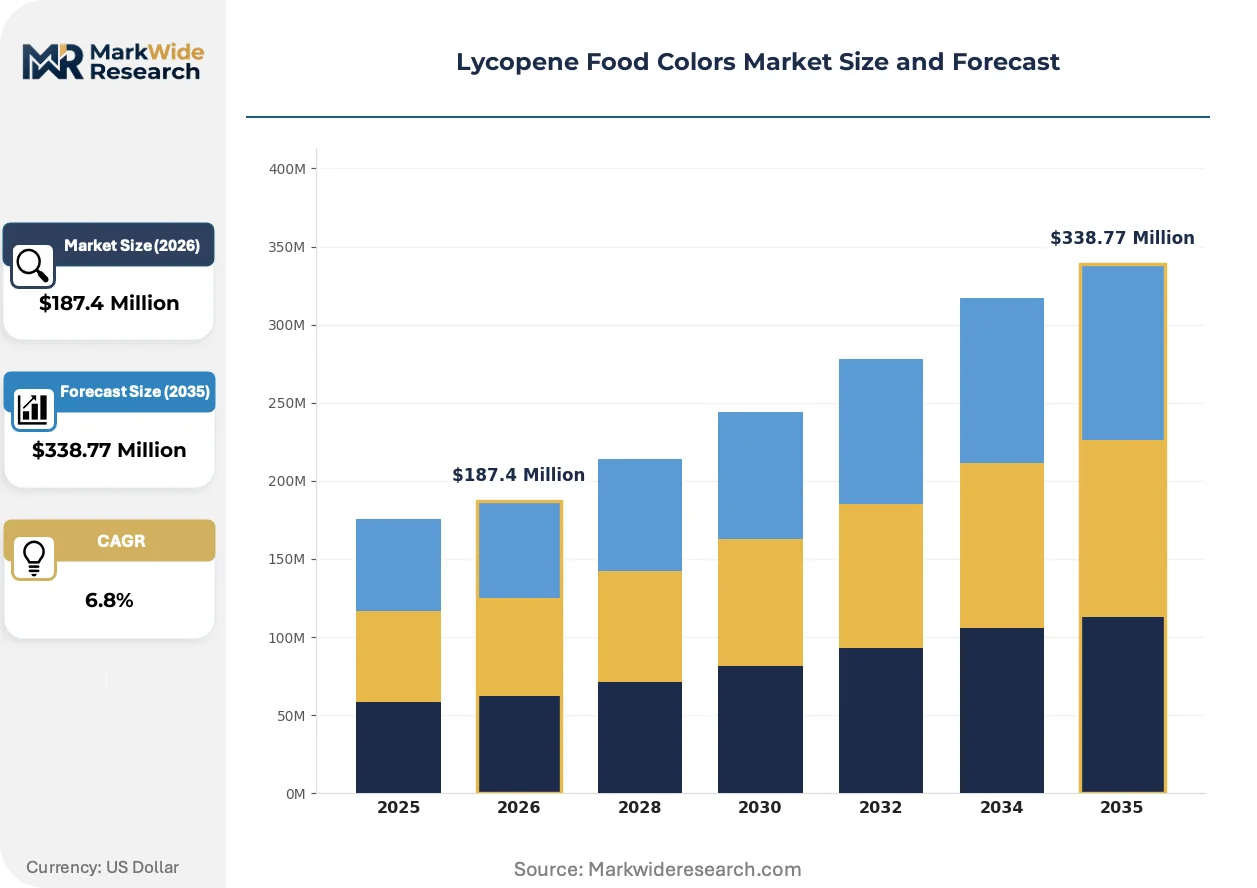
Market Dynamics
Synthetic dye prohibition timelines across major jurisdictions are forcing accelerated reformulation cycles, compressing supplier qualification windows and elevating documentation burdens for natural colorant manufacturers serving beverage and confectionery processors.
Growth Catalysts
- EFSA additive re-evaluations:Tightened acceptable daily intake thresholds for synthetic azo dyes are compelling EU-based food manufacturers to source lycopene alternatives with transparent supply chains and validated safety profiles.
- Fermentation scale-up:Microbial production platforms are expanding lycopene output independent of tomato crop cycles, reducing seasonality constraints that previously limited supply security for large-scale buyers.
- Clean-label dairy processors:German and French yogurt and cheese manufacturers are specifying E160d colorants in procurement tenders to meet retailer demands for simplified ingredient declarations.
Market Restraints
- Tomato paste price volatility:Concentrated extraction feedstock costs fluctuate with agricultural yields in Spain and Italy, compressing margins for solvent-based processors lacking fermentation alternatives.
- Novel Food approval friction:Fermentation-derived lycopene candidates face extended EFSA safety assessment timelines, delaying market entry for synthetic biology suppliers against established extractors.
- Annatto and paprika substitution:Lower-cost natural colorants with comparable orange-red spectra capture share in price-sensitive seasoning and snack applications where thermal stability requirements are less stringent.
Strategic Opportunities
- India FSSAI natural colorant mandates:Proposed restrictions on synthetic dyes in traditional sweets and beverages would open procurement channels for lycopene suppliers with halal and vegetarian certifications.
- Pharmaceutical soft gel encapsulation:Antioxidant-grade lycopene specifications for dietary supplements command premium pricing and longer contract durations than commodity food-grade volumes.
- Direct-to-processor digital platforms:Specialty ingredient marketplaces are bypassing traditional distributor markups, enabling smaller extraction specialists to access mid-size bakery and nutraceutical manufacturers.
Industry Challenges
- FSSC 22000 certification timelines:Smaller fermentation operators face 12-18 month documentation and audit cycles to qualify for supply contracts with multinational food manufacturers.
- Cross-batch color consistency:Natural variation in carotenoid profiles between tomato cultivars and fermentation runs requires advanced spectrophotometric standardization that strains quality control resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lycopene Food Colors Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Extract Application: Beverages, Dairy Products, Confectionery, Snacks End User: Food Manufacturers, Restaurants, Catering Services, Retailers Distribution Channel: Online, Wholesalers, Supermarkets, Specialty Stores |
| Companies Covered | Lycored, DSM-Firmenich, BASF SE, Divi's Laboratories, DDW (Kerry Group), International Flavors & Fragrances, Archer Daniels Midland Company, EID Parry, Wellgreen Technology Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lycopene Food Colors Market Shifts & Advancements
Fermentation-derived production methods and precision extraction technologies are restructuring supply economics, while regulatory displacement of synthetic alternatives accelerates specification changes across formulation laboratories.
Continuous fermentation systems utilizing engineered yeast strains are displacing batch solvent extraction as the dominant production paradigm for food-grade lycopene. Beverage concentrate manufacturers in North America are adopting these supplies to secure year-round availability and reduce agricultural input dependencies. This shift is compressing capital recovery timelines for tomato-processing incumbents while elevating technical barriers for new market entrants lacking bioprocess engineering capabilities.
EFSA's systematic re-evaluation of food additive safety profiles is tightening permissible exposure levels for synthetic colorants across the European Union. Food manufacturers are reformulating product lines ahead of scheduled prohibition dates to avoid supply disruptions and label redesign costs. Confectionery and flavored dairy segments in Germany and France exhibit the most advanced transition timelines, with procurement specifications now excluding azo dyes entirely.
Ingredient co-manufacturing partnerships are replacing arm's-length spot purchasing among mid-size natural food brands. Bakery and plant-based meat startups are embedding lycopene suppliers directly into product development workflows rather than selecting colorants from distributor catalogs. This pattern concentrates most visibly in California and Netherlands innovation clusters, where rapid prototyping cycles demand real-time technical support and customized dispersion systems.
Lycopene Food Colors Market Segmentation
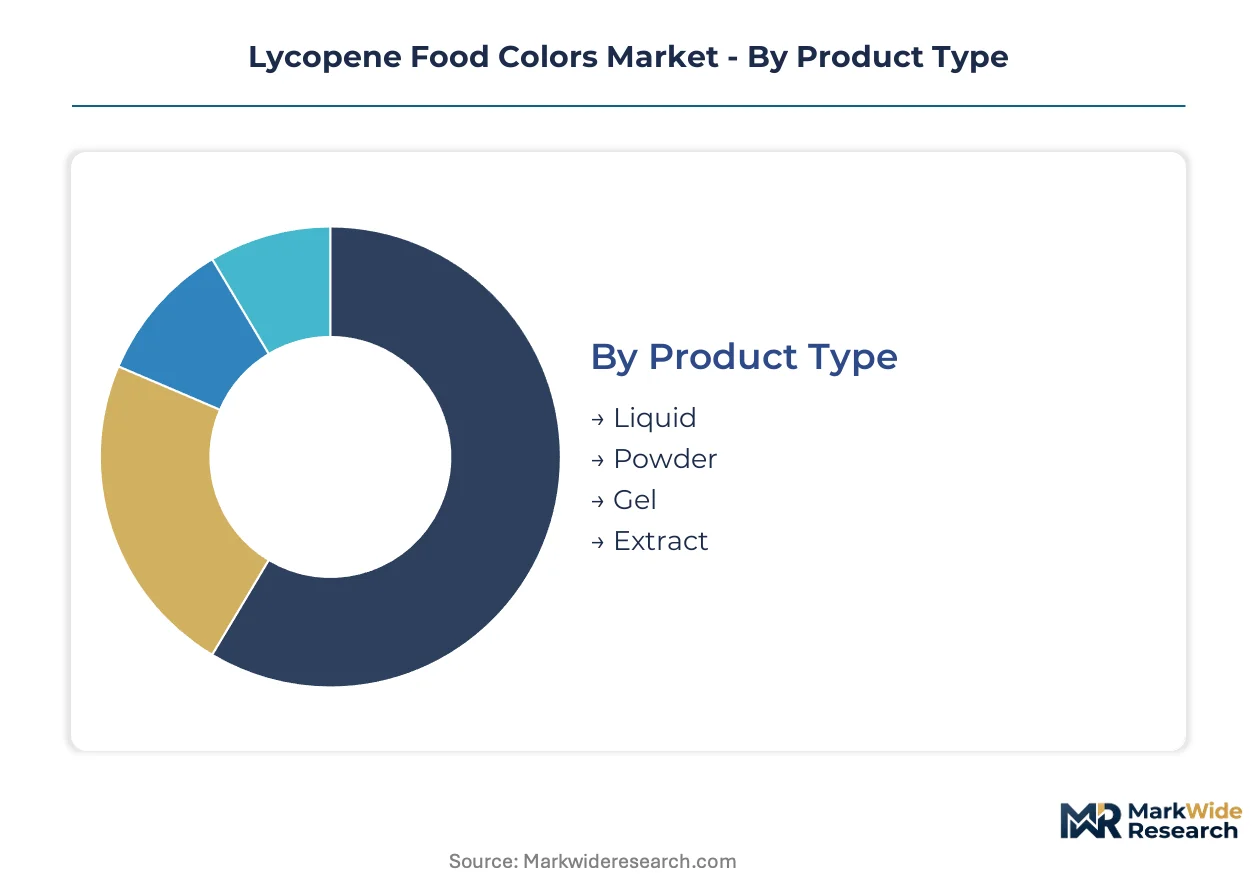
Lycopene food colors flow through highly differentiated channel pathways, with powder and liquid formats commanding distinct logistics networks and customer service requirements. Understanding these segment boundaries reveals where formulation expertise concentrates and where price competition intensifies.
Product Type:
Liquid concentrates move through pump-equipped tanker networks to beverage processors, while powder travels via dry bulk distribution to seasoning houses and bakery premix suppliers.
- Liquid:Pumpable concentrates with standardized color intensity enable metered dosing in high-throughput bottling lines. Beverage manufacturers in Germany and France specify liquid E160d for transparent labeling claims and thermal stability in pasteurized juices.
- Powder:Spray-dried carotenoid matrices with extended shelf stability suit dry-blending operations. Seasoning and bakery premix producers favor powder for inventory flexibility and reduced cold-chain dependency.
- Gel:Semi-solid dispersions with controlled viscosity target artisanal confectionery applications requiring precise visual intensity control.
- Extract:Minimal-process tomato oleoresins command premium positioning in clean-label dairy where processing claims support margin pools.
By volume, powder leads. By growth pace, liquid concentrates are climbing the fastest as beverage reformulation accelerates.
Application:
Cost tiers separate commodity snack coloring from premium dairy and confectionery specifications, with certification requirements widening the spread.
- Beverages:Transparent ingredient declarations drive lycopene adoption in fruit-flavored waters and functional drinks. EFSA additive re-evaluations are compressing synthetic dye timelines across EU bottling operations.
- Dairy Products:Yogurt and cheese manufacturers specify E160d for red-orange fruit preparations and colored rinds. German procurement tenders now exclude azo dyes entirely.
- Confectionery:Hard candy and gummy applications demand heat-stable colorants surviving 140°C cooking temperatures.
- Snacks:Seasoning applications tolerate lower thermal thresholds, exposing lycopene to annatto and paprika substitution in price-sensitive markets.
Dairy commands the highest specification premiums. Beverage applications are gaining share fastest as clean-label mandates spread.
End User:
Volume concentration sits with multinational food manufacturers, while customer type determines technical service intensity and contract structure.
- Food Manufacturers:Large-scale processors negotiate multi-year supply agreements with embedded technical support. FSSC 22000 certification gates entry to their approved supplier lists.
- Restaurants:Limited direct procurement; colorant selection typically delegated to co-manufacturers and ingredient suppliers.
- Catering Services:Minimal direct demand; specifications flow through prepared meal distributors.
- Retailers:Private-label development teams increasingly specify natural colorants for store-brand beverages and dairy.
Food manufacturers dominate volume. Retailer private-label teams are expanding specifications most aggressively.
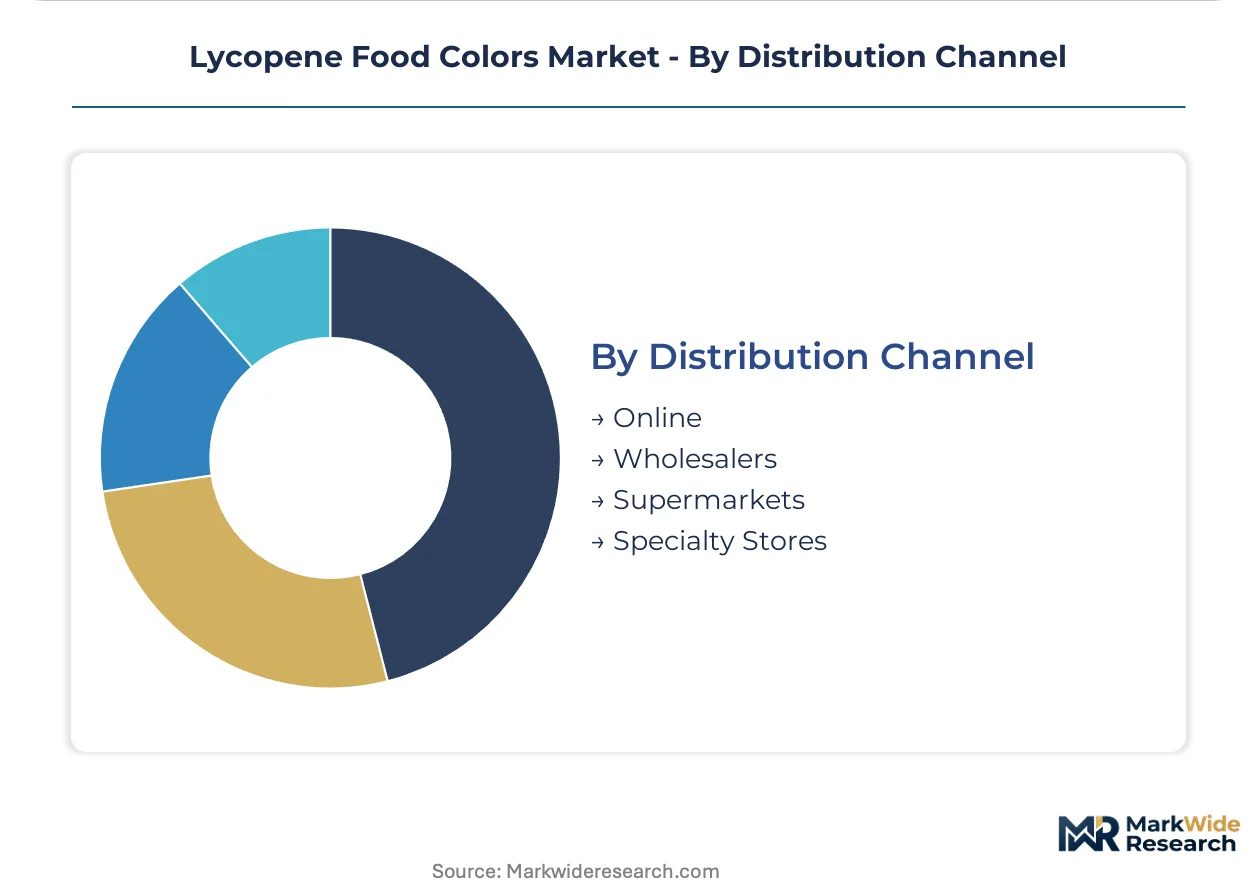
Distribution Channel:
Supply concentration varies sharply by channel, with specialty stores and online platforms fragmenting procurement while wholesalers consolidate large-account relationships.
- Online:Digital marketplaces enable smaller extraction specialists to bypass traditional distributor markups. Mid-size nutraceutical manufacturers source directly through these platforms.
- Wholesalers:Consolidated distributors manage inventory and technical service for multinational food manufacturers. REACH documentation and batch traceability flow through these relationships.
- Supermarkets:Limited direct colorant sales; channel relevance centers on retailer private-label ingredient specifications.
- Specialty Stores:Artisanal and clean-label ingredient suppliers serve boutique confectionery and dairy producers.
Wholesalers handle the largest volume flows. Online channels are expanding access fastest for smaller processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tomato cultivation and fermentation capacity cluster in distinct geographies, with extraction facilities positioning near agricultural feedstocks or biotech hubs. Regulatory displacement of synthetic dyes is compressing procurement timelines unevenly across jurisdictions.
Germany
EFSA additive re-evaluations are compelling dairy and confectionery manufacturers to exclude azo dyes from procurement specifications entirely. The country's federal food safety authority enforces strict Novel Food approval timelines for fermentation-derived candidates. Hamburg and Lower Saxony host concentrated reformulation activity among yogurt processors seeking E160d alternatives.
United States
FDA framework tightening on synthetic color petitions is accelerating beverage reformulation toward natural alternatives. California's Proposition 65 litigation exposure has pushed West Coast manufacturers toward transparent ingredient declarations. Los Angeles and San Francisco innovation clusters embed lycopene suppliers directly into plant-based meat and functional drink development workflows.
China
SAMR food additive standards are elevating documentation requirements for imported natural colorants while domestic fermentation capacity expands. The country's dual carbon goals incentivize microbial production platforms over solvent-intensive extraction. Yangtze River Delta biotech corridors concentrate pilot-scale lycopene fermentation operations serving regional seasoning manufacturers.
India
FSSAI proposed restrictions on synthetic dyes in traditional sweets would open procurement channels for suppliers with halal and vegetarian certifications. The regulator's draft notification timeline is compressing supplier qualification windows for Diwali and Holi production cycles. Maharashtra and Gujarat processing hubs are negotiating directly with extraction specialists to secure colorant pipelines ahead of mandate implementation.
France
ANSM food safety alerts on azo dye hypersensitivity reactions are reinforcing retailer pressure for clean-label dairy formulations. EFSA acceptable daily intake thresholds shape formulation ceilings for flavored yogurt and cheese rind applications. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate procurement specification changes among private-label development teams.
Lycopene Food Colors Market Competitive Landscape
Concentration sits with vertically integrated extraction specialists and fermentation-scale operators commanding distinct cost structures. The competitive map splits between tomato-cultivation-backed processors and synthetic biology platforms. Three archetypes dominate: agricultural-integrated extractors, microbial production specialists, and diversified ingredient conglomerates. Capacity expansion and backward integration into captive feedstock supply represent the dominant competitive vectors.
Among agricultural-integrated operators, Lycored exemplifies vertical control from cultivation through extraction. Fermentation-scale specialists include Divi's Laboratories, occupying a position within Asia-Pacific pharmaceutical and food-grade supply. Diversified ingredient conglomerates are represented by DSM-Firmenich and BASF SE, sitting within portfolios spanning multiple natural colorant categories. These anchors illustrate how competitive positioning stratifies across feedstock security, bioprocess engineering capability, and regulatory navigation bandwidth.
| Leading Market Players |
|---|
| Lycored |
| DSM-Firmenich |
| BASF SE |
| Divi's Laboratories |
| DDW (Kerry Group) |
| International Flavors & Fragrances |
| Archer Daniels Midland Company |
| EID Parry |
| Wellgreen Technology Co Ltd |
| Others |
Supply & Pricing Matrix
Ninety-day fermentation batch cycles from microbial platforms compress supplier pricing power against tomato-extraction incumbents, while EFSA Novel Food approval timelines extend inventory carrying costs for synthetic biology entrants. This lead-time asymmetry between production methods concentrates margin capture with vertically integrated extractors in Spain and Italy, forcing fermentation specialists to absorb certification burdens or cede share in commodity food-grade tenders.
Pricing Analysis
EFSA additive re-evaluations dictate the pricing tier structure across European procurement channels, separating pharmaceutical-grade specifications from commodity food-grade volumes. Three-tier pricing structure across premium, standard, and economy levels reflects FSSC 22000 certification status, tomato oleoresin concentration, and fermentation-derived purity grades. Cost compression in standard-grade powder runs through annatto substitution pressure from Southeast Asian seasoning houses. Beverage processors in Germany exhibit lowest price sensitivity due to reformulation mandate urgency, while Indian snack manufacturers anchor economy-tier demand.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes European importers to concentrated feedstock flows from Chinese fermentation hubs and Indian extraction facilities. Raw material dependencies center on engineered yeast strains, tomato paste from Spanish and Italian processors, and solvent recovery systems. Single-source vulnerability concentrates in microbial strain IP controlled by three biotech platforms. Distribution runs through REACH-compliant wholesalers managing batch traceability for multinational food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
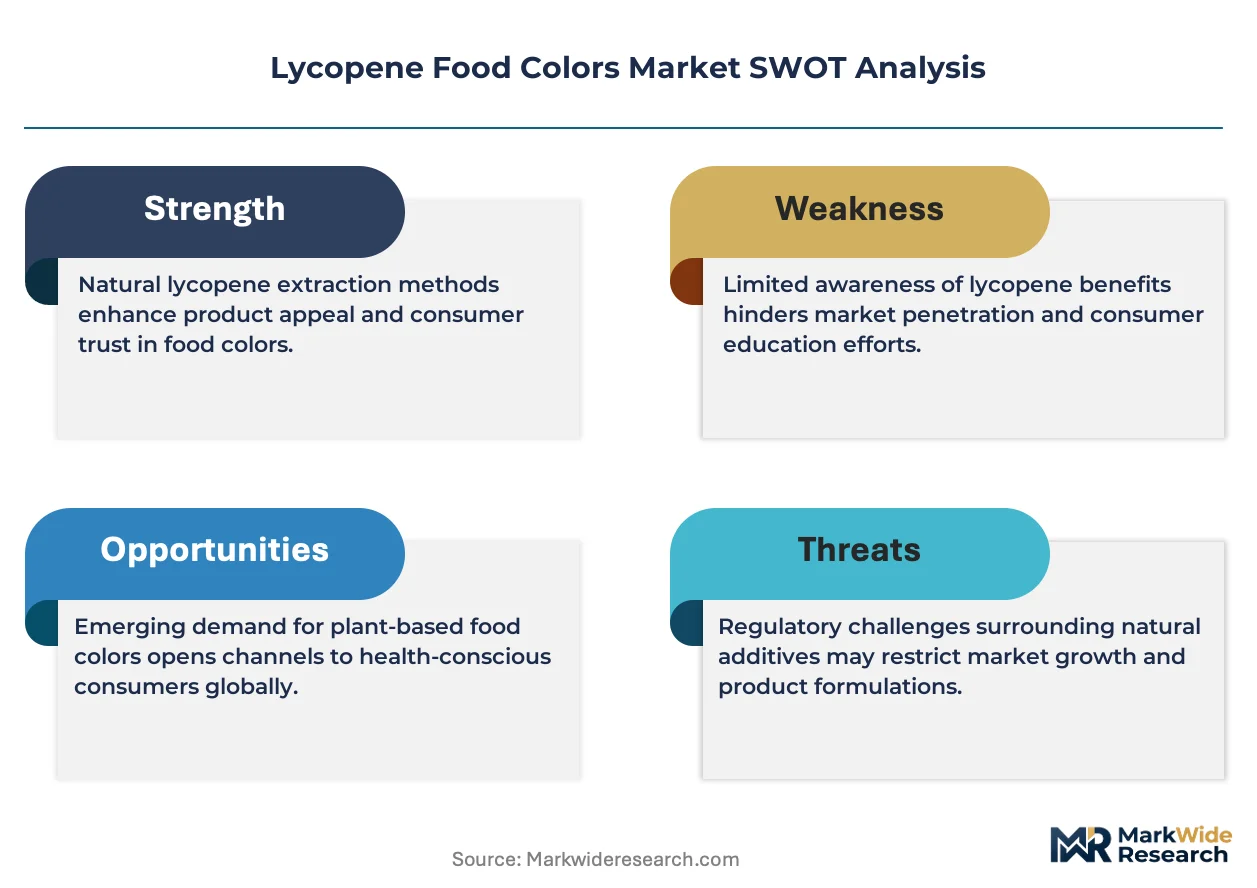
Annatto and paprika substitution threats demand defensive positioning from lycopene incumbents, as price-sensitive applications in snacks and seasonings tolerate spectral trade-offs for cost advantage.
For Market Incumbents: Fortify captive tomato supply agreements in Italy and Spain to offset fermentation scale-up threats from synthetic biology entrants. Secure FSSC 22000 certification extensions ahead of EFSA Novel Food approval waves to maintain supplier list eligibility with German dairy processors. Prioritize pharmaceutical-grade capacity additions that command contract durations exceeding commodity food-grade cycles. For New Entrants and Emerging Players: Lead with halal-certified fermentation output targeting India's FSSAI mandate implementation for traditional sweets and beverages. Capture share in online direct-to-processor platforms serving mid-size nutraceutical manufacturers lacking distributor relationships. Embed technical service capabilities into California plant-based meat innovation clusters where rapid prototyping cycles demand real-time dispersion system customization. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory displacement play because synthetic dye prohibition timelines across FDA and EFSA jurisdictions create structural demand migration with limited reversal pathways. Target acquisition profiles emphasizing fermentation bioprocess engineering capabilities over commodity extraction assets. Monitor EFSA acceptable daily intake threshold revisions as the critical signal for acceleration or deceleration in European reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Engineered yeast platforms reduce agricultural yield dependency for beverage processors in Germany. |
| Backward Integration into Tomato Cultivation | Captive Spanish and Italian feedstock supply secures margin capture against microbial competitors. |
| FSSC 22000 Certification Investment | Audit documentation gates entry to multinational food manufacturer approved supplier lists. |
| Pharmaceutical-Grade Specification Development | Antioxidant-grade lycopene commands premium pricing and extended contract durations. |
| Direct-to-Processor Digital Platform Launch | Specialty ingredient marketplaces bypass distributor markups for mid-size bakery manufacturers. |
Research Methodology
A standing panel of food colorant procurement managers, fermentation process engineers, regulatory affairs specialists at EFSA-notified bodies, and clean-label brand managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA additive re-evaluation reports, FDA color additive petitions, FSSC 22000 certification databases, and customs trade data for E160d classifications. Bottom-up volume estimates from extraction facility capacities and top-down demand segmentation from beverage and dairy processor specifications were triangulated for consistency.
Forecast outputs were validated against external benchmarks including EFSA prohibition timeline announcements and fermentation scale-up disclosures from biotech platforms. The analytical framework spans product type, application segment, end-user category, and distribution channel dimensions across the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier concentration, with fermentation yield improvements and tomato paste cost volatility as primary sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside EFSA Novel Food approval timelines or FSSAI mandate implementation schedules would require recalibration. Practitioners should keep alternative scenarios live as synthetic dye prohibition enforcement intensity and microbial production cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Australia Food Additives Market