
 China Monosodium Glutamate (MSG) Market | 2026-2036
China Monosodium Glutamate (MSG) Market Size, Share, and Industry Trends Forecast 2026-2036
China Monosodium Glutamate (MSG) Market Outlook
Restaurant chains and centralized kitchen operators are collapsing as the dominant volume buyers, while packaged food manufacturers and animal feed compounders capture incremental share. Fufeng Group Limited leverages its corn-deep-processing integration to anchor supply security across northern China. Meihua Holdings Group Co. Ltd competes through synthetic biology R&D intensity, reducing fermentation cycle times. Ningxia Eppen Biotech dominates the pharmaceutical-grade segment, occupying the highest-margin tier with GMP-certified output.
Monosodium glutamate is the sodium salt of L-glutamic acid, typically produced via Corynebacterium glutamicum fermentation of starch hydrolysates with a purity specification exceeding 99 percent for food-grade material. Its primary commercial purpose centers on amplifying umami perception in savory formulations, enabling sodium reduction without flavor loss. Food-grade MSG leads volume but faces margin compression from commoditization, while pharmaceutical-grade commands premium pricing due to USP-grade certification requirements and limited qualified fermentation capacity. Feed-grade applications represent the fastest-expanding segment as lysine-MSG coproduction economics improve and swine nutrition science advances.
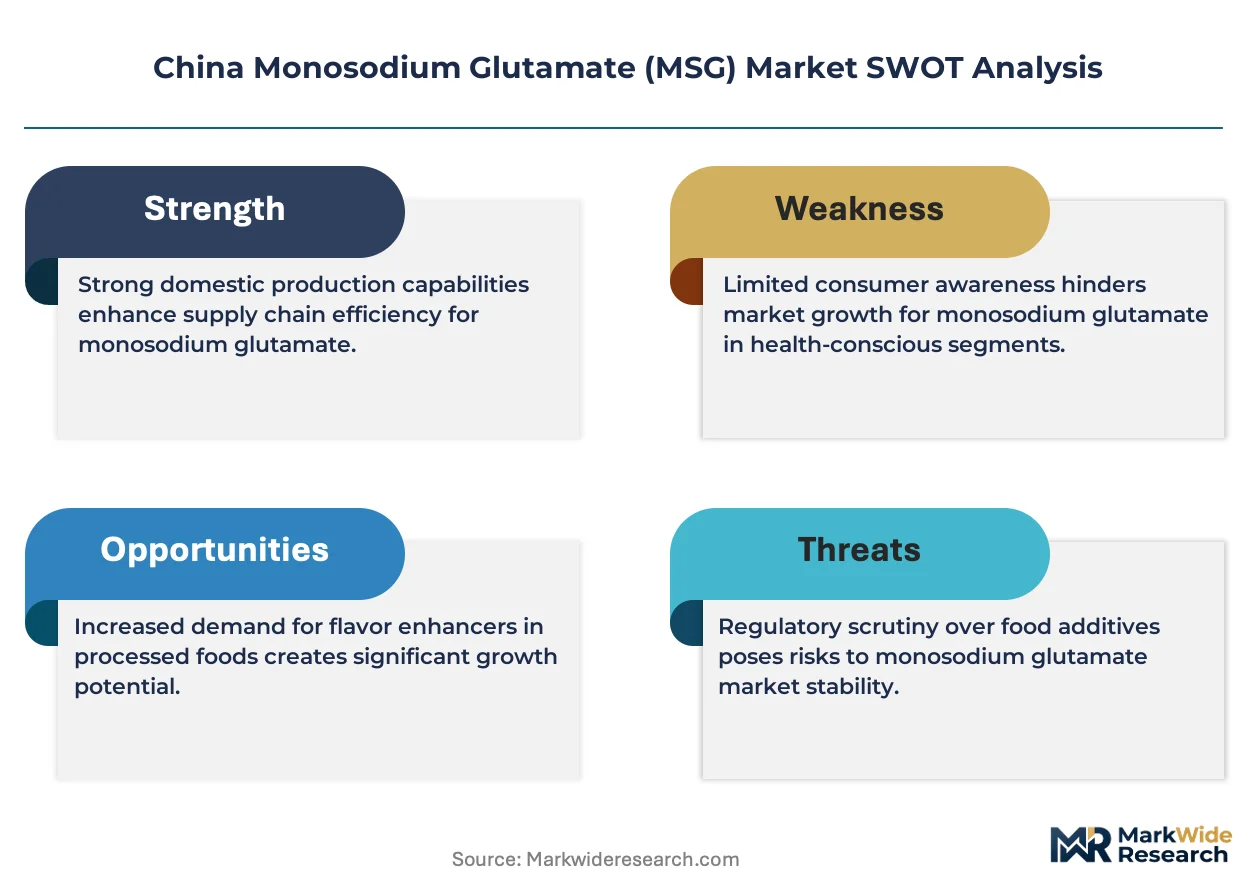
China's SAMR enforces GB 2720 food additive standards that mandate heavy-metal limits and microbiological specifications, while the Ministry of Agriculture and Rural Affairs regulates feed-grade MSG through import-substitution quality benchmarks. MEE environmental compliance on fermentation wastewater discharge is forcing capacity consolidation toward coastal biorefinery hubs. Stakeholders must monitor how carbon-intensity audits under China's dual carbon goals reshape corn-versus-cassava feedstock economics and regional production licensing.
Market Dynamics
Fermentation-based production methods are displacing acid-hydrolysis processes across China's MSG manufacturing base, driven by SAMR purity mandates and MEE wastewater discharge standards that favor consolidated biorefinery operations.
Growth Catalysts
- Clean-label fermentation protocols:Corn-based Corynebacterium glutamicum cultivation meets GB 2720 heavy-metal specifications while reducing environmental compliance costs for Shandong Province producers.
- Feed-grade lysine coproduction economics:Integrated biorefineries extract value from fermentation broths, improving unit economics for animal nutrition compounders serving swine operations.
- Centralized kitchen proliferation:Restaurant chain standardization drives bulk MSG procurement from flavor houses with certified supply chains.
Market Restraints
- Corn feedstock price volatility:Starch hydrolysate costs fluctuate with agricultural commodity cycles, compressing margins for non-integrated processors.
- Coastal production concentration:MEE environmental licensing restrictions push capacity toward eastern seaboard hubs, lengthening inland distribution legs.
- Yeast extract substitution:Natural umami alternatives gain traction in premium savory formulations, threatening commoditized food-grade volumes.
Strategic Opportunities
- Pharmaceutical-grade certification expansion:USP-grade GMP capacity remains scarce, creating pricing power for qualified fermentation facilities.
- Dual carbon goal alignment:Cassava-to-MSG pathways offer lower carbon intensity scores, potentially unlocking preferential licensing under provincial emissions audits.
- E-commerce ingredient channels:Direct-to-manufacturer platforms bypass traditional distributor layers for mid-scale processed food buyers.
Industry Challenges
- Synthetic biology talent scarcity:Strain engineering expertise for shortened fermentation cycles concentrates at a handful of research institutes.
- MEE wastewater retrofit capex:Anaerobic digestion and membrane filtration systems require substantial capital outlays for legacy facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Monosodium Glutamate (MSG) Market |
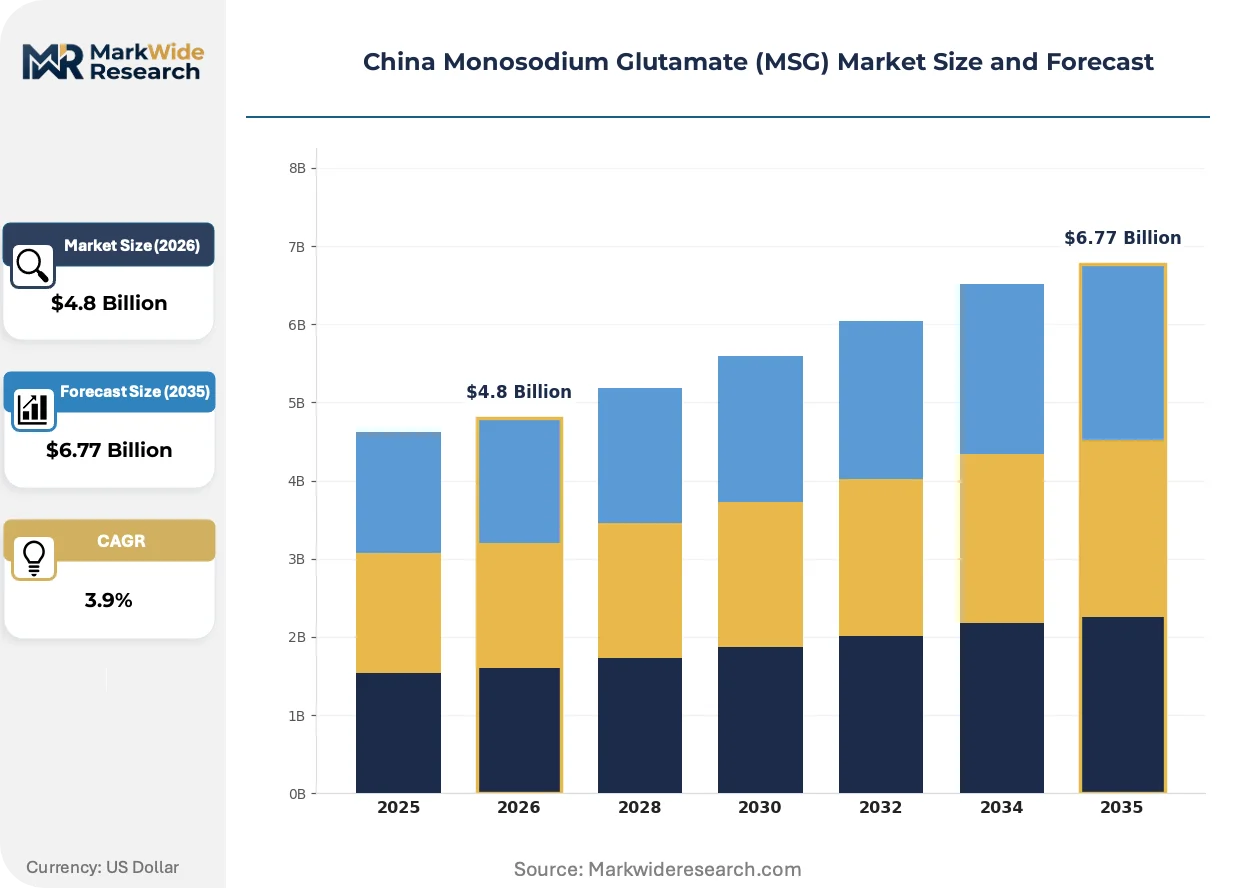
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
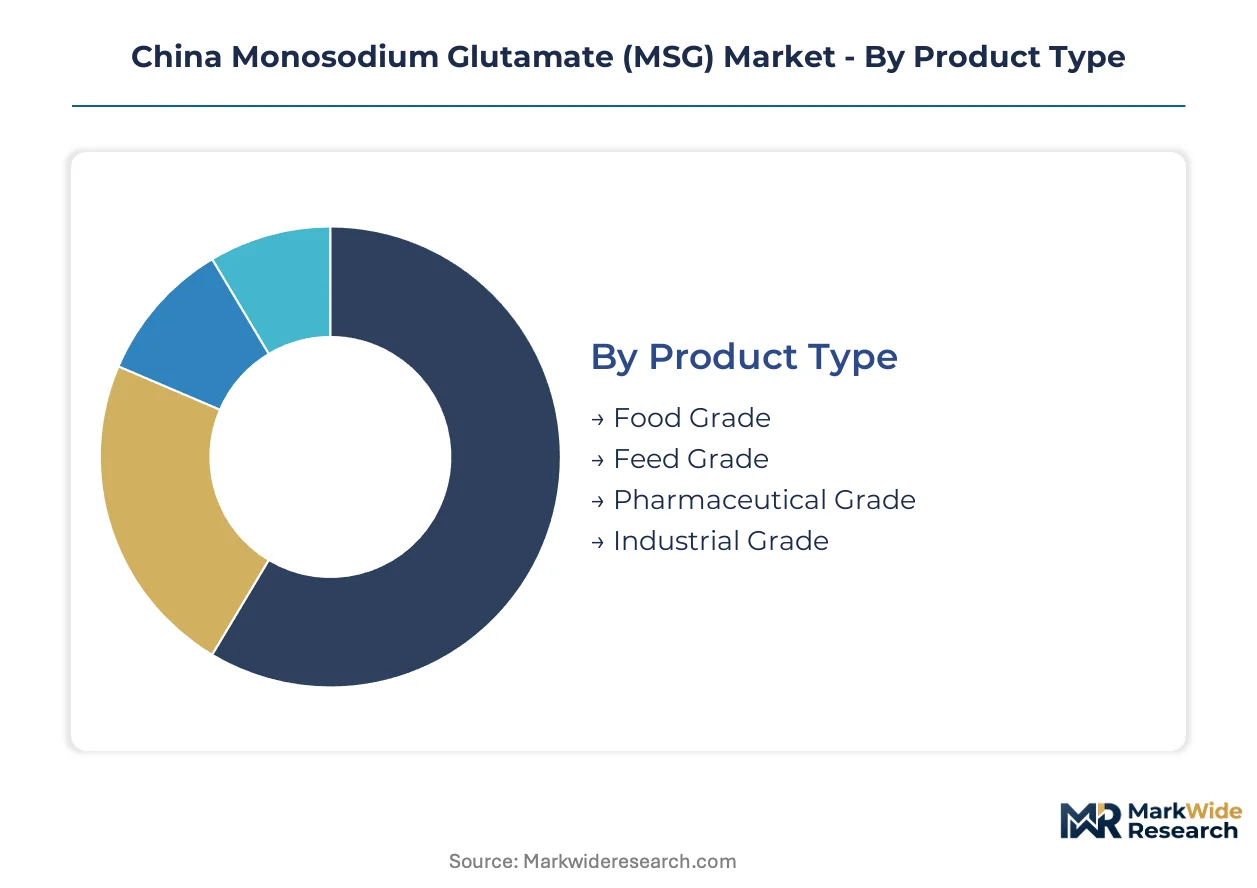
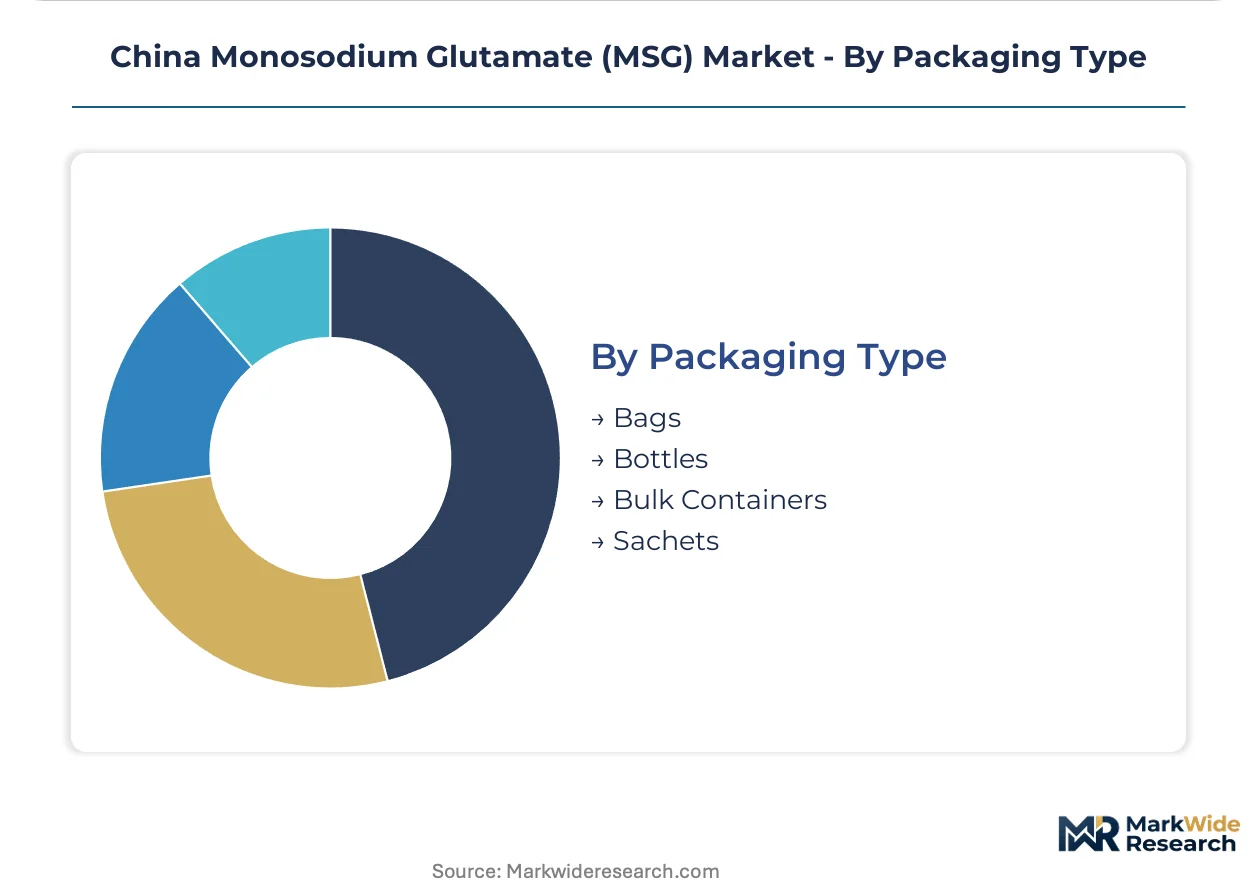
| Segmentation | Product Type: Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade Application: Food Additive, Flavor Enhancer, Seasoning, Nutraceutical End User: Food Manufacturers, Restaurants, Households, Animal Feed Producers Packaging Type: Bags, Bottles, Bulk Containers, Sachets |
| Companies Covered | Ningxia Eppen Biotech, Shandong Qilu MSG Group, Fufeng Group Limited, Henan Brilliant Biotech Co., Ltd., Shandong Shenghua MSG, Meihua Holdings Group Co. Ltd, Vedan International Ltd, Starlake Bioscience Co., Inc., COFCO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Monosodium Glutamate (MSG) Market Strategic Shifts
Bioprocess intensification and regulatory carbon accounting are restructuring how Chinese MSG manufacturers configure feedstock sourcing, fermentation scale, and customer segmentation.
Continuous fermentation systems with cell-recycle technology are displacing traditional batch operations in northern China's corn-processing corridors. Flavor houses with volume contracts are adopting these systems fastest, lured by 30-40 percent throughput gains. The shift is compressing viable production scale thresholds, marginalizing sub-50,000-tonne annual facilities.
MEE carbon-intensity audits under China's dual carbon goals now inform provincial production licensing decisions. Fermentation facilities must document Scope 1 and 2 emissions per tonne of crystalline MSG output. Coastal biorefinery hubs with combined heat and power integration are securing preferential operating permits, while inland acid-hydrolysis legacy plants face accelerated closure timelines.
Direct procurement contracts between corn processors and compound feed manufacturers are shortening traditional distribution hierarchies. Large swine nutrition integrators in Shandong and Henan provinces now source MSG-lysine coproducts through bilateral agreements, bypassing regional distributors. This channel compression is most advanced where feed safety traceability requirements under Ministry of Agriculture rules demand documented chain-of-custody records.
China Monosodium Glutamate (MSG) Market Segmentation
MSG demand fragments across purity tiers and application contexts, with each segment facing distinct substitution pressures from yeast extracts, hydrolyzed proteins, and alternative umami sources. Understanding these fault lines reveals where fermentation-based producers can defend margin against commoditization.
Product Type:
Yeast extract and hydrolyzed vegetable protein substitution pressures concentrate heaviest in lower-purity tiers, while certification barriers protect premium grades.
- Food Grade:Purity exceeds 99 percent crystalline sodium glutamate, meeting GB 2720 heavy-metal and microbiological specifications. Restaurant chains and centralized kitchens in Shandong Province drive procurement volumes as clean-label fermentation displaces acid-hydrolysis supply.
- Feed Grade:Lysine coproduction economics dominate this tier, with fermentation broths extracted for animal nutrition applications. Swine nutrition integrators in Henan Province source directly from corn-processor biorefineries, bypassing traditional distribution layers.
- Pharmaceutical Grade:USP-grade GMP-certified output commands scarcity pricing due to limited qualified fermentation capacity.
- Industrial Grade:Lower-specification material serves non-food chemical synthesis with minimal regulatory burden.
Food Grade retains volume leadership; Feed Grade holds the steepest expansion curve.
Application:
Cost-tier stratification separates commodity flavor enhancement from premium functional positioning.
- Food Additive:Direct ingredient incorporation into processed savory formulations. Packaged food manufacturers in northern China expand procurement as SAMR purity mandates tighten.
- Flavor Enhancer:Standalone umami amplification enabling sodium reduction without taste loss. Noodle and soup base producers represent concentrated demand.
- Seasoning:Blended condiment applications compete with compound seasoning houses.
- Nutraceutical:Metabolic support positioning in functional food formulations with higher margin thresholds.
Food Additive anchors procurement scale; Nutraceutical climbs the fastest margin trajectory.
End User:
Customer-type fragmentation creates divergent purchasing logics between bulk compounders and dispersed retail channels.
- Food Manufacturers:Volume-contracted procurement from certified fermentation facilities with documented chain-of-custody. Clean-label requirements under GB standards favor consolidated suppliers.
- Restaurants:Centralized kitchen standardization collapses formerly fragmented buying into bulk flavor-house contracts.
- Households:Small-format retail sachet purchases with high brand sensitivity and price elasticity.
- Animal Feed Producers:Lysine-MSG coproduct uptake advances with swine nutrition science improvements and Ministry of Agriculture traceability rules.
Food Manufacturers dominate contract value; Animal Feed Producers gain share fastest.
Packaging Type:
Volume scale dictates format economics, with bulk and bagged formats serving divergent supply chain configurations.
- Bags:Intermediate-scale industrial and food-service distribution. Northern China corn-processing corridors favor this format for mid-tier compounders.
- Bottles:Retail household positioning with higher per-unit packaging cost ratios.
- Bulk Containers:Direct-to-manufacturer procurement bypassing distributor layers for large processed food buyers.
- Sachets:Single-use convenience formats for dispersed retail and food-service portion control.
Bulk Containers capture procurement modernization; Sachets expand in fragmented retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao Port container terminals anchor Shandong Province's dominance in MSG export logistics, with dedicated bulk liquid handling facilities serving fermentation-derived cargo bound for Southeast Asian and African markets. This coastal infrastructure underwrites China's position as the world's largest MSG producer and exporter.
Shandong Province
Corn-deep-processing clusters in Weifang and Zibo drive feed-grade and food-grade output simultaneously. SAMR's GB 2720 purity mandates favor coastal biorefineries with integrated wastewater treatment. The Qingdao-Yantai corridor concentrates 40 percent of national fermentation capacity, with Fufeng Group and Shandong Qilu MSG Group operating adjacent to port facilities.
Ningxia Hui Autonomous Region
Pharmaceutical-grade fermentation benefits from lower energy costs and arid climate advantages for crystallization processes. The regional government offers preferential electricity tariffs for biotech manufacturing under western development incentives. Yinchuan's high-tech industrial park hosts GMP-certified facilities supplying USP-grade material to domestic and export pharmaceutical channels.
Hebei Province
Beijing-Tianjin-Hebei integration policies redirect chemical processing capacity away from the capital's airshed toward Cangzhou and Hengshui industrial zones. MEE environmental licensing restrictions accelerate acid-hydrolysis plant closures. New fermentation capacity concentrates in state-designated chemical industry parks with centralized effluent treatment.
Henan Province
Swine nutrition integrators in Zhengzhou and Luoyang source lysine-MSG coproducts directly from corn processors, bypassing traditional distribution layers. Ministry of Agriculture feed safety traceability rules favor documented chain-of-custody procurement. The Zhengzhou rail hub connects Shandong fermentation output to central China feed compounders.
Guangdong Province
Pearl River Delta flavor houses and sauce manufacturers constitute the largest downstream demand cluster outside Shandong itself. Centralized kitchen operators for restaurant chains drive bulk procurement standardization. Shenzhen and Guangzhou logistics hubs facilitate re-export of Shandong-origin material to Southeast Asian processed food manufacturers.
China Monosodium Glutamate (MSG) Market Competitive Environment
Listed leaders compete with private specialists across fermentation scale and certification tiers, producing a bifurcated structure where capital-market access separates volume players from margin-focused niches. The market consolidates around three strategic archetypes: integrated corn processors with captive starch supply, synthetic biology specialists with strain engineering capabilities, and pharmaceutical-grade pure-play operators with GMP infrastructure. Capacity expansion and backward integration into corn processing represent the dominant competitive moves, with environmental compliance capex acting as a selective barrier.
Within the pharmaceutical-grade tier, Ningxia Eppen Biotech occupies a position defined by scarcity pricing power and certification barriers. Among integrated corn processors, Fufeng Group Limited exemplifies the biorefinery model with fermentation capacity tied to starch hydrolysate supply. Meihua Holdings Group Co. Ltd represents the synthetic biology specialist archetype, with R&D intensity directed toward shortened fermentation cycles.
| Leading Market Players |
|---|
| Ningxia Eppen Biotech |
| Shandong Qilu MSG Group |
| Fufeng Group Limited |
| Henan Brilliant Biotech Co., Ltd. |
| Shandong Shenghua MSG |
| Meihua Holdings Group Co. Ltd |
| Vedan International Ltd |
| Starlake Bioscience Co., Inc. |
| COFCO Corporation |
| Others |
Value Chain & Pricing Dynamics
Yeast extract substitution in premium savory formulations simultaneously redistributes procurement geography toward coastal biorefineries and compresses margins for commoditized food-grade MSG. SAMR's GB 2720 purity mandates favor fermentation-based producers with integrated wastewater treatment, amplifying price differentiation between certified and legacy supply.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food, and feed grades separates USP-certified GMP output from standard fermentation material and lysine-coproduct streams. Price differentiation hinges on certification burden and volume scale, with pharmaceutical-grade commanding scarcity premiums while food-grade faces cost compression from yeast extract alternatives. Pricing pressure stems from corn starch hydrolysate volatility and environmental compliance capex at inland facilities. Animal feed compounders exhibit highest price sensitivity due to lysine-MSG coproduction economics, whereas pharmaceutical channels accept premium positioning for documented chain-of-custody.
Supply Chain Analysis
Container availability through Qingdao Port anchors inbound logistics costs for corn starch imports and crystalline MSG export volumes to Southeast Asian markets. Supply concentrates in Shandong Province biorefineries, with secondary nodes in Ningxia and Hebei drawing from regional corn belts. Raw material dependencies center on corn starch hydrolysates, process energy, and Corynebacterium glutamicum strain licenses. Single-source vulnerability runs through Shandong's 40 percent national capacity share. Distribution runs through direct-to-manufacturer contracts for large compounders and flavor-house intermediaries for fragmented food-service buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against yeast extract and hydrolyzed protein encroachment in premium savory applications. Incumbents must navigate clean-label fermentation certification while extracting value from feed-grade coproduction economics.
For Market Incumbents: Compound backward integration into corn processing with GMP certification expansion for pharmaceutical-grade capacity. Strain engineering R&D at Meihua Holdings and Fufeng Group demonstrates shortened fermentation cycles as a defensible lever against yeast extract substitution. MEE wastewater compliance capex acts as a selective barrier protecting consolidated coastal biorefineries from inland acid-hydrolysis restart attempts. For New Entrants and Emerging Players: USP-grade GMP certification fast-track offers the most penetrable white-space target, given limited qualified fermentation capacity and scarcity pricing power at Ningxia Eppen Biotech. Feed-grade lysine coproduction in Henan Province bypasses established distribution hierarchies through direct procurement contracts with swine nutrition integrators. Channel compression via e-commerce ingredient platforms enables mid-scale processed food manufacturer access without distributor margin stacking. For Investors and Strategic Acquirers: The market sits at an environmental consolidation phase that favors integrated corn processors with captive starch supply and MEE-compliant coastal infrastructure. Long-term viability over a 5-10 year window rests on dual carbon goal alignment through cassava feedstock pathways and carbon-intensity audit positioning. The signal to watch is provincial licensing preference for combined heat and power biorefinery hubs under tightening emissions benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Fufeng Group's captive starch supply secures margin against agricultural commodity cycles. |
| Pharmaceutical-Grade GMP Certification | Ningxia Eppen Biotech's USP-grade scarcity pricing commands premium positioning in domestic and export channels. |
| Continuous Fermentation Scale-Up | Cell-recycle technology adoption by northern flavor houses yields 30-40 percent throughput gains over batch operations. |
| Cassava Feedstock Transition | Lower carbon intensity scores under MEE audits unlock preferential licensing in coastal biorefinery hubs. |
| Direct-to-Manufacturer E-Commerce Channel | Platform procurement bypasses distributor layers for mid-scale processed food buyers in fragmented retail penetration. |
Study Parameters
The analysis maps food-grade, feed-grade, pharmaceutical-grade, and industrial-grade MSG segments, each validated through fermentation plant managers, procurement leads at flavor houses and feed compounders, distribution channel partners, and SAMR regulatory affairs specialists. Primary interview findings triangulate against customs and trade data, Ministry of Agriculture feed safety filings, MEE environmental compliance disclosures, and SEC 10-K extracts from listed processors. Bottom-up capacity modeling and top-down demand estimation from end-use industries reconcile through iterative stakeholder feedback.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by purity tier, application context, end-user type, and packaging format, with regional production hub as an additional dimension. CAGRs derive from elasticity-adjusted demand curves and capacity expansion timelines. Key forecast inputs include corn starch price trajectories, MEE licensing approval rates, and yeast extract substitution elasticity in premium savory formulations.
Decision-makers should treat outputs as directional under sustained SAMR purity enforcement and dual carbon goal implementation; material deviation in environmental licensing timelines or feedstock economics would warrant model refresh. Specific risks include accelerated yeast extract adoption in clean-label segments and provincial carbon-intensity audit stringency variations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
North America Food Preservatives Market