
 Ellagic Acid Market | 2026-2036
Ellagic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Ellagic Acid Market Foresight
Multi-source extraction from pomegranate peel and oak bark is pivoting toward vertically integrated berry processors. Aktin Chemicals leverages captive walnut shell supply chains to secure raw material consistency. Sabinsa Corporation anchors its position through sustained investment in standardized polyphenol extraction protocols. Chengdu Biopurify Phytochemicals competes on geographic proximity to Asian botanical sourcing corridors.
Ellagic acid is a polyphenol compound, C14H6O8, extracted primarily from ellagitannin-rich plant matrices through hydrolysis and solvent purification; it functions as a potent antioxidant and anti-inflammatory agent in therapeutic and cosmetic formulations. Powder formulations dominate pharmaceutical compounding due to superior stability and dosing precision, while liquid extracts are gaining traction in functional beverage applications where rapid dispersion matters. Dietary supplements occupy the deepest margin pools as branded finished goods command premium positioning over bulk ingredient sales.
FDA dietary supplement cGMP standards and EFSA novel food evaluations shape product entry pathways on both sides of the Atlantic, with REACH chemical registration adding compliance layers for European cosmetic ingredient suppliers. China's NMPA and GB standards for natural extracts are tightening import specifications, redirecting some supply toward domestic certification investments. Stakeholders must monitor evolving pharmacopeial monographs and decide whether to pursue pharmaceutical-grade qualification or remain in nutraceutical-grade bulk supply.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing supplier margins while concentrating procurement among vertically integrated botanical processors capable of certifying hydrolysis consistency from raw tannin to finished isolate.
Growth Catalysts
- Antioxidant therapy expansion:Formulators in Germany and the United States are scaling high-purity ellagic acid procurement for inflammatory disease protocols, tightening supplier qualification standards.
- REACH compliance premium:ECHA registration mandates for cosmetic-grade polyphenols are filtering out uncertified European suppliers, consolidating volume among REACH-registered extractors.
- Green solvent extraction:Supercritical CO2 hydrolysis methods are displacing hexane-based processes, reducing residual solvent risk for dietary supplement manufacturers.
Market Restraints
- Pomegranate peel supply volatility:Seasonal harvest fluctuations in India and Iran concentrate raw material risk among processors lacking multi-botanical sourcing.
- Pharmaceutical-grade capex barrier:USP-NF monograph compliance requires seven-figure investment in chromatographic purification capacity, excluding mid-scale entrants.
- Gallic acid substitution:Lower-cost hydrolyzable tannins from grape seed extractors are capturing price-sensitive nutraceutical contracts in functional beverage applications.
Strategic Opportunities
- Cosmeceutical dermal delivery:Liposomal encapsulation technology convergence with nano-emulsion formulation is opening photodamage repair segments previously closed to polyphenol instability.
- FSSAI novel food clearance:India's 2024 streamlined botanical extract approval pathway enables direct entry into ayurvedic pharmaceutical compounding without EU mutual recognition dependency.
- Direct-to-brand e-procurement:B2B ingredient marketplaces are disintermediating traditional distributor networks for mid-volume nutraceutical contract manufacturers.
Industry Challenges
- Pharmacopeial monograph lag:Delayed USP-NF and EP updates for ellagic acid assay methodology create batch release uncertainty for pharmaceutical qualification pursuits.
- Ellagitannin characterization expertise:Scarce analytical chemists capable of validating hydrolysis completion ratios command premium compensation, constraining quality team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ellagic Acid Market |
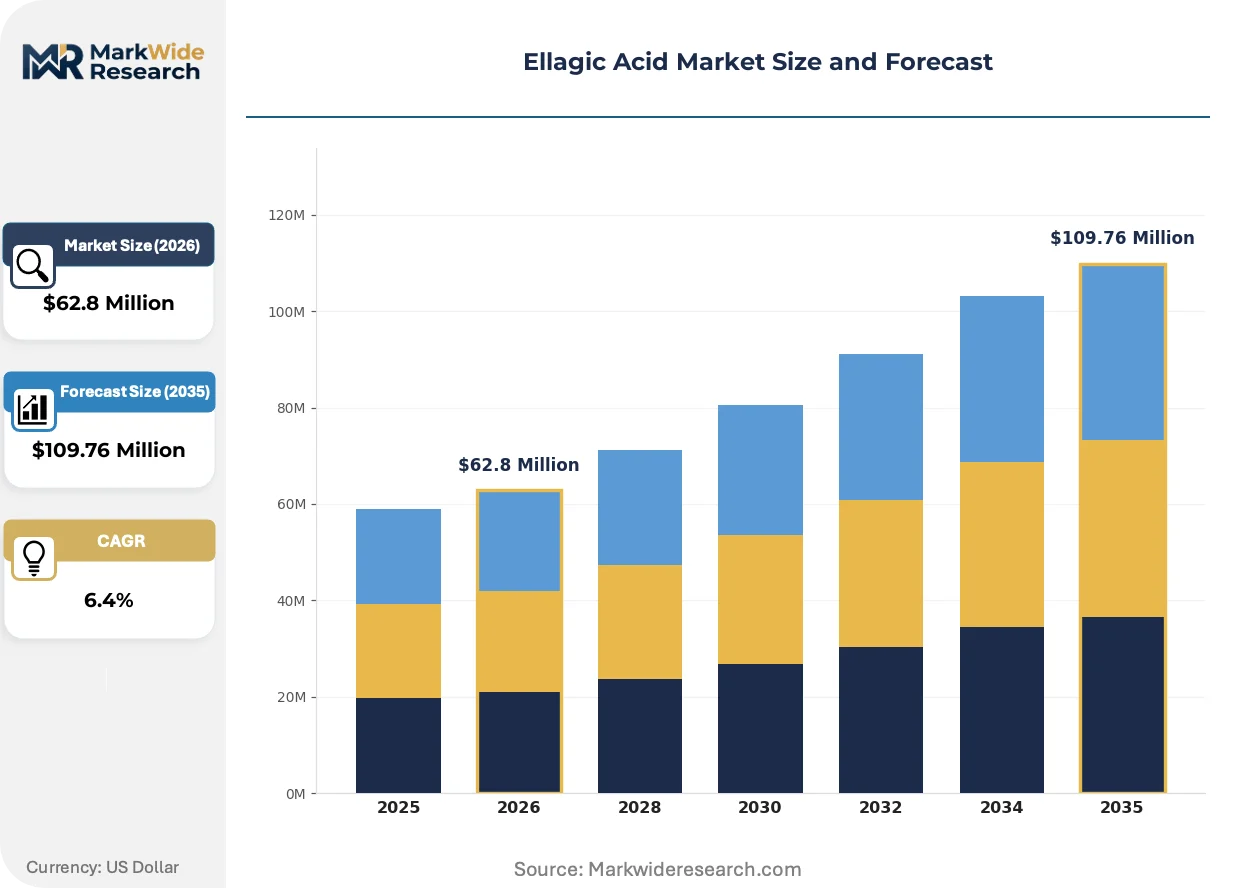
| Market Size in 2026 | $62.8 Million |
| Market Size in 2035 | $109.76 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tablets Application: Food & Beverage, Pharmaceuticals, Cosmetics, Dietary Supplements End User: Healthcare Providers, Nutraceutical Companies, Manufacturers, Retailers Sales Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Shanghai Kanwinn Pharmchem Ltd., Baoji Runyu Bio-Technology Co., Ltd., Aktin Chemicals, Inc., Hale Cosmeceuticals Inc., Biomax, Plamed Green Science Group, Alchem International, Chengdu Biopurify Phytochemicals, Sabinsa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ellagic Acid Market Shifts & Advancements
Extraction technology maturation and regulatory clarity around polyphenol stability claims are reshaping how suppliers differentiate beyond raw purity metrics toward validated bioavailability data.
Continuous-flow hydrolysis reactor technology is automating the transition from batch-wise ellagitannin acid conversion to steady-state processing. German pharmaceutical extractors are adopting these systems to reduce cycle times from 48 hours to sub-6-hour residence. The compression of conversion variability is enabling real-time release testing that reduces quarantine inventory holding costs.
EFSA's 2023 revised guidance on health claim substantiation for polyphenol antioxidants is forcing dietary supplement marketers to abandon generic "antioxidant" positioning in favor of specific oxidative stress biomarker studies. The industrial consequence is a bifurcation between commodity-grade suppliers and those investing in human clinical trials. German and French finished goods manufacturers are now requiring ingredient partners to carry proprietary trial data as a procurement precondition.
Long-term offtake contracting is displacing spot purchasing among North American nutraceutical contract manufacturers seeking supply security for 36-month branded product lifecycles. The shift compresses working capital flexibility for smaller extractors while rewarding processors with captive raw material supply. This pattern is most visible in California and New Jersey, where functional beverage formulators are locking in three-year pomegranate peel derivative supply agreements.
Ellagic Acid Market Segmentation
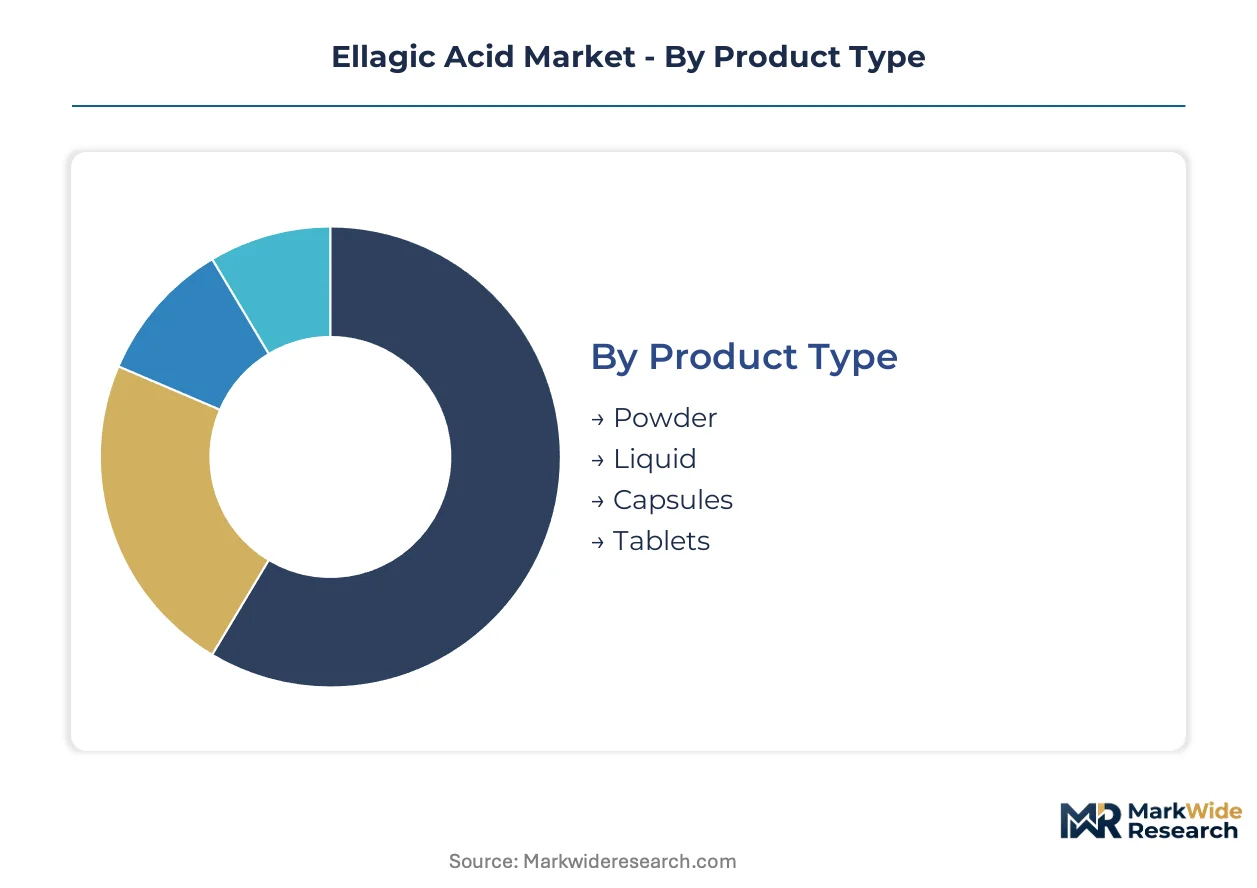
Ellagic acid procurement patterns diverge sharply across specification grades and delivery formats, with pharmaceutical compounders demanding USP-NF certified isolates while functional beverage formulators prioritize rapid-dispersion liquid concentrates. Understanding these segment boundaries reveals where margin pools concentrate and where commoditization pressures are most acute.
Product Type:
Specification chemistry and stability requirements differentiate procurement behavior across physical formats, with hydrolysis completion ratios and residual solvent profiles serving as primary qualification gates.
- Powder:Crystalline or amorphous isolates standardized to 90-98% purity enable precise dosing in pharmaceutical compounding and solid dosage manufacturing. German and US pharmaceutical contract manufacturers dominate procurement, driven by cGMP batch documentation requirements and USP-NF monograph alignment for antioxidant therapy protocols.
- Liquid:Hydro-alcoholic or glycerite solutions with rapid dispersion characteristics suit functional beverage integration and cosmetic serum formulation. California-based beverage formulators are scaling procurement for 36-month offtake contracts, compressing spot market liquidity while rewarding processors with captive pomegranate peel supply.
- Capsules:Pre-measured gelatin or vegetable cellulose shells containing standardized ellagic acid powder simplify dosing compliance for direct-to-consumer supplement brands.
- Tablets:Compressed formulations with binding agents and disintegration modifiers target pharmacy retail channels requiring extended shelf stability.
Powder leads on scale; liquid leads on momentum.
Application:
End-use regulatory pathways create divergent margin structures, with pharmaceutical qualification commanding premium pricing against commodity nutraceutical positioning.
- Pharmaceuticals:High-purity isolates for inflammatory disease protocols and antioxidant therapy development face stringent pharmacopeial compliance. REACH-registered European extractors and FDA-inspected US facilities capture volume as EMA and FDA audit requirements filter uncertified suppliers.
- Dietary Supplements:Branded finished goods command deepest margin pools through premium positioning over bulk ingredient sales, though EFSA's revised polyphenol health claim substantiation rules are forcing clinical trial investments.
- Cosmetics:Liposomal encapsulation and nano-emulsion formulations enable photodamage repair claims previously blocked by polyphenol instability, opening dermal delivery segments.
- Food & Beverage:Functional beverage applications favor rapid-dispersion liquid extracts where gallic acid substitution from grape seed sources pressures price-sensitive contracts.
Pharmaceuticals anchors value capture; dietary supplements shows steepest expansion trajectory.
End User:
Procurement sophistication varies with technical capability, separating specification-driven compounders from price-sensitive blenders.
- Nutraceutical Companies:Contract manufacturers and branded marketers with formulation expertise drive standardized polyphenol demand, with German and French finished goods manufacturers now requiring proprietary clinical trial data as procurement preconditions.
- Healthcare Providers:Hospital systems and specialty clinics sourcing for integrative medicine protocols prioritize batch consistency documentation and pharmacopeial alignment.
- Manufacturers:Ingredient processors and finished goods producers with captive extraction capacity leverage backward integration into raw tannin supply.
- Retailers:Mass-market and specialty channels with limited technical staff depend on pre-certified supplier relationships and third-party testing documentation.
Nutraceutical companies concentrate procurement volume; healthcare providers are gaining share fastest.
Sales Channel:
Channel structure reflects buyer scale and technical sophistication, with direct relationships displacing intermediaries among mid-volume purchasers.
- Distributors:Traditional ingredient distributors with warehousing and technical service capabilities retain relevance for small-batch pharmaceutical compounders requiring just-in-time delivery.
- Direct Sales:Long-term offtake contracting between processors and large nutraceutical contract manufacturers is displacing spot purchasing, compressing working capital flexibility for smaller extractors.
- Online Retail:B2B ingredient marketplaces are disintermediating traditional networks for mid-volume buyers seeking supply security without distributor markups.
- Offline Retail:Conventional trade channels serve price-sensitive regional blenders with limited specification requirements.
Distributors maintain infrastructure dominance; direct sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redrawing production geography as REACH compliance costs in Europe and FDA inspection backlogs in the United States push some extraction capacity toward jurisdictions with streamlined botanical extract pathways. Processors weighing pharmaceutical-grade qualification against nutraceutical bulk supply are calculating jurisdiction-specific cost-of-compliance gaps.
Germany
Pharmaceutical contract manufacturers in Baden-Württemberg and Bavaria are scaling high-purity ellagic acid procurement for inflammatory disease protocols. EMA audit requirements and REACH registration mandates filter uncertified suppliers, consolidating volume among ECHA-registered extractors with chromatographic purification capacity.
United States
California and New Jersey functional beverage formulators are locking in three-year offtake contracts for rapid-dispersion liquid extracts. FDA dietary supplement cGMP standards and USP-NF monograph alignment requirements shape supplier qualification, with seven-figure capex barriers excluding mid-scale entrants from pharmaceutical-grade certification.
China
NMPA and GB standards for natural extracts are tightening import specifications, redirecting supply toward domestic certification investments. Yangtze River Delta processors leverage geographic proximity to Asian botanical sourcing corridors while navigating the national pharmaceutical regulator's evolving purity benchmarks for polyphenol isolates.
India
FSSAI's 2024 streamlined botanical extract approval pathway enables direct entry into ayurvedic pharmaceutical compounding without EU mutual recognition dependency. Maharashtra and Gujarat-based contract manufacturers are scaling extraction capacity to serve both domestic nutraceutical demand and export contracts to European formulators.
France
Finished goods manufacturers in Île-de-France and Auvergne-Rhône-Alpes now require ingredient partners to carry proprietary clinical trial data as procurement preconditions. EFSA's revised polyphenol health claim substantiation rules are forcing dietary supplement marketers to abandon generic positioning in favor of specific oxidative stress biomarker studies.
Ellagic Acid Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cosmeceutical dermal delivery and liposomal encapsulation technology. The supplier base concentrates among vertically integrated botanical processors capable of certifying hydrolysis consistency from raw tannin to finished isolate. Three archetypes dominate: REACH-registered European extractors with pharmaceutical-grade capacity, Asia-Pacific processors leveraging geographic sourcing proximity, and North American specialists with captive raw material supply. Competitive moves center on long-term offtake contracting for supply security and supercritical CO2 hydrolysis technology licensing to displace hexane-based processes.
Within the Asia-Pacific processor tier, Shanghai Kanwinn Pharmchem Ltd. and Chengdu Biopurify Phytochemicals occupy positions anchored by proximity to Chinese botanical sourcing corridors. Sabinsa Corporation exemplifies the North American specialist archetype with backward integration into standardized polyphenol extraction protocols. These three entities represent the geographic and capability segmentation shaping procurement decisions for pharmaceutical compounders and nutraceutical contract manufacturers.
| Leading Market Players |
|---|
| Shanghai Kanwinn Pharmchem Ltd. |
| Baoji Runyu Bio-Technology Co., Ltd. |
| Aktin Chemicals, Inc. |
| Hale Cosmeceuticals Inc. |
| Biomax |
| Plamed Green Science Group |
| Alchem International |
| Chengdu Biopurify Phytochemicals |
| Sabinsa Corporation |
| Others |
Supply & Pricing Matrix
Supercritical CO2 hydrolysis technology adoption is compressing processing costs for dietary supplement-grade material while simultaneously concentrating supply among capitalized processors capable of displacing hexane-based extraction. This dual effect—cost reduction at the technology frontier and margin compression for legacy operators—is redrawing competitive boundaries between REACH-registered European extractors and Asia-Pacific processors with geographic sourcing proximity.
Pricing Analysis
Distributor margin layers in traditional ingredient supply chains face disintermediation pressure as B2B marketplaces enable direct contracting between processors and mid-volume nutraceutical compounders. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and economy-bulk levels separates USP-NF certified isolates from standardized polyphenol extracts and uncharacterized raw tannin hydrolysates. Pricing pressure stems from gallic acid substitution in functional beverage applications, where grape seed-derived hydrolyzable tannins capture price-sensitive contracts. Contract manufacturers exhibit highest price sensitivity; pharmaceutical formulators in Germany and the United States demonstrate lowest elasticity due to pharmacopeial compliance requirements.
Supply Chain Analysis
Refurbishment and reprocessing flows for extraction solvents are gaining operational significance as supercritical CO2 systems enable closed-loop recovery that hexane-based operations cannot replicate. Raw material supply concentrates in India and Iran for pomegranate peel, China for oak bark and walnut shell, with Germany and the United States anchoring downstream pharmaceutical compounding. Critical inputs include ellagitannin-rich botanical matrices, chromatographic purification resins, and green solvent systems. Single-source vulnerability in seasonal pomegranate harvests creates raw material risk for processors lacking multi-botanical sourcing. Distribution runs through long-term offtake contracting between vertically integrated processors and large nutraceutical contract manufacturers, compressing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ellagic acid procurement economics favor margin expansion through supercritical CO2 technology licensing and pharmaceutical-grade certification investments that command premium positioning over commodity nutraceutical supply.
For Market Incumbents: Acquire chromatographic purification capacity and REACH registration assets to defend against gallic acid substitution in functional beverage applications. Secure captive walnut shell or berry processing supply through backward integration into raw tannin sources. Prioritize long-term offtake contracting with California and New Jersey functional beverage formulators to lock in 36-month supply visibility. For New Entrants and Emerging Players: Launch via B2B ingredient marketplaces targeting mid-volume nutraceutical contract manufacturers seeking supply security without distributor markups. Penetrate India's ayurvedic pharmaceutical compounding segment through FSSAI novel food clearance, bypassing EU mutual recognition dependency. Emphasize liposomal encapsulation technology for cosmeceutical dermal delivery as a differentiated entry angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale hexane-dependent extractors facing technology obsolescence, while REACH-registered European processors with pharmaceutical-grade capacity command scarcity premiums. Five-to-ten year viability hinges on regulatory compliance depth and clinical trial data ownership. Monitor EFSA health claim substantiation enforcement and USP-NF monograph updates as inflection indicators for ingredient partner procurement preconditions.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Technology Licensing | Green solvent extraction displaces hexane-based processes, reducing residual solvent risk for FDA cGMP compliance. |
| REACH Registration Investment | ECHA compliance mandates filter uncertified European suppliers, consolidating volume among registered extractors. |
| Long-term Supply Agreement | Thirty-six month offtake contracting with California beverage formulators compresses working capital for spot-dependent competitors. |
| Pharmaceutical-grade Certification | USP-NF monograph alignment enables antioxidant therapy protocol supply to German and US pharmaceutical compounders. |
| Liposomal Encapsulation R&D | Nano-emulsion formulation opens photodamage repair segments previously closed to polyphenol instability. |
Research Methodology
Bottom-up pharmaceutical and nutraceutical procurement modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with plant managers at botanical processors, procurement leads at dietary supplement contract manufacturers, regulatory affairs specialists navigating EMA and FDA pathways, and technical R&D directors supervising hydrolysis optimization were cross-validated against secondary sources including ECHA registration databases, FDA cGMP inspection records, FSSAI approval notifications, USP-NF monograph drafts, and customs trade data for ellagitannin-rich raw material flows.
Input-output matrices mapping hydrolysis completion ratios to finished isolate yields across powder, liquid, capsule, and tablet formats generate volume and value trajectories over the projection horizon. Segmentation dimensions span specification grade, physical format, end-use application, and regional regulatory cluster. CAGRs derive from modeled adoption curves for supercritical CO2 technology and pharmaceutical-grade qualification investments. Key forecast inputs include seasonal pomegranate peel harvest variability and EFSA polyphenol health claim substantiation enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pharmacopeial monograph delays or abrupt FSSAI regulatory shifts. Practitioners should monitor REACH registration renewal timelines and EMA audit backlog resolution for early signals of European supply consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market