
 Beverage Encapsulants Market | 2026-2036
Beverage Encapsulants Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Encapsulants Market Analytics
European specialty chemical producers is expanding microencapsulation capacity for heat-sensitive beverage actives. Givaudan leverages integrated flavor-encapsulation labs in Switzerland and Singapore to anchor regional formulation services. Kerry Group sustains R&D intensity across hydrocolloid and liposome delivery platforms for sports nutrition clients. BASF competes on synthetic polymer alternatives to natural wall materials, positioning its portfolio for cost-sensitive soft drink makers.
Beverage encapsulants are barrier-forming materials—typically gelatin, gum arabic, modified starch, or pectin—deposited as protective matrices around volatile flavors, vitamins, probiotics, or colorants, with particle sizes commonly ranging from 10 to 1000 microns depending on the release mechanism required. These structures shield core actives from oxidation, moisture, and thermal degradation during pasteurization, carbonation, or shelf storage, enabling precise temporal or pH-triggered release in the finished drink. The functional beverages application leads in value contribution, as brands seek to differentiate through stable probiotic and nootropic delivery in ready-to-drink formats. Powder form dominates current production volumes due to compatibility with dry-blend manufacturing lines and extended ambient stability, though liquid emulsion formats are gaining traction in cold-fill aseptic operations where rapid dispersion matters.
The FDA governs encapsulated food additives through GRAS self-affirmation and food contact notification pathways, while the EPA tracks solvent residues from spray-drying and coacervation processes. The EU's EFSA evaluates novel encapsulation technologies under the Novel Food Regulation, with REACH compliance required for synthetic shell materials crossing into food-contact applications. Stakeholders must monitor how divergent clean-label definitions across jurisdictions reshape acceptable wall material portfolios and reformulation timelines.
Market Dynamics
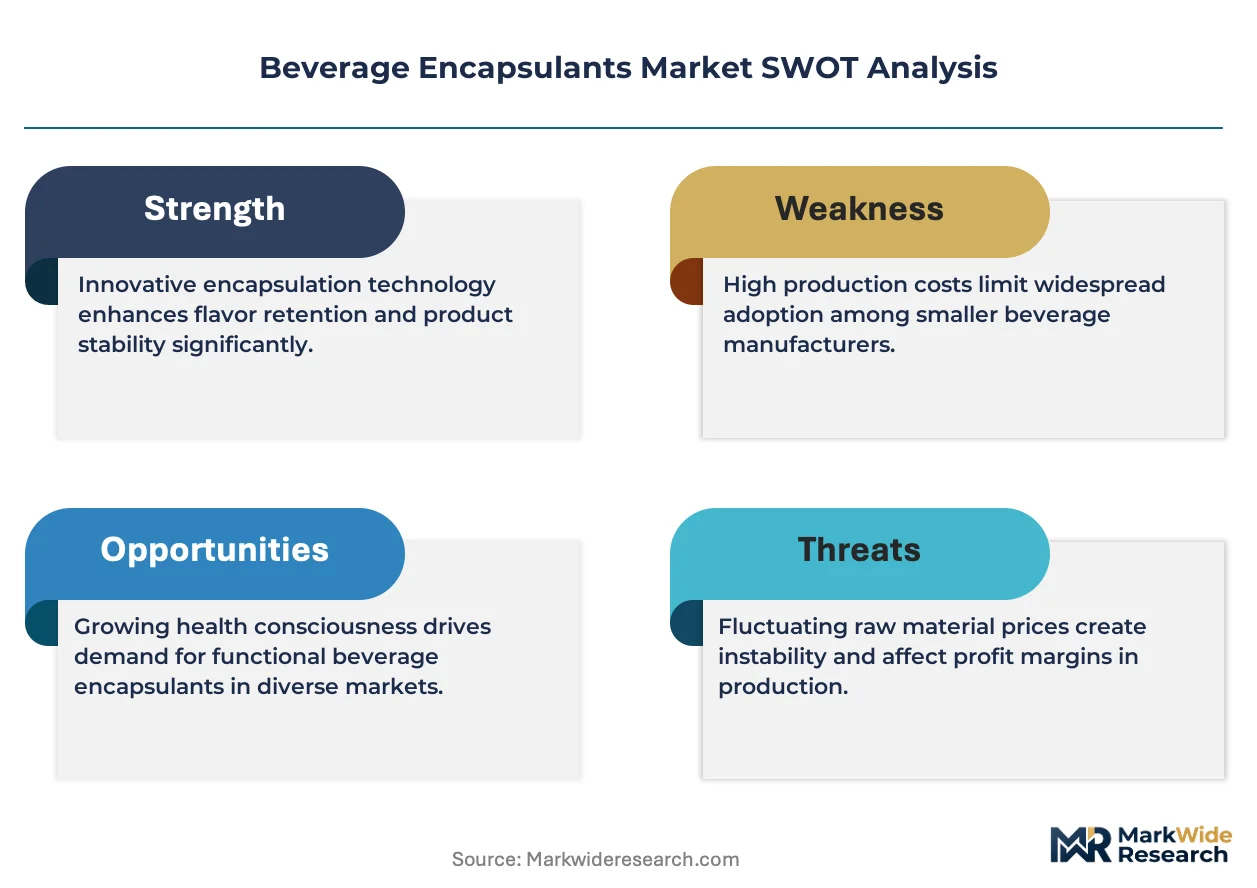
Clean-label reformulation mandates from EFSA and FDA are compressing acceptable wall material portfolios, forcing simultaneous investments in natural hydrocolloid R&D and synthetic polymer substitution pathways across formulation labs.
Growth Catalysts
- Functional beverage proliferation:Sports nutrition and nootropic drink brands in Germany and the United States are scaling purchases of encapsulated bioactives to differentiate shelf-stable probiotic and vitamin delivery systems.
- Co-location clustering:Flavor houses and ingredient suppliers are concentrating pilot production facilities around Chicago and Toronto, reducing formulation-to-scale timelines for North American contract manufacturers.
- Novel Food substantiation:Tightened EFSA evaluation pathways under the EU's Novel Food Regulation are accelerating investment in pre-clinical validation infrastructure by European specialty chemical producers.
Market Restraints
- Gum arabic supply volatility:Sudanese and Sahelian harvest disruptions constrain natural wall material availability, forcing reformulation cycles and price hedging by dry-blend manufacturers.
- Spray-drying solvent residues:EPA tracking of residual organic carriers from coacervation processes imposes additional purification capex and compliance documentation burdens.
- Heat-sensitive active degradation:Pasteurization temperatures above 85°C degrade unprotected probiotics and certain vitamins, limiting application scope in hot-fill beverage categories.
Strategic Opportunities
- pH-triggered release systems:Stomach-acid responsive microcapsules enable precise intestinal delivery of bioactives, opening formulation partnerships with pharmaceutical-nutrition convergence brands.
- Cold-fill aseptic liquid emulsions:Rapid-dispersion formats are gaining production share in premium refrigerated functional beverages where powder reconstitution is unacceptable.
- Swiss and Singaporean anchor labs:Integrated flavor-encapsulation facilities in these jurisdictions offer regional formulation services that bypass EU Novel Food queue congestion for Asia-Pacific market entry.
Industry Challenges
- Microencapsulation talent scarcity:Formulation chemists with simultaneous expertise in hydrocolloid chemistry and liposome engineering command premium compensation, constraining mid-tier supplier expansion.
- GRAS self-affirmation documentation:FDA notification pathways for new encapsulation technologies require 18-24 month substantiation timelines that delay product launch windows.
- Clean-label definition divergence:Jurisdiction-specific prohibitions on modified starches and synthetic polymers force parallel formulation tracks, multiplying SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Encapsulants Market |
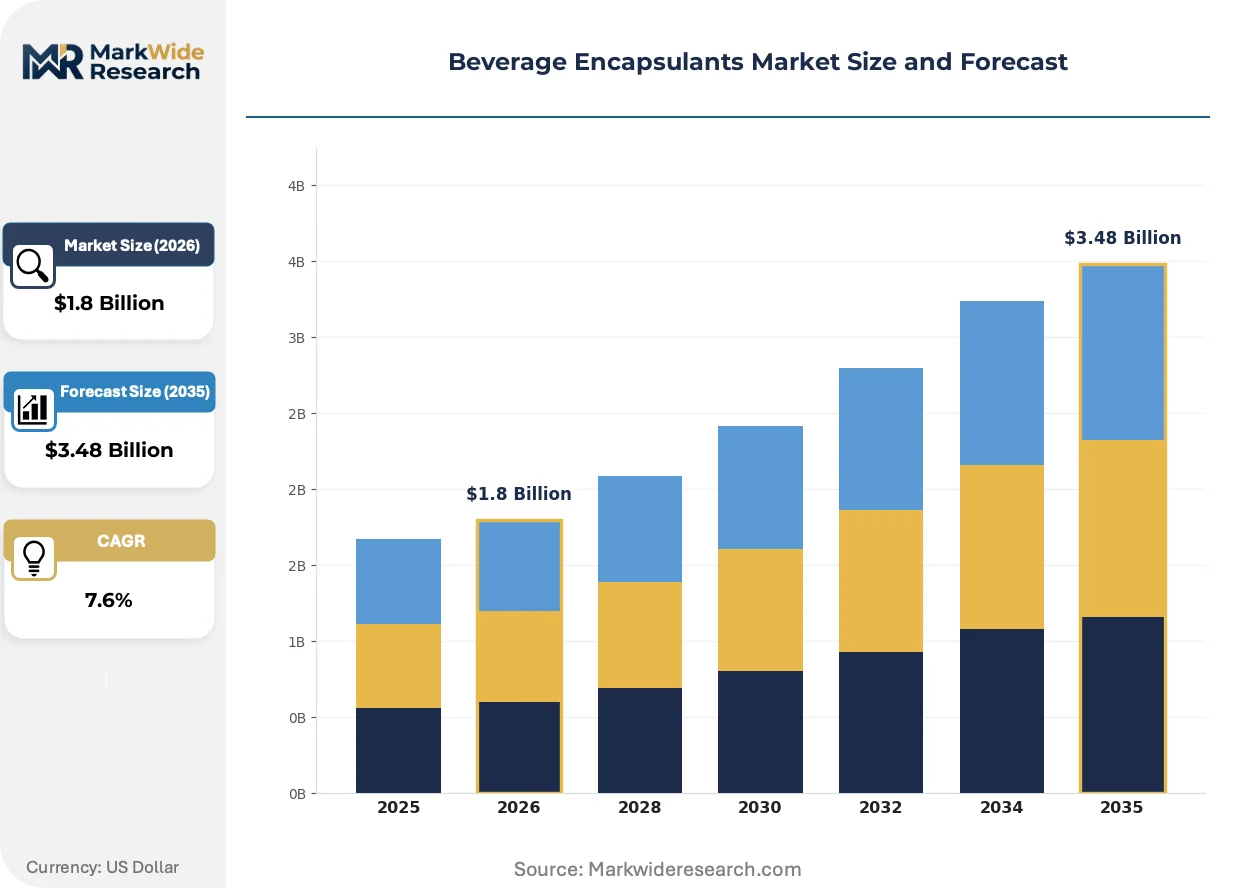
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Gum Arabic, Starch, Pectin Application: Functional Beverages, Soft Drinks, Sports Drinks, Nutraceuticals Form: Powder, Liquid, Granulated, Emulsion End User: Food & Beverage Manufacturers, Contract Manufacturers, Private Label Brands, Research Institutions |
| Companies Covered | Givaudan, International Flavors & Fragrances, Kerry Group, Symrise, BASF, Cargill, Koninklijke DSM, Balchem Corporation, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Encapsulants Market Evolving Landscape
Electrospraying and coaxial extrusion methods are compressing particle size distributions below 50 microns while improving encapsulation efficiency, reshaping equipment procurement priorities across pilot and production scales.
Liposome-in-hydrogel hybrid architectures are electrifying sports nutrition formulation pipelines. Ready-to-drink brands seeking stable omega-3 and nootropic delivery are adopting these dual-barrier systems at pilot scale. The technology is compressing oxidation-related shelf-life limitations that previously constrained functional beverage distribution radius.
REACH compliance requirements for synthetic shell materials are tightening substance authorization timelines. Food-contact applications of petroleum-derived polymers now face full dossier submission mandates. Soft drink makers are responding by accelerating natural wall material qualification programs, particularly in German and French formulation centers.
Buyer concentration among multinational functional beverage brands is compressing supplier negotiation cycles. Long-term offtake agreements with encapsulated ingredient minimums are displacing spot purchasing for core bioactives. This pattern is most visible in United States contract manufacturing hubs where CMOs now carry inventory risk for tier-one clients.
Beverage Encapsulants Market Segmentation
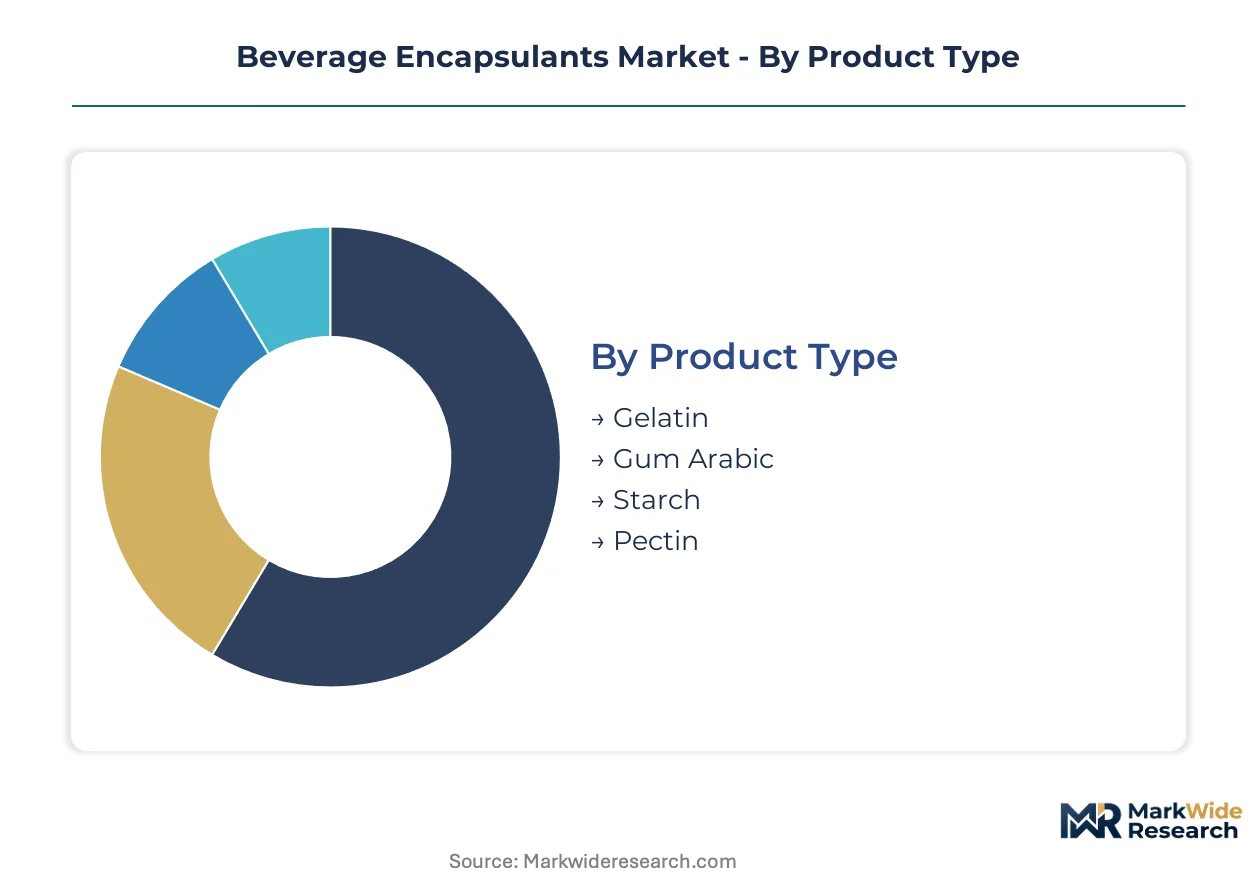
Encapsulant selection hinges on release kinetics, thermal tolerance, and clean-label positioning. Manufacturers segment procurement by wall material chemistry, beverage application, physical form, and supply chain role.
Product Type:
Buyers differentiate by natural origin certification, heat stability thresholds, and regional supply security.
- Gelatin:Animal-derived protein matrices deliver superior oxygen barrier properties for vitamin and probiotic protection. Demand concentrates in German functional beverage manufacturing where EFSA clean-label scrutiny elevates pharmaceutical-grade bovine and porcine sourcing standards.
- Gum Arabic:Acacia senegal exudate provides emulsification-stable encapsulation for flavor oils and colorants. Sudanese and Sahelian harvest disruptions force United States dry-blend manufacturers into aggressive price hedging and reformulation cycles.
- Starch:Modified and native corn or tapioca derivatives offer cost-efficient alternatives for spray-dried beverage premixes.
- Pectin:Citrus and apple-derived polysaccharides enable pH-triggered release systems for intestinal delivery applications.
Volume sits with starch and gelatin; growth tilts toward pectin as pharmaceutical-nutrition convergence accelerates.
Application:
End-use concentration varies by thermal processing intensity and bioactive fragility.
- Functional Beverages:Shelf-stable probiotic, nootropic, and adaptogenic delivery systems command premium encapsulation specifications. Chicago and Toronto contract manufacturing hubs scale pilot production for ready-to-drink brands seeking differentiation through stable active release.
- Sports Drinks:Electrolyte and amino acid encapsulation demands rapid dissolution kinetics without residual mouthfeel. German formulation centers prioritize liposome-in-hydrogel architectures for omega-3 stability in isotonic matrices.
- Soft Drinks:Carbonation-compatible flavor encapsulation requires pressure-resistant wall structures.
- Nutraceuticals:Medical-food positioning drives pharmaceutical-grade encapsulation standards and documentation burdens.
Revenue concentrates in functional beverages; steepest expansion trajectory appears in nutraceuticals as regulatory substantiation pathways mature.
Form:
Physical state selection tracks manufacturing line compatibility and shelf-life requirements.
- Powder:Spray-dried and fluid-bed agglomerated formats dominate dry-blend operations with ambient stability exceeding 24 months. United States flavor houses in the Chicago cluster optimize powder flow properties for high-speed beverage filling lines.
- Liquid:Emulsion and suspension formats enable cold-fill aseptic processing where powder reconstitution is unacceptable. Singaporean anchor labs develop rapid-dispersion liquid systems for Asia-Pacific premium refrigerated functional beverages.
- Granulated:Agglomerated particles improve handling characteristics for tabletop and stick-pack applications.
- Emulsion:Oil-in-water nanoemulsions enhance bioavailability of lipophilic actives in clear beverage matrices.
Production volume favors powder; technology investment flows toward emulsion formats for bioavailability enhancement.
End User:
Procurement sophistication diverges by scale, regulatory burden, and formulation capability.
- Food & Beverage Manufacturers:Multinational brands leverage long-term offtake agreements with encapsulated ingredient minimums, displacing spot purchasing. Inventory risk shifts to contract manufacturing organizations in United States hubs serving tier-one functional beverage clients.
- Contract Manufacturers:Co-located pilot facilities around Chicago and Toronto compress formulation-to-scale timelines through proximity to Givaudan and Kerry Group technical service labs.
- Private Label Brands:Retail-owned formulations demand cost-optimized encapsulation with acceptable clean-label positioning.
- Research Institutions:Academic and government laboratories validate novel encapsulation technologies under EFSA Novel Food and FDA GRAS pathways.
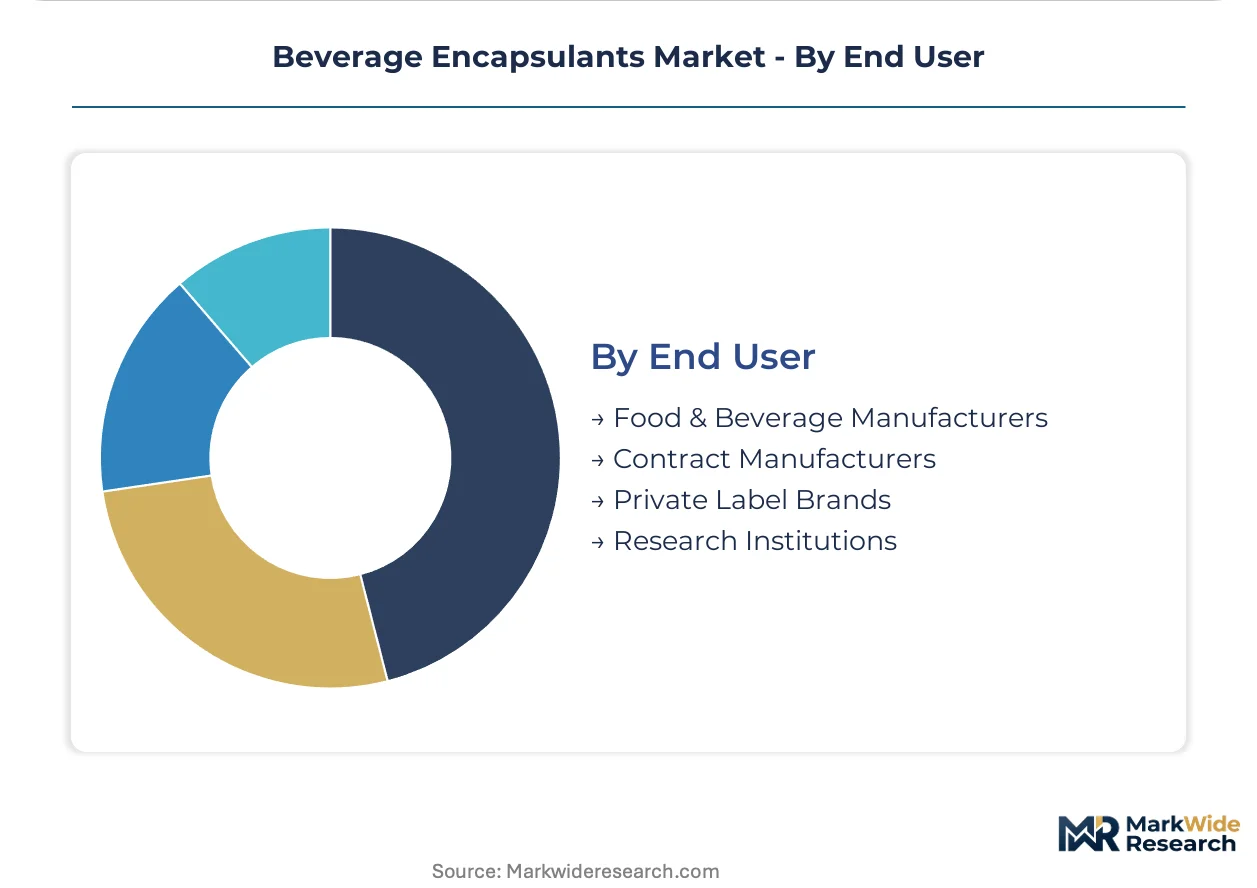
Procurement volume concentrates among food and beverage manufacturers; capability building accelerates fastest within contract manufacturing organizations seeking captive formulation expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sudanese gum arabic harvests anchor supply security calculations for European and North American formulators. Regional beverage encapsulant demand patterns track functional beverage manufacturing density, regulatory substantiation burdens, and co-location clustering of flavor houses with contract manufacturers.
United States
Chicago anchors North American contract manufacturing concentration for encapsulated bioactives. FDA GRAS self-affirmation pathways impose 18-24 month documentation timelines on novel encapsulation technologies. Pilot production facilities cluster around Chicago and Toronto to compress formulation-to-scale cycles for ready-to-drink brands.
Germany
Functional beverage manufacturers in Bavaria and North Rhine-Westphalia scale purchases of encapsulated probiotics and nootropics. EFSA clean-label scrutiny elevates pharmaceutical-grade gelatin sourcing standards above baseline EU requirements. BASF maintains synthetic polymer R&D operations for cost-sensitive soft drink applications.
Switzerland
Givaudan leverages integrated flavor-encapsulation labs to anchor regional formulation services for Asia-Pacific market entry. Swissmedic pharmaceutical-grade standards bleed into food-contact encapsulation specifications. The Zurich-Geneva corridor concentrates liposome-in-hydrogel hybrid architecture development.
Singapore
Rapid-dispersion liquid emulsion formats gain production share in premium refrigerated functional beverages. Anchor labs develop cold-fill aseptic systems that bypass EU Novel Food queue congestion. The city-state's position enables formulation partnerships targeting pharmaceutical-nutrition convergence brands across Southeast Asia.
Canada
Toronto contract manufacturing hubs co-locate with Kerry Group technical service facilities. Health Canada regulations align with FDA pathways while permitting faster pilot-scale validation. Ontario-based dry-blend manufacturers hedge against Sudanese gum arabic supply volatility through diversified wall material portfolios.
Beverage Encapsulants Market Competitive Landscape
Global majors compete with regional champions across formulation technology and regulatory substantiation capability. The vendor base organizes around three tiers: integrated flavor houses with captive encapsulation labs, specialty chemical producers with synthetic polymer portfolios, and mid-tier hydrocolloid suppliers serving cost-optimized dry-blend markets. Strategic moves concentrate on co-location clustering with contract manufacturers and pre-clinical validation infrastructure investments for Novel Food substantiation.
Within the integrated flavor-encapsulation tier, Givaudan and International Flavors & Fragrances exemplify the anchor-lab model with regional formulation services spanning Switzerland and Singapore. Kerry Group represents the specialty nutrition platform archetype with sustained R&D intensity across hydrocolloid and liposome delivery systems. BASF occupies a position among diversified chemical majors competing on synthetic polymer alternatives to natural wall materials.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Kerry Group |
| Symrise |
| BASF |
| Cargill |
| Koninklijke DSM |
| Balchem Corporation |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap hydrocolloid specialists in France and Germany anchor regional supply security through captive acacia plantations and long-term Sudanese offtake contracts, translating procurement discipline into stable pricing for pharmaceutical-grade gelatin and pectin grades while forcing synthetic polymer competitors into aggressive discounting to retain soft drink accounts.
Pricing Analysis
Service bundling separates formulation support from base material supply, with Givaudan and Kerry Group embedding technical consultation and pilot-scale validation into premium encapsulant contracts while commodity starch and gum arabic suppliers strip out services for spot-market transactions. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels reflects EFSA and FDA documentation burdens. Cost compression in natural wall materials is intensifying because Sudanese harvest disruptions force reformulation cycles and emergency sourcing premiums. Private label brands exhibit highest price sensitivity, demanding cost-optimized encapsulation with minimal clean-label compromise, while nutraceutical manufacturers absorb premiums for GRAS-substantiated novel delivery systems.
Supply Chain Analysis
Dual-sourcing mandates from Chicago and Toronto contract manufacturers require simultaneous qualification of European and Asia-Pacific gelatin suppliers to hedge against bovine spongiform encephalopathy-related import suspensions. Production gravity centers on Germany, Switzerland, and Singapore for high-value liposome-in-hydrogel systems, with spray-dried powder capacity concentrated in the United States and France. Raw material portfolios draw from Sudanese gum arabic, Brazilian and Indonesian pectin feedstocks, and corn-derived modified starches from the United States Midwest. Single-source vulnerability in acacia senegal exudate creates structural exposure to Sahelian climate volatility and export licensing disruptions. Distribution runs through co-located flavor house technical service labs that compress formulation-to-scale timelines for North American functional beverage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into upstream wall material production and downstream pilot-scale formulation services has become the decisive capability race, with captive acacia plantations and in-house liposome engineering separating margin-defensible specialists from commodity-pressed suppliers.
For Market Incumbents: Hedge against gum arabic supply volatility through accelerated pectin and modified starch qualification programs in German and French formulation centers. Invest in pre-clinical validation infrastructure to compress EFSA Novel Food substantiation timelines before REACH authorization burdens tighten further on synthetic polymer alternatives. Defensive consolidation should target mid-tier hydrocolloid suppliers with established clean-label certifications.
For New Entrants and Emerging Players: Contract manufacturing organizations in the Chicago-Toronto corridor represent the most penetrable entry point, as inventory risk shifting from multinational brands creates demand for agile formulation partners. Target cold-fill aseptic liquid emulsion formats where rapid-dispersion technology gaps persist among incumbent powder specialists. Go-to-market should anchor on pharmaceutical-nutrition convergence brands seeking pH-triggered intestinal delivery partnerships.
For Investors and Strategic Acquirers: Kerry Group or Givaudan acquiring a liposome engineering specialist is the leading indicator that hybrid-architecture capabilities are consolidating beyond mid-tier reach. Long-term viability favors vertically integrated platforms spanning natural wall material sourcing through GRAS-substantiated novel delivery systems. Watch for BASF divesting synthetic polymer food-contact portfolios under REACH pressure as the signal that natural-material substitution has crossed into irreversible structural shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acacia Plantations | Captive Sudanese and Senegalese gum arabic supply secures pharmaceutical-grade certification tiers against harvest volatility. |
| Pre-Clinical Validation Infrastructure Buildout | In-house EFSA Novel Food dossier capabilities compress 18-24 month substantiation timelines for probiotic encapsulation. |
| Liposome-in-Hydrogel Hybrid Architecture Development | Dual-barrier omega-3 stability commands premium positioning in German sports nutrition formulation pipelines. |
| Anchor Lab Co-Location with CMOs | Singapore and Switzerland technical service proximity accelerates Asia-Pacific market entry bypassing EU regulatory queues. |
| Synthetic Polymer Portfolio Divestiture | REACH compliance cost avoidance redirects R&D toward pectin and starch qualification for clean-label soft drink accounts. |
Research Methodology
Document review covered FDA GRAS notification databases, EFSA Novel Food approved applications, and REACH substance authorization filings, complemented by interviews with encapsulation R&D directors at flavor houses, procurement leads at Chicago and Toronto contract manufacturing organizations, regulatory affairs managers navigating EFSA substantiation pathways, and technical service heads at hydrocolloid suppliers. Secondary validation drew from customs trade data on gum arabic and gelatin imports, SEC 10-K disclosures from diversified chemical majors, and specialty chemical industry association capacity reports. Bottom-up segment sizing triangulated against top-down functional beverage production volume estimates.
Cross-referencing historical capacity expansion patterns against panel input from plant engineering firms shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include wall material chemistry, beverage application thermal processing intensity, physical form manufacturing line compatibility, and supply chain role procurement sophistication. CAGRs were derived from slope analysis of segment-specific adoption curves calibrated to clean-label regulatory enforcement intensity and functional beverage brand launch pipelines. Forecast inputs incorporated Sudanese harvest yield variability and EFSA Novel Food queue duration trends.
Caveats apply where Sudanese political instability, REACH substance authorization delays, or FDA GRAS notification backlogs could materially shift the outlook. Deviation in acacia senegal export licensing or EFSA clean-label definition expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Africa Food Emulsifiers Market