
 Tapioca Market | 2026-2036
Tapioca Market Size, Share, and Industry Trends Forecast 2026-2036
Tapioca Market Outlook
Skilled agricultural labor availability across cassava-growing belts is collapsing, tightening raw material flows and forcing processors to automate harvesting or relocate sourcing. Cargill, Inc. leverages its integrated supply chain from Thai farms to North American food manufacturers, sustaining volume commitments despite regional labor shortages. PT Budi Starch & Sweetener Tbk anchors Southeast Asian production capacity, while Ingredion Incorporated competes through specialty modified starch R&D in the Americas and Europe.
Tapioca denotes the extracted starch and processed derivatives from the cassava root (Manihot esculenta), a tuberous crop containing 25-30% amylopectin by dry weight that undergoes washing, grating, and centrifugal separation to yield a white, neutral-flavored powder used as a thickener, binder, and texturizer across food and industrial applications. Starch commands the largest product type position due to its ubiquity in processed foods and adhesives, while pearls maintain strong growth momentum through bubble tea channel expansion across East Asian and North American food service. Flour occupies a mature niche in gluten-free bakery, where margin pools concentrate in certified organic and non-GMO supply tiers.
The EU Green Deal and REACH frameworks impose traceability and chemical residue limits on imported starch, compelling exporters to upgrade processing documentation. Thailand's Ministry of Agriculture and Cooperatives enforces national Good Agricultural Practice standards that shape farm-level certification requirements for international buyers. Stakeholders must monitor evolving deforestation-linked due diligence rules in European import regulations and assess whether backward integration into cassava farming or third-party audit partnerships offer stronger compliance pathways.
Market Dynamics
Clean-label formulation mandates from EU Green Deal procurement rules are forcing tapioca starch processors to revalidate every farm in their sourcing network, compressing supplier lists and raising compliance costs for exporters serving European food manufacturers.
Growth Catalysts
- EU Green Deal traceability mandates:European food manufacturers now require deforestation-free sourcing documentation, pulling certified Thai and Vietnamese cassava into premium supply tiers.
- Bubble tea channel expansion:Food service operators across East Asia and North America are standardizing tapioca pearls as a core menu component, creating dedicated procurement pipelines.
- Modified starch R&D:Ingredient technologists are developing cold-water swelling variants for instant food applications, opening formulation possibilities in ready meals.
Market Restraints
- Skilled agricultural labor collapse:Cassava-growing belts in Thailand and Vietnam face harvesting workforce shortages, constraining raw material throughput during peak seasons.
- REACH chemical residue limits:ECHA documentation requirements for imported starches add testing costs and documentation delays for Asian exporters.
- Potato and corn starch substitution:Commodity grain starches compete on price in non-premium thickener applications, capping tapioca penetration in cost-sensitive segments.
Strategic Opportunities
- Indian subcontinent penetration:FSSAI clean-label standards are creating entry points for certified organic tapioca in domestic processed food manufacturing.
- Biodegradable packaging films:Thermoplastic starch formulations are displacing petroleum-based films in Japanese and South Korean flexible packaging.
- PLI scheme alignment:India's production-linked incentive framework for food processing infrastructure rewards backward integration into cassava farming cooperatives.
Industry Challenges
- Good Agricultural Practice certification timelines:Thai Ministry of Agriculture audits require 18-24 month farm-level documentation buildouts, delaying market access.
- Legacy equipment integration:Southeast Asian processing facilities must retrofit centrifugal separation lines to meet EU Green Deal batch traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tapioca Market |
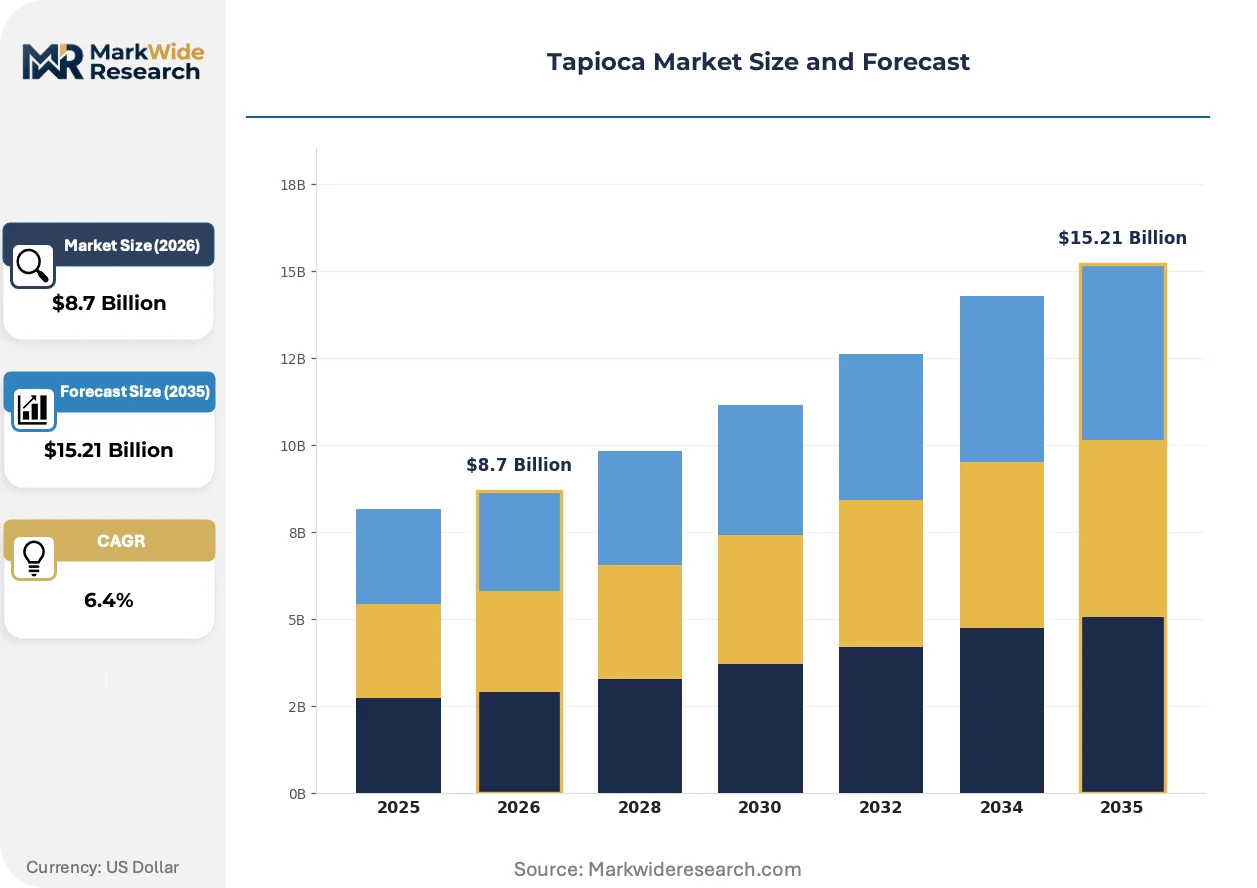
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Pearls, Starch, Snacks Application: Food & Beverage, Processed Foods, Bakery, Culinary Uses End User: Household, Food Service, Manufacturing, Exporters Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Archer Daniels Midland Company, PT Budi Starch & Sweetener Tbk, Ingredion Incorporated, Grain Processing Corporation, Emsland Group, Cargill, Inc., Thai Wah Public Company Limited, Bangkok Starch Industrial Co., Ltd., Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tapioca Market Strategic Shifts
Processing technology and regulatory documentation requirements are converging to reshape competitive positioning, with automation and traceability systems becoming the primary axes of differentiation among starch suppliers.
Enzymatic modification protocols for tapioca starch are fragmenting the traditional wet-milling value chain. Specialty food manufacturers in Japan and South Korea are adopting these processes to achieve specific viscosity profiles without chemical cross-linking. The technology is fragmenting procurement patterns as buyers bypass commodity traders to contract directly with enzymatic processing specialists.
REACH framework updates on deforestation-linked due diligence are tightening documentation requirements for starch imports into the European Union. ECHA guidance now requires geolocation data for every farm contributing to a processed batch. European bakery and confectionery manufacturers are responding by consolidating supplier lists to those with integrated farm-to-factory traceability systems.
Food service procurement is consolidating around direct-import arrangements for tapioca pearls. North American bubble tea chains are establishing captive supply relationships with Thai and Vietnamese processors, displacing traditional ingredient distributors. This consolidation is most visible in metropolitan markets across California and Texas where chain density supports dedicated container shipments.
Tapioca Market Segmentation
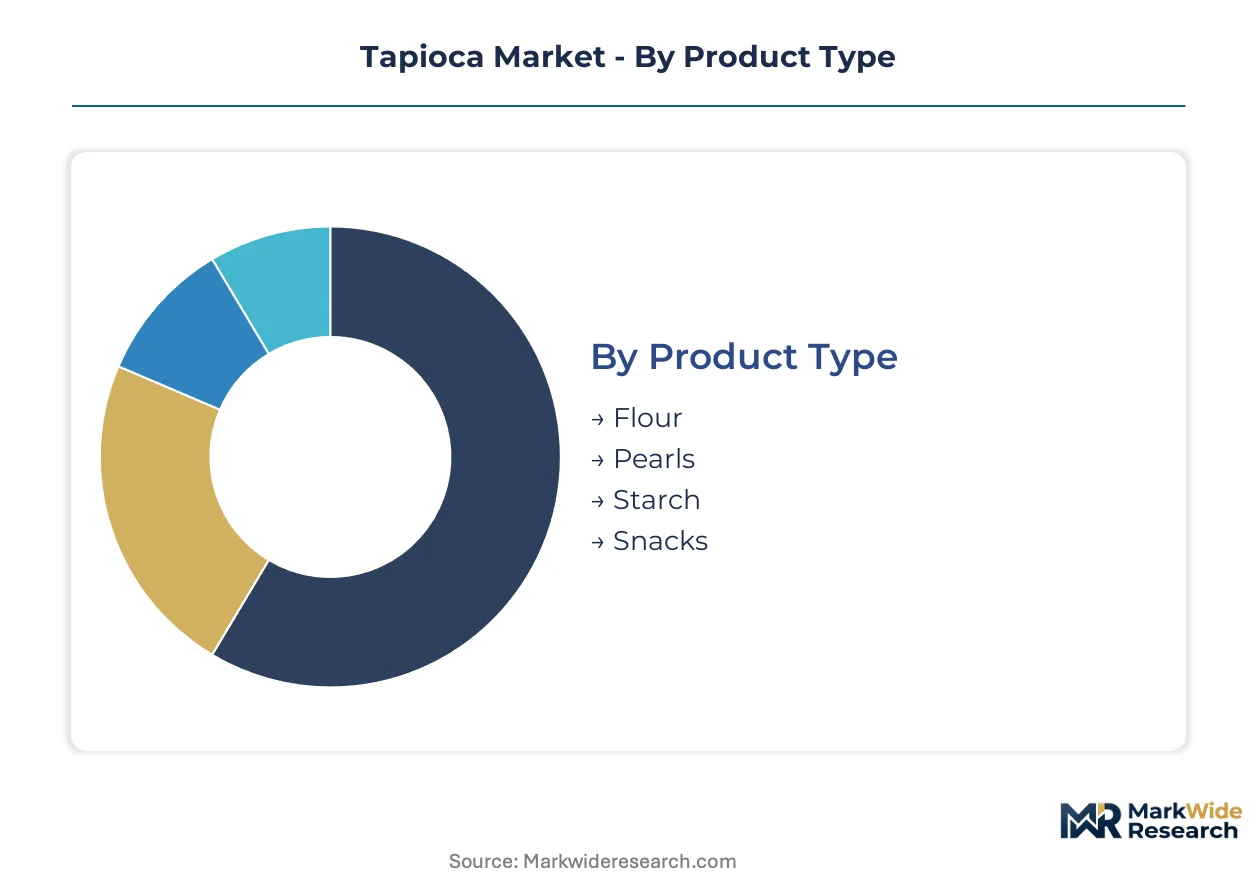
Tapioca derivatives serve distinct functional roles across food manufacturing and consumer channels, with margin capture varying sharply by processing intensity and certification requirements. Segmentation reveals where value concentrates amid tightening traceability mandates and shifting procurement patterns.
Product Type:
Margin pools concentrate in modified starch grades and specialty pearl formulations where enzymatic processing and clean-label certification create pricing power above commodity tiers.
- Starch:Extracted through washing, grating, and centrifugal separation into a white powder containing 25-30% amylopectin. Demand concentrates in North American and European food manufacturing where EU Green Deal traceability requirements favor suppliers with integrated Thai farm networks. Clean-label formulation mandates are compressing supplier lists to certified processors.
- Pearls:Spherical aggregates formed through extrusion and sizing for food service applications. Bubble tea channel expansion across California, Texas, and East Asian metropolitan markets is driving dedicated procurement pipelines direct from Thai and Vietnamese processors. Cold-chain logistics requirements sustain regional processing clusters.
- Flour:Finely ground cassava root retaining fiber content for gluten-free bakery applications. Certified organic and non-GMO supply tiers command premium positioning in specialty retail channels.
- Snacks:Fried or baked cassava chip and crisp products targeting mass-market consumption. Regional flavor localization drives formulation variation across Southeast Asian domestic markets.
The dominant share belongs to Starch, while Pearls is closing the gap fastest through food service channel consolidation.
Application:
Volume throughput scales with industrial processing intensity, yet margin extraction improves furthest from commodity ingredient sales into finished product integration.
- Food & Beverage:Encompasses beverage texturization, dairy alternatives, and functional drink formulations. Japanese and South Korean manufacturers are adopting enzymatic modification protocols to achieve specific viscosity profiles without chemical cross-linking.
- Processed Foods:Ready meal thickeners, instant soup bases, and sauce applications requiring cold-water swelling variants. Modified starch R&D is opening formulation possibilities in convenience food segments.
- Bakery:Gluten-free bread, cake, and pastry applications where tapioca flour substitutes wheat. FSSAI clean-label standards in India are creating certified organic entry points for domestic manufacturing.
- Culinary Uses:Direct household and restaurant preparation including traditional Southeast Asian desserts and thickeners. Recipe authenticity requirements sustain regional sourcing preferences.
Food & Beverage holds the largest volume position, though Processed Foods shows the steepest expansion trajectory through instant application development.
End User:
Procurement sophistication varies sharply by scale, with integrated manufacturers capturing cost advantages unavailable to fragmented household buyers.
- Manufacturing:Industrial food and adhesive producers purchasing bulk starch with specification-grade consistency. REACH documentation requirements from ECHA are adding testing costs and delays for Asian exporters serving European manufacturers.
- Food Service:Restaurant chains, bubble tea operators, and institutional caterers requiring pearl and flour products. North American chains are establishing captive supply relationships displacing traditional ingredient distributors.
- Household:Retail consumers purchasing packaged flour, pearls, and snacks through grocery channels. Price sensitivity limits penetration against potato and corn starch substitutes in non-premium applications.
- Exporters:Trading intermediaries and regional processors shipping to international markets. EU Green Deal deforestation-free sourcing documentation is pulling certified Thai and Vietnamese cassava into premium supply tiers.
Manufacturing commands the value share, while Food Service is gaining share fastest through direct-import consolidation.
Distribution Channel:
Channel selection determines traceability depth and margin retention, with integrated wholesale arrangements outperforming fragmented retail in compliance-intensive segments.
- Wholesale:Bulk transactions between processors and industrial manufacturers or large food service operators. Container-scale shipments from Thai and Vietnamese processing clusters support metropolitan chain density in California and Texas.
- Supermarkets:Packaged retail products through mass-market grocery networks. Certification labeling requirements vary by jurisdiction, complicating pan-regional SKU management.
- Online Retail:Direct-to-consumer and B2B platform sales expanding specialty and organic product access. India's PLI scheme for food processing infrastructure rewards backward integration into cassava farming cooperatives.
- Convenience Stores:Impulse and immediate-consumption snack and small-format pearl sales. Urban density in East Asian cities sustains high-turnover placement.
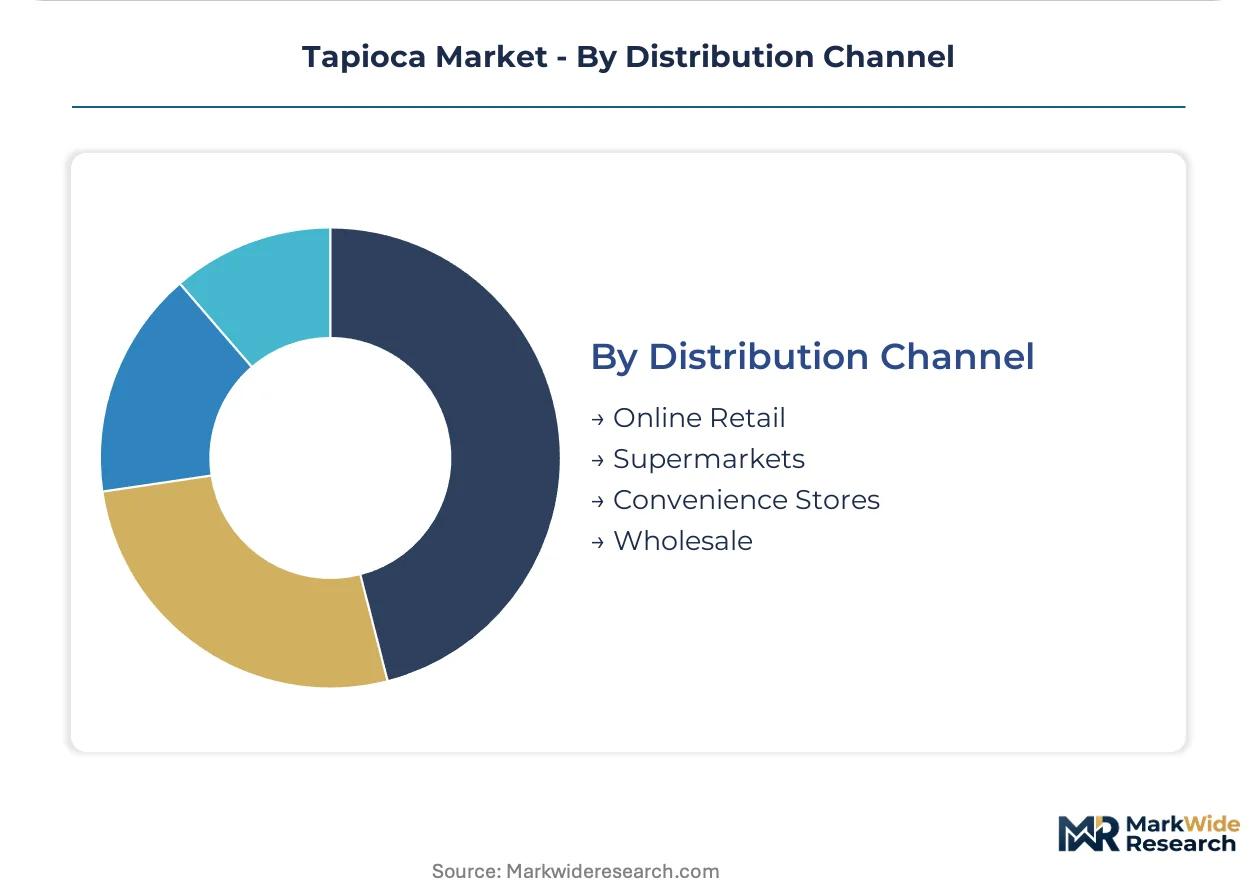
Wholesale retains the dominant flow volume, though Online Retail is climbing the fastest through B2B platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand processes tapioca starch predominantly for export-driven food manufacturing, while Vietnam channels harvests into pearl production for East Asian bubble tea chains, and India diverts increasing volumes toward domestic gluten-free bakery substitution.
Thailand
Bangkok-based food manufacturers source native starch for clean-label sauce formulations bound for European export markets. The Ministry of Agriculture and Cooperatives enforces national Good Agricultural Practice standards that shape farm-level certification timelines. Processing clusters in Nakhon Ratchasima and Kanchanaburi provinces retrofit centrifugal separation lines to meet EU Green Deal batch traceability requirements.
Vietnam
Tay Ninh and Dong Nai provinces supply pearl-grade tapioca to North American bubble tea chains establishing direct-import arrangements. The country lacks equivalent GAP infrastructure to Thailand, forcing exporters to absorb third-party audit costs for ECHA documentation. Ho Chi Minh City logistics hubs coordinate cold-chain container shipments to California and Texas metropolitan markets.
United States
Food service operators in Los Angeles, Dallas, and Houston metropolitan areas drive pearl procurement through captive supply relationships displacing traditional distributors. FDA food additive regulations govern starch import specifications without deforestation-linked due diligence requirements. Modified starch R&D concentrates in Midwestern food technology corridors serving ready meal manufacturers.
India
Maharashtra and Gujarat processors target FSSAI clean-label compliance for domestic gluten-free bakery ingredient sales. The PLI scheme for food processing infrastructure rewards backward integration into cassava farming cooperatives in Karnataka and Andhra Pradesh. Mumbai and Ahmedabad trading houses intermediate between emerging farm clusters and regional food manufacturers.
Germany
REACH framework updates from ECHA require geolocation data for every Southeast Asian farm contributing to processed starch batches. Emsland Group and regional compounders consolidate supplier lists to integrated processors with farm-to-factory traceability systems. Hamburg and Rotterdam port authorities handle documentation verification delays adding testing costs for Asian exporters.
Tapioca Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with Thai and Vietnamese processors controlling upstream farm networks while North American and European firms dominate downstream formulation science. The structure rewards scale in traceability infrastructure and proximity to bubble tea procurement channels. Two archetypes prevail: integrated agricultural processors with captive sourcing and specialty starch technologists with enzymatic modification capabilities. Competitive moves concentrate on backward integration into farming cooperatives and direct-import relationship building with food service chains.
Among Thai-listed processors, PT Budi Starch & Sweetener Tbk and Thai Wah Public Company Limited exemplify the integrated archetype with exposure to both commodity starch and pearl derivative markets. Cargill, Inc. occupies a position bridging agricultural sourcing and North American food manufacturing logistics. Ingredion Incorporated represents the specialty technology vector with modified starch R&D concentration in the Americas and Europe. These three anchors illustrate how competitive positioning splits between upstream farm control and downstream formulation partnerships.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| PT Budi Starch & Sweetener Tbk |
| Ingredion Incorporated |
| Grain Processing Corporation |
| Emsland Group |
| Cargill, Inc. |
| Thai Wah Public Company Limited |
| Bangkok Starch Industrial Co., Ltd. |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Thai starch processors and European food manufacturers lock in supply access while anchoring price visibility against EU Green Deal compliance cost swings. These contracts bundle farm-level certification documentation with volume commitments, insulating buyers from spot-market volatility in Nakhon Ratchasima processing clusters.
Pricing Analysis
Contract-based long-term offtake dominates starch procurement, with premium-mid-economy pricing differentiation driven by EU Green Deal certification grade and volume scale. Cost compression in standard-grade native starch is intensifying because Vietnamese exporters absorb third-party audit costs to compensate for weaker domestic GAP infrastructure. Food service operators show least price sensitivity due to captive supply relationships, while household retail buyers face substitution pressure from corn and potato starches.
Supply Chain Analysis
Thailand and Vietnam anchor global tapioca processing, with Nakhon Ratchasima and Tay Ninh provinces feeding distinct product streams—native starch for European export and pearl-grade material for North American bubble tea chains. Raw material flows draw from cassava root harvests, enzymatic modification inputs, and cold-chain logistics capacity. Single-source vulnerability concentrates in Thai farm networks where skilled labor shortages constrain peak-season throughput. Distribution runs through Ho Chi Minh City and Bangkok logistics hubs coordinating container-scale shipments to California and Texas metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traceability-as-a-service offerings are expanding faster than commodity starch sales, with farm-level audit documentation and batch geolocation emerging as recurring-revenue layers commanding premium attach rates.
For Market Incumbents: Consolidate supplier lists around integrated processors with captive Thai farm networks to defend against REACH documentation cost inflation. Prioritize backward integration into Vietnamese pearl production to capture food service direct-import momentum displacing traditional distributors.
For New Entrants and Emerging Players: FSSAI clean-label certification fast-tracks entry into Indian gluten-free bakery ingredient manufacturing where domestic processing capacity lags demand. Target Maharashtra and Gujarat food manufacturers with certified organic tapioca flour positioned against wheat price volatility.
For Investors and Strategic Acquirers: Capital is best deployed toward enzymatic modification specialists with cold-water swelling IP and established Japanese and South Korean customer relationships. Monitor bubble tea chain procurement consolidation in California and Texas as inflection signal for pearl-grade capacity scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Captive cassava supply secures EU Green Deal traceability compliance for European export contracts. |
| Enzymatic Modification Capacity Expansion | Cold-water swelling variants open formulation possibilities in Japanese ready meal manufacturing. |
| Direct-Import Relationship Building | Food service chains in Texas and California displace traditional distributors with captive supply pipelines. |
| FSSAI Certification Investment | Clean-label compliance unlocks Indian domestic gluten-free bakery ingredient substitution demand. |
| Biodegradable Packaging Film Development | Thermoplastic starch formulations displace petroleum-based films in South Korean flexible packaging. |
Study Parameters
A standing panel of starch procurement managers at European food manufacturers, Thai Ministry of Agriculture certification auditors, Vietnamese pearl processors, and North American bubble tea chain supply chain directors provided ongoing calibration. Primary fieldwork combined structured interviews with customs data from Thai and Vietnamese export authorities, EU REACH documentation filings, and FSSAI registration databases. Secondary validation drew from ECHA guidance updates, SEC filings of listed processors, and trade flow records. Bottom-up farm-level production estimates triangulated against top-down end-use consumption models.
Consistency checks validated volume and value outputs against external benchmarks including regional starch processing capacity disclosures and food service procurement pipeline announcements. The analytical framework segmented by product type, application, end user, and distribution channel across the projection horizon. CAGRs were derived from regression analysis of historical trade flows and elasticity-adjusted demand projections. Industry-specific inputs incorporated EU Green Deal compliance cost buildouts and bubble tea channel expansion rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU deforestation-linked due diligence enforcement and stable Thai-Vietnamese agricultural labor availability; material deviation in either driver would warrant model refresh. Recalibration cycles align with REACH framework updates and FSSAI clean-label standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Beer Adjuncts Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Coconut Derivatives Market
Ingredients
Pea Hull Fiber Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Kairomones Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Baking Ingredients Market
Ingredients
Ximenia Oil Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Corn Oil Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Asparagus Extract Market
Ingredients
Arachidonic Acid Market
Ingredients
Potato Granules Market
Ingredients
Global Distillers Grains Market