
 Global Sodium Starch Glycolate Market | 2026-2036
Global Sodium Starch Glycolate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Starch Glycolate Market Foresight
Specialty pharmaceutical formulators is reorganizing demand away from commodity tablet manufacturers toward high-potency and fixed-dose combination drug producers. BASF SE leverages its backward integration into potato starch supply chains to secure raw material consistency across European and Asian plants. DFE Pharma anchors its position through dedicated excipient R&D facilities in Germany and India. Roquette Frères differentiates via pea-derived starch alternatives that appeal to clean-label and vegan formulation trends.
Sodium starch glycolate is a cross-linked sodium carboxymethyl starch derivative with a degree of substitution typically between 0.2 and 0.4, manufactured through alkaline etherification of starch followed by cross-linking with agents such as phosphorus oxychloride or sodium trimetaphosphate; its primary function is to accelerate tablet disintegration through rapid water uptake and swelling in aqueous media. Cross-linked and powder grades command premium positioning due to superior swelling capacity and batch-to-batch uniformity demanded by high-speed direct compression lines. Tablet disintegrant applications dominate volume offtake, though food additive and stabilizer uses in instant dry mixes represent faster-growing niche outlets with less regulatory friction and shorter qualification cycles.
The US FDA enforces ICH Q3D elemental impurity limits on all excipients intended for oral dosage forms, while the European Medicines Agency applies REACH registration obligations to imported starch derivatives and the EU Medical Device Regulation extends scrutiny to excipients used in drug-device combinations. India's Central Drugs Standard Control Organization mandates excipient testing under Schedule M of the Drugs and Cosmetics Act for domestic pharmaceutical manufacturers. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and JP monographs, as divergence in swelling capacity and pH specifications continues to fragment procurement standards across manufacturing geographies.
Market Dynamics
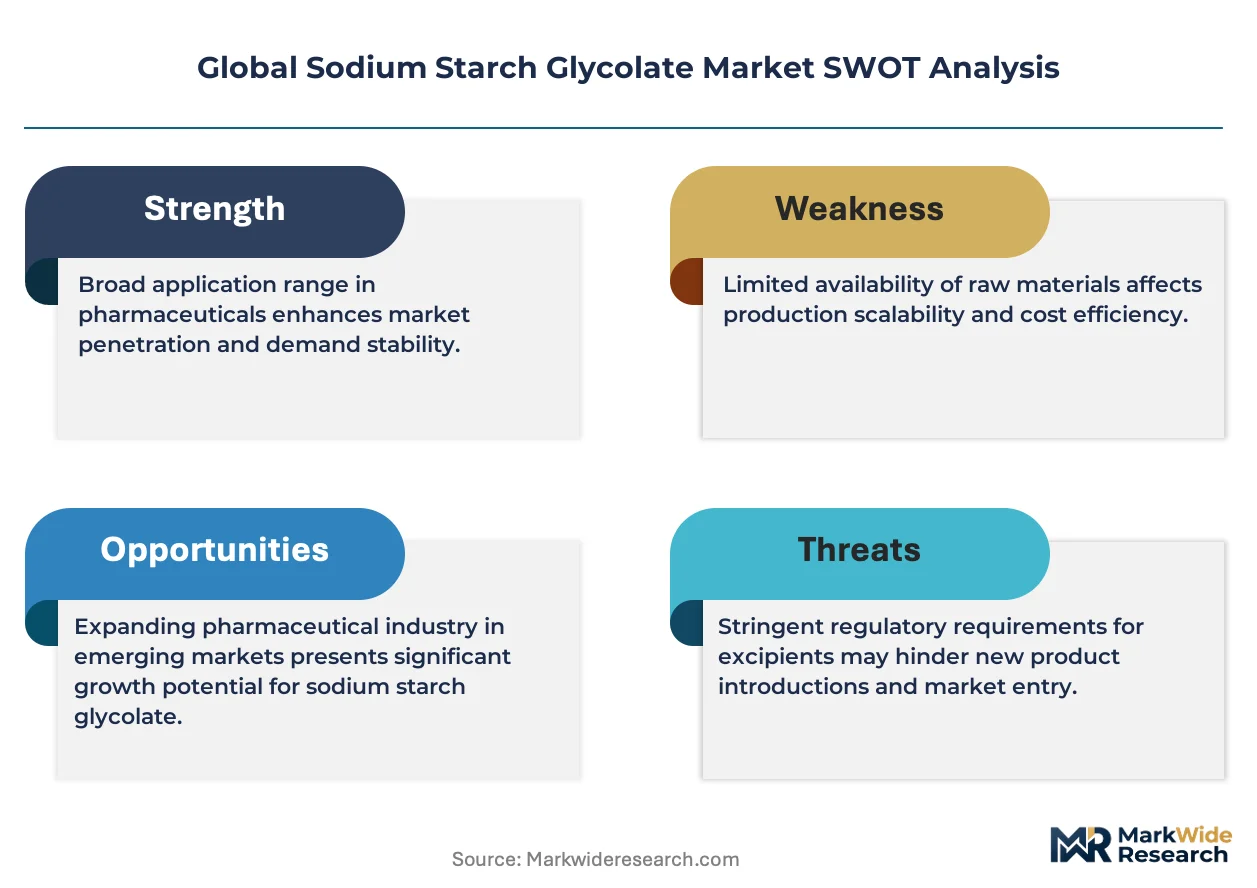
Pharmaceutical formulators are consolidating procurement around excipient suppliers capable of certifying compliance with tightening elemental impurity standards while simultaneously qualifying alternative starch feedstocks for supply security.
Growth Catalysts
- Orally Disintegrating Tablet Demand:Fixed-dose combination and high-potency drug manufacturers are expanding superdisintegrant volumes to achieve sub-30-second disintegration times required for pediatric and geriatric compliance.
- ICH Q3D Implementation:The US FDA's elemental impurity guidelines are forcing formulators to source sodium starch glycolate with validated low-heavy-metal certificates, creating pull for premium cross-linked grades.
- Hyderabad-Ahmedabad Cluster Expansion:India's generic API-to-finished-dose vertical integration is concentrating excipient demand in these manufacturing hubs, with domestic qualification cycles shortening versus imported alternatives.
Market Restraints
- Potato Starch Supply Volatility:Climate-induced yield fluctuations in Northern European growing regions are transmitting price instability to modified starch derivatives.
- Cross-Linked Grade Production Concentration:Pharmaceutical-grade cross-linking capacity remains concentrated among Western European and North American chemical processors, creating geographic supply risk.
- Croscarmellose Sodium Substitution:Formulators facing swelling capacity variability are qualifying croscarmellose sodium as a direct functional replacement in direct compression applications.
Strategic Opportunities
- Pea Starch Feedstock Diversification:Non-GMO and vegan certification trends are opening formulation specification windows for pea-derived sodium starch glycolate in nutraceutical and clean-label pharmaceutical segments.
- Instant Dry Mix Food Applications:Stabilizer demand in convenience food manufacturing represents a lower-regulatory-friction outlet with faster customer qualification timelines than pharmaceutical channels.
- CDSCO Schedule M Alignment:India's domestic excipient testing mandates are incentivizing local production investments that can bypass import documentation burdens for subcontinent formulators.
Industry Challenges
- Pharmacopeial Harmonization Gaps:Divergent swelling capacity and pH specifications between USP-NF, EP, and JP monographs are forcing manufacturers to maintain multiple product grades for geographic market access.
- Cross-Contamination Control:High-potency drug manufacturing requires dedicated superdisintegrant production lines, elevating capital intensity for excipient suppliers serving oncology and hormone therapy formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Starch Glycolate Market |
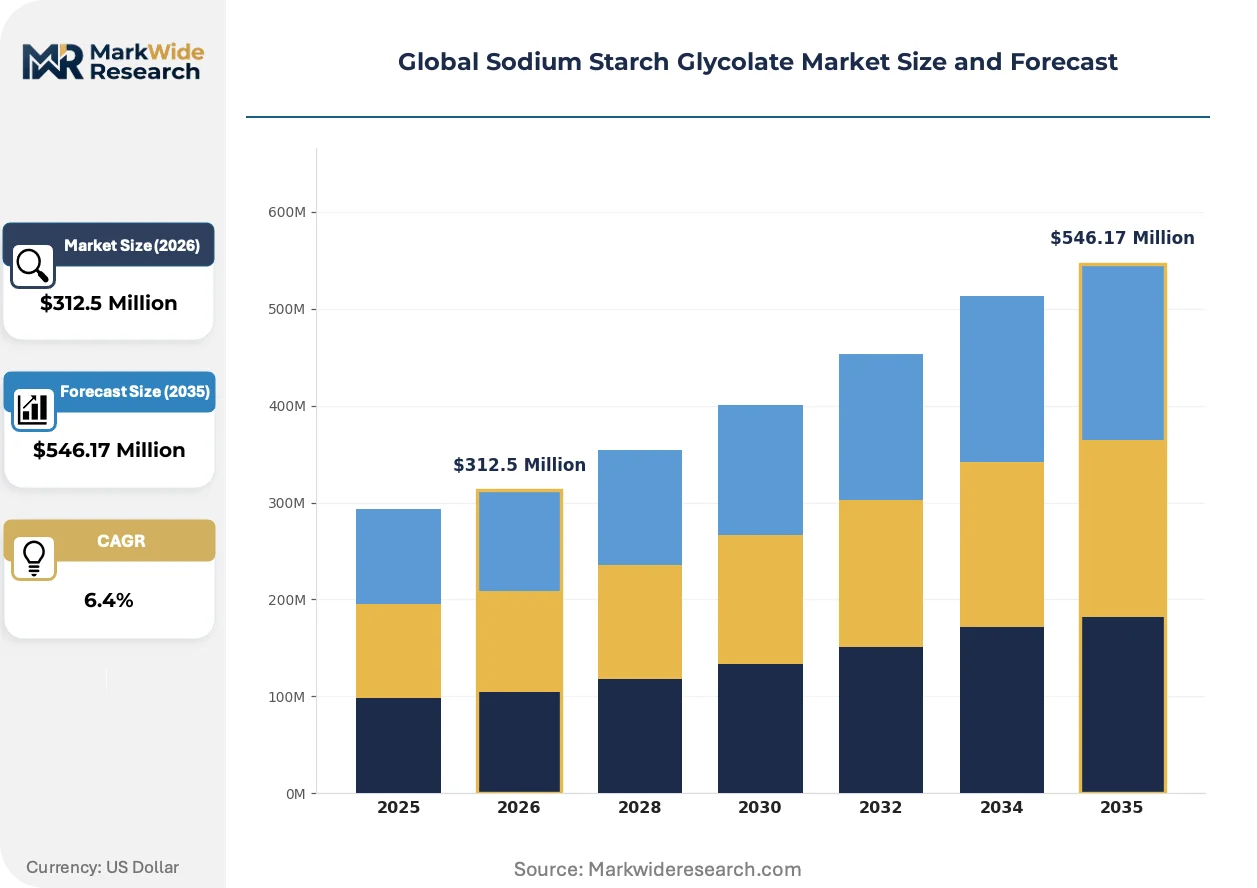
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
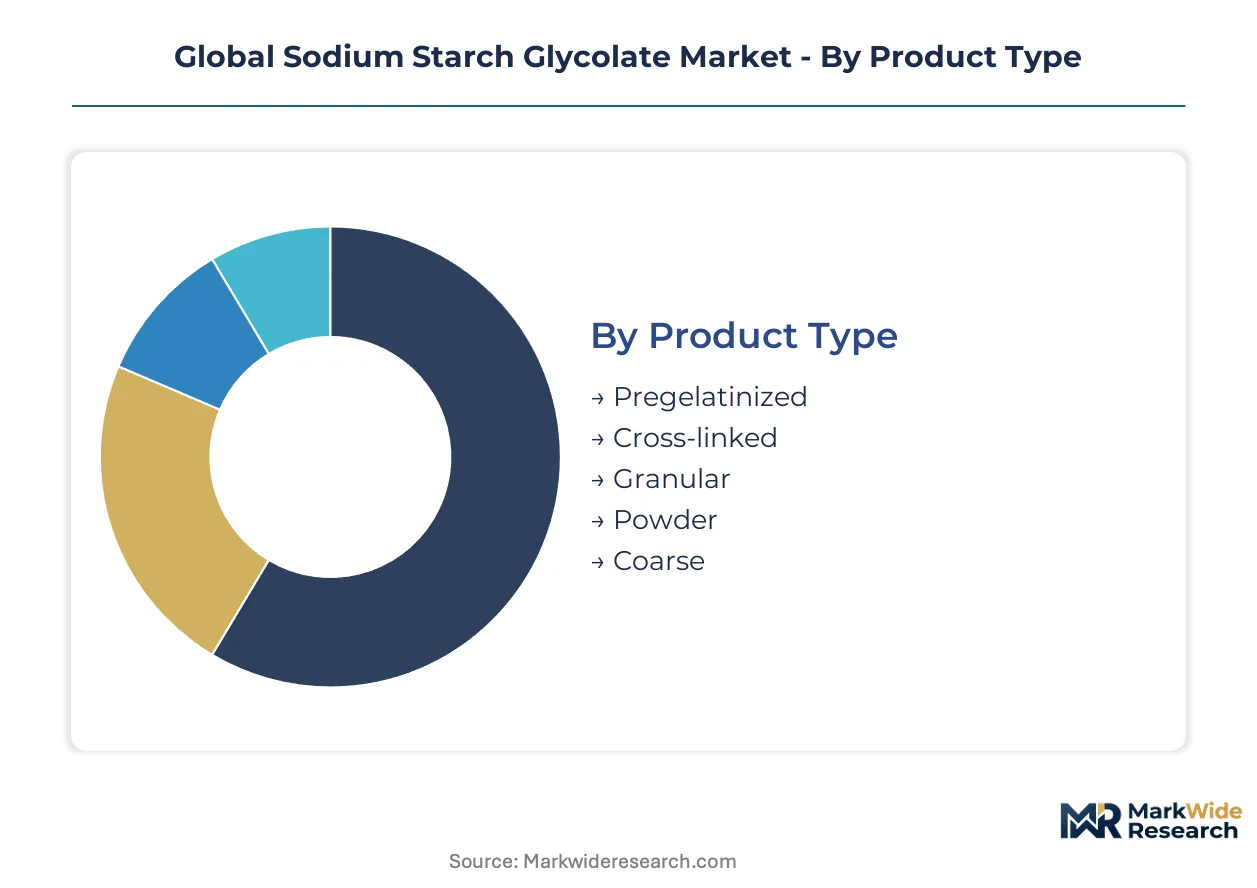
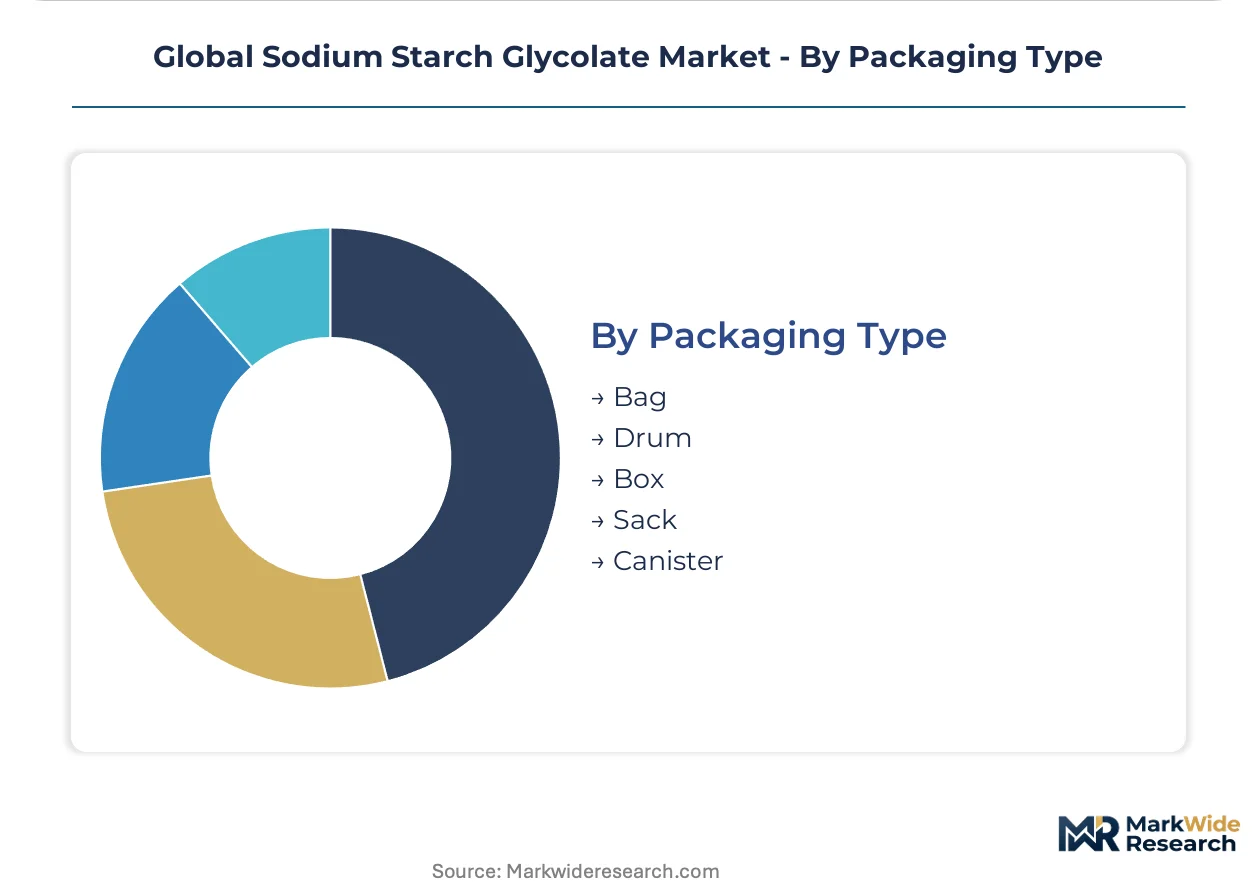
| Segmentation | Product Type: Pregelatinized, Cross-linked, Granular, Powder, Coarse Application: Tablet Disintegrant, Capsule Disintegrant, Adhesive Agent, Stabilizer, Food Additive End User Industry: Pharmaceutical, Nutraceutical, Cosmetic, Agrochemical, Textile Packaging Type: Bag, Drum, Box, Sack, Canister |
| Companies Covered | BASF SE, Ashland Global Holdings, DFE Pharma, Spectrum Chemical Manufacturing Corp., Merck KGaA, Roquette Frères, Colorcon, Shreeji Pharma International, JRS Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Starch Glycolate Market Shifts & Advancements
Superdisintegrant technology is bifurcating between high-performance cross-linked grades for regulated pharmaceuticals and cost-optimized powder grades for food and nutraceutical applications.
Cross-linked sodium starch glycolate is miniaturizing particle size distributions to sub-50-micron specifications that enable uniform dispersion in high-speed direct compression lines. Contract manufacturing organizations serving North American generic sponsors are adopting these micronized grades to eliminate blend segregation risks in fixed-dose combinations. The technology is miniaturizing equipment footprints and compression force requirements, allowing tablet press throughput gains of 15-20% without capital expansion.
REACH registration obligations for imported starch derivatives are compelling non-European suppliers to establish EU-based repackaging and testing facilities. The European Chemicals Agency's extended safety data sheet requirements are lengthening qualification timelines for new excipient sources. High-volume oral solid dose manufacturers in Germany and the Netherlands are responding by locking in multi-year supply agreements with REACH-registered European producers.
Formulator buying committees are consolidating excipient supplier panels from 12-15 vendors to 3-5 strategic partners capable of delivering integrated regulatory documentation packages. This vendor consolidation is compressing qualification cycles for new product introductions while elevating technical service expectations. The shift is most pronounced among mid-sized generic sponsors in India and Eastern Europe seeking to accelerate ANDA submission timelines.
Global Sodium Starch Glycolate Market Segmentation
Product differentiation in sodium starch glycolate hinges on swelling capacity specifications and cross-linking density, which determine suitability for high-speed pharmaceutical lines versus cost-sensitive food applications. Procurement committees weight pharmacopeial compliance against unit economics when segmenting supplier portfolios.
Product Type:
Cross-linked and pregelatinized grades capture the deepest margin pools due to pharmaceutical certification requirements and batch-to-batch uniformity premiums.
- Cross-linked:Manufactured through phosphorus oxychloride or sodium trimetaphosphate cross-linking to achieve controlled swelling kinetics. Hyderabad and Ahmedabad generic manufacturers are consolidating procurement around cross-linked grades to meet US FDA ICH Q3D elemental impurity certificates for export-bound formulations.
- Pregelatinized:Cold-water-soluble starch derivative produced via drum drying or extrusion cooking. Nutraceutical formulators in Germany and the Netherlands are adopting pregelatinized grades for instant drink mixes where rapid hydration without heating accelerates production cycles.
- Granular:Free-flowing agglomerated particles optimized for direct compression tableting.
- Powder:Fine-milled specification serving cost-optimized food stabilizer applications.
- Coarse:Larger particle size distribution for controlled-release matrix formulations.
Cross-linked holds installed capacity. Pregelatinized is rotating up the share rankings.
Application:
Tablet disintegrant applications command volume leadership, though food additive and stabilizer uses are climbing the fastest.
- Tablet Disintegrant:Primary superdisintegrant function enabling sub-30-second disintegration through rapid water uptake and swelling. Fixed-dose combination manufacturers in India are expanding offtake to achieve pediatric and geriatric compliance targets.
- Stabilizer:Viscosity control and moisture retention in instant dry mixes. Convenience food processors in the United States qualify stabilizer grades under shorter timelines than pharmaceutical channels, bypassing lengthy drug master file documentation.
- Capsule Disintegrant:Hard gelatin and HPMC capsule applications requiring controlled swelling rates.
- Adhesive Agent:Binder functionality in wet granulation processes.
- Food Additive:Clean-label starch modification for texture modification.
Tablet disintegrant dominates current procurement volumes. Stabilizer is expanding most quickly in customer qualification pipelines.
End User Industry:
Pharmaceutical buyers concentrate purchasing power, while nutraceutical demand is gaining share fastest.
- Pharmaceutical:Oral solid dose manufacturers requiring USP-NF, EP, and JP pharmacopeial compliance. CDSCO Schedule M testing mandates in India are shortening domestic qualification cycles versus imported alternatives.
- Nutraceutical:Clean-label and vegan certification trends opening specification windows. Pea-derived sodium starch glycolate is penetrating this segment as Roquette Frères and specialty suppliers promote non-GMO feedstock alternatives.
- Cosmetic:Thickening and stabilizing applications in topical formulations.
- Agrochemical:Granule disintegration aids for controlled-release fertilizer coatings.
- Textile:Sizing agent functionality in yarn processing.
Pharmaceutical maintains the deepest supplier relationships. Nutraceutical is rotating up the share rankings.
Packaging Type:
Drum and bag formats split procurement based on volume scale and contamination control requirements.
- Drum:Steel and fiber drum configurations for pharmaceutical-grade material requiring dedicated handling protocols. High-potency drug manufacturers mandate drum packaging to prevent cross-contamination in oncology and hormone therapy production environments.
- Bag:Multi-wall paper and woven polypropylene for food-grade and industrial applications. Instant dry mix manufacturers in North America prefer bag packaging for automated ingredient handling systems.
- Box:Corrugated fiberboard for retail-scale nutraceutical distribution.
- Sack:Bulk flexible intermediate bulk container formats for agrochemical and textile processors.
- Canister:Rigid plastic containers for laboratory and R&D sampling quantities.
Drum holds installed capacity for pharmaceutical certification. Bag is rotating up the share rankings in food applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports pharmaceutical-grade sodium starch glycolate to Indian generic manufacturers, while the Netherlands serves as a distribution hub for REACH-registered starch derivatives entering European formulation plants.
United States
FDA's ICH Q3D enforcement drives demand for certified low-heavy-metal grades among generic sponsors in New Jersey and North Carolina. The agency's elemental impurity guidelines force formulators to validate excipient certificates for ANDA submissions. High-volume tablet manufacturers around Raleigh-Durham consolidate procurement around suppliers delivering integrated regulatory documentation packages.
Germany
REACH registration obligations for imported starch derivatives compel domestic formulators to source from ECHA-registered European producers. The country's pharmaceutical excipient R&D facilities anchor backward integration into potato starch supply chains. Chemical processors in Ludwigshafen and Frankfurt maintain cross-linking capacity for pharmaceutical-grade specifications demanded by export markets.
India
CDSCO Schedule M testing mandates under the Drugs and Cosmetics Act shorten domestic qualification cycles versus imported alternatives. The Central Drugs Standard Control Organization requires excipient testing for manufacturers in Hyderabad and Ahmedabad. These clusters concentrate generic API-to-finished-dose vertical integration, pulling sodium starch glycolate demand toward local suppliers.
Netherlands
EMA's extended safety data sheet requirements lengthen qualification timelines for new excipient sources entering European markets. The country's Rotterdam port infrastructure supports REACH-registered repackaging facilities for Asian starch derivative imports. Oral solid dose manufacturers in Oss and Groningen lock in multi-year supply agreements with registered producers to bypass documentation burdens.
France
ANSM oversight of drug-device combinations extends scrutiny to excipients used in combination products. The regulator's pharmacopeial alignment with EP monographs influences swelling capacity specifications for domestic formulators. Pea-derived starch alternatives from Roquette Frères in Lestrem penetrate nutraceutical segments seeking vegan certification.
Global Sodium Starch Glycolate Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and feedstock control. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive starch supply, dedicated excipient specialists with pharmacopeial focus, and regional distributors serving cost-optimized food applications. Strategic moves center on REACH registration completion for European market access and micronization capacity expansion for high-speed direct compression lines.
Within the multinational tier, BASF SE and Merck KGaA exemplify integrated players with backward control over raw material consistency. DFE Pharma occupies a position among dedicated excipient specialists with dual-continent R&D infrastructure. These three anchors represent divergent approaches to regulatory documentation depth and geographic manufacturing footprint.
| Leading Market Players |
|---|
| BASF SE |
| Ashland Global Holdings |
| DFE Pharma |
| Spectrum Chemical Manufacturing Corp. |
| Merck KGaA |
| Roquette Frères |
| Colorcon |
| Shreeji Pharma International |
| JRS Pharma |
| Others |
Supply & Pricing Matrix
Croscarmellose sodium substitution in direct compression applications simultaneously redraws supply geography toward cellulose derivative producers and compresses pricing premiums for commodity-grade sodium starch glycolate. Formulators qualifying alternative superdisintegrants force starch-based suppliers to defend cross-linked grade positioning through ICH Q3D certification investments that widen price spreads against powder grades.
Pricing Analysis
Cross-linked pharmaceutical grades command substantial premiums over pregelatinized and powder specifications due to batch-to-batch uniformity requirements for high-speed direct compression lines. Pricing stratifies across pharmaceutical-certified, food-grade, and industrial tiers, with elemental impurity testing costs driving differentiation between export-bound and domestic Indian supply. Cost compression in standard powder grades is intensifying because potato starch feedstock volatility transmits from Northern European growing regions. Generic sponsors in Hyderabad exhibit highest price sensitivity, while oncology formulators in Germany accept premiums for dedicated production line guarantees.
Supply Chain Analysis
Phosphorus oxychloride cross-linking capacity concentration in Germany, the Netherlands, and the United States creates a chokepoint that limits pharmaceutical-grade supply responsiveness. Raw material flows draw from potato starch processing in Northern Europe, pea starch cultivation in France, and tapioca derivatives in Southeast Asia. Single-source vulnerability runs through REACH-registered European repackaging facilities that handle Asian starch derivative imports. Distribution runs through drum-format pharmaceutical channels for high-potency applications and bag-format food-grade logistics for instant dry mix processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate croscarmellose sodium substitution threats that erode market share in direct compression segments unless countered by micronization technology investments and regulatory certification depth.
For Market Incumbents: Secure backward integration into pea starch supply chains to diversify feedstock exposure beyond potato-derived volatility. Anchor cross-linked grade positioning through dedicated production line investments that serve oncology and hormone therapy formulators requiring contamination control protocols. Certification depth in ICH Q3D elemental impurity testing represents the critical defensive lever against cellulose-based substitute penetration. For New Entrants and Emerging Players: Regulatory documentation service gaps among mid-sized Indian generic sponsors create white-space opportunities for suppliers offering integrated ANDA submission packages. Target food-grade stabilizer applications in North American instant dry mix manufacturing where qualification timelines compress versus pharmaceutical channels. Pea-derived non-GMO certification provides the most penetrable positioning angle against established potato starch incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors excipient specialists with dual-continent manufacturing footprints and REACH registration completion. Long-term viability across the analysis window hinges on micronization capacity scale and pharmacopeial harmonization adaptability. The signal to watch is CDSCO Schedule M enforcement intensity that accelerates domestic Indian production investments.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | ECHA compliance unlocks European market access for Asian starch derivative suppliers. |
| Micronization Capacity Expansion | Sub-50-micron specifications enable high-speed direct compression line qualification. |
| Pea Starch Feedstock Diversification | Non-GMO certification captures nutraceutical clean-label specification windows. |
| Integrated Regulatory Documentation | Consolidated supplier panels compress ANDA submission timelines for generic sponsors. |
| Dedicated Production Line Investment | Cross-contamination control serves high-potency oncology and hormone therapy formulators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA drug master files, EMA scientific advice letters, USP-NF monograph revisions, and Indian customs import data for starch derivatives. Primary interviews engaged pharmaceutical formulation scientists, excipient procurement managers at generic sponsors, CDSCO regulatory affairs consultants, and potato starch processing plant operators. Bottom-up volume estimates from application-specific consumption rates triangulate against top-down value projections derived from trade flow analysis and pharmacopeial grade pricing spreads.
Segmentation dimensions modeled include product type hierarchy, application function, end-user industry vertical, packaging format requirements, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand projections across the modeling period, incorporating ICH Q3D implementation timelines and CDSCO Schedule M enforcement trajectories. Forecast inputs integrated Hyderabad-Ahmedabad cluster expansion rates, REACH registration completion schedules, and pea starch feedstock adoption curves in nutraceutical channels.
Underlying assumptions cover sustained ICH Q3D enforcement intensity, stable potato starch yield patterns in Northern Europe, and continued croscarmellose sodium substitution pressure in direct compression segments, with deviation risk concentrated in climate-induced feedstock volatility and pharmacopeial specification divergence between USP-NF and EP monographs. Practitioners should keep alternative scenarios live as CDSCO domestic testing mandate expansion and EMA drug-device combination scrutiny evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Russia Food Enzymes Market