
 North America Food Emulsifiers Market | 2026-2036
North America Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Emulsifiers Market Analytics
Asset-light toll manufacturing partnerships is rewriting competitive entry dynamics for mid-sized emulsifier suppliers across North America. Corbion N.V. leverages its fermentation-derived portfolio to anchor sustainable positioning in lecithin alternatives. Kerry Group PLC sustains formulation integration services that extend beyond commodity supply into co-development relationships with food manufacturers. Cargill, Incorporated controls integrated oilseed processing that secures backward supply security for its emulsifier operations.
Food emulsifiers are surface-active compounds with hydrophilic-lipophilic balance values typically between 3 and 16, designed to stabilize heterogeneous mixtures by reducing interfacial tension between immiscible phases such as oil and water. These agents functionally prevent phase separation, control crystallization, and modify rheological properties in processed foods ranging from shelf-stable dressings to aerated confectionery. Lecithin dominates volume flows due to its broad regulatory acceptance and cost-efficient sourcing from soy and sunflower streams, though monoglycerides command premium positioning in clean-label bakery segments where partial hydrogenation restrictions have eliminated legacy alternatives. Polysorbates retain defensive demand in industrial-scale beverage emulsions where thermal stability requirements exclude natural alternatives, while diglycerides compete in dairy applications through fat-sparing and texture-modification claims.
The FDA governs emulsifier safety through GRAS self-affirmation and food additive petition pathways, while Health Canada evaluates novel emulsifiers under its Food Directorate's amendment process for food additive tables. Mexico's national health regulator applies NOM standards that increasingly reference Codex Alimentarius specifications for emulsifier usage levels and labeling declarations. Stakeholders must monitor how evolving clean-label definitions across these three jurisdictions reshape acceptable ingredient lists and reformulation timelines.
Market Dynamics
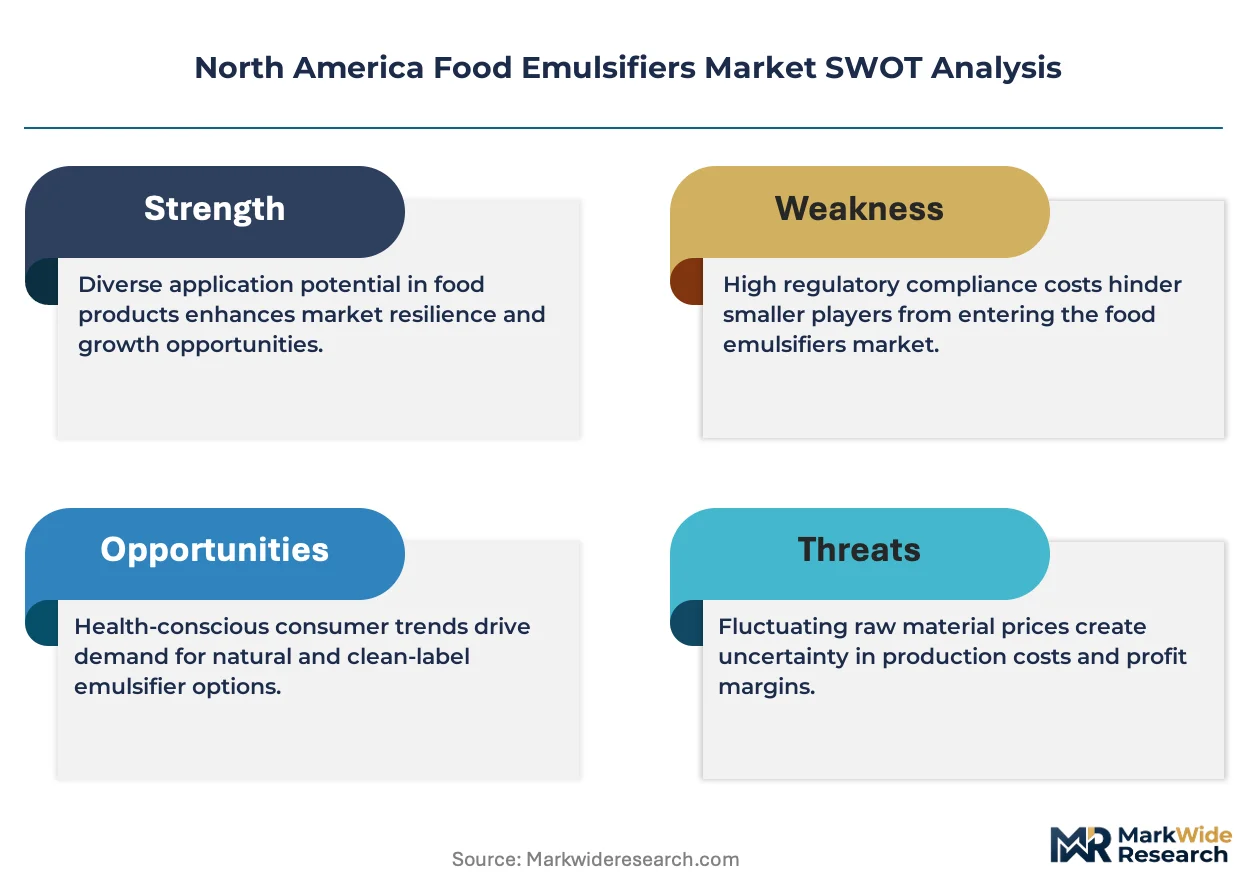
The FDA's updated GRAS notification framework is forcing mid-sized suppliers toward toll manufacturing partnerships while California's plant-based food corridor and Mexico's processed dairy sector pull demand in divergent formulation directions.
Growth Catalysts
- Clean-label bakery reformulation:Partial hydrogenation restrictions across the U.S. and Canada eliminate legacy emulsifiers, creating immediate substitution demand for monoglycerides and lecithin alternatives in shelf-stable baked goods.
- Mexico's dairy processing expansion:NOM standards referencing Codex Alimentarius specifications accelerate diglyceride adoption for fat-sparing and texture-modification claims in cheese and cream applications.
- Fermentation-derived lecithin:Advanced bioprocessing platforms reduce dependency on soy and sunflower agricultural cycles, offering supply security for manufacturers facing climate-driven crop volatility.
Market Restraints
- Sunflower lecithin supply concentration:Ukraine and Argentina dominate raw sunflower seed flows, exposing North American processors to geopolitical disruption and price spikes.
- Polysorbate thermal stability lock-in:Industrial beverage emulsions require heat-resistant synthetic emulsifiers where natural alternatives fail, constraining clean-label migration in high-volume categories.
- Health Canada's Food Directorate amendment timelines:Novel emulsifier approvals extend 18-24 months, delaying product launches and freezing R&D investment cycles.
Strategic Opportunities
- California plant-based meat corridor:Oakland and Los Angeles manufacturing clusters seek customized emulsifier blends for fat-mimicry in alternative proteins, opening co-development service contracts.
- Outcome-based formulation partnerships:Food manufacturers now contract for finished product performance rather than ingredient supply, enabling margin capture through technical service bundling.
- Mexico's NOM-Codex harmonization:Regulatory alignment with international standards reduces dual-compliance costs for exporters serving both domestic and U.S. Hispanic markets.
Industry Challenges
- Emulsifier-food protein interaction modeling:Formulation chemists capable of predicting HLB-protein binding behavior remain scarce, extending development cycles for novel applications.
- GRAS self-affirmation documentation:FDA's intensified scrutiny of safety data packages demands expanded toxicology studies, raising compliance costs for smaller ingredient suppliers.
- Legacy equipment retrofitting:Existing spray-drying and extrusion infrastructure requires modification to handle hygroscopic natural emulsifiers with different flow properties than synthetic predecessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Emulsifiers Market |
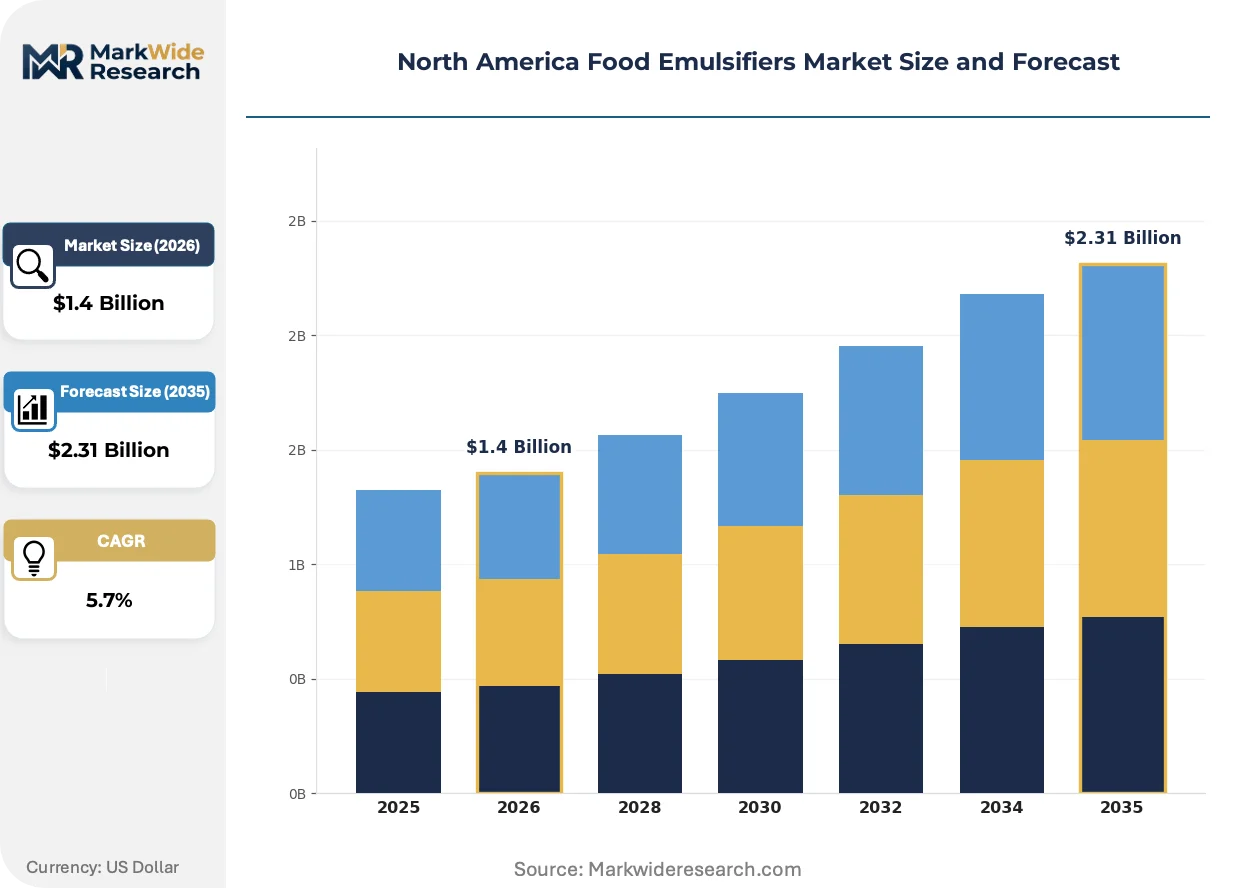
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
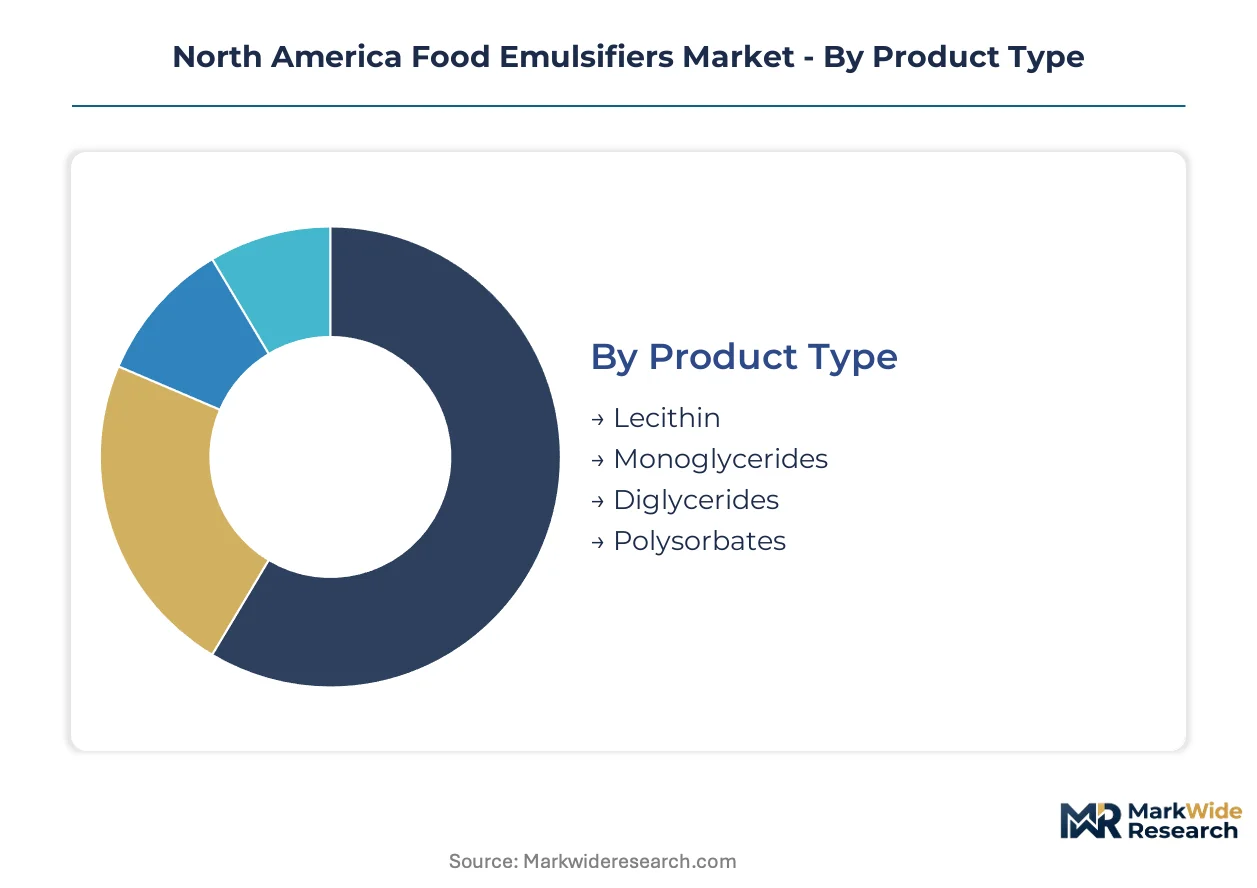
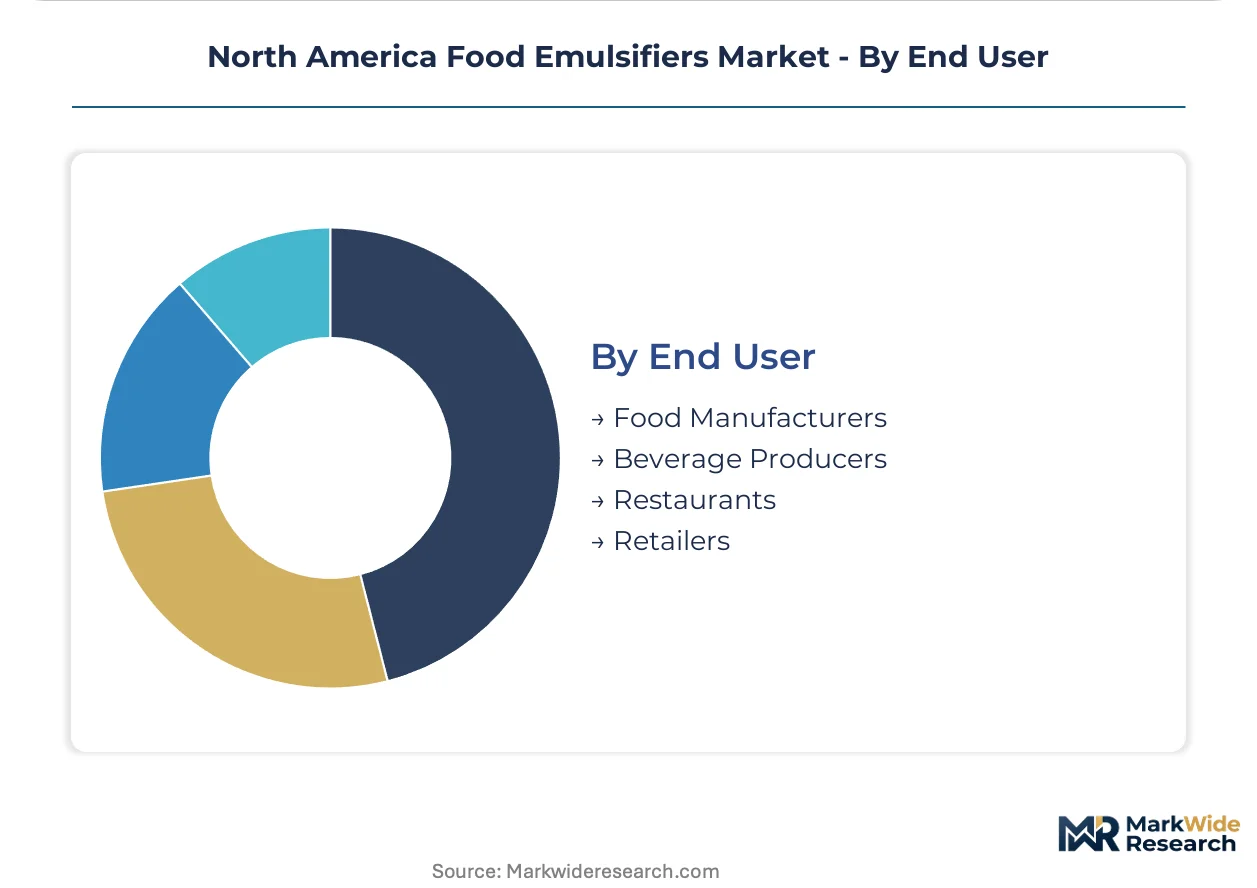
| Segmentation | Product Type: Lecithin, Monoglycerides, Diglycerides, Polysorbates Application: Baked Goods, Dairy Products, Sauces, Beverages Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Beverage Producers, Restaurants, Retailers |
| Companies Covered | Corbion N.V., Kerry Group PLC, Archer Daniels Midland Company, Palsgaard A/S, Ingredion Incorporated, Cargill, Incorporated, Tate & Lyle PLC, Stepan Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Emulsifiers Market Evolving Landscape
Digital process control, regulatory transparency mandates, and buyer-side technical service expectations are converging to reshape how emulsifier suppliers compete beyond commodity pricing.
Enzymatic interesterification is digitizing production scheduling and yield optimization across North American monoglyceride facilities. Bakery and confectionery manufacturers now demand batch-level traceability data, compelling suppliers to deploy sensor networks that feed real-time HLB consistency metrics directly into customer ERP systems. This infrastructure investment is compressing price competition among commodity producers while rewarding technical service capabilities.
Health Canada's mandatory front-of-package labeling regulations for foods high in saturated fat, sugars, or sodium are accelerating reformulation timelines. Emulsifier suppliers must now deliver fat-reduction solutions that maintain mouthfeel without triggering warning labels, pushing R&D toward diglyceride and structured lipid systems. Quebec and Ontario food processors face the tightest compliance windows, driving concentrated demand for rapid formulation support.
Buyers now unbundle ingredient supply from technical service, contracting emulsifier performance by finished-product specification rather than input quantity. Large meat alternatives manufacturers in California and Texas negotiate outcome-based agreements where suppliers bear formulation risk for texture stability across shelf life. This procurement model shift favors integrated players with pilot-scale testing capabilities and regulatory dossier expertise over pure commodity traders.
North America Food Emulsifiers Market Segmentation
Emulsifier purchasing across North America fragments sharply across formulation requirements, with California plant-based meat processors and Mexico's dairy cooperatives demanding incompatible technical specifications from the same supplier base. Segmentation discipline reveals where margin pools concentrate and which product forms justify dedicated production assets.
Product Type:
Cost tier determines sourcing strategy for emulsifier procurement, with natural-derived options commanding premiums against synthetic alternatives that retain defensive positions in heat-stressed applications.
- Lecithin:Phospholipid mixtures extracted from soy and sunflower oilseeds dominate volume flows through cost-efficient supply chains. California's plant-based meat corridor pulls concentrated demand for non-GMO and organic-certified grades as clean-label requirements harden.
- Monoglycerides:Glycerol esters of fatty acids synthesized through glycerolysis or direct esterification anchor bakery reformulation efforts. Partial hydrogenation restrictions across the U.S. and Canada have eliminated legacy emulsifier options, accelerating substitution demand for shelf-stable baked goods.
- Diglycerides:Partial glycerides deliver fat-sparing functionality in processed cheese and cream applications. Mexico's expanding dairy sector under NOM standards referencing Codex Alimentarius specifications drives adoption for texture-modification claims.
- Polysorbates:Ethoxylated sorbitan esters retain lock-in demand where thermal stability requirements exclude natural alternatives. Industrial-scale beverage emulsions in Texas and Florida manufacturing clusters depend on these synthetic agents for shelf-stable flavor systems.
Lecithin holds installed capacity. Monoglycerides is rotating up the share rankings.
Application:
End-use application dictates HLB specification requirements and regulatory compliance burdens, with bakery and dairy pulling divergent formulation investments from shared supplier technical service teams.
- Baked Goods:Aeration stability and crumb softening requirements demand precise emulsifier selection for extended shelf life. Health Canada's front-of-package labeling regulations for high saturated fat content are accelerating reformulation timelines in Quebec and Ontario processing facilities.
- Dairy Products:Fat globule stabilization and texture modification in ice cream, cheese, and cream applications require tailored HLB values. Mexico's processed dairy sector expansion under harmonized NOM-Codex standards reduces dual-compliance costs for cross-border suppliers.
- Sauces:Oil-in-water emulsion stability for mayonnaise and dressing applications depends on lecithin and monoglyceride blends. FDA GRAS notification scrutiny has extended safety documentation requirements for novel emulsifier introductions in shelf-stable categories.
- Beverages:Flavor oil emulsification and cloud stability in citrus and dairy-based drinks require heat-resistant synthetic options. California and Florida beverage manufacturing clusters face clean-label migration constraints where polysorbate thermal performance remains unmatched by natural alternatives.
Baked goods maintains formulation service intensity. Dairy products is gaining share fastest through Mexico's capacity expansion.
Form:
Physical form selection determines handling infrastructure requirements, with powder and liquid formats commanding distinct supply chain investments and customer equipment compatibility constraints.
- Liquid:Pumpable emulsifier concentrates reduce dust exposure and simplify metering in continuous processing lines. High-volume bakery and beverage manufacturers in the U.S. Midwest prefer liquid delivery for automated dosing systems.
- Powder:Spray-dried emulsifiers enable extended shelf stability and reduced shipping weights for distributed manufacturing networks. Hygroscopic properties of natural-derived powders require modified handling protocols versus synthetic predecessors.
- Granular:Free-flowing particulate forms bridge dissolution speed and dust control for mid-scale food manufacturers. Mexican dairy processors favor granular lecithin for cheese production flexibility.
- Paste:Semi-solid emulsifier preparations suit small-batch artisan bakery and restaurant applications requiring manual incorporation. Limited scale constrains supplier margin capture in this format tier.
Liquid holds installed capacity. Powder is rotating up the share rankings.
End User:
Customer type stratifies procurement power and technical service expectations, with large food manufacturers unbundling ingredient supply from formulation support while smaller accounts remain price-sensitive.
- Food Manufacturers:Integrated processors of baked goods, dairy, and prepared foods negotiate outcome-based contracts where suppliers bear shelf-life stability risk. California and Texas meat alternative manufacturers demand co-development relationships with pilot-scale testing capabilities.
- Beverage Producers:Flavor houses and ready-to-drink bottlers prioritize thermal stability and batch-to-batch consistency for cloud and emulsion performance. Health Canada's Food Directorate amendment timelines delay novel emulsifier approvals, freezing R&D cycles for reformulation projects.
- Restaurants:Foodservice distributors and chain operators source emulsifier blends through broadline suppliers with limited technical specification negotiation. Volume concentration in national accounts compresses margin capture for specialty grades.
- Retailers:Private-label food product development teams at grocery chains increasingly specify clean-label emulsifier requirements for supplier compliance. FDA's intensified GRAS self-affirmation documentation demands raise barriers for smaller ingredient suppliers serving this channel.
Food manufacturers holds installed capacity. Beverage producers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's intensified GRAS notification scrutiny is redirecting supplier investment toward Canada and Mexico while California's plant-based manufacturing corridor and Mexico's dairy processing expansion pull demand in divergent technical directions.
United States
California's Oakland-Los Angeles plant-based meat cluster demands customized emulsifier blends for fat-mimicry applications in alternative proteins. FDA's updated GRAS framework extends safety documentation timelines for novel emulsifier introductions. Texas and Florida beverage manufacturing clusters retain synthetic emulsifier dependence where thermal stability requirements exclude natural alternatives.
Canada
Quebec and Ontario food processors face compressed reformulation timelines under Health Canada's front-of-package labeling regulations for high saturated fat content. Health Canada's Food Directorate amendment process extends 18-24 months for novel emulsifier approvals. Prairie provinces' canola processing infrastructure supports domestic lecithin supply chains for bakery and confectionery applications.
Mexico
Expanding processed dairy capacity in Nuevo León and Jalisco accelerates diglyceride adoption for fat-sparing and texture-modification claims in cheese and cream. NOM standards increasingly reference Codex Alimentarius specifications, reducing dual-compliance costs for cross-border suppliers. Bajío Region dairy cooperatives drive concentrated demand for granular lecithin in cheese production flexibility.
North America Food Emulsifiers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation service tiers. The supplier base organizes around integrated oilseed processors, fermentation-derived specialists, and technical service bundlers. Three archetypes dominate: backward-integrated agricultural processors securing captive raw material flows, bioprocessing platforms leveraging fermentation for supply security, and formulation integrators capturing margin through co-development relationships. Competitive moves concentrate on toll manufacturing partnerships and outcome-based contracting models.
Among Netherlands-based specialists, Corbion N.V. exemplifies the fermentation-derived platform archetype for sustainable lecithin alternatives. Ireland-based Kerry Group PLC occupies a position within the formulation integration tier, bundling technical services beyond commodity supply. Cargill, Incorporated anchors the backward-integrated processor archetype with oilseed processing infrastructure securing supply chain control. These three representations illustrate how geographic and technological positioning stratify competitive access across the region's divergent demand clusters.
| Leading Market Players |
|---|
| Corbion N.V. |
| Kerry Group PLC |
| Archer Daniels Midland Company |
| Palsgaard A/S |
| Ingredion Incorporated |
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Stepan Company |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Undercapacity in California's plant-based emulsifier blending facilities is pushing contract manufacturers toward extended lead times and selective customer acceptance, tightening pricing discipline across the premium tier while forcing mid-market buyers toward toll-manufacturing partnerships with less favorable terms.
Pricing Analysis
Certification level creates the primary spread across the North American food emulsifiers market, with FDA GRAS-notified grades commanding substantial premiums over self-affirmed alternatives and organic-certified lecithin separating further from conventional soy-derived baselines. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label intensity, volume scale, and technical service bundling rather than commodity feedstock costs alone. Cost compression in the standard tier is intensifying because sunflower lecithin supply volatility from Ukraine-Argentina concentration has compressed margins for non-integrated processors. Small-scale artisan bakeries and regional dairy cooperatives exhibit the highest price sensitivity, while California meat-alternative manufacturers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from large food manufacturers are squeezing working capital across mid-tier emulsifier suppliers, accelerating consolidation toward backward-integrated players with balance-sheet depth. Raw material flows concentrate in Argentina and Ukraine for sunflower seed, the U.S. Midwest for soy crush, and Brazil for sustainable soy certification programs. Manufacturing capacity clusters in Illinois, California, and Nuevo León feed from these agricultural inputs through solvent extraction and enzymatic interesterification pathways. Single-source vulnerability in Black Sea sunflower flows exposes processors to geopolitical disruption and price spikes. Distribution runs through integrated oilseed processors with captive logistics networks, supplemented by regional toll manufacturers serving formulation-integrated customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of formulation chemists capable of predicting HLB-protein binding behavior is constraining product development cycles and concentrating technical service capabilities among integrated players, creating durable competitive moats for incumbents with pilot-scale testing infrastructure.
For Market Incumbents: Insulate margin position by deepening backward integration into non-GMO and organic oilseed crush capacity in the U.S. Midwest and Prairie provinces, securing captive supply as sunflower lecithin volatility persists. Accelerate certification investment for FDA GRAS notification dossiers to extend regulatory moats against self-affirmed competitors. Prioritize co-development relationship lock-in with California meat-alternative manufacturers through outcome-based contracting that transfers shelf-life stability risk from buyer to supplier. For New Entrants and Emerging Players: Pursue toll manufacturing partnerships with underutilized enzymatic interesterification facilities in the U.S. Southeast, accessing installed capacity without capital-intensive greenfield investment. Target Mexico's expanding dairy processing corridor in Nuevo León and Jalisco, where diglyceride demand for fat-sparing applications outpaces domestic supply and NOM-Codex harmonization reduces regulatory friction. Lead with rapid formulation support capabilities rather than commodity pricing to differentiate from established oilseed processors. For Investors and Strategic Acquirers: Long-term, this sits as a technical service consolidation play because outcome-based contracting is unbundling ingredient supply from formulation expertise, rewarding integrated players with pilot-scale infrastructure and regulatory dossier capabilities. Acquisition targets should prioritize fermentation-derived lecithin platforms with sustainable positioning and established GRAS notifications. The signal to watch is Health Canada Food Directorate amendment timeline compression, which would accelerate novel emulsifier approval cycles and shift R&D investment patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Oilseed Crush | Captive supply of non-GMO and organic feedstocks insulates against sunflower lecithin volatility from Argentina-Ukraine concentration. |
| FDA GRAS Notification Dossier Investment | Extended safety documentation under intensified scrutiny creates regulatory differentiation against self-affirmed competitors. |
| Toll Manufacturing Partnership Expansion | Asset-light capacity access enables mid-tier suppliers to serve California plant-based meat corridor without greenfield capital. |
| Outcome-Based Contracting Model | Technical service bundling transfers shelf-life stability risk from food manufacturers to emulsifier suppliers, capturing margin premium. |
| Fermentation-Derived Lecithin Platform Development | Advanced bioprocessing reduces agricultural cycle dependency and anchors sustainable positioning in clean-label segments. |
Research Methodology
A spread of perspectives from formulation chemists at integrated oilseed processors, procurement directors at California meat-alternative manufacturers, regulatory affairs leads navigating FDA GRAS notification pathways, and technical service managers at fermentation-derived specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA GRAS notification filings, Health Canada Food Directorate amendment records, SEC 10-K disclosures from publicly traded ingredient suppliers, and customs data tracking soy and sunflower lecithin trade flows. Bottom-up capacity modeling across enzymatic interesterification facilities and top-down demand estimation from bakery, dairy, and beverage processing volumes were triangulated to constrain forecast ranges.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, application, physical form, and end-user procurement sophistication. CAGRs were derived from installed capacity utilization trends, reformulation timeline acceleration under Health Canada front-of-package regulations, and Mexico's dairy processing capacity expansion under NOM-Codex harmonization. Industry-specific forecast inputs included HLB specification requirements by application, clean-label certification penetration rates, and toll manufacturing partnership formation velocity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by backward-integrated agricultural processors or accelerated FDA GRAS notification approvals would shift outcomes materially. Macroeconomic deviation, regulatory timeline compression, or breakthroughs in emulsifier-food protein interaction modeling would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Spain Food Enzymes Market