
 Food Enzymes Market | 2026-2036
Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Food Enzymes Market Analysis
Specialty enzyme formulation revenue is rewriting profit distribution across the value chain. Novonesis Group leverages its merged biosolutions platform to dominate microbial strain development. DSM-Firmenich sustains leadership through backward integration into precision fermentation capacity. Kerry Group plc anchors its position with application-specific technical service teams embedded in customer R&D labs.
Food enzymes are protein-based biocatalysts, typically operating at 30–60°C and pH 4.0–8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. Proteases command the largest volume share due to their ubiquity in dairy coagulation and meat tenderization, though lipase blends for structured fats are expanding fastest as clean-label interest intensifies. Liquid formulations retain manufacturing preference for inline dosing systems, while powder and granular forms compete on stability during ambient storage and transport.
EMA and EFSA frameworks govern enzyme safety evaluations and novel food approvals across Europe, while REACH compliance shapes raw material sourcing for biocatalyst production. The EU Green Deal's processing emissions targets are redirecting capital toward enzymatic alternatives that reduce thermal energy inputs. Stakeholders must monitor regulatory divergence between European hazard classification protocols and emerging biocatalytic guidance from other jurisdictions to anticipate certification burdens.
Market Dynamics
Biocatalytic processing is displacing thermal-intensive methods across European food manufacturing, with the EU Green Deal's emissions benchmarks forcing capital reallocation toward enzyme-based reaction systems that operate at ambient temperatures.
Growth Catalysts
- EU Green Deal processing mandates:Binding emissions reduction targets for food manufacturers are accelerating substitution of heat-dependent unit operations with enzymatic alternatives in dairy and bakery processing.
- Bakery automation integration:Industrial bakeries in Germany are embedding inline enzyme dosing systems into continuous production lines, creating pull for liquid formulation stability.
- Clean-label structured fats:Lipase-catalyzed interesterification is replacing chemical hydrogenation in margarine and shortening production as trans-fat regulations tighten.
Market Restraints
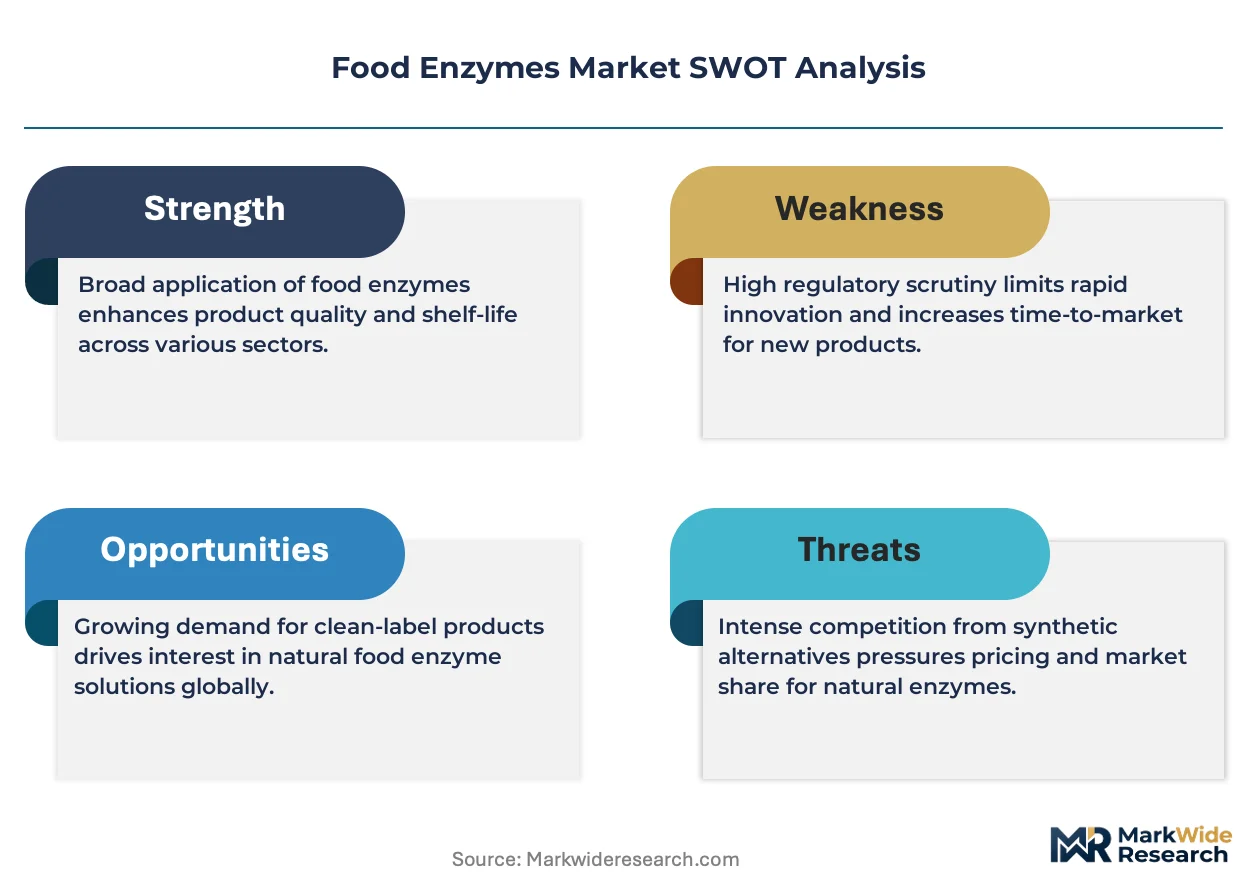
- Precision fermentation feedstock volatility:Dextrose and nitrogen source costs fluctuate with agricultural commodity cycles, compressing margins for bulk enzyme manufacturers.
- Strain development concentration:Proprietary microbial platform ownership clusters among three Danish-Dutch biotechnology groups, limiting supplier diversity for novel biocatalysts.
- Thermostability ceiling:Most food-grade proteases denature above 60°C, restricting application in ultra-high-temperature sterilization processes.
Strategic Opportunities
- Plant-based protein texturization:Transglutaminase and protease blends for meat analogs remain underdeveloped in extrusion-hydration applications.
- EU F-Gas Regulation biocatalytic loophole:The phase-down of hydrofluorocarbon refrigerants creates regulatory space for enzymatic cold-processing alternatives in frozen dough conditioning.
- Direct-to-bakery technical service:Embedded formulation scientists at customer R&D facilities represent an unexploited channel for application-specific enzyme design.
Industry Challenges
- Enzymologist talent scarcity:Industrial biocatalysis expertise concentrates in academic and pharmaceutical sectors, creating recruitment friction for food-grade strain optimization roles.
- EFSA novel food timeline:Microbial source approval processes extend 18-24 months, delaying market entry for fermentation-derived enzyme variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Enzymes Market |
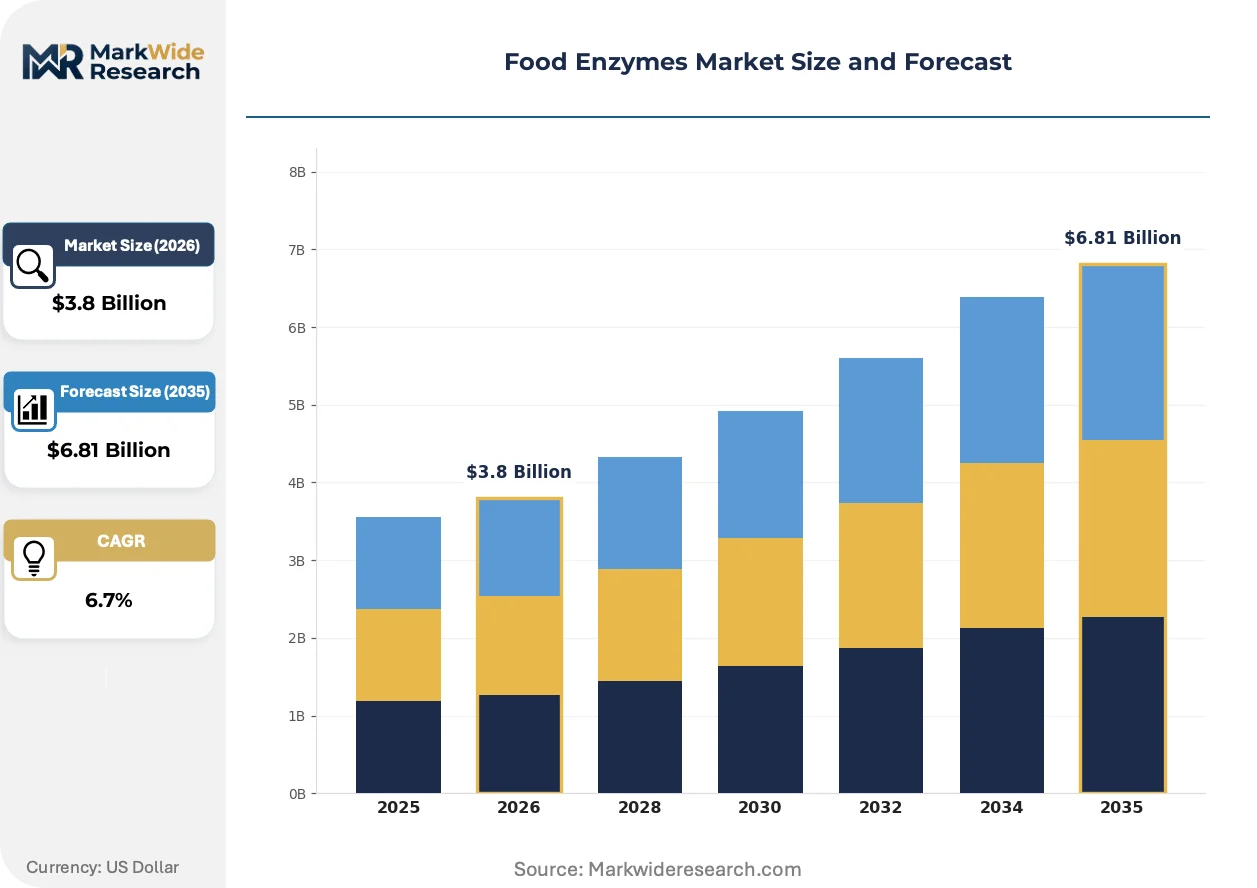
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Beverages, Dairy, Bakery, Meat Processing End User: Food Manufacturers, Beverage Producers, Restaurants, Households Formulation Type: Liquid, Powder, Granular, Tablets |
| Companies Covered | Novonesis Group, DSM-Firmenich, International Flavors & Fragrances Inc., Kerry Group plc, BASF SE, AB Enzymes GmbH, DuPont Nutrition & Biosciences, Amano Enzyme Inc., Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Enzymes Market Emerging Trajectories
Multi-enzyme synergistic formulations are replacing single-activity products, with manufacturers engineering cascade reactions that accomplish sequential processing steps without intermediate thermal resets.
Cell-free enzyme systems is collapsing the traditional fermentation-to-formulation value chain. These stabilized catalytic complexes bypass upstream biomass handling entirely. Dairy processors in the Netherlands are piloting direct integration of cell-free protease cocktails into cheese vats. The technology is collapsing capital requirements for mid-scale enzyme users who previously lacked fermentation infrastructure.
REACH biocidal product regulation is reclassifying certain enzyme preparations, triggering reformulation mandates for manufacturers using preservative-stabilized liquid products. Industrial laundries and food sanitation sectors face overlapping compliance burdens. Bakery enzyme suppliers are responding with powder-form alternatives that circumvent the biocidal authorization pathway entirely.
Specification-driven procurement now dominates enzyme sourcing for multinational food manufacturers. Technical service depth and application-specific stability data have displaced price-per-activity-unit as the primary vendor selection criterion. German dairy cooperatives are requiring embedded formulation support as a contract precondition. This shift concentrates purchasing power among suppliers with captive R&D presence in customer facilities.
Food Enzymes Market Segmentation
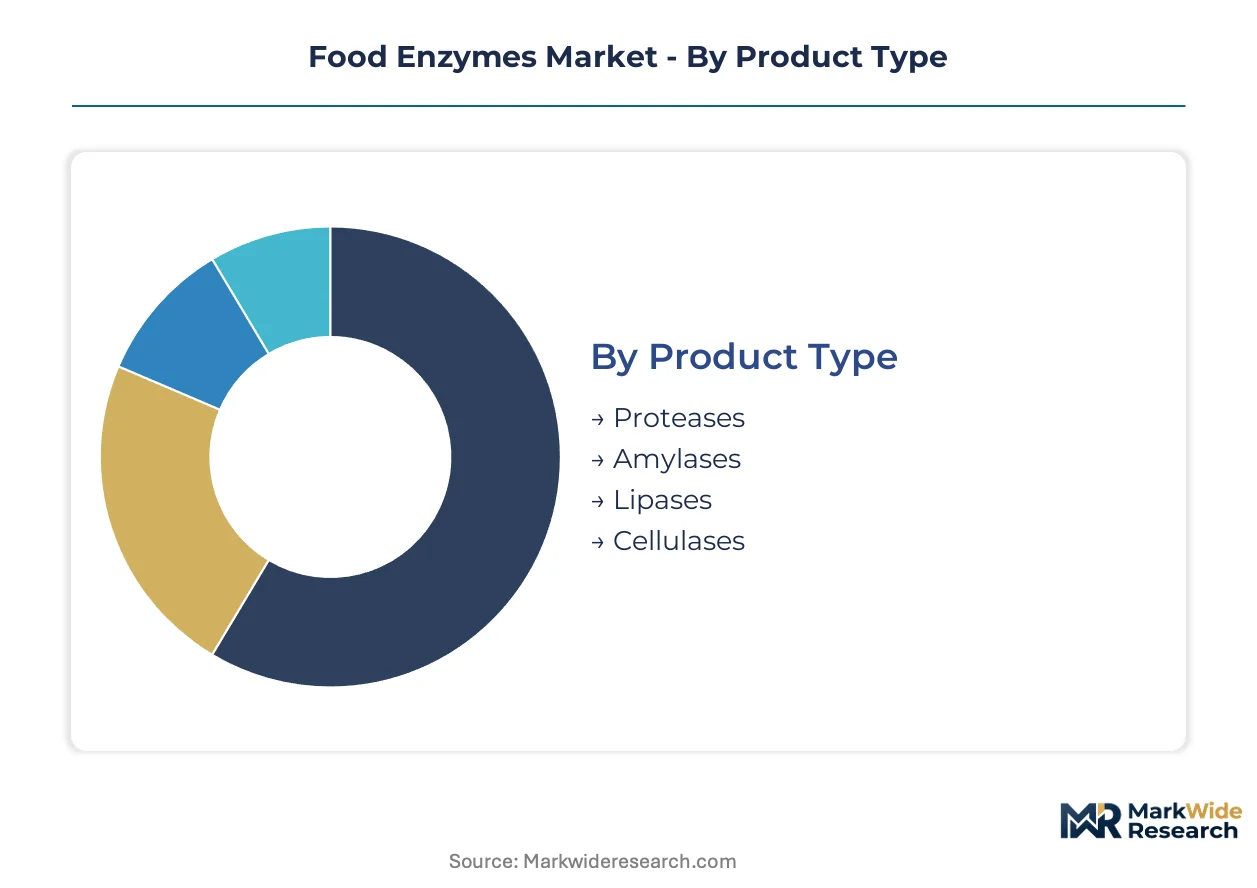
Segmentation in food enzymes reveals divergent commercial rhythms. Formulation stability requirements and application-specific thermal tolerances create distinct inventory velocity patterns across product categories.
Product Type:
Cycle times vary sharply by catalytic class. Proteases turn over fastest due to dairy sector demand continuity, while lipase blends move slower as clean-label fat restructuring projects extend qualification timelines.
- Proteases:These protein-hydrolyzing enzymes operate optimally at 45–55°C and pH 5.5–7.0, with subtilisin variants dominating cheese coagulation. German dairy cooperatives are absorbing bulk volumes for quark and fresh cheese production, pressured by EFSA processing aid reclassifications that demand enhanced purity documentation.
- Amylases:Starch-degrading enzymes split α-1,4 glycosidic bonds to control dough viscosity and syrup conversion. Industrial bakeries in the Netherlands deploy fungal amylases for extended shelf-life bread, though thermostability limitations below 65°C constrain ultra-high-temperature applications.
- Lipases:Triacylglycerol hydrolases enable position-specific interesterification for trans-fat-free margarines. Danish lipid technology firms are scaling immobilized lipase reactors.
- Cellulases:β-1,4-glucanases break plant cell wall structures for juice clarification and dietary fiber modification. Spanish citrus processors represent concentrated demand.
Proteases anchors the volume base while lipases gains share at the steepest rate.
Application:
Margin structures diverge by processing intensity. Dairy and bakery applications command formulation premiums for inline dosing compatibility, while beverage applications compete on cost-per-activity-unit.
- Dairy:Chymosin and microbial rennet variants for cheese curd formation, whey protein hydrolysis, and lactose-free milk production. French cheese PDO specifications are tightening enzyme source documentation requirements.
- Bakery:Dough conditioning enzymes reduce mixing time and extend crumb softness. German industrial bakeries are embedding liquid amylase-protease blends into continuous production lines.
- Beverages:Pectinases and cellulases for juice yield extraction and haze stabilization. Italian wine cooperatives drive seasonal demand spikes.
- Meat Processing:Papain and bromelain applications for collagen softening in cured products. Spanish cured ham DOP regulations restrict exogenous enzyme use.
Dairy commands the revenue concentration while bakery expands most quickly through automation integration.
End User:
Procurement sophistication stratifies sharply by scale. Multinational food manufacturers specify stability data and embedded technical service, while household channels compete on shelf visibility.
- Food Manufacturers:Industrial-scale enzyme procurement with specification-driven tendering and long-term supply agreements. Swiss chocolate processors are requiring lipase interesterification for cocoa butter alternatives.
- Beverage Producers:Seasonal demand patterns for harvest-period enzyme deployment. German fruit juice concentrators dominate regional volume.
- Restaurants:Limited penetration due to cold-chain requirements for liquid formulations. Powder meat tenderizers retain niche presence.
- Households:Retail-packaged baking enhancers and meat tenderizers. Italian domestic bread-making traditions sustain modest demand.
Food manufacturers concentrate purchasing power while beverage producers exhibit the most volatile seasonal demand.
Formulation Type:
Supply chain configuration determines geographic reach. Liquid formulations require refrigerated logistics, while powder and granular forms achieve ambient distribution economics.
- Liquid:Inline dosing compatibility and rapid dispersion in aqueous food matrices. REACH biocidal product regulation is triggering reformulation mandates for preservative-stabilized variants.
- Powder:Extended ambient stability and reduced transport costs. Spray-dried protease concentrates serve remote dairy processing facilities.
- Granular:Dust-free handling characteristics for large-scale bakery operations. German millers prefer granulated amylase for flour enrichment.
- Tablets:Precise unit-dosing for small-batch meat processing. Limited to artisanal sausage production.
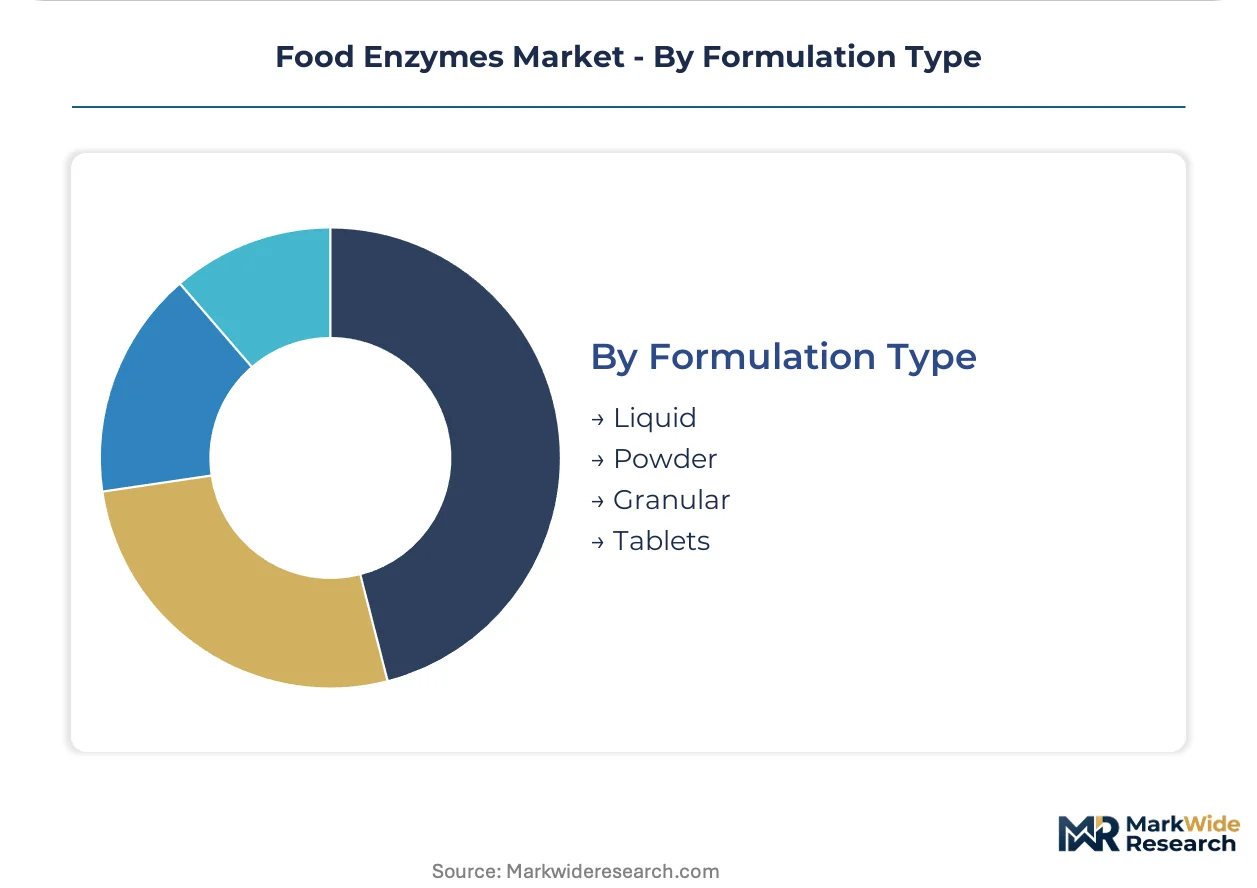
Liquid formulations dominate manufacturing preference while powder gains share in distribution-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German industrial bakeries absorb price premiums for inline dosing compatibility, while Spanish juice processors compete on cost-per-activity-unit. Italian cheese cooperatives occupy the middle ground, prioritizing technical service depth over raw material economics.
Germany
Industrial bakeries in Munich and Stuttgart drive pull for liquid amylase-protease blends embedded in continuous production lines. The EU Green Deal's binding emissions targets accelerate substitution of thermal dough conditioning with enzymatic alternatives. North Rhine-Westphalia hosts concentrated dairy processing clusters where EFSA processing aid reclassifications demand enhanced enzyme purity documentation.
Netherlands
Dairy cooperatives in Friesland pilot cell-free protease cocktails for cheese vat integration, collapsing capital requirements for mid-scale processors. REACH biocidal product regulation triggers reformulation mandates for preservative-stabilized liquid enzymes. The Eindhoven-Wageningen corridor anchors precision fermentation infrastructure development.
France
PDO cheese specifications in Auvergne-Rhône-Alpes tighten enzyme source documentation requirements, favoring suppliers with captive strain traceability. EMA novel food approval timelines extend 18-24 months for microbial-derived variants. Paris Basin dairy processors concentrate purchasing power through specification-driven tendering.
Denmark
Danish lipid technology firms scale immobilized lipase reactors for trans-fat-free margarine production. The F-Gas Regulation phase-down of hydrofluorocarbon refrigerants creates regulatory space for enzymatic cold-processing alternatives. Copenhagen biosolutions clusters dominate proprietary microbial platform ownership.
Italy
Seasonal demand spikes from Trentino-Alto Adige wine cooperatives concentrate pectinase procurement during harvest windows. Domestic bread-making traditions sustain modest retail enzyme demand in Emilia-Romagna. EFSA safety evaluation frameworks govern novel enzyme approvals across Lombardy beverage processing facilities.
Food Enzymes Market Vendor Landscape
Capability concentration sits with biosolutions specialists; scale advantage sits with diversified ingredient conglomerates. Three Danish-Dutch biotechnology groups cluster proprietary microbial strain ownership, limiting supplier diversity for novel biocatalysts. Strategic archetypes separate into precision fermentation platform owners, application-specific technical service providers, and backward-integrated fermentation capacity operators. Dominant competitive moves include merger-driven biosolutions platform consolidation and embedded R&D team deployment at customer facilities.
Within the merged-platform tier, Novonesis Group and DSM-Firmenich occupy positions as archetypal precision fermentation consolidators. Kerry Group plc anchors the technical service vector with application-specific formulation scientists. Among European chemical conglomerates, BASF SE exemplifies diversified ingredient scale players competing on ambient distribution economics. AB Enzymes GmbH represents regional specialists concentrating on spray-dried concentrates for remote dairy facilities. These four entities collectively illustrate the competitive tension between captive strain development and outsourced biocatalytic supply.
| Leading Market Players |
|---|
| Novonesis Group |
| DSM-Firmenich |
| International Flavors & Fragrances Inc. |
| Kerry Group plc |
| BASF SE |
| AB Enzymes GmbH |
| DuPont Nutrition & Biosciences |
| Amano Enzyme Inc. |
| Chr. Hansen Holding A/S |
| Others |
Supply Flow & Price Mechanics
Precision fermentation feedstock volatility determines both pricing tier spreads and supply chain shape in the food enzymes sector. Dextrose and nitrogen source costs fluctuate with agricultural commodity cycles, compressing margins for bulk enzyme manufacturers while forcing tiered pricing differentiation between commodity-grade and specialty-formulation buyers.
Pricing Analysis
Embedded technical service contracts drive lifetime value in food enzyme procurement. Three-tier pricing structure across premium, standard, and economy levels separates formulation-specific stability guarantees from commodity activity-unit sales. Price differentiation rests on certification grade and volume scale, with EFSA processing aid documentation commanding premiums. Cost compression in standard-grade protease concentrates is intensifying because German dairy cooperatives are consolidating purchasing through specification-driven tendering. Small-scale meat processors exhibit highest price sensitivity; multinational bakery automation integrators show lowest.
Supply Chain Analysis
Export-control regimes on precision fermentation equipment limit technology flows into competing jurisdictions. Manufacturing gravity centers on Denmark, the Netherlands, and Germany, where proprietary microbial platform ownership clusters among biosolutions specialists. Raw material dependencies draw from agricultural dextrose suppliers, nitrogen source providers, and specialized bioreactor component fabricators. Single-source vulnerability concentrates in strain development IP held by three Danish-Dutch biotechnology groups. Distribution runs through ambient-stable powder and granular formats for remote dairy facilities, with liquid formulations requiring refrigerated logistics chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food enzyme markets function as service-attach opportunities where embedded formulation scientists and application-specific technical support expand faster than commodity biocatalyst sales. Recurring revenue from stability monitoring and strain optimization contracts outpaces hardware-like enzyme concentrate growth.
For Market Incumbents: Pre-empt margin erosion from precision fermentation feedstock volatility by locking long-term dextrose supply agreements with agricultural cooperatives in Germany and the Netherlands. Consolidate proprietary microbial platform ownership through selective acquisition of regional strain-development specialists before EFSA novel food timelines extend competitive moats. Embedded technical service deployment at customer R&D facilities remains the priority defensive lever against price-per-activity-unit commoditization.
For New Entrants and Emerging Players: Pursue plant-based protein texturization as the most penetrable white-space segment, where transglutaminase and protease blends for meat analogs remain underdeveloped in extrusion-hydration applications. Target Spanish citrus processors and Italian wine cooperatives for seasonal pectinase and cellulase demand with powder-form distribution bypassing REACH biocidal compliance burdens. Direct-to-bakery technical service represents the specific go-to-market angle for bypassing incumbent specification lock-in.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision fermentation platform owners with captive strain traceability. Long-term viability over the coming decade hinges on backward integration into dextrose sourcing and nitrogen recovery systems. Acquisition target archetype: mid-scale European enzyme formulators with EFSA-approved microbial source documentation and existing embedded service contracts. The signal to watch is EU F-Gas Regulation enforcement accelerating substitution demand for enzymatic cold-processing alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation Feedstock | Captive dextrose supply from German agricultural cooperatives insulates margin from commodity volatility. |
| Embedded Technical Service Deployment | Formulation scientists at customer R&D labs displace price-per-activity-unit as vendor selection criterion. |
| Cell-Free Enzyme System Commercialization | Stabilized catalytic complexes collapse capital requirements for mid-scale dairy processors in the Netherlands. |
| EFSA Novel Food Approval Acceleration | Reduced 18-24 month microbial source timelines unlock faster market entry for fermentation-derived variants. |
| Multi-Enzyme Synergistic Formulation Development | Cascade reaction engineering eliminates intermediate thermal resets in German industrial bakery lines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary research phases. Enzyme formulation scientists at Novonesis Group and DSM-Firmenich, procurement leads at German industrial bakeries, technical R&D directors at dairy cooperatives in the Netherlands, and regulatory affairs specialists navigating EFSA novel food frameworks provided qualitative inputs. Secondary validation drew from EFSA safety evaluations, REACH biocidal product regulation filings, EU Green Deal emissions target documentation, and customs data on fermentation equipment trade flows. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Calibration against historical volume trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include catalytic class, application sector, formulation type, and end-user procurement sophistication tier. CAGRs were derived from fitted growth curves adjusted for regulatory inflection points and automation adoption rates. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and EMA processing aid reclassification timelines.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price indices and precision fermentation capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions on strain development success rates and regulatory approval timelines. Material shifts in EU Green Deal enforcement stringency or REACH biocidal reclassification scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Clean Label Ingredients Market