
 Global Organic Food Preservatives Market | 2026-2036
Global Organic Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Food Preservatives Market Foresight
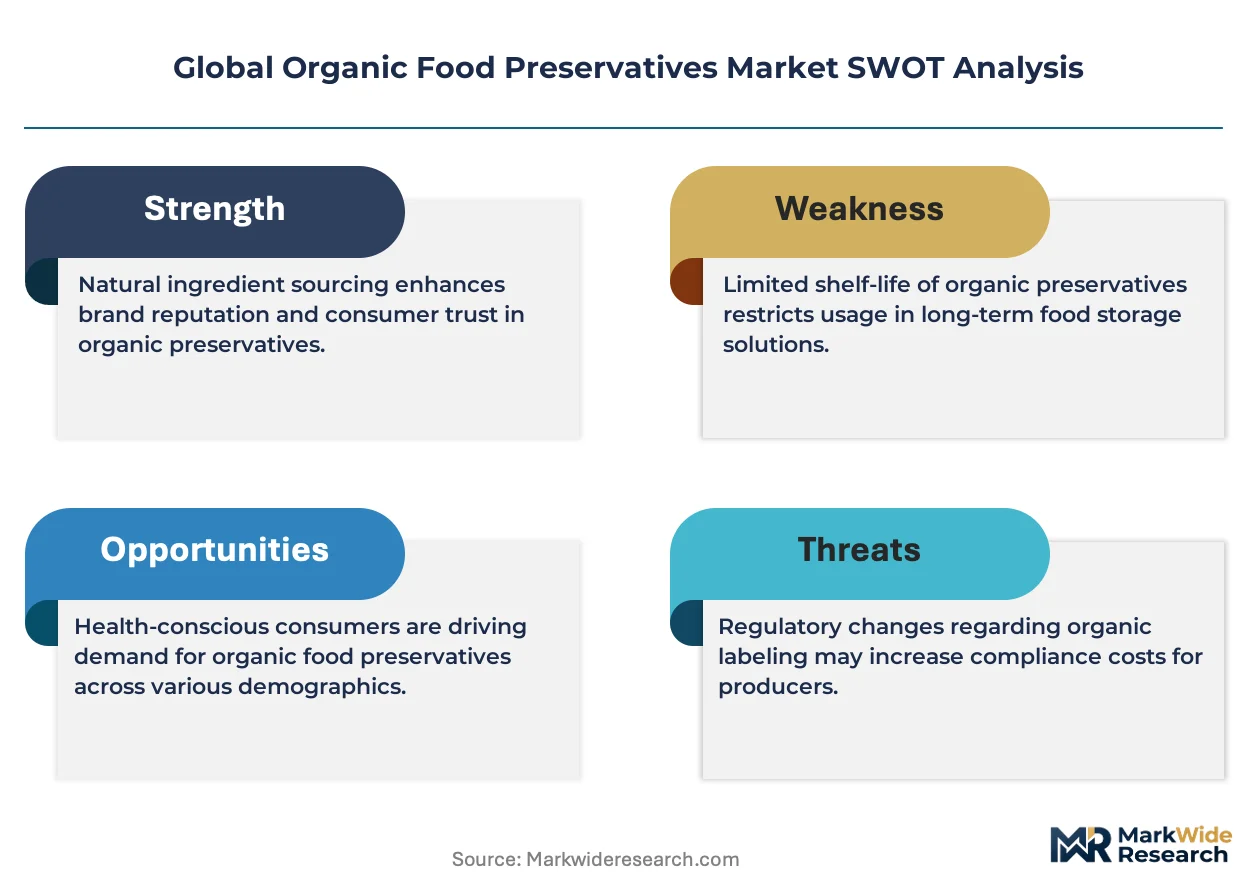
USDA Organic certification is reorganizing competitive access across the Global Organic Food Preservatives Market, filtering out suppliers unable to maintain chain-of-custody documentation from farm to finished ingredient. Cargill, Incorporated leverages its grain origination networks to secure certified organic raw material streams for antioxidant production. BASF SE anchors its position through fermentation-derived preservative platforms developed at European biotechnology centers. Chr. Hansen Holding A/S specializes in microbial culture formulations that deliver bioprotective effects without synthetic chemical residues.
Organic food preservatives comprise naturally sourced or biologically produced substances that inhibit microbial spoilage, oxidative rancidity, and enzymatic degradation in packaged foods, typically functioning through pH reduction, competitive exclusion, or radical scavenging at inclusion rates between 0.01% and 2.0% by weight. Their primary commercial purpose is to extend shelf life while satisfying clean-label requirements that prohibit synthetic additives such as benzoates or sorbates. Natural antioxidants currently command the largest product type position due to established supply chains for rosemary and green tea extracts, though fermented extracts are gaining fastest as biotechnology scales reduce unit costs. Within applications, meat processing generates the deepest margin pools because pathogen-control specifications justify premium pricing for certified organic solutions.
The US FDA maintains GRAS notification pathways that distinguish organic preservatives from regulated food additives, while EFSA in Europe enforces purity standards through the EU Organic Regulation 2018/848 that restrict carrier solvents and processing aids. India's FSSAI has begun aligning its organic labeling requirements with Codex Alimentarius guidelines, creating compliance complexity for exporters serving multiple jurisdictions. Stakeholders must monitor how evolving maximum residue limits for processing contaminants in organic systems reshape formulation choices and supplier qualification protocols.
Market Dynamics
EU Green Deal sustainability mandates are compressing permissible synthetic additive thresholds across food manufacturing, forcing ingredient suppliers to accelerate fermentation-derived preservative development or lose qualified supplier status with major processors.
Growth Catalysts
- Clean-label reformulation mandates:Major bakery manufacturers are eliminating benzoates and sorbates from shelf-stable products, creating immediate procurement pull for rosemary and green tea extract alternatives.
- USDA Organic certification expansion:Chain-of-custody documentation requirements are filtering non-compliant suppliers, concentrating volume with certified organic raw material networks.
- Fermentation biotechnology scale-up:European biotechnology centers are reducing unit production costs for microbial culture preservatives, accelerating adoption in artisanal meat processing.
Market Restraints
- Organic feedstock cost volatility:Certified organic grain and herb supplies face weather-driven price swings that compress antioxidant producer margins.
- Carrier solvent restrictions:EU Organic Regulation 2018/848 limits permissible extraction solvents, constraining rosemary extract yield efficiency.
- Synthetic preservative price anchoring:Conventional benzoates maintain 60-70% cost advantages that block organic penetration in mass-market retail channels.
Strategic Opportunities
- India FSSAI alignment:Codex Alimentarius harmonization creates export pathway for fermentation-derived preservatives into South Asian processed food markets.
- Bioprotective culture convergence:Chr. Hansen-style microbial formulations combining bacteriocin production with pH reduction are opening clean-label dairy applications.
- Direct-processor distribution:Bypassing ingredient distributors to contract directly with German artisanal meat clusters captures margin and secures volume commitments.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with GMP bioprocessing experience command premium compensation that strains mid-tier producer economics.
- Multi-jurisdiction certification timelines:Simultaneous USDA Organic, EU 2018/848, and FSSAI compliance audits extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Food Preservatives Market |
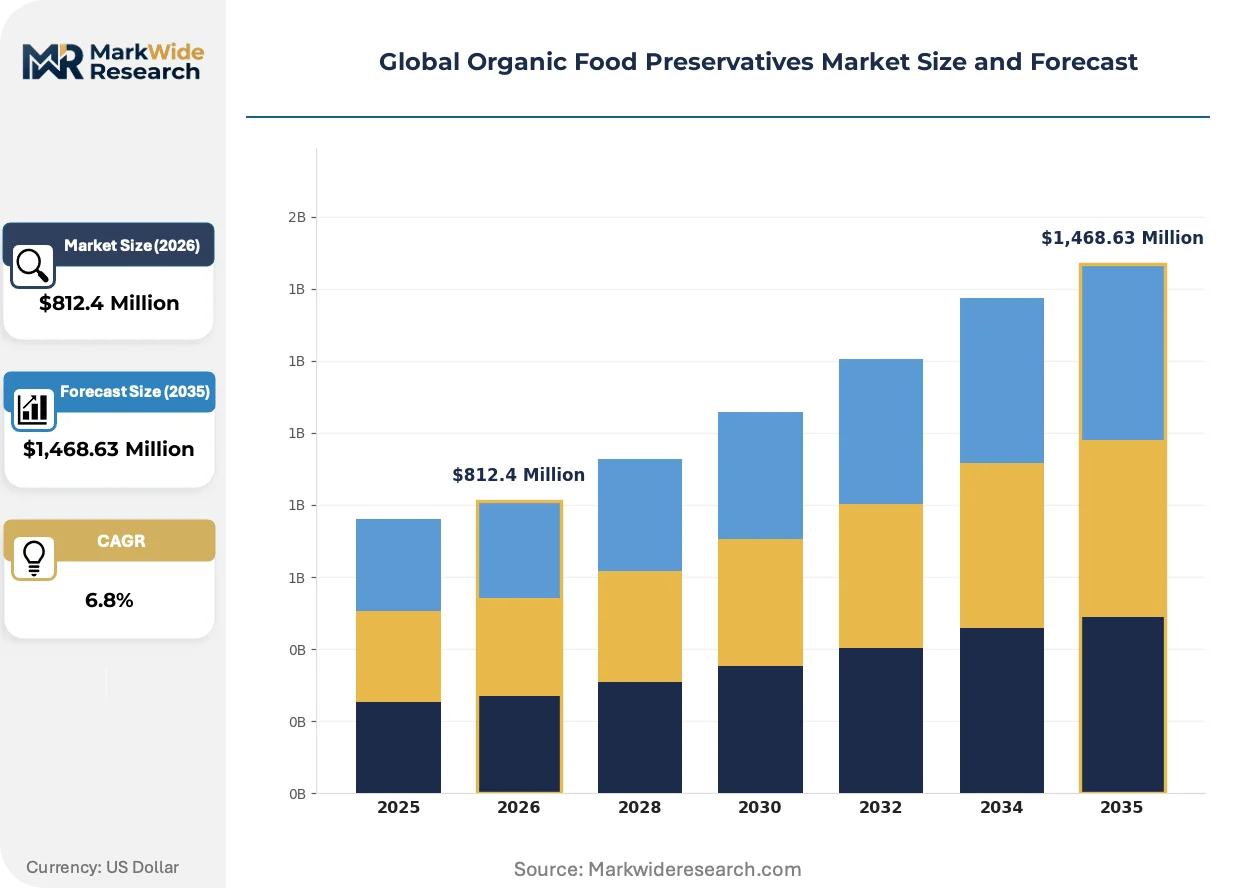
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Antioxidants, Fermented Extracts, Essential Oils, Plant Extracts, Microbial Cultures Application: Dairy Products, Baked Goods, Meat Processing, Beverages, Confectionery End User: Food Manufacturers, Specialty Bakers, Beverage Producers, Meat Processors, Artisan Producers Packaging Type: Glass Containers, PET Bottles, Aluminum Cans, Paperboard Cartons, Biodegradable Films |
| Companies Covered | Cargill, Incorporated, DuPont de Nemours, Inc., Kemin Industries, Inc., Tate & Lyle PLC, BASF SE, Chr. Hansen Holding A/S, Givaudan SA, Univar Solutions Inc., Hawkins Watts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Food Preservatives Market Shifts & Advancements
Fermentation-derived bioprotective cultures are compressing synthetic preservative reliance across premium meat and dairy segments, while regulatory purity standards tighten and procurement models favor direct supplier-processor relationships.
Precision fermentation platforms producing bacteriocins and organic acids are displacing chemical preservatives in refrigerated meat applications. German artisanal processors are adopting these solutions at accelerated rates to satisfy EU Green Deal procurement specifications. This technology is displacing traditional rosemary extract dominance in high-margin pathogen-control segments where performance consistency outweighs cost premiums.
EFSA enforcement of EU Organic Regulation 2018/848 is restricting carrier solvents and processing aids in extraction workflows. Industrial consequence includes reformulation of rosemary and green tea extract production lines to comply with purity thresholds. Meat processing applications face the steepest compliance costs, driving consolidation toward integrated fermentation-derived alternatives.
Direct contracting between preservative producers and meat processors is fragmenting traditional ingredient distribution channels. German processor clusters now negotiate multi-year supply agreements that bypass regional distributors entirely. This pattern concentrates most visibly in Bavaria and Baden-Württemberg, where artisanal sausage manufacturers seek supply security for certified organic inputs.
Global Organic Food Preservatives Market Segmentation
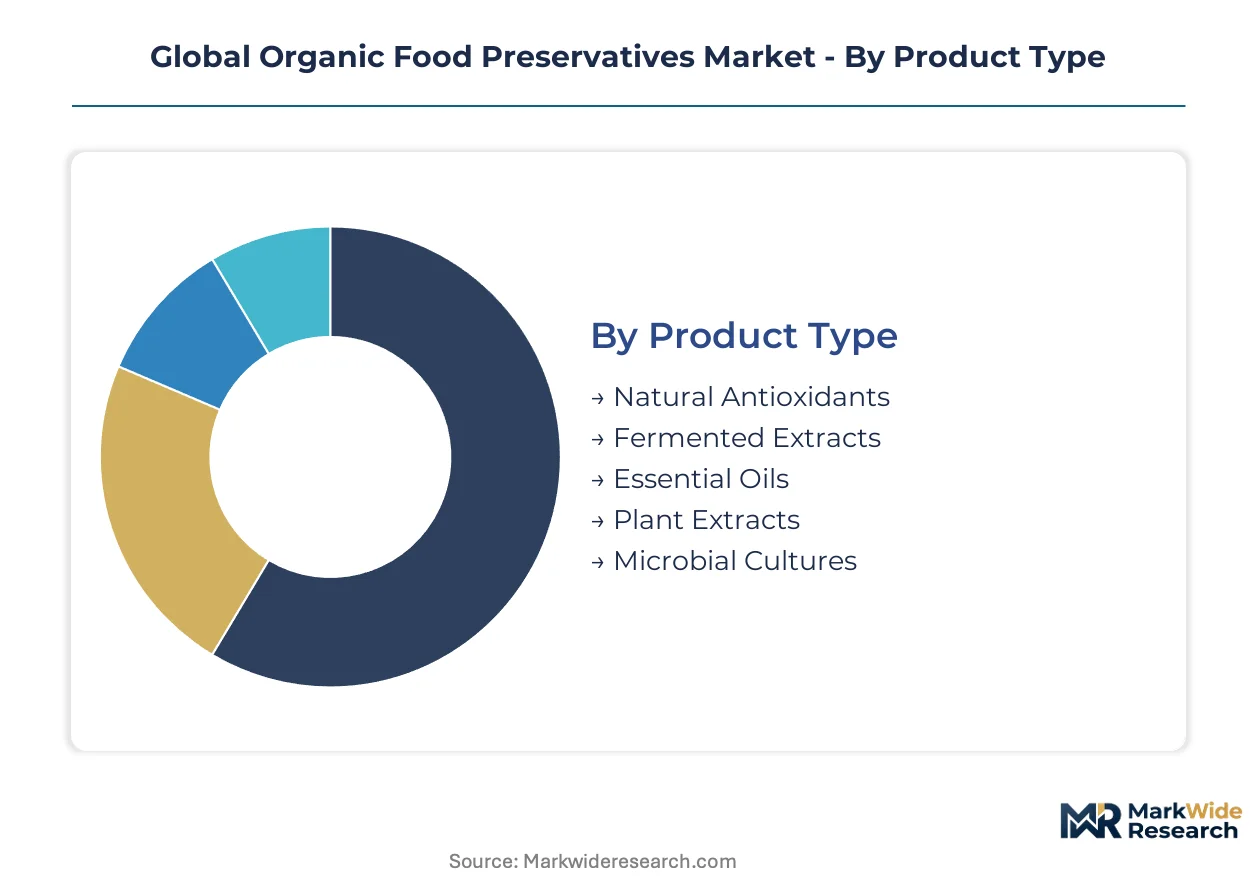
Organic food preservatives segment across functional chemistry, application severity, and procurement sophistication. Each dimension reveals distinct margin architectures and certification requirements that reshape supplier-processor relationships.
Product Type:
Natural antioxidants capture the deepest margin pools due to established extraction infrastructure and premium positioning in clean-label meat applications.
- Natural Antioxidants:Rosemary and green tea extracts dominate current procurement volumes through proven radical-scavenging efficacy at 0.01-0.5% inclusion rates. German meat processors anchor demand as EFSA purity mandates tighten permissible carrier solvents.
- Fermented Extracts:Biotechnology platforms produce organic acids and bacteriocins via controlled microbial fermentation. Bavarian artisanal sausage clusters are switching to these solutions fastest as EU Green Deal specifications harden against synthetic alternatives.
- Essential Oils:Thyme and oregano oil fractions deliver antimicrobial activity through phenolic compounds.
- Plant Extracts:Grape seed and acerola derivatives provide ascorbic acid equivalents for oxidation control.
- Microbial Cultures:Live bioprotective strains enable competitive exclusion in refrigerated dairy matrices.
Natural antioxidants hold installed capacity. Fermented extracts are rotating up the share rankings.
Application:
Meat processing commands premium pricing tolerance due to pathogen-control liability and USDA Organic certification requirements.
- Meat Processing:Pathogen inhibition specifications justify 40-60% cost premiums over conventional preservatives. Artisanal German processors drive fermentation-derived adoption to satisfy chain-of-custody documentation for EU organic exports.
- Dairy Products:Refrigerated shelf-life extension relies on microbial culture integration without synthetic chemical residues. Clean-label reformulation in French and Italian specialty cheese operations accelerates bioprotective culture procurement.
- Baked Goods:Mold inhibition in shelf-stable bread and pastries favors rosemary extract solutions.
- Beverages:pH-stable antioxidant systems prevent oxidative off-flavors in organic juices and plant milks.
- Confectionery:Rancidity control in nut-containing chocolates employs mixed tocopherol systems.
Meat processing maintains the steepest pricing power. Dairy applications are climbing the fastest on bioprotective convergence.
End User:
Artisan producers generate the highest per-kilogram margins despite smaller batch volumes, due to multi-certification complexity and direct contracting preferences.
- Artisan Producers:Small-batch meat and dairy operations in Bavaria and Baden-Württemberg negotiate multi-year supply agreements bypassing distributors entirely. Their procurement prioritizes chain-of-custody transparency over unit cost minimization.
- Food Manufacturers:Large-scale bakery and beverage operations consolidate rosemary extract volumes through certified organic grain origination networks.
- Specialty Bakers:Clean-label shelf-stable product lines eliminate benzoates in favor of green tea extract alternatives.
- Beverage Producers:Organic juice processors require oxidation control without synthetic antioxidant carryover.
- Meat Processors:Mid-tier sausage manufacturers face margin compression from feedstock volatility and certification audit costs.
Food manufacturers hold volume concentration. Artisan producers are gaining negotiation leverage through direct sourcing.
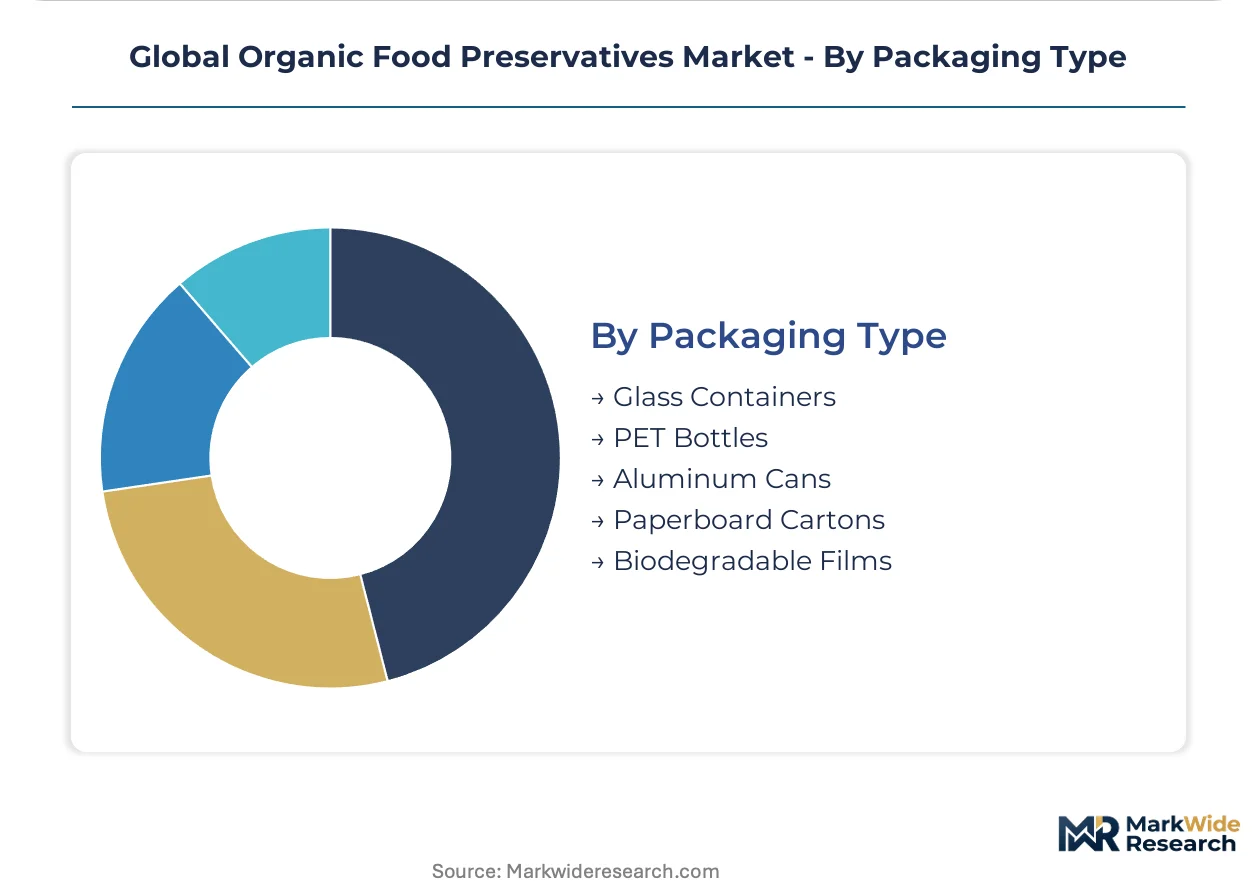
Packaging Type:
Biodegradable films concentrate innovation investment as EU sustainability mandates reshape barrier property requirements for organic products.
- Biodegradable Films:Cellulose and PLA-based structures require reformulated preservative systems due to moisture permeability differences. German organic retail chains are mandating these materials fastest under packaging waste reduction targets.
- Glass Containers:Inert barrier properties suit high-acid organic beverages and fermented vegetable applications.
- PET Bottles:Oxygen scavenger integration competes with direct preservative addition in juice applications.
- Aluminum Cans:Interior coating compatibility limits essential oil migration in carbonated organic beverages.
- Paperboard Cartons:Aseptic filling requirements drive laminated barrier structures with natural antioxidant stabilization.
Glass containers maintain established infrastructure. Biodegradable films are expanding most quickly on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement specifications are redirecting supply chain investments toward certified organic preservative networks, while USDA Organic certification expansion in North America and FSSAI harmonization in India reshape competitive access across three continents.
Germany
Artisanal meat processors in Bavaria and Baden-Württemberg are switching to fermentation-derived preservatives to satisfy EU 2018/848 chain-of-custody requirements. The country's national food safety regulator enforces purity thresholds that constrain rosemary extract carrier solvents. Stuttgart-based sausage manufacturers now negotiate multi-year supply agreements bypassing traditional distributors entirely.
United States
Clean-label bakery reformulation in California and Illinois is eliminating benzoates from shelf-stable products. USDA Organic certification filters non-compliant suppliers from grain origination networks. Chicago-area food manufacturers consolidate rosemary extract volumes through certified organic supply chains anchored in Midwest grain belts.
India
FSSAI alignment with Codex Alimentarius guidelines creates export pathways for fermentation-derived preservatives into South Asian processed food markets. The national food regulator tightens organic labeling requirements for imported ingredients. Maharashtra-based dairy operations accelerate bioprotective culture procurement for clean-label cheese applications.
France
Specialty cheese producers in Auvergne-Rhône-Alpes adopt microbial culture formulations without synthetic chemical residues. EFSA enforcement of EU Organic Regulation 2018/848 restricts processing aids in extraction workflows. Lyon-region artisan dairies drive fastest adoption of Chr. Hansen-style bioprotective convergence in European dairy applications.
Australia
TGA-equivalent organic certification standards for food ingredients tighten permissible additive thresholds in natural antioxidant imports. Victoria and New South Wales beverage processors require oxidation control systems for organic juices and plant milks. Melbourne-area packaging innovators mandate biodegradable films with reformulated preservative barriers under waste reduction targets.
Global Organic Food Preservatives Market Competitive Landscape
Player mix skews toward integrated agricultural-input suppliers and specialized biotechnology platforms. The market structure concentrates volume among grain-origination networks and fermentation-scale operators, with mid-tier extract producers facing margin compression from feedstock volatility. Three archetypes dominate: certified organic raw material controllers, precision fermentation specialists, and microbial culture formulators. Competitive moves center on backward integration into organic grain supply and direct contracting with processor clusters to bypass distribution.
Within the integrated agricultural tier, Cargill, Incorporated anchors positions through certified organic grain origination networks. BASF SE occupies the biotechnology platform vector with European fermentation-derived preservative development. Chr. Hansen Holding A/S exemplifies the microbial culture specialization archetype, representing bioprotective formulation capabilities without synthetic chemical residues.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DuPont de Nemours, Inc. |
| Kemin Industries, Inc. |
| Tate & Lyle PLC |
| BASF SE |
| Chr. Hansen Holding A/S |
| Givaudan SA |
| Univar Solutions Inc. |
| Hawkins Watts |
| Others |
Supply & Pricing Matrix
EU Organic Regulation 2018/848 gates both supplier qualification and price differentiation simultaneously, as compliance with its carrier solvent restrictions and chain-of-custody documentation requirements separates certified organic preservative producers from conventional extract suppliers while commanding 40-60% premiums in meat processing applications.
Pricing Analysis
Cost-plus contracts with organic grain indexation dominate procurement between antioxidant producers and German meat processors, insulating suppliers from feedstock volatility while transferring weather-driven price swings to buyers. Three-tier pricing structure across premium certified-organic, standard natural, and economy conventional levels stratifies by certification grade and volume scale. Pricing pressure stems from synthetic benzoate cost advantages that block organic penetration in mass-market retail channels. Artisan producers in Bavaria show least price sensitivity due to EU Green Deal procurement mandates, while mid-tier sausage manufacturers face acute margin compression.
Supply Chain Analysis
Germany and India anchor organic preservative supply through contrasting specializations—German biotechnology centers produce fermentation-derived bacteriocins while Indian extract processors supply rosemary and green tea derivatives. Raw material flows draw from certified organic grain belts in the US Midwest, herb cultivation regions in southern France, and microbial culture banks in Denmark. Single-source vulnerability concentrates in fermentation-scale capacity, where GMP-qualified bioprocessing facilities remain scarce. Distribution runs through direct-processor contracting that bypasses traditional ingredient distributors entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Organic Food Preservatives Market expansion sits in early-cycle acceleration, as EU Green Deal mandates force synthetic additive phase-outs faster than fermentation biotechnology can scale capacity.
For Market Incumbents: Consolidate backward integration into certified organic grain origination networks to secure feedstock streams against weather-driven volatility. Lock multi-year direct supply agreements with German artisanal meat clusters before fermentation-derived alternatives achieve cost parity. Prioritize chain-of-custody documentation investments that filter non-compliant competitors from qualified supplier lists. For New Entrants and Emerging Players: Lead with precision fermentation platforms targeting dairy bioprotective cultures, where Chr. Hansen-style microbial formulations remain underpenetrated in French and Italian specialty cheese operations. Exploit FSSAI-Codex harmonization to establish South Asian export positions before incumbent distribution networks consolidate. Anchor go-to-market strategy through direct technical service relationships with artisan processors seeking supply security. For Investors and Strategic Acquirers: EU 2018/848 enforcement milestones reshape the acquisition landscape by devaluing extract-based producers facing carrier solvent compliance costs while elevating fermentation-platform valuations. Long-term viability favors biotechnology specialists with GMP-scale capacity and multi-jurisdiction certification capabilities. Monitor EFSA purity threshold tightening as the signal indicating accelerated consolidation toward integrated fermentation solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feedstock | Cargill-style grain origination networks secure certified raw material streams against price volatility. |
| Precision Fermentation Scale-Up | BASF SE anchors positions through European biotechnology centers reducing unit production costs. |
| Direct-Processor Supply Agreements | Bavarian sausage manufacturers bypass distributors entirely through multi-year volume commitments. |
| Multi-Jurisdiction Certification Investment | Simultaneous USDA Organic, EU 2018/848, and FSSAI compliance opens export pathway arbitrage. |
| Bioprotective Culture Convergence | Chr. Hansen-style microbial formulations displace rosemary extract in high-margin pathogen control. |
Research Methodology
The analysis maps natural antioxidants, fermented extracts, essential oils, and microbial cultures, each validated through fermentation scientists, meat processing procurement leads, dairy quality managers, and organic certification auditors. Primary interviews with ingredient distributors and direct-processor contracting officers combined with secondary validation from EFSA guidance documents, USDA Organic certification databases, FSSAI circulars, and EU Green Deal implementation reports. Bottom-up volume estimates triangulated against top-down market sizing across functional chemistry segments.
Consistency checks validated volume and value outputs against customs trade flows for rosemary extract and microbial culture shipments, with discrepancies reconciled through re-interview loops. Segmentation modeling spanned product type, application severity, end-user procurement sophistication, and packaging format across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating synthetic preservative price anchoring effects and EU regulatory threshold tightening schedules.
Forecasts assume regulatory continuity in EU Organic Regulation 2018/848, USDA Organic certification requirements, and FSSAI-Codex alignment; material policy shifts would require re-modeling. Specific risks include EFSA carrier solvent restriction tightening, organic grain supply shocks, and fermentation talent scarcity compressing scale-up timelines. Recalibration cycles align with material shifts in EU Green Deal enforcement intensity and biotechnology platform cost reduction trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Brazil Food Enzymes Market