
 Gellan Gum Market | 2026-2036
Gellan Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Gellan Gum Market Intelligence
Demand from the dairy alternatives sector is hardening the market's reliance on high-performance hydrocolloids. This shift benefits specialized producers focused on clean-label texturants. CP Kelco specializes in application-specific gellan gum grades, commanding a premium. Fufeng Group leverages significant fermentation capacity in China to compete on scale, while Cargill integrates gellan gum within its broader texturizing solutions portfolio.
Gellan gum is a water-soluble polysaccharide produced through the fermentation of the microorganism Sphingomonas elodea. It is valued commercially for its ability to form stable gels at exceptionally low concentrations, acting as a gelling agent and stabilizer. The distinction between low acyl and high acyl product types defines application suitability. Low acyl gellan gum creates firm, non-elastic gels preferred in confectionery, while high acyl variants produce softer, elastic textures ideal for fluid gels in dairy alternatives.
Market access is governed by food additive regulations enforced by bodies like the US FDA and the European Food Safety Authority (EFSA). These agencies define purity criteria and permissible use levels, such as the E418 designation in the EU. Future formulation success depends on mastering the functional differences between high and low acyl types to meet evolving consumer texture preferences.
Market Dynamics
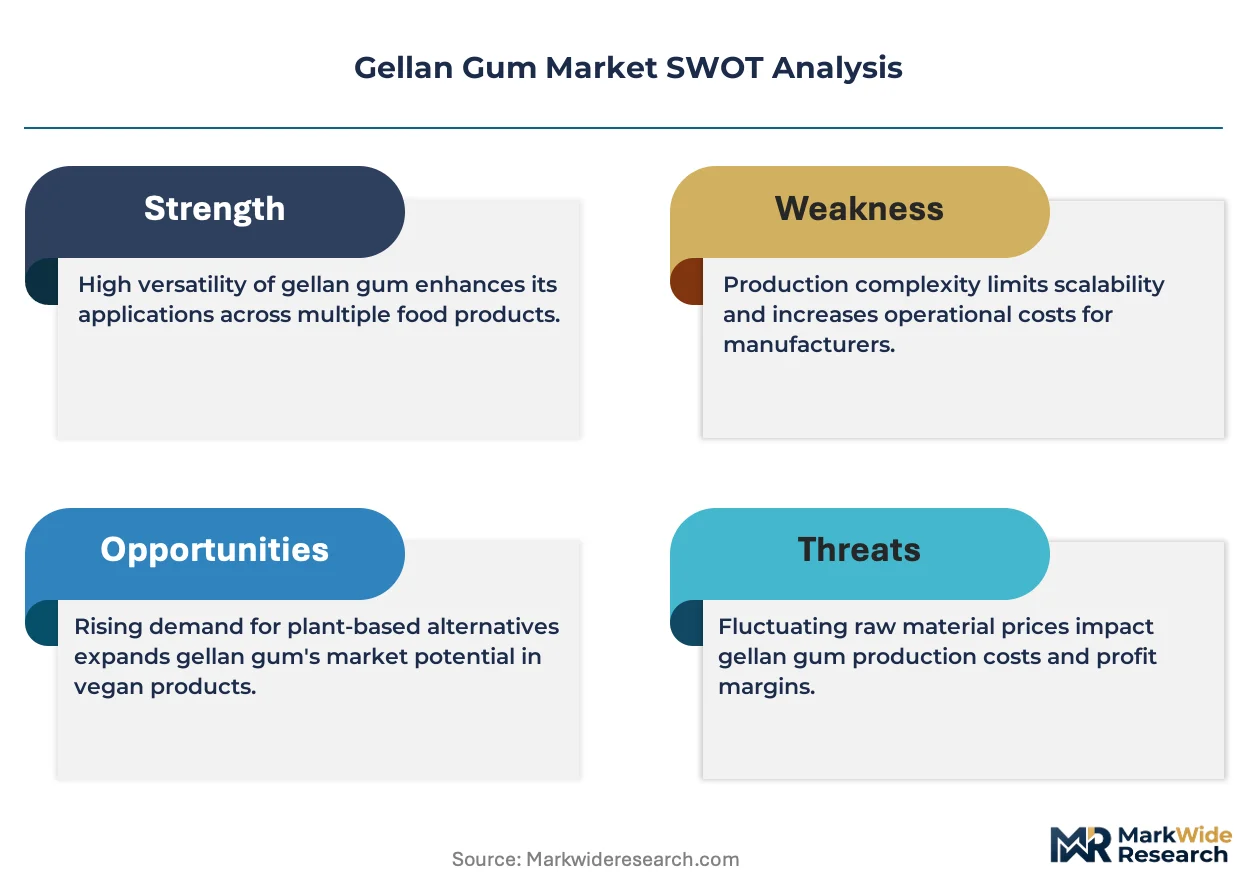
The primary structural force shaping the market is the demand for specific textural properties in plant-based foods. This elevates the functional distinction between high acyl and low acyl gellan gum from a technical detail to a central market driver.
Growth Catalysts
- Plant-Based Demand:The expansion of dairy alternatives and vegan product lines directly increases the need for high-performance gelling and stabilizing agents.
- Clean-Label Alignment:Gellan gum's origin from fermentation meets consumer preference for minimally processed, recognizable ingredients, fitting within clean-label formulation strategies.
- Production Economics:Significant fermentation capacity, particularly in China, creates economies of scale that improve cost-competitiveness against other hydrocolloids in certain applications.
Market Restraints
- Substitution Pressure:Competition from other hydrocolloids like xanthan gum, carrageenan, and pectin remains a significant restraint, especially in price-sensitive food processing applications.
- Fermentation Cost:Production costs are linked to the price of fermentation inputs like glucose, making the final product sensitive to commodity market volatility.
- Technical Specificity:The functional differences between high and low acyl types require specialized formulation knowledge, which can be a barrier for smaller food manufacturers.
Strategic Opportunities
- Pharmaceutical Delivery:Emerging use in pharmaceutical applications for controlled-release drug delivery systems and in-situ gelling ophthalmic solutions presents a high-value opportunity.
- Geographic Expansion:Underpenetrated food processing markets in Southeast Asia and Latin America offer new growth avenues as consumer diets shift toward convenience foods.
- Hybrid Texturants:Developing synergistic blends of gellan gum with other texturants like starches or proteins can create novel functionalities and textures for premium products.
Industry Challenges
- Batch Consistency:Maintaining consistent quality and functional properties from one fermentation batch to another is a persistent operational challenge requiring stringent process controls.
- Formulation Expertise:A scarcity of food scientists with deep expertise in hydrocolloid interactions limits the speed of new product development for end-users.
- Regulatory Harmonization:Divergent national regulations on permissible use levels and applications beyond basic safety approvals from bodies like the FDA or EFSA create trade friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gellan Gum Market |
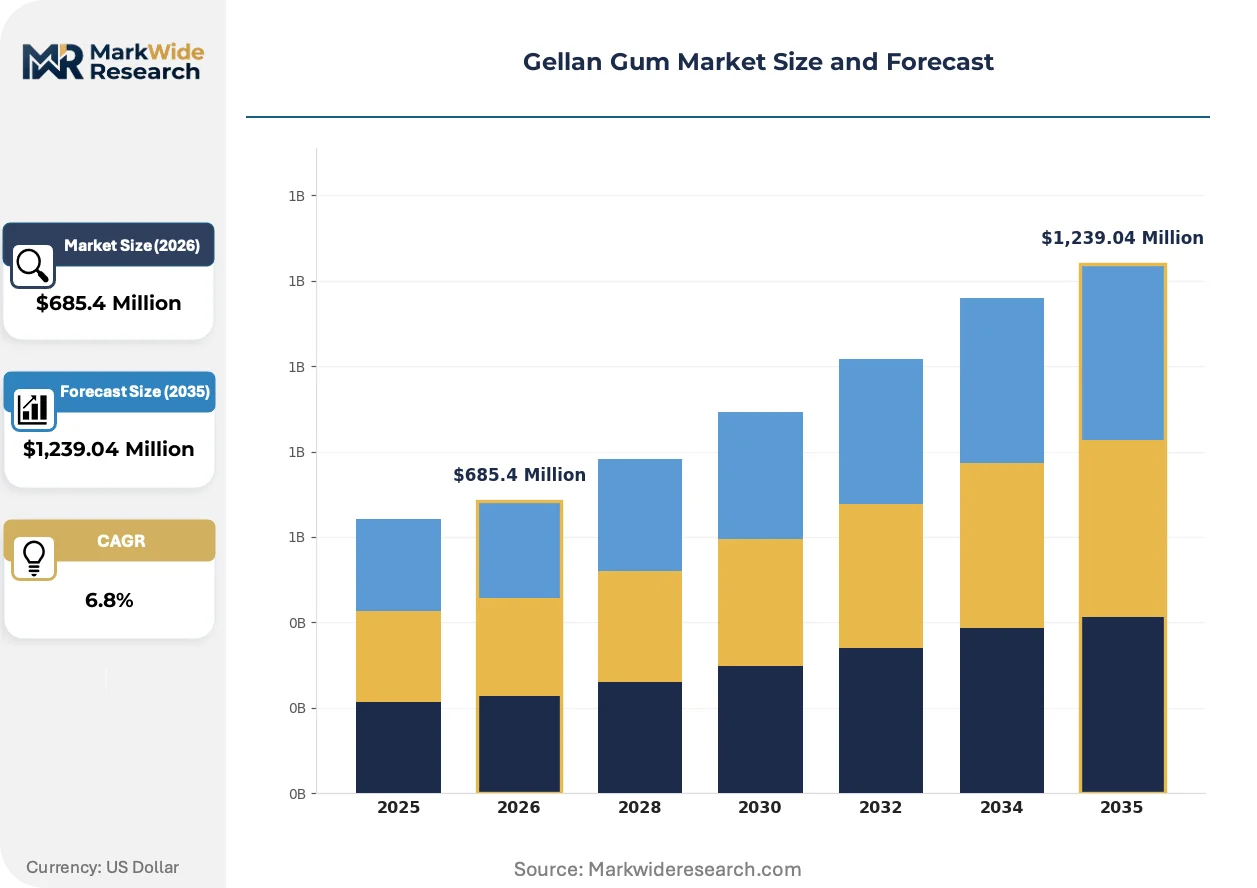
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Acyl Gellan Gum, Low Acyl Gellan Gum, Native Gellan Gum, Modified Gellan Gum Application: Dairy Alternatives, Confectionery, Bakery, Pharmaceuticals, Personal Care End Use Industry: Food Processing, Cosmetics Manufacturing, Pharmaceutical Production, Agriculture, Animal Nutrition Form: Powder, Granules, Liquid Concentrate, Dry Film |
| Companies Covered | CP Kelco, Cargill, Ingredion, DowDuPont, Fufeng Group, Dancheng Caixin Sugar Industry, Koninklijke DSM, Biopolymer International, Jungbunzlauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gellan Gum Market Strategic Shifts & Innovations
Formulation science is converging with consumer sensory expectations, creating a new competitive axis based on textural performance. Success now hinges on mastering the biotechnical and chemical nuances of hydrocolloids to deliver specific mouthfeels in complex food systems.
Precision fermentation allows for the targeted production of gellan gum variants with highly consistent and predictable functionalities. Food manufacturers in the premium vegan and dairy-alternative segments are rapidly adopting these specialized grades. This advanced biomanufacturing is overtaking less predictable, conventional batch fermentation, enabling customized texturant solutions previously unattainable at scale.
Heightened regulatory scrutiny from bodies like the European Food Safety Authority (EFSA) is a defining trend. Its ongoing re-evaluation of all food additives, under Regulation (EC) No 1333/2008, requires extensive safety and purity data from producers. This affects the confectionery and dairy alternative segments most, forcing formulators to prioritize suppliers with robust compliance documentation.
Consumer purchasing criteria are shifting toward a "texture-first" evaluation, especially in categories like plant-based yogurt and nutritional beverages. This pattern disrupts traditional procurement focused solely on ingredient cost, favoring suppliers who provide deep formulation expertise. The trend is most pronounced in developed North American and European food markets.
Gellan Gum Market Segmentation
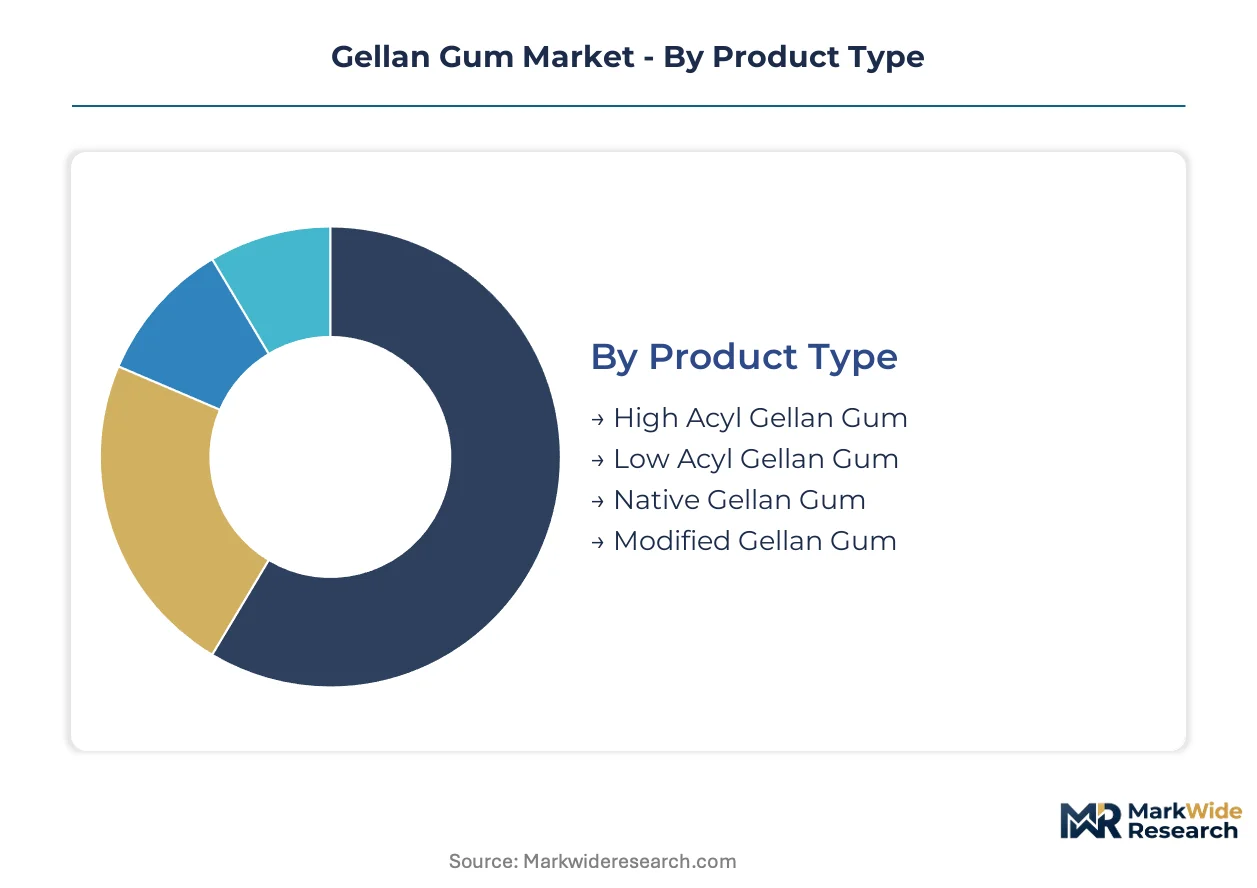
The Gellan Gum Market structure reflects diverse functional requirements across multiple end-use sectors. Understanding these segmentations is critical for producers to align product development with specific application needs and for formulators to select optimal gellan gum variants for desired textural outcomes.
Product Type:
Navigating the product type segment requires careful consideration of regulatory approvals, as the specific chemical modifications can influence certification burdens from bodies like the US FDA and European Food Safety Authority (EFSA).
- High Acyl Gellan Gum:This variant retains all its acyl groups, producing soft, elastic gels with good suspension properties. Demand concentrates in the dairy alternatives sector, where it provides a fluid gel texture crucial for plant-based yogurts and beverages.
- Low Acyl Gellan Gum:Produced by removing acyl groups, this type forms firm, brittle gels with excellent clarity and heat stability. Its primary demand comes from the confectionery industry, providing desired chewiness in gummies and jellies.
- Native Gellan Gum:This is the unmodified form of gellan gum, directly obtained from fermentation before any deacylation process. It offers a balance of gelling and texturizing properties suitable for various food applications.
- Modified Gellan Gum:This encompasses gellan gum treated to enhance specific characteristics like solubility, gel strength, or stability for specialized industrial uses.
Leading the category by volume: Low Acyl Gellan Gum. Growing fastest: High Acyl Gellan Gum.
Application:
The suitability of gellan gum for various applications determines its market penetration and value capture. Different industries require distinct gelling and stabilizing properties, influencing formulation strategies.
- Dairy Alternatives:Gellan gum provides crucial texture and stability in plant-based milk, yogurts, and cheeses, preventing ingredient separation. The expansion of vegan product lines in North America and Europe directly increases demand for high-performance gellan gum.
- Pharmaceuticals:This application leverages gellan gum for controlled-release drug delivery systems and in-situ gelling ophthalmic solutions. High-value opportunities exist in specialized medical formulations requiring precise viscosity and gelation.
- Confectionery:Gellan gum acts as a gelling agent in various sweets, including jellies, gummies, and fruit preparations, delivering a firm yet melt-in-mouth texture.
- Bakery:In bakery products, gellan gum improves moisture retention, enhances texture, and extends shelf life, particularly in gluten-free formulations.
- Personal Care:Gellan gum functions as a thickener, stabilizer, and emulsifier in cosmetics and personal care products like lotions and creams.
Demand for specific textural properties drives segment expansion across the application landscape.
End Use Industry:
The maturity and scale of various end-use industries dictate the volume and specificity of gellan gum procurement. Each industry presents unique challenges and opportunities for ingredient suppliers.
- Food Processing:This industry represents the largest end-use segment, utilizing gellan gum extensively as a gelling, stabilizing, and texturizing agent in diverse food products. The shift towards plant-based foods in European markets significantly impacts this segment.
- Pharmaceutical Production:Gellan gum finds use in drug encapsulation, excipients, and ophthalmic preparations due to its biocompatibility and gelling properties. This sector demands stringent purity standards and regulatory compliance from suppliers.
- Cosmetics Manufacturing:Gellan gum serves as a rheology modifier and emulsion stabilizer in a wide range of personal care and beauty products.
- Agriculture:In agriculture, gellan gum is used in seed coatings, controlled-release fertilizers, and as a binding agent in animal feed.
- Animal Nutrition:Gellan gum improves texture and stability in pet foods and livestock feed, enhancing palatability and nutrient delivery.
Innovation in product formulation distinguishes end-use industry requirements for gellan gum.
Form:
The physical form of gellan gum influences its ease of integration into manufacturing processes and its functional performance in final products. Processing efficiency is a key consideration for end-users.
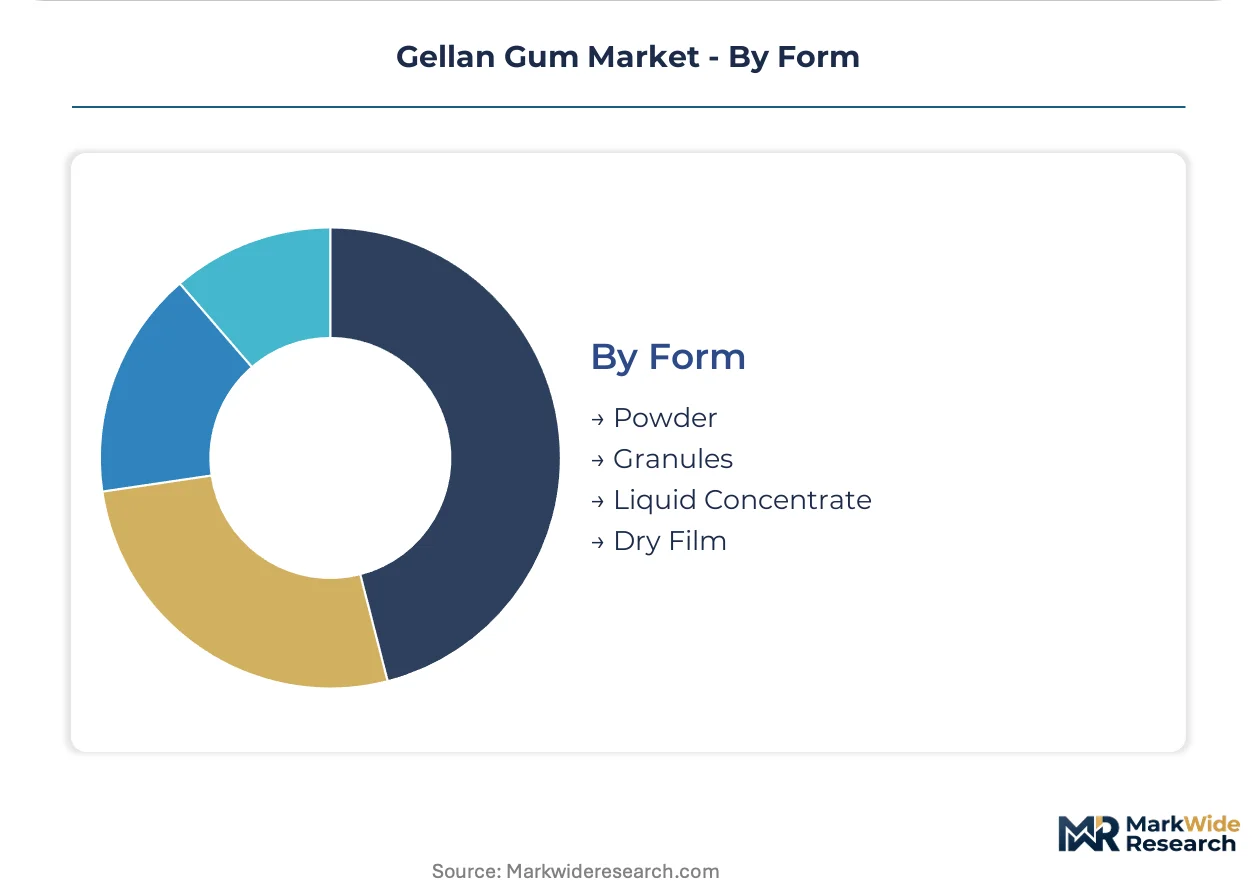
- Powder:The most common form, powdered gellan gum offers ease of storage, transport, and precise dosing in various formulations. It is widely used across food processing and pharmaceutical industries for its versatility.
- Liquid Concentrate:This form provides enhanced dispersibility and solubility, simplifying the incorporation of gellan gum into liquid-based formulations. It is preferred in applications requiring rapid hydration or continuous processing.
- Granules:Granular gellan gum offers improved flowability and reduced dust during handling compared to fine powders. It is often used in applications requiring controlled dissolution.
- Dry Film:Gellan gum dry films are specialized forms used in niche applications such as edible coatings, transdermal patches, or specific packaging solutions.
The choice of gellan gum form impacts processing efficiency and final product characteristics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in China drive significant gellan gum production, leveraging cost efficiencies and large domestic demand. These zones foster an environment for large-scale fermentation, positioning China as a global supply anchor. This concentration influences supply dynamics for various end-use industries worldwide.
China
China's vast domestic market consumes substantial gellan gum in dairy alternatives and confectionery. The country's GB standards rigorously control food additive quality and permissible use. Production hubs in provinces like Shandong leverage significant fermentation capacity to supply global markets.
United States
United States demand for gellan gum rises from the expanding plant-based food sector and clean-label ingredient preferences. The US FDA enforces rigorous safety and purity standards for hydrocolloids in food applications. Food innovation centers in California drive new product development for specialized gellan gum grades.
Germany
Germany's food processing sector requires high-performance gellan gum for sophisticated textures in dairy alternatives and confectionery. The European Food Safety Authority (EFSA) continues its re-evaluation of E418, influencing formulation strategies across the continent. Research institutions in Bavaria focus on biopolymer science, advancing gellan gum's functional properties.
India
India's expanding packaged food industry and rising consumer income create a substantial market for gellan gum. The Food Safety and Standards Authority of India (FSSAI) oversees the approval and usage of food additives. Food ingredient manufacturers in Maharashtra are actively integrating gellan gum into various convenience food formulations.
Brazil
Brazil's large consumer market shows increasing demand for gellan gum in processed foods and beverages, including plant-based options. ANVISA, the national health surveillance agency, sets regulatory standards for food additive use in the country. Food and beverage processors in São Paulo lead the adoption of gellan gum for texture and stability enhancements.
Gellan Gum Market Key Industry Players
Top-tier vendors anchor the specialized gellan gum segment, while large-scale producers compete on volume and cost efficiency. The market structure features specialized hydrocolloid producers, diversified ingredient suppliers, and fermentation-focused manufacturers. Specialized producers develop application-specific grades for premium markets. Diversified players integrate gellan gum into broader texturizing solutions. Competitive moves include significant fermentation capacity expansion and strategic portfolio diversification.
Within the specialized hydrocolloid tier, CP Kelco exemplifies a focus on high-performance, application-specific gellan gum grades, catering to precise formulation needs. Fufeng Group, a prominent Chinese enterprise, represents the large-scale fermentation capacity that drives cost-competitive production, influencing global supply dynamics. Cargill, a global ingredient supplier, occupies a position integrating gellan gum within its extensive portfolio of texturizing solutions, serving a broad customer base. These companies collectively shape the market's innovation trajectory and product availability across diverse end-use sectors.
| Leading Market Players |
|---|
| CP Kelco |
| Cargill |
| Ingredion |
| DowDuPont |
| Fufeng Group |
| Dancheng Caixin Sugar Industry |
| Koninklijke DSM |
| Biopolymer International |
| Jungbunzlauer |
| Others |
Cost & Logistics Intelligence
Plant-based food manufacturers increasingly rely on contract-based pricing for gellan gum. This ensures supply stability and consistent quality for their specialized formulations.
Pricing Analysis
Premium pricing for short lead times reflects the urgent need for specialized gellan gum grades. Contract-based long-term offtake dominates for larger food processors. Quality grade, specifically high acyl versus low acyl variants, and regulatory certifications like EFSA E418 designation, drive price differentiation. Pricing softness stems from competition against other hydrocolloids like xanthan gum. Smaller food manufacturers exhibit higher price sensitivity, while large dairy alternative producers prioritize consistent supply and specific functional properties.
Supply Chain Analysis
Direct sales channels and specialized distributors manage the flow of gellan gum to end-users. Production predominantly concentrates in China, leveraging significant fermentation capacity, with some specialized output from the United States. The supply chain depends on glucose as a primary fermentation input. Commodity price volatility for glucose presents a structural risk. This ensures precise delivery of application-specific gellan gum grades to food processing and pharmaceutical clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gellan gum market is becoming a vertical-integration race, as key players pursue in-house fermentation capacity. This strategy aims to control quality, secure raw material supply, and optimize production costs.
For Market Incumbents:Hedge against commodity price volatility by securing long-term glucose supply contracts. Incumbents must also diversify fermentation input sources and invest in bioprocess R&D for alternative feedstocks. This counters substitution pressure from other hydrocolloids. Strategic acquisitions of smaller specialized producers can consolidate market share and expand application expertise.
For New Entrants and Emerging Players:Launch via direct-to-customer technical sales teams targeting emerging food categories. New entrants should focus on niche applications like hybrid texturants or specialized pharmaceutical delivery systems. The pharmaceutical application segment offers high-value entry points due to precise functional requirements. Emphasize custom formulation support and rapid prototyping for novel product development.
For Investors and Strategic Acquirers:The window for entry favors patient capital seeking long-term growth in specialty ingredients. Long-term viability over the next decade depends on biomanufacturing advancements and regulatory clarity from bodies like the EFSA. Target specialized hydrocolloid producers with strong R&D pipelines for application-specific gellan gum variants. Increased M&A activity in the precision fermentation sector serves as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Leverages cost efficiencies and addresses rising domestic and global demand for gellan gum. |
| Precision Fermentation Investment | Enables targeted production of consistent, high-performance gellan gum variants for premium segments. |
| Hybrid Texturant Development | Creates novel functionalities and textures, meeting evolving consumer preferences in plant-based foods. |
| Regulatory Compliance Enhancement | Ensures market access and builds trust with food manufacturers navigating EFSA and US FDA requirements. |
| Geographic Market Penetration | Taps into underpenetrated food processing markets in Southeast Asia and Latin America. |
Research Approach
Academic journals, industry reports, and company financial disclosures formed the secondary backbone for this market analysis. Primary interviews with R&D directors, procurement managers, and regulatory affairs specialists at food manufacturers and hydrocolloid producers provided critical insights. This approach combined bottom-up market sizing with top-down validation, triangulating data points across various sources.
Historical trendline analysis and regression modeling established baseline growth trajectories across the analysis window. Segmentation dimensions included product type, application, end-use industry, and regional consumption patterns. Compound annual growth rates were derived by projecting demand drivers and supply-side capacities. Key forecast inputs included plant-based food consumption growth and fermentation input costs.
Regulatory changes, commodity price shifts, and technological breakthroughs are the dominant revision risks for market forecasts. All forecasts reflect explicit assumptions regarding market dynamics and competitive landscapes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Japan Food Acidulants Market