
 Granola Bars Market | 2026-2036
Granola Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Granola Bars Market Analysis
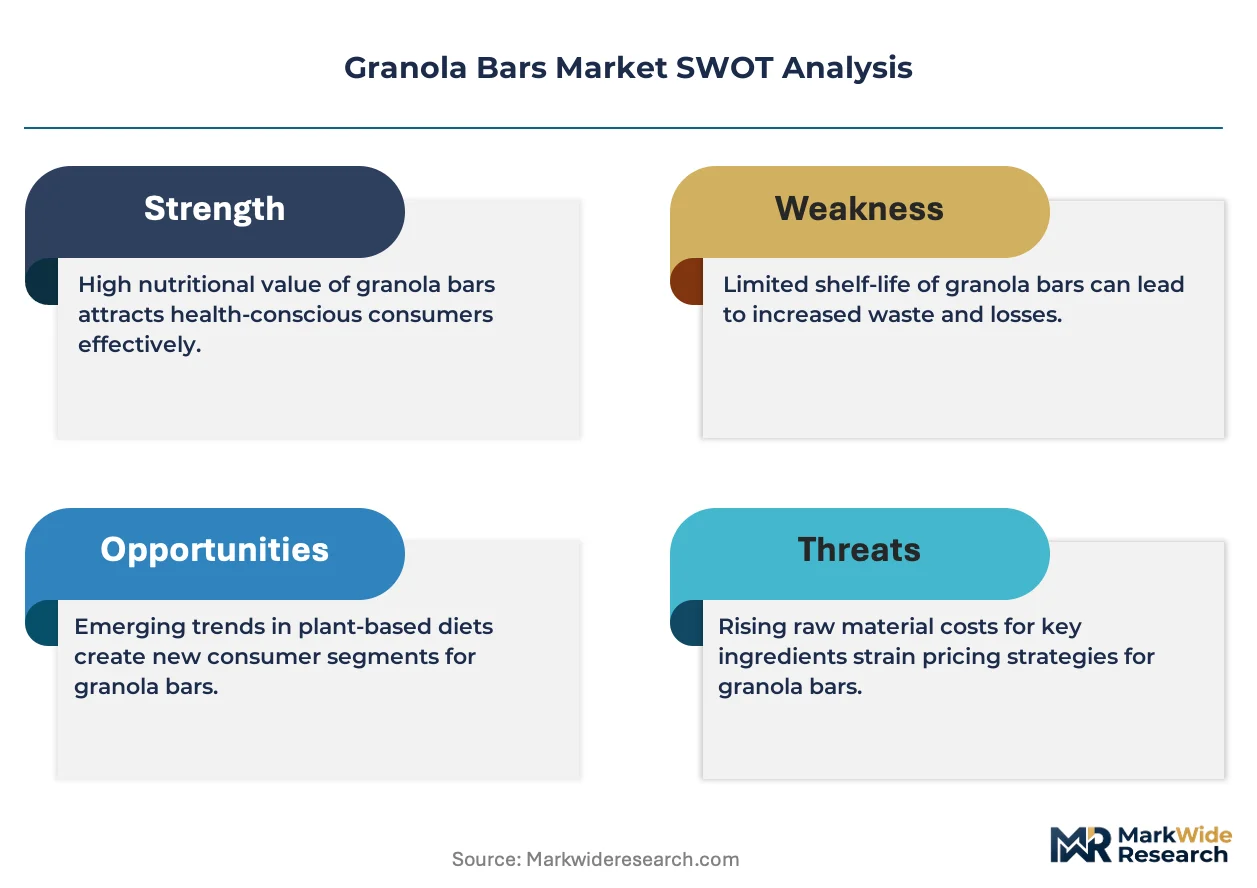
Single-serve to multi-pack bundling is realigning how households stock pantry staples versus impulse purchases. General Mills leverages its cereal supply chain to anchor ingredient costs across chewy and crunchy bar lines. Mondelez International competes through global distribution density, while Clif Bar & Company specializes in organic-certified formulations that command shelf space in health food stores.
Granola bars are baked or cold-pressed cereal bars composed of rolled oats, sweeteners, and binders, typically containing 100–250 calories per serving and formulated for shelf-stable portability. Chewy bars dominate volume due to lower manufacturing complexity and broader child-appeal, while protein bars capture margin pools as sports nutrition overlaps with mainstream snacking. Organic bars remain supply-constrained by certified ingredient availability, constraining expansion relative to conventional lines.
The FDA governs nutritional labeling and health claim substantiation, while USDA Organic certification shapes premium tier access; in Europe, EFSA scrutiny of glycemic index claims filters which products enter EU retail. Stakeholders must monitor evolving sugar taxation frameworks and front-of-pack labeling mandates that will determine formulation viability and retail placement decisions.
Market Dynamics
Clean-label reformulations and tightening nutritional claims oversight by the FDA and EFSA are compelling manufacturers to substantiate ingredient sourcing, fundamentally altering how granola bar portfolios are architected and marketed.
Growth Catalysts
- Protein fortification technology:Micro-encapsulation of plant proteins enables taste-masked formulations that expand the addressable base beyond sports nutrition into mainstream snacking.
- FDA health claim substantiation:Validated structure-function claims on fiber and heart health create permissible differentiation in US retail channels.
- Urban millennial concentration:Dense coastal metro corridors in the United States generate recurring subscription demand for portable, portion-controlled breakfast alternatives.
Market Restraints
- Certified organic supply scarcity:Limited acreage under USDA Organic cultivation constrains expansion of premium-tier product lines relative to conventional formulations.
- Input cost volatility:Rolled oats and honey prices fluctuate with North American commodity harvest cycles, compressing margin predictability.
- Substitution elasticity:Fresh prepared snacks and refrigerated protein alternatives in convenience retail capture occasion-based purchasers.
Strategic Opportunities
- Direct-to-online subscription channels:Recurring revenue models bypass slotting fee structures and capture household pantry-stocking behavior.
- EU front-of-pack labeling mandates:Nutri-Score alignment creates first-mover advantage for reformulated low-sugar lines entering continental European retail.
- Cold-pressed processing convergence:Raw-food positioning intersects with sports nutrition to unlock premium price tiers in health food store channels.
Industry Challenges
- Clean-label R&D timelines:Removing artificial preservatives while maintaining shelf stability demands extended formulation cycles and sensory testing protocols.
- Cross-functional talent scarcity:Combined expertise in food science and regulatory navigation is concentrated among a limited pool of specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granola Bars Market |
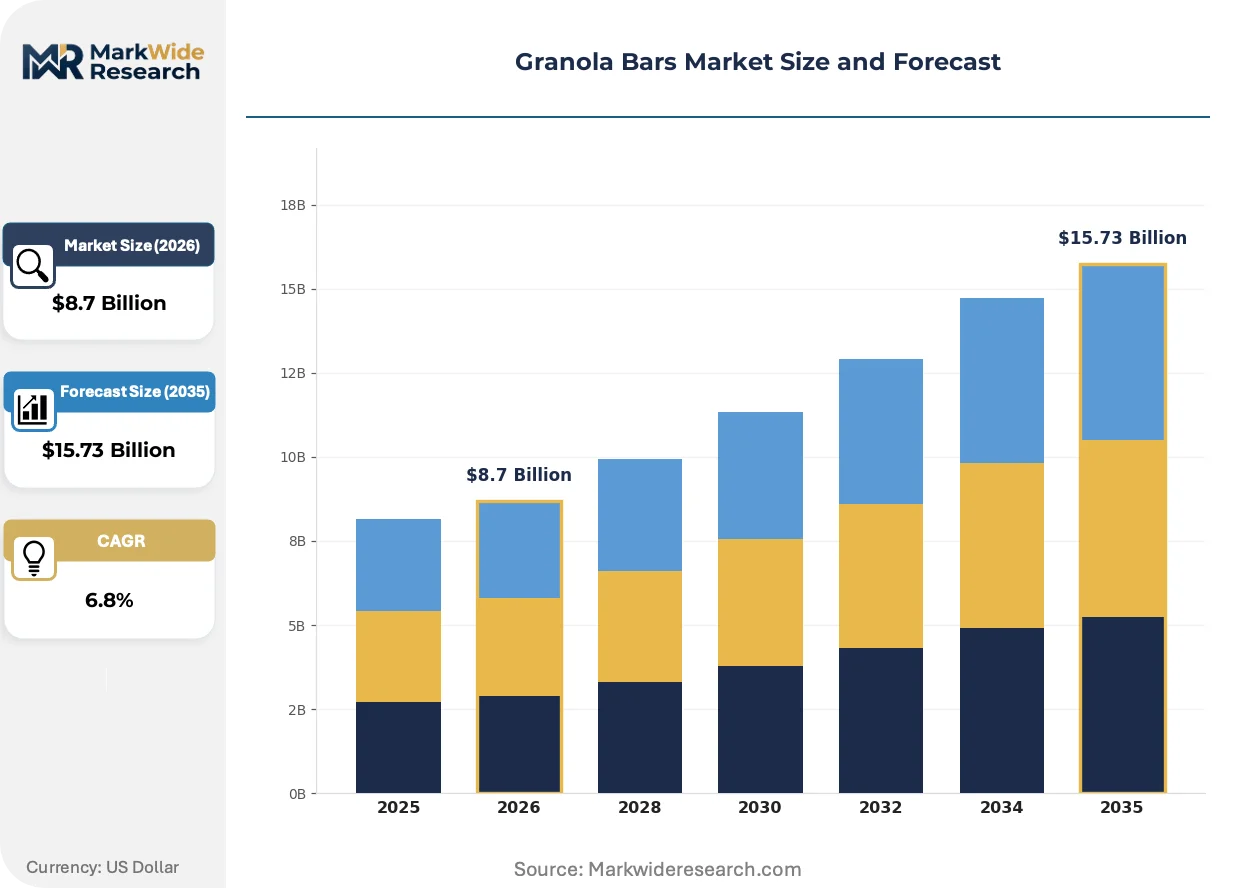
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewy Bars, Crunchy Bars, Protein Bars, Organic Bars Flavor Profile: Chocolate, Peanut Butter, Fruit & Nut, Vanilla Almond Packaging Type: Single Serve, Multi-Pack, Bulk Packaging, Resealable Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores |
| Companies Covered | Mars, McKee Foods, General Mills, Blue Diamond Growers, Mondelez International, PepsiCo, Clif Bar & Company, MadeGood Foods, Kellanova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granola Bars Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape how granola bars are developed, certified, and purchased across retail and digital channels.
Precision fermentation of alternative sweeteners is modularizing the sweetener layer of granola bar formulations. Clean-label brands adopt these inputs to reduce added sugar declarations while maintaining binding functionality. The technology is compressing the reformulation cycle from 18 months to under 12 months for mid-tier manufacturers.
EFSA scrutiny of glycemic index claims is filtering which products secure EU retail placement. Manufacturers must generate clinical substantiation or abandon specific positioning language. Protein-forward lines targeting athletic consumers face the highest compliance burden and are consolidating claims around validated nutrient profiles.
Pantry-loading behavior is displacing single-serve impulse purchasing in suburban households. Multi-pack bundling through club retail and subscription platforms captures volume commitment. This shift concentrates demand in the United States, where warehouse club penetration and direct-to-consumer infrastructure are most mature.
Granola Bars Market Segmentation
Granola bar manufacturers architect portfolios around four intersecting dimensions that determine margin capture and channel access. Product type and flavor profile dictate formulation investment, while packaging and distribution choices shape household penetration versus impulse conversion rates.
Product Type:
Supply concentration clusters around manufacturing equipment flexibility and ingredient sourcing scale rather than brand equity alone.
- Chewy Bars:Rolled oat and binder formulations extruded through continuous processing lines yield softer textures with 12-month shelf stability. United States suburban households stock multi-pack configurations as breakfast replacements, though child-appeal limits premium pricing power.
- Protein Bars:Micro-encapsulated whey and plant protein isolates elevate caloric density to 200-300 calories while masking chalky off-notes. Sports nutrition consumers in coastal US metro corridors drive recurring subscription demand, compressing customer acquisition costs relative to conventional lines.
- Crunchy Bars:Baked oat clusters with lower moisture content require precision humidity control during production.
- Organic Bars:USDA Organic certification constrains expansion due to certified acreage scarcity and dual-source ingredient requirements.
Today's leader: Chewy Bars. Tomorrow's challenger: Protein Bars.
Flavor Profile:
Application occasions split between indulgence positioning and functional snacking, with formulation complexity varying by binding compatibility.
- Chocolate:Cocoa powder and chip inclusions demand fat bloom stabilization through tempered chocolate coatings. United States convenience store channels capture impulse purchasers seeking dessert substitutes.
- Peanut Butter:Roasted nut paste provides natural binding and protein fortification without additive costs. Southeast US households show disproportionate pantry-loading behavior for this profile.
- Fruit & Nut:Dried cranberry and almond combinations target clean-label positioning with visible ingredient differentiation.
- Vanilla Almond:Lighter flavor intensity appeals to adult breakfast replacement occasions.
Chocolate dominates velocity. Peanut Butter climbs fastest on protein-forward reformulation.
Packaging Type:
Volume economics favor formats that minimize per-unit material cost while preserving shelf stability through distribution.
- Single Serve:Individually wrapped 1.2-2.0 oz bars optimize convenience store and vending placement. Urban commuter corridors in the United States generate highest turnover rates for this format.
- Multi-Pack:Club retail configurations of 6-12 units capture household commitment and reduce packaging cost per serving. Warehouse club penetration in the United States concentrates demand here.
- Bulk Packaging:Foodservice and institutional channels require extended shelf life through nitrogen flushing.
- Resealable Pouches:Flexible film structures with zip-lock closures target family snacking occasions.
Multi-Pack commands volume. Resealable Pouches gain on pantry-stocking behavior.
Distribution Channel:
Margin structure varies sharply by slotting fee burden and inventory velocity requirements across retail formats.
- Supermarkets:Center-store placement demands promotional calendar participation and category management fees. United States conventional grocery chains remain the volume anchor despite share erosion.
- Online Retail:Direct-to-consumer subscription models bypass slotting structures and capture household replenishment data. United States coastal metros show highest subscription conversion rates.
- Convenience Stores:Front-counter placement drives impulse conversion with limited SKU count.
- Health Food Stores:Organic and cold-pressed lines command premium positioning through educated consumer self-selection.
Supermarkets hold volume. Online Retail expands most quickly on subscription infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Granola bar commercialization traces its roots to California health food movements of the 1970s, where cold-pressed oat formulations first gained traction among outdoor recreation communities. This heritage shapes contemporary demand geography, with coastal metropolitan clusters driving premium-tier adoption while heartland regions anchor volume consumption.
United States
Subscription-based direct-to-consumer platforms and warehouse club multi-packs capture divergent household behaviors, with coastal metros favoring protein-forward lines and suburban markets prioritizing child-appeal chewy formats. FDA nutritional labeling enforcement and structure-function claim substantiation requirements filter permissible marketing language. Austin, Texas and Boulder, Colorado host dense concentrations of clean-label startups testing cold-pressed processing innovations.
Canada
Health Canada front-of-pack labeling proposals and sugar reduction targets are accelerating reformulation timelines for cross-border product lines. Toronto and Vancouver metropolitan corridors concentrate demand for organic-certified bars, constrained by limited domestic certified oat acreage. Quebec's dairy processing infrastructure supports whey protein isolate supply for sports nutrition positioned lines.
Germany
EFSA glycemic index claim scrutiny and Nutri-Score labeling mandates are reshaping permissible positioning for products entering continental European retail. Munich and Berlin health food store channels command premium placement for cold-pressed and raw-food positioned bars. German consumers demonstrate higher willingness-to-pay for verified low-sugar formulations relative to neighboring markets.
United Kingdom
Ofcom broadcast advertising restrictions on high-fat-salt-sugar products constrain marketing reach for conventional chewy lines targeting family households. London's financial district commuter corridors sustain impulse demand for single-serve protein bars through convenience retail. The UK's departure from EU regulatory alignment creates parallel compliance obligations for manufacturers serving both markets.
Australia
FSANZ nutrition content claims standards and health star rating systems determine retail placement eligibility for imported and domestic lines alike. Sydney and Melbourne urban centers generate recurring demand for portable breakfast alternatives among time-constrained professional demographics. Australian consumers show elevated preference for visible ingredient differentiation through fruit and nut inclusions.
Granola Bars Market Vendor Landscape
The competitive structure tilts toward diversified consumer packaged goods conglomerates with cereal supply chain leverage. General Mills and Mondelez International anchor volume tiers through distribution density and slotting fee capacity, while specialized organic operators occupy premium health food channels. Three archetypes dominate: diversified food conglomerates with cross-category procurement scale, organic-certified specialists with supply-constrained ingredient sourcing, and private-label contract manufacturers serving retail-owned brands. Consolidation pressure operates through M&A activity targeting organic certification assets and strategic partnerships securing alternative protein supply.
Among diversified packaged goods operators, General Mills, Mondelez International, and Kellanova represent scale-driven archetypes with cross-category procurement leverage and conventional retail channel dominance. Mars and PepsiCo occupy parallel positions with beverage and confectionery supply chain adjacencies. Clif Bar & Company exemplifies the organic-certified specialist model with supply-constrained expansion relative to conventional lines. MadeGood Foods represents emerging challenger positioning within allergen-free and school-safe formulation segments.
| Leading Market Players |
|---|
| Mars |
| McKee Foods |
| General Mills |
| Blue Diamond Growers |
| Mondelez International |
| PepsiCo |
| Clif Bar & Company |
| MadeGood Foods |
| Kellanova |
| Others |
Supply Flow & Price Mechanics
Rolled oats futures on the Chicago Mercantile Exchange cascade through three distinct pricing tiers, binding conventional chewy bars to commodity harvest cycles while insulating organic and protein-fortified lines through certified ingredient premiums and micro-encapsulation technology costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and protein content. USDA Organic certification and micro-encapsulated protein isolates command shelf price premiums, while conventional chewy bars face cost compression from private-label competition. Price differentiation intensifies as honey and nut butter input costs fluctuate with North American agricultural output. Value-conscious suburban households exhibit highest price sensitivity, whereas coastal metro professionals purchasing subscription protein bars demonstrate inelastic demand.
Supply Chain Analysis
Dual-sourcing requirements for USDA Organic certification compel manufacturers to qualify multiple oat suppliers across the United States and Canada, constraining expansion when certified acreage falls short of demand. Honey supply draws from domestic apiary cooperatives and Argentine import channels, while chocolate inclusions source from Côte d'Ivoire and Ghana processing facilities. Single-source vulnerability concentrates in certified organic oat supply, where limited domestic acreage creates allocation bottlenecks. Distribution runs through warehouse club networks and direct-to-consumer subscription platforms, bypassing conventional grocery slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The granola bars market compounds steadily as portable protein fortification penetrates mainstream snacking occasions, with subscription retention rates insulating revenue from impulse-purchase volatility.
For Market Incumbents: Lock in oat supply through backward integration into certified organic acreage or long-term grower contracts, defending against input cost spikes that compress conventional line margins. Secure shelf stability in club retail through exclusive multi-pack configurations, neutralizing private-label encroachment in suburban pantry-loading segments. For New Entrants and Emerging Players: Time-constrained professional households in secondary US metros represent an underserved buyer archetype with limited protein-forward subscription penetration. Cold-pressed processing capabilities unlock health food store placement without competing for conventional grocery slotting fees, while allergen-free formulations capture school-safe segments where incumbents lack dedicated lines. For Investors and Strategic Acquirers: Asymmetric upside sits with organic-certified specialists possessing captive ingredient sourcing and established health food channel relationships. Long-term viability hinges on reformulation agility as FDA and EFSA tighten nutritional claim substantiation. Watch for FDA guidance on structure-function claim enforcement as an inflection indicator for permissible marketing differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses slotting fees and captures household replenishment data for protein-forward lines. |
| USDA Organic Certification Investment | Unlocks premium placement in Whole Foods and natural channel retail with supply-constrained scarcity. |
| Cold-Pressed Processing Scale-Up | Positions raw-food claims in health food stores where EFSA glycemic index scrutiny filters competitors. |
| Multi-Pack Club Retail Exclusivity | Captures suburban pantry-loading behavior through Costco and Sam's Club volume commitments. |
| Precision Fermentation Partnership | Secures alternative sweetener supply for clean-label reformulation under 12-month development cycles. |
Methodological Framework
Coverage spans the United States, Canada, Germany, the United Kingdom, and Australia, with primary inputs from each market informing demand pattern calibration. The study combines structured interviews with brand managers, category buyers at club retailers, supply planners at oat processing cooperatives, and regulatory affairs specialists at FDA and EFSA, cross-referenced against Nielsen retail audit data, USDA organic certification databases, customs import records, and SEC filings from diversified packaged goods operators. Bottom-up volume modeling triangulates against top-down category expenditure estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, flavor profile, packaging configuration, and distribution channel as core segmentation dimensions, with protein fortification technology adoption as an industry-specific overlay. CAGRs derive from historical elasticity patterns applied to projected household penetration rates and per-capita consumption trends, incorporating FDA structure-function claim enforcement timelines and EFSA glycemic index substantiation requirements as regulatory scenario inputs.
Underlying measurement precision varies by segment; protein bars and online retail carry tighter precision than conventional chewy bars and foodservice channels due to data availability from subscription platforms. Forecasts reflect assumptions about oat harvest yields, certified organic acreage expansion, and regulatory claim permissibility. Deviation in FDA enforcement intensity or EFSA Nutri-Score implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Fat Free Meals and Snacks Market
Snacks
Low Fat Sweet Snacks Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Europe Popcorn Market
Snacks
Asia Pacific Snack Food Market
Snacks
India Snack Bar Market
Snacks
Argentina Snack Bar Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Crackers Market
Snacks
India Energy Bar Market
Snacks
Australia Snack Bar Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Premium Snacks Market
Snacks
Germany Snack Bar Market
Snacks
Savoury Biscuits Market