
 Fruit and Vegetable Chips Market | 2026-2036
Fruit and Vegetable Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable Chips Market Intelligence
Non-GMO Project Verified certification is bifurcating the market, creating distinct tiers for certified and conventional products. PepsiCo, Inc. leverages its extensive distribution network to place its offerings in mainstream retail channels globally. The Hain Celestial Group, Inc. specializes in the organic and natural foods segment, primarily targeting specialty health food stores. Seneca Foods Corporation, in contrast, controls a significant portion of its raw vegetable supply chain through direct farm relationships.
Fruit and vegetable chips are thinly sliced produce processed via baking, dehydration, or vacuum frying to achieve a shelf-stable, crispy texture. The primary commercial purpose is to offer a perceived healthier alternative to traditional potato chips, often with lower fat and higher nutrient retention. Sweet potato chips lead the product type category, valued for their familiar flavor and strong nutritional profile. Demand from the health enthusiasts end-user segment is a primary growth engine, prioritizing clean-label products over conventional snack options.
Food safety and labeling regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern permissible health claims and ingredient declarations. Additionally, China's GB standards impose strict quality and safety requirements on imported food products, directly impacting market access. Future success will hinge on a manufacturer's ability to navigate these complex international trade regulations while meeting consumer demands for sustainable packaging.
Market Dynamics
The central force shaping the fruit and vegetable chips market is the consumer-led push for clean-label, minimally processed snacks. This demand pattern compels manufacturers to innovate in processing technology and supply chain transparency to deliver perceived healthier alternatives to conventional snacks.
Growth Catalysts
- Vacuum Frying Technology:This processing method enables the production of chips with lower fat content and higher nutrient retention compared to traditional frying, directly appealing to the health enthusiast segment seeking superior nutritional profiles.
- Demand from Health Enthusiasts:This specific end-user segment actively seeks out products with clean labels, including non-GMO and organic certifications, creating a strong pull for premium, certified fruit and vegetable chip offerings.
- Market Concentration in Developed Economies:High consumer health consciousness and disposable income levels in countries like the United States and Germany establish concentrated and mature demand centers for premium snack products.
Market Restraints
- Raw Material Price Volatility:The cost and availability of fresh fruits and vegetables are subject to significant seasonal, climatic, and logistical fluctuations, which introduces volatility into production costs and final product pricing.
- Complex Health Claim Regulations:Regulatory bodies like the US FDA and EFSA enforce strict standards for nutritional and health claims on packaging, limiting marketing flexibility and requiring costly substantiation for any stated benefits.
- Substitution from Other Snack Categories:The market faces intense competition from a wide array of snack options, including traditional potato chips, nuts, seeds, popcorn, and snack bars, all vying for the same consumer snacking occasion.
Strategic Opportunities
- Expansion in Emerging Markets:Growing middle-class populations and increasing health awareness in regions such as Southeast Asia and Latin America represent significant, underpenetrated markets for fruit and vegetable chip manufacturers.
- Direct-to-Consumer (DTC) Channels:Leveraging e-commerce platforms and subscription box models allows brands to bypass traditional retail gatekeepers, build direct customer relationships, and test new product innovations with lower risk.
- Exotic and Functional Ingredients:Incorporating novel fruits and vegetables, particularly those with perceived functional benefits like adaptogens or high antioxidant levels, can support the creation of premium, differentiated product lines.
Industry Challenges
- Supply Chain Consistency:Securing a consistent, year-round supply of raw produce that meets stringent quality, size, and ripeness specifications for industrial-scale processing remains a significant operational hurdle for manufacturers.
- Sustainable Packaging Implementation:Developing and sourcing cost-effective packaging materials that are recyclable or compostable while also providing the necessary barrier properties to maintain product crispness and shelf life is a major technical challenge.
- Navigating Certification Labyrinths:The process of obtaining and maintaining multiple distinct certifications, such as organic and Non-GMO Project Verified, for different international markets is both administratively burdensome and financially costly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable Chips Market |
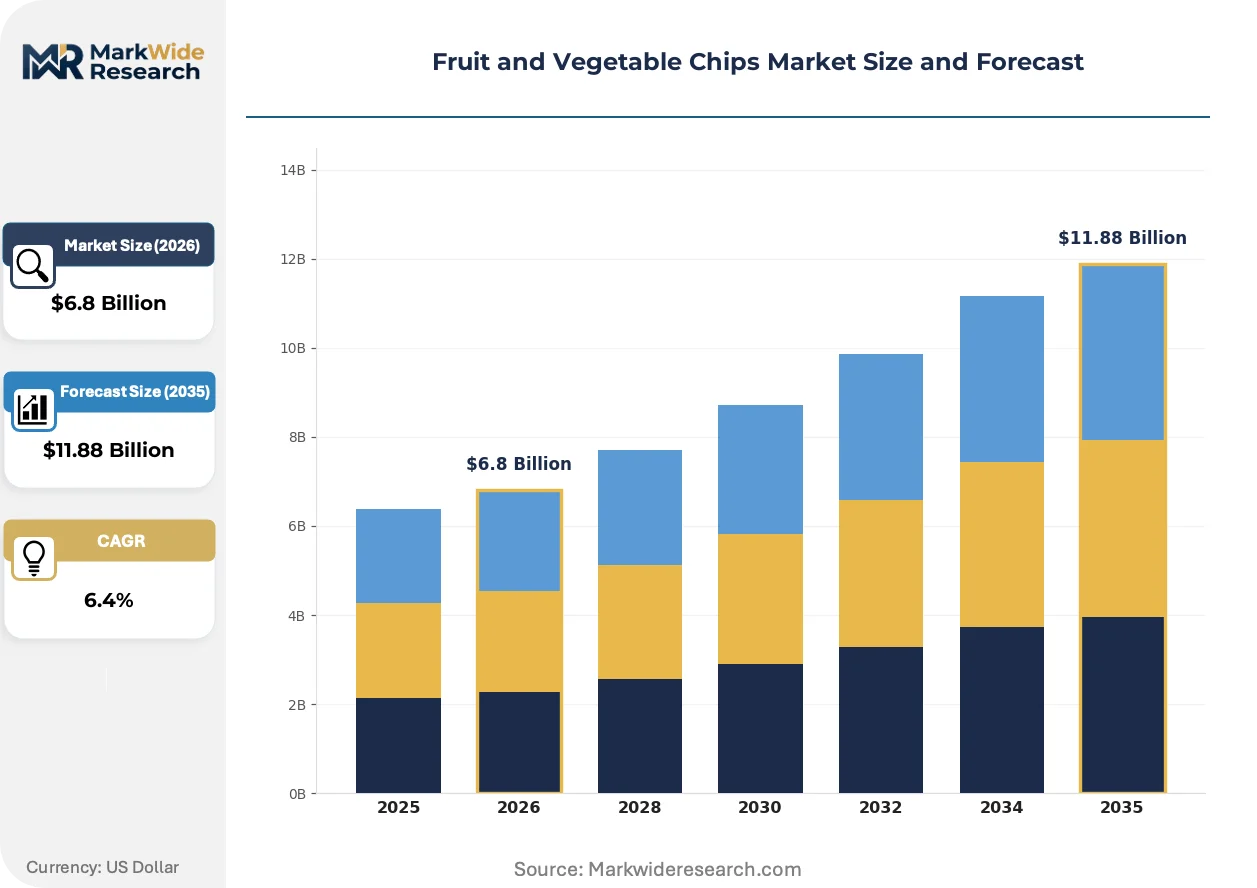
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Potato Chips, Beetroot Chips, Kale Chips, Apple Chips End User: Retail Consumers, Food Service, Health Enthusiasts, Snack Manufacturers Flavor Profile: Spicy, Sweet, Savory, Tangy Packaging Type: Stand-up Pouches, Bags, Cans, Cartons |
| Companies Covered | PepsiCo, Inc., Calbee North America, General Mills, Inc., Kellanova, Seneca Foods Corporation, Hain Celestial Group, Inc., Luke's Organic, Crispy Green, Inc., Rhythm Superfoods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable Chips Market Strategic Shifts & Innovations
Processing advancements are enabling product formulations that align more closely with consumer demand for nutrient density and authenticity. This alignment is redefining the competitive landscape, favoring brands that can effectively communicate superior nutritional value and clean-label attributes through transparent sourcing and innovative production methods.
Vacuum frying is a low-temperature processing technique that preserves more of the original color, flavor, and nutrients of the raw produce. Premium brands and health-focused consumer segments are driving its adoption. This technology is bifurcating the market into higher-priced, nutrient-dense products and conventional, lower-cost baked or dehydrated alternatives, creating distinct value tiers.
Front-of-pack labeling (FOPL) systems, including Europe's Nutri-Score and similar initiatives under consideration by the FDA, are gaining regulatory traction. These policies pressure manufacturers to reformulate products to achieve more favorable nutritional ratings, often by reducing sodium and added sugars. The vegetable chip category is particularly affected, as brands leverage these labels to highlight inherent nutritional benefits.
A pronounced shift in consumer purchasing behavior favors products that carry third-party certifications like organic or Non-GMO Project Verified. This trend is altering shelf-space allocation within mainstream supermarkets, where certified products are increasingly displacing conventional options. This demand-side pull is most visible among consumers in North America and Germany, influencing retailer procurement strategies.
Fruit and Vegetable Chips Market Segmentation
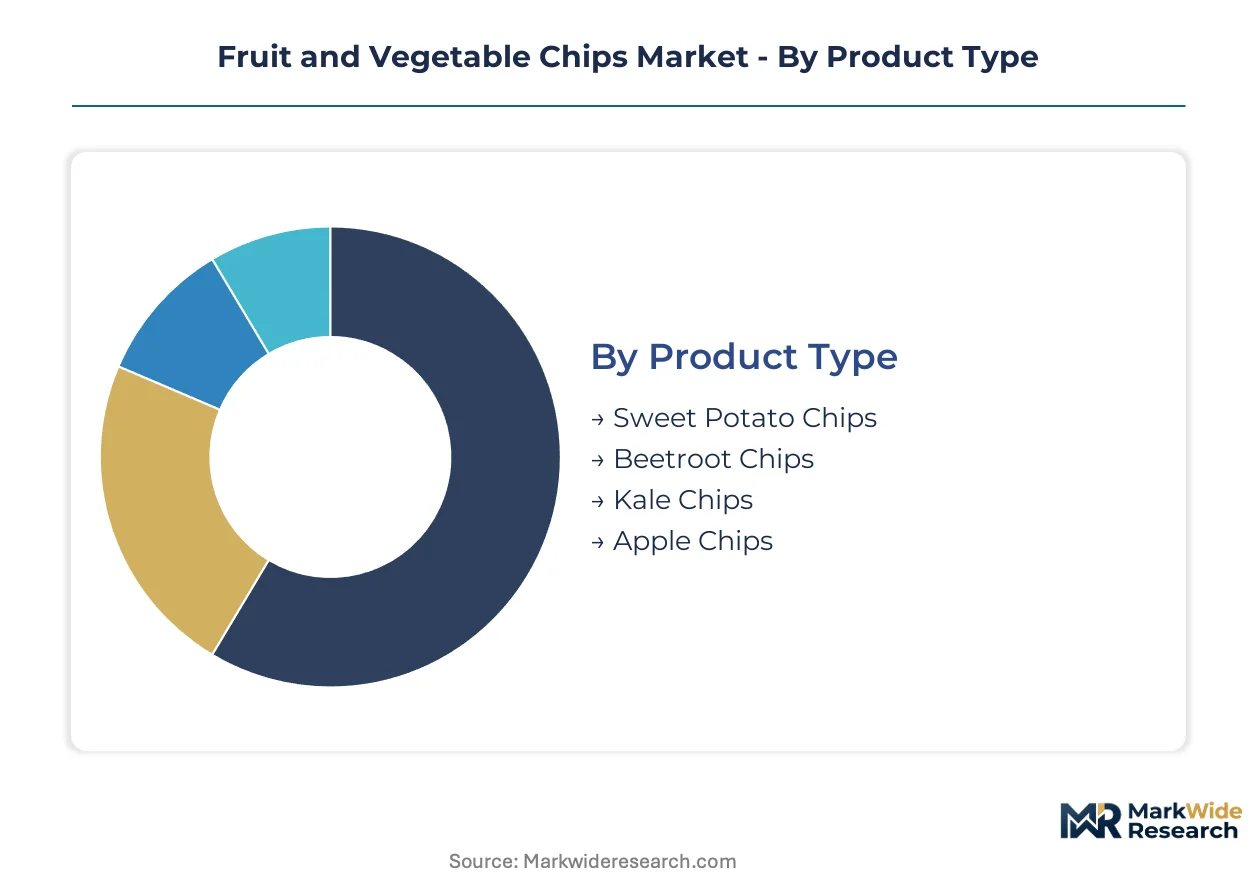
The Fruit and Vegetable Chips Market exhibits diverse segmentation across various attributes, reflecting distinct consumer preferences and manufacturing capabilities. Understanding these segments helps manufacturers tailor product development, marketing strategies, and distribution channels to maximize market penetration and profitability.
Product Type:
Margin pools within product types often concentrate on offerings that command premium pricing due to perceived health benefits or novel ingredients.
- Sweet Potato Chips:These chips are typically processed from thin slices of sweet potato, often vacuum-fried or baked, retaining their natural sweetness and vibrant color. Demand concentrates among health-conscious consumers in the United States, who value their familiar flavor and higher fiber content compared to traditional potato chips.
- Kale Chips:Made from kale leaves coated with seasonings and then baked or dehydrated, these products offer a nutrient-dense, low-calorie snack. Health enthusiasts in Germany and other European markets prioritize kale chips for their clean-label attributes and significant vitamin content.
- Beetroot Chips:These chips provide an earthy flavor and distinctive red hue, appealing to consumers seeking unique vegetable snack options.
- Apple Chips:Dehydrated or baked apple slices offer a naturally sweet and crispy snack, popular among children and those seeking fruit-based alternatives.
The dominant share belongs to Sweet Potato Chips, while Kale Chips are closing the gap fastest.
End User:
Product application and consumption patterns define the end-user segments, influencing packaging formats and distribution logistics.
- Health Enthusiasts:This segment comprises consumers actively seeking snacks with superior nutritional profiles, clean labels, and specific certifications like Non-GMO Project Verified. Their demand directly drives innovation in processing technologies such as vacuum frying and ingredient sourcing transparency.
- Retail Consumers:This broad category includes individuals purchasing fruit and vegetable chips through supermarkets, convenience stores, and online retail channels for household consumption. Volume sales are highest in this segment, driven by everyday snacking occasions and family preferences.
- Food Service:Restaurants, cafes, airlines, and institutional caterers comprise this segment, sourcing chips for inclusion in meals, side dishes, or as standalone snack offerings. Product specifications often emphasize bulk packaging and consistent quality for commercial kitchen use.
- Snack Manufacturers:Some manufacturers procure processed fruit and vegetable chips as ingredients for inclusion in mixed snack packs or other food products.
Health Enthusiasts are driving significant innovation, while Retail Consumers continue to absorb the largest production volumes.
Flavor Profile:
Consumer palate preferences dictate the flavor profile segment, influencing ingredient combinations and seasoning development.
- Savory:These chips feature classic seasoning blends like sea salt, black pepper, or garlic, appealing to a broad consumer base seeking traditional snack experiences. Savory options are a staple in most markets, providing a direct alternative to conventional potato chips.
- Sweet:Often found in fruit chips or root vegetable chips with natural sweetness, these products may also incorporate cinnamon, honey, or other sweet spices. This profile is popular with consumers preferring milder, dessert-like snack choices, particularly in North America.
- Spicy:Chips with added chili, jalapeño, or other heat-inducing spices target consumers who enjoy bold and intense flavor experiences.
- Tangy:This profile includes flavors like vinegar, lime, or sour cream and onion, offering a sharp, zesty taste for specific consumer preferences.
The market diversifies through Savory and Sweet options, with Spicy and Tangy profiles catering to niche preferences.
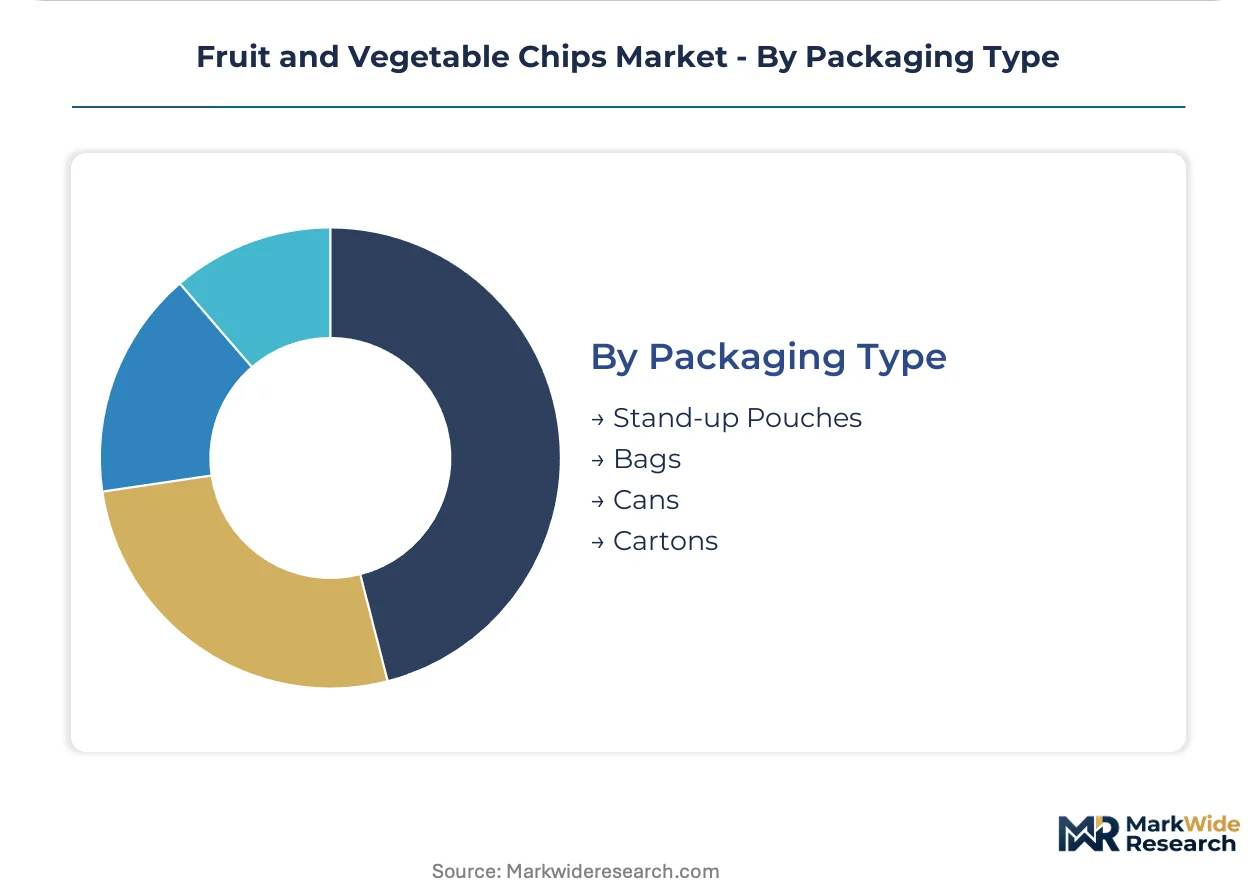
Packaging Type:
Packaging innovation focuses on convenience, shelf life, and sustainability, impacting consumer choice and brand perception.
- Bags:Flexible plastic or foil-lined bags remain the most common and cost-effective packaging solution for fruit and vegetable chips. These are widely used across all price points due to their versatility and efficient production.
- Stand-up Pouches:Offering convenience with resealable closures and improved shelf presence, these pouches are increasingly popular for premium and single-serve portions. Their design supports brand visibility and consumer portability.
- Cans:Less common, cans provide robust protection against crushing and moisture, often used for specialty or larger volume products.
- Cartons:Primarily utilized for multi-packs or specific brand aesthetics, cartons offer a more rigid structure for product protection.
Consumer preference for convenience and portability increasingly favors Stand-up Pouches, though Bags maintain a substantial market presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major international shipping ports and interconnected freight rail systems underwrite the global market's ability to move raw materials and finished fruit and vegetable chips across continents, ensuring widespread product availability and access to diverse consumer bases.
United States
Health enthusiasts drive strong demand for fruit and vegetable chips, prioritizing clean labels and superior nutritional profiles. The US FDA enforces rigorous standards for health claims and ingredient declarations on snack packaging. Food innovation centers in California lead product development for new fruit and vegetable chip varieties, often focusing on organic sourcing.
Germany
German consumers exhibit high health consciousness, creating robust demand for organic and non-GMO certified fruit and vegetable chips. EFSA regulations and Nutri-Score initiatives influence product reformulation towards healthier snack options. Bavaria's food processing sector hosts several specialty snack manufacturers.
China
A growing middle class in China seeks imported premium snacks, including fruit and vegetable chips, driven by perceived quality and health benefits. China's GB standards impose stringent quality and safety requirements on imported food products, directly impacting market access. Major distribution hubs like Shanghai facilitate the entry and spread of international snack brands across the country.
United Kingdom
UK consumers increasingly favor healthier snack alternatives, boosting demand for fruit and vegetable chips in retail channels. The Food Standards Agency oversees strict labeling requirements and health claims for food products. London serves as a key distribution and innovation hub for premium imported snack foods, reflecting evolving consumer tastes.
Fruit and Vegetable Chips Market Key Industry Players
Listed leaders compete with private specialists across distribution scale and product innovation within the fruit and vegetable chips market. The market exhibits a tiered structure, with established food conglomerates alongside agile, health-focused brands. Strategic archetypes include global snack giants leveraging extensive networks, organic and natural food specialists targeting premium segments, and vertically integrated produce processors focused on raw material control. Portfolio diversification and geographic expansion represent dominant competitive moves among these players, alongside targeted M&A for niche brands.
At the scale-driven end, PepsiCo, Inc. exemplifies global reach and mainstream market penetration, leveraging its extensive distribution infrastructure. The Hain Celestial Group, Inc. occupies a position within the organic and natural foods segment, appealing to health-conscious consumers seeking certified clean-label products. Seneca Foods Corporation represents a model focused on upstream control, demonstrating backward integration into raw vegetable supply chains. These companies collectively illustrate the diverse strategic approaches employed across the fruit and vegetable chips market, from broad consumer appeal to niche specialization and supply chain efficiency.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Calbee North America |
| General Mills, Inc. |
| Kellanova |
| Seneca Foods Corporation |
| Hain Celestial Group, Inc. |
| Luke's Organic |
| Crispy Green, Inc. |
| Rhythm Superfoods |
| Others |
Cost & Logistics Intelligence
Operational scale in vacuum frying and raw material procurement underwrites both the supply concentration among large players and the establishment of distinct price floors for certified products. This market segment exhibits a clear relationship between production volume and cost efficiency.
Pricing Analysis
Certification level (Non-GMO Project Verified, organic) creates the primary spread in fruit and vegetable chip pricing. The dominant pricing structure involves tiered premium-mid-economy differentiation, where vacuum-fried organic options command higher prices. Price differentiation stems from processing technology, clean-label certifications, and brand equity. Pricing softness affects conventional baked or dehydrated alternatives due to competition from traditional snacks. Retail Consumers exhibit higher price sensitivity compared to Health Enthusiasts.
Supply Chain Analysis
Raw material price volatility for fresh produce introduces a significant structural risk across the supply chain. Geographic supply concentrations for key ingredients include the United States for sweet potatoes and Germany for kale. The industry depends on consistent availability of fresh fruits and vegetables, and specialized packaging materials. Distribution runs through extensive retail networks for mainstream brands and direct-to-consumer channels for niche players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense against traditional, often lower-cost, potato chips that incumbents must navigate to maintain market share.
For Market Incumbents: Fortify market position by continuously investing in advanced processing technologies like vacuum frying to enhance nutritional profiles and product authenticity. Secure long-term, direct contracts with growers to mitigate raw material price volatility and ensure consistent quality. Invest in robust sustainable packaging solutions to meet evolving consumer and regulatory demands. Diversify product portfolios with novel fruit and vegetable varieties to differentiate from commodity snacks.
For New Entrants and Emerging Players: Anchor in specific, underserved niche segments, such as functional ingredients or exotic fruit varieties with perceived health benefits. Target Health Enthusiasts in developed economies like the United States and Germany, who prioritize premium, certified clean-label products. Leverage direct-to-consumer (DTC) e-commerce platforms to build brand loyalty and efficiently test new product innovations. Focus on obtaining relevant third-party certifications like Non-GMO Project Verified early to establish credibility.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated processors with strong clean-label certifications and proprietary vacuum frying capabilities. Long-term viability over the next 5-10 years centers on brands that can consistently deliver superior nutritional value and transparent sourcing. Acquisition targets should demonstrate strong brand equity within the premium segment. The adoption rate of advanced sustainable packaging materials by major players is a signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Innovation with Functional Ingredients | Developing snacks with adaptogens or high antioxidants attracts health-conscious consumers seeking additional benefits. |
| Expansion into Emerging Markets | Reaching growing middle-class populations in Southeast Asia unlocks new consumer bases for premium snacks. |
| Investment in Vacuum Frying Technology | Producing lower-fat chips with higher nutrient retention directly appeals to the health enthusiast segment. |
| Sustainable Packaging Development | Implementing recyclable or compostable materials aligns with consumer environmental values and regulatory pressures. |
| Direct-to-Consumer Channel Buildout | Establishing direct sales channels fosters customer relationships and offers greater control over brand messaging. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, procurement managers, brand managers, and retail buyers, and refined through iterative analysis. This approach combined in-depth primary interviews with rigorous secondary validation. Secondary data sources included US FDA filings, EFSA reports, industry trade association publications, and company annual reports, triangulating insights from both bottom-up and top-down perspectives.
Variance decomposition across the analysis window formed the core of the analytical framework, modeling market dynamics over the projection horizon. Segmentation dimensions modeled included product type, end-user, flavor profile, packaging type, and processing technology. Compound annual growth rates were derived from projected market shifts, incorporating consumer health consciousness trends and raw material availability as key forecast inputs.
Material uncertainties — geopolitical events, unexpected regulatory changes, and climate-related supply disruptions — sit outside the modeled envelope of this study. Forecasts reflect documented assumptions regarding market conditions and technological advancements. Practitioners should keep alternative scenarios live as global trade policies and consumer preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Organic Snacks Market
Snacks
Edible Flakes Market
Snacks
Seaweed Snacks Market
Snacks
North America Pretzel Market
Snacks
France Energy Bar Market
Snacks
North America Cereal Bar Market
Snacks
Snack Food Packaging Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Asia Pacific Snack Food Market
Snacks
Global Protein Snack Market
Snacks
Global Snack Food Market
Snacks
Cheese Snacks Market
Snacks
United Kingdom Snack Bar Market
Snacks
Germany Energy Bar Market
Snacks
Granola Market
Snacks
Middle East and Africa Snack Pellets Market