
 Middle East and North Africa Extruded Snack Food Market | 2026-2036
Middle East and North Africa Extruded Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and North Africa Extruded Snack Food Market Intelligence
Food technologist availability across the Middle East and North Africa is reorganizing how quickly manufacturers can scale clean-label extruded lines. Almarai leverages its integrated dairy and snack infrastructure to control distribution depth in Saudi Arabia. Mondelez International sustains brand recognition through flavor localization that matches regional palate preferences. Frito-Lay anchors volume throughput via manufacturing scale and route-to-market density in Egypt and the Levant.
Extruded snack foods are products formed by forcing moistened starch-based dough through a die under heat and pressure, then expanding through rapid moisture flash-off to create a porous, crunchy matrix with bulk densities typically below 150 g/L; these structures serve as delivery vehicles for seasonings, oils, and functional ingredients in commercial ready-to-eat applications. Corn snacks occupy the largest volume share due to raw material cost advantages and processing familiarity across North African milling networks. Rice snacks represent the fastest-growing product type as gluten-free positioning gains traction among health-conscious consumers in Gulf urban centers. Pouch packaging dominates margin pools through extended shelf-life barriers and premium single-serve pricing in convenience channels.
Saudi Food and Drug Authority standards, UAE Ministry of Industry and Advanced Technology technical regulations, and Egypt's Egyptian Organization for Standardization and Quality specifications collectively govern additive limits, nutritional labeling, and import certification pathways for extruded snack foods across the region. These frameworks elevate compliance costs for new entrants while creating specification advantages for established producers with in-house analytical laboratories. Stakeholders must monitor evolving Gulf Cooperation Council harmonization timelines and local-content incentives that could redraw competitive boundaries between imported and domestically manufactured snack portfolios.
Market Dynamics
Saudi Food and Drug Authority sodium labeling mandates are forcing manufacturers across the Gulf Cooperation Council corridor to accelerate clean-label reformulation timelines, compressing product development cycles and redrawing competitive boundaries between domestic and imported snack portfolios.
Growth Catalysts
- SFDA Sodium Standards:Saudi Arabia's phased sodium reduction targets for processed foods create immediate demand for reformulated extruded bases using alternative salt-delivery technologies and yeast extracts.
- Urban Convenience Channels:Dubai and Riyadh convenience store density expansion is pulling single-serve pouch formats into petrol station and metro retail footprints.
- Gluten-Free Positioning:Rice-based extrusion systems are capturing health-conscious consumers in Abu Dhabi and Doha through allergen-free claims and premium shelf placement.
Market Restraints
- Palm Oil Price Volatility:Malaysia and Indonesia export duty fluctuations transmit directly into coating and frying cost structures across Egyptian and Moroccan production facilities.
- Equipment Import Dependency:Twin-screw extruder and die-head systems concentrate sourcing from Italian and German suppliers, exposing North African processors to euro-denominated capex cycles and extended lead times.
- Fresh Snack Substitution:Levantine bakery chains and Egyptian foul sandwich vendors capture midday consumption occasions that extruded snacks cannot penetrate without hot-food service infrastructure.
Strategic Opportunities
- Algerian Distribution White Space:Underdeveloped modern trade penetration in Oran and Constantine creates first-mover potential for pouch-format extruded snacks through wholesale cash-and-carry networks.
- MOHAP Nutritional Certification:UAE Ministry of Health and Prevention's voluntary nutrient-profiling scheme offers premium positioning leverage for reformulated products meeting reduced sodium and saturated fat thresholds.
- E-Commerce Subscription Models:Direct-to-consumer snack boxes aggregating regional flavor variants are bypassing traditional distributor markups in Saudi Arabia's secondary cities.
Industry Challenges
- Food Technologist Scarcity:Extrusion process optimization and clean-label formulation expertise concentrates in Cairo and Dubai, leaving Jeddah and Riyadh facilities dependent on expatriate talent with elevated turnover.
- Dual Certification Burden:Simultaneous Gulf Cooperation Council harmonization timelines and Egypt's EOSQ import specifications force parallel testing protocols that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and North Africa Extruded Snack Food Market |
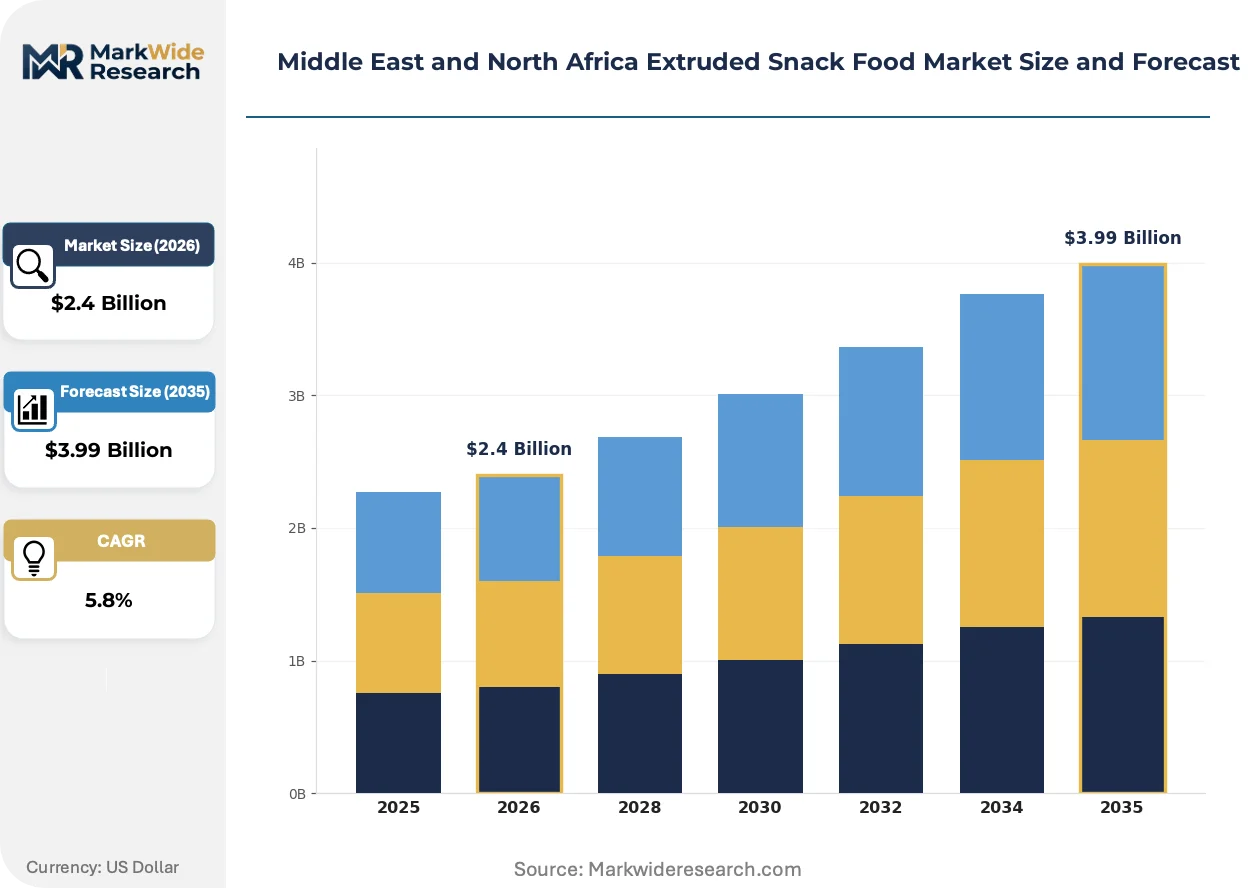
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato Snacks, Corn Snacks, Rice Snacks, Pulses Snacks Flavor Profile: Spicy, Sweet, Savory, Sour Packaging Type: Bags, Boxes, Pouches, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service |
| Companies Covered | Frito-Lay, Nadec, Almarai, Aperitivos Flaper, JFC International, Kellogg's, Mondelez International, Bag Snacks, ITC, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and North Africa Extruded Snack Food Market Strategic Shifts & Innovations
Extrusion technology advancement and regulatory tightening are converging to reshape ingredient sourcing, processing architecture, and route-to-market strategies across Middle Eastern and North African snack manufacturing.
High-pressure short-time extrusion systems operating at elevated screw speeds and reduced residence times are preserving native starch functionality while achieving expansion ratios comparable to conventional thermal processing. Saudi and UAE manufacturers are retrofitting existing lines with these systems to meet clean-label demands without full equipment replacement. This retrofit pathway is displacing greenfield investment cycles and compressing payback periods for mid-scale processors.
SFDA and MOHAP coordinated front-of-pack labeling requirements are mandating interpretive nutritional symbols that penalize high sodium and saturated fat formulations. Manufacturers are responding by reformulating base matrices with pulse flours and fiber concentrates that maintain texture while improving scoring algorithms. Egyptian and Lebanese exporters to Gulf markets face the steepest compliance ramps due to legacy recipe portfolios.
Young urban consumers in Riyadh and Dubai are rotating snack consumption toward "permissible indulgence" positioning that balances craveability with functional claims. This preference shift is elevating protein-fortified and fiber-enhanced extruded formats above traditional corn and potato bases in convenience channel planograms. Moroccan and Tunisian manufacturers are adapting by localizing flavor profiles—harissa, zaatar, and kabsa seasonings—rather than competing on health claims alone.
Middle East and North Africa Extruded Snack Food Market Segmentation
Extruded snack manufacturers in the Middle East and North Africa calibrate portfolio mix against divergent margin structures across product formats and channel economics. Segment-level profitability varies sharply between impulse-driven convenience formats and planned-purchase retail packs.
Product Type:
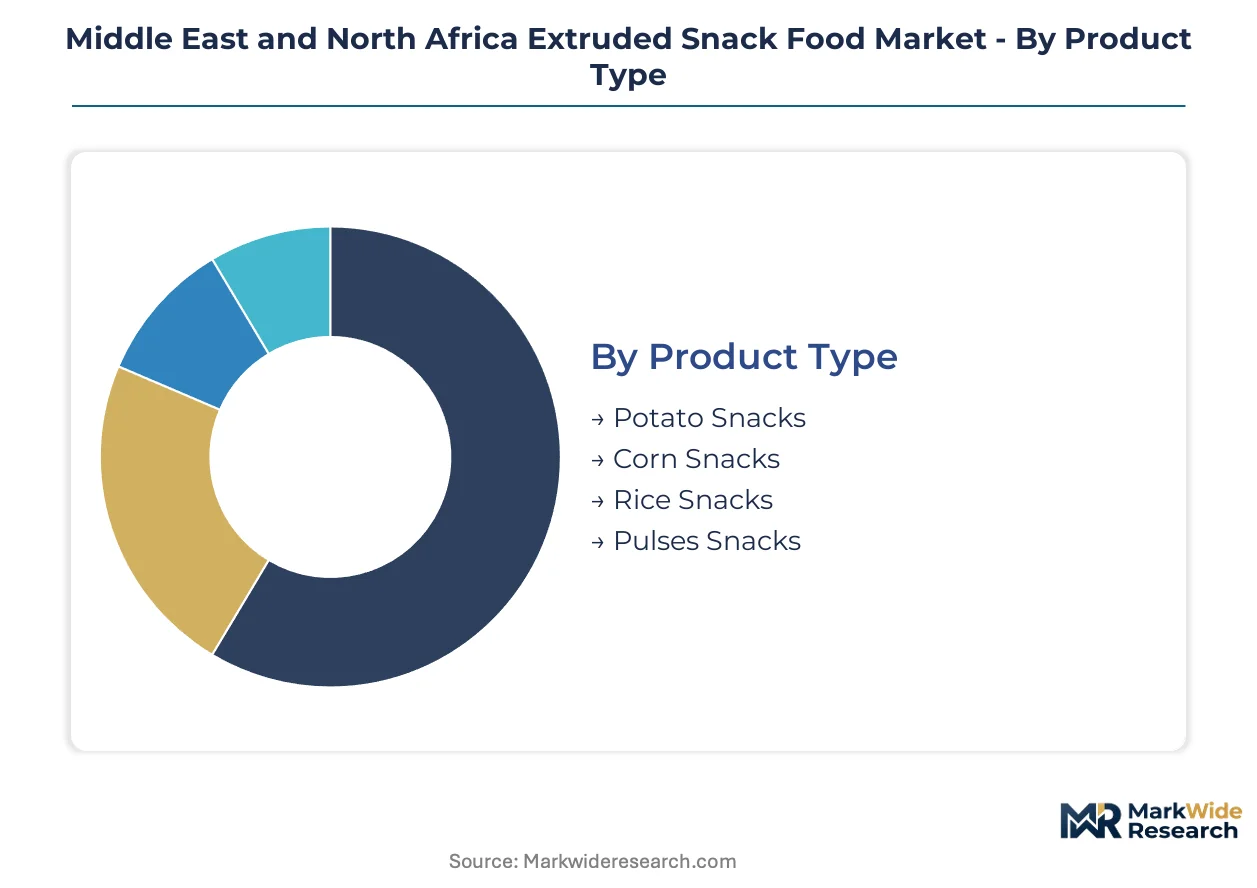
Margin pools concentrate in corn and rice extrusion lines where Gulf urban consumers pay premiums for texture consistency and clean-label positioning.
- Corn Snacks:These formulations leverage North African milling infrastructure and established extrusion parameters to deliver the lowest unit production costs across the region. Saudi Arabia and Egypt anchor volume demand through family-size pack preferences in modern trade channels, though sodium-reduction mandates are forcing base-matrix reformulation.
- Rice Snacks:Manufacturers deploy these gluten-free bases to capture health-positioning premiums in Dubai and Abu Dhabi convenience networks. The absence of wheat allergens supports shelf placement in pharmacy and wellness retail formats where unit economics exceed conventional corn lines.
- Potato Snacks:Dehydrated potato flake extrusion dominates Levantine production facilities serving Levant and Iraq distribution corridors.
- Pulses Snacks:Chickpea and lentil bases are emerging from Tunisian and Moroccan processors targeting protein-fortification claims.
The dominant share belongs to Corn Snacks, while Rice Snacks is closing the gap fastest.
Flavor Profile:
Application contexts determine flavor investment intensity, with food service and convenience channels demanding distinct seasoning architectures.
- Savory:Cheese, barbecue, and chicken variants constitute the baseline formulation investment across Riyadh and Jeddah manufacturing facilities. These profiles minimize SKU complexity while maximizing production run lengths.
- Spicy:Harissa, chili-lime, and regional pepper blends command placement premiums in Egyptian and Gulf Cooperation Council petrol station retail. Heat intensity calibration varies by sub-region, with UAE consumers tolerating milder formulations than Saudi or Egyptian markets.
- Sweet:Honey, date, and caramel coatings target Ramadan and Eid consumption occasions through gift-pack formats.
- Sour:Vinegar and tamarind profiles remain niche, concentrated in Lebanese and Syrian expatriate consumer segments.
Savory formulations retain volume leadership, though Spicy variants are expanding shelf allocation most aggressively.
Packaging Type:
Cost tier stratification separates commodity formats from barrier-film premium positioning in climate-controlled supply chains.
- Pouches:Metallized and clear-barrier flexible films dominate Dubai and Riyadh convenience channels through single-serve price points and extended shelf-life performance in high-temperature storage conditions.
- Bags:Multi-layer polyethylene structures serve family-size retail formats across Egyptian and Moroccan mass-market distribution, balancing moisture protection against per-unit material cost constraints.
- Boxes:Shelf-ready cartons concentrate in Saudi Arabian hypermarket planograms for variety packs and seasonal gift assortments.
- Cans:Composite and tinplate containers remain marginal, limited to tourist-oriented souvenir formats and air travel retail.
Pouch formats command the steepest margin premiums, while Bag formats maintain volume dominance through modern trade penetration.
Distribution Channel:
Customer type fragmentation between planned and impulse purchase occasions shapes route-to-market investment priorities.
- Convenience Stores:Petrol station and metro-adjacent formats in Dubai, Riyadh, and Jeddah pull single-serve pouch SKUs with rapid inventory turns and limited shelf-space competition from fresh alternatives.
- Supermarkets:Hypermarket and supermarket chains across Saudi Arabia and Egypt anchor planned-purchase volume through multi-pack promotions and private-label placement.
- Online Retail:Direct-to-consumer and aggregator platforms are expanding fastest in Saudi secondary cities, bypassing traditional distributor markups through subscription box models.
- Food Service:Hotel, airline, and catering channels demand bulk formats with customized seasoning for institutional procurement contracts.
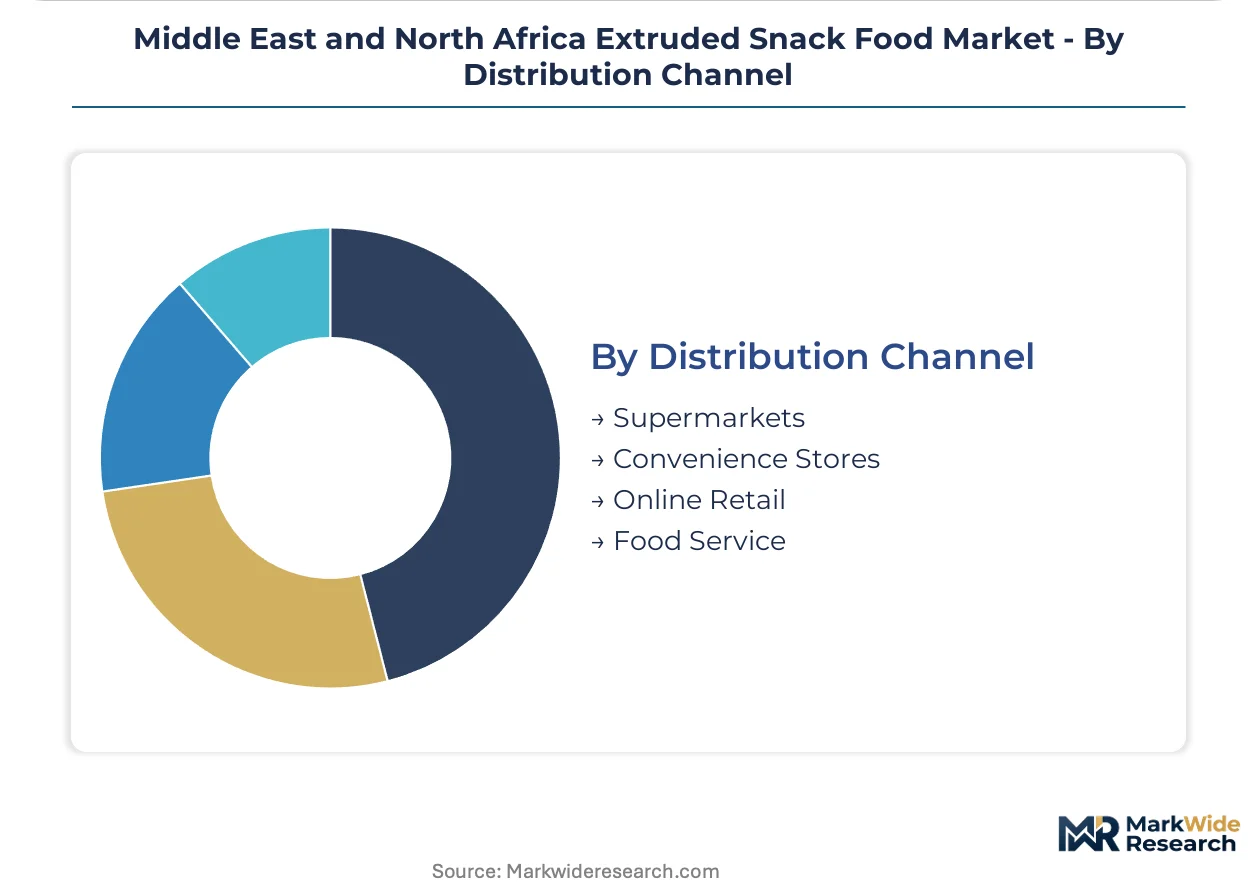
Supermarkets retain the largest revenue base, though Online Retail is accelerating most quickly as logistics infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE consumers pay 40-60% premiums for clean-label extruded snacks versus Egyptian mass-market equivalents, creating a bifurcated margin architecture across the Gulf Cooperation Council corridor and North Africa.
Saudi Arabia
Riyadh and Jeddah convenience networks pull single-serve pouch formats through petrol station retail density expansion. SFDA sodium reduction mandates force reformulation of legacy corn-based recipes using yeast extract and potassium chloride alternatives. The Eastern Province manufacturing cluster near Dammam concentrates extrusion capacity serving domestic and Bahrain export markets.
UAE
Dubai and Abu Dhabi health-positioning premiums support rice-based gluten-free lines in pharmacy and wellness retail channels. MOHAP voluntary nutrient-profiling certification creates tiered shelf placement advantages for compliant manufacturers. Jebel Ali free zone logistics infrastructure enables re-export distribution into Oman and Qatar with reduced customs friction.
Egypt
Cairo and Alexandria mass-market volumes anchor regional corn snack production through established milling networks and route-to-market density. EOSQ import specifications and labeling requirements govern additive limits for domestic consumption and Libyan export corridors. The 10th of Ramadan industrial city concentrates mid-scale extrusion facilities serving Levantine distribution.
Morocco
Casablanca and Rabat modern trade expansion pulls pouch-format premium positioning into hypermarket planograms. Local-content incentives and import tariff structures favor domestic manufacturing over European snack imports. Tangier Med port logistics enable Spanish and Portuguese market access for harissa-flavored specialty lines.
Algeria
Oran and Constantine wholesale cash-and-carry networks represent underdeveloped modern trade white space for first-mover pouch-format entrants. Central Bank foreign exchange constraints complicate equipment import financing for extrusion line upgrades. Domestic wheat and barley availability supports emerging pulse-flour extrusion trials in Constantine processing facilities.
Middle East and North Africa Extruded Snack Food Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Middle East and North Africa extruded snack food market. Multinational packaged food conglomerates with Gulf distribution infrastructure occupy premium positioning tiers, while regional dairy and beverage integrators leverage backward supply chain control for mid-market penetration. Three archetypes dominate: global snack specialists with flavor localization capabilities, vertically integrated regional food conglomerates with captive dairy and milling assets, and North African family-owned processors serving price-sensitive mass channels. Competitive dynamics center on route-to-market density expansion and sodium-compliant reformulation speed rather than manufacturing scale alone.
Among Gulf-based integrated food conglomerates, Almarai and Nadex exemplify archetypes combining dairy distribution depth with snack portfolio extension. Mondelez International and Frito-Lay anchor multinational positioning through brand recognition and manufacturing scale across Egyptian and Levantine production facilities. These named entities represent competitive concentration points without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Frito-Lay |
| Nadec |
| Almarai |
| Aperitivos Flaper |
| JFC International |
| Kellogg's |
| Mondelez International |
| Bag Snacks |
| ITC |
| Others |
Cost & Logistics Intelligence
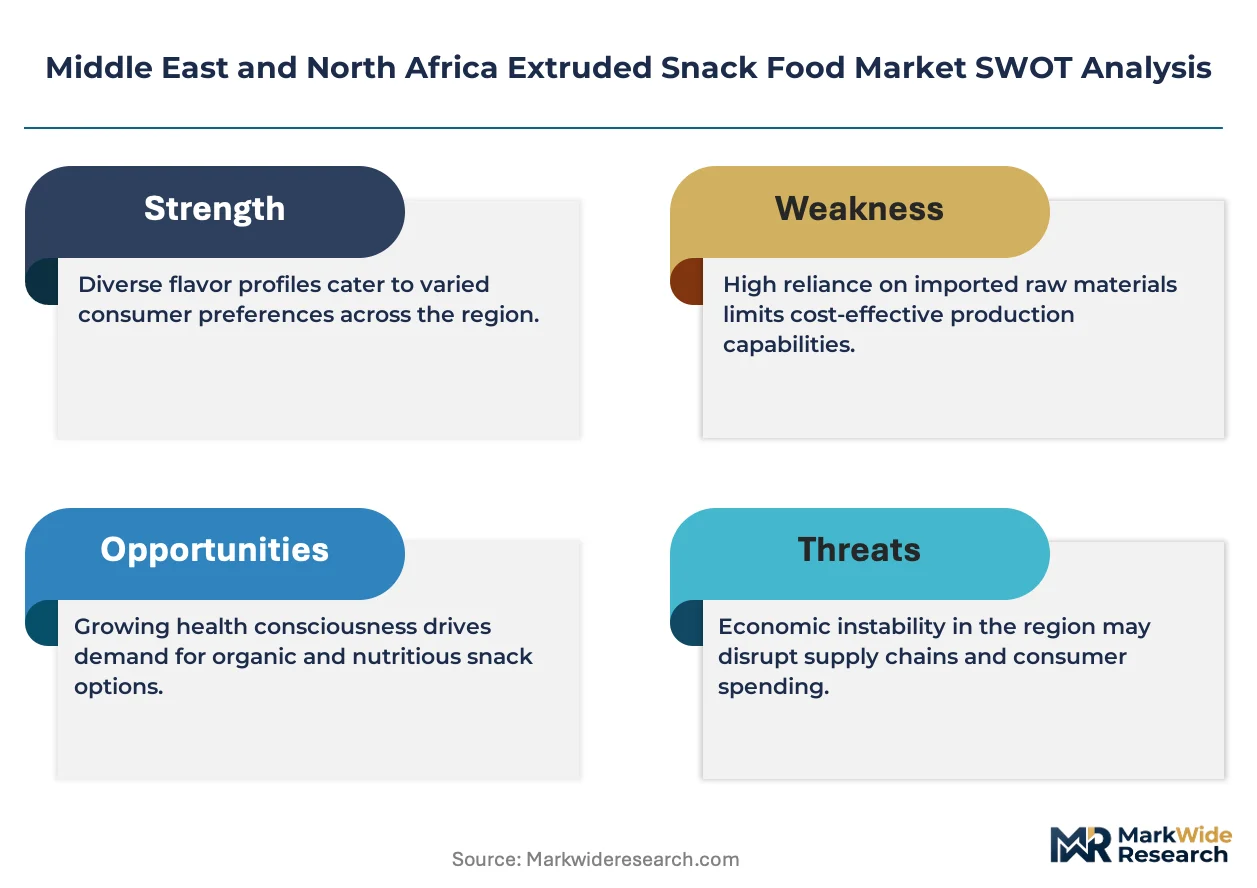
Capacity utilization at Egyptian corn milling networks and Saudi extrusion facilities anchors regional price floors, concentrating supply-side leverage among integrated processors while compressing margins for import-dependent entrants lacking backward control over raw material flows.
Pricing Analysis
Customization-premium spreads separate standard corn-based formulations from sodium-compliant reformulated lines carrying MOHAP certification marks. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label positioning, Gulf urban delivery premiums, and volume scale discounts for hypermarket private-label contracts. Pricing pressure stems from palm oil coating cost volatility transmitted through Malaysian export duty fluctuations. Mass-market Egyptian consumers exhibit highest price sensitivity, while UAE pharmacy-channel buyers tolerate substantial premiums for gluten-free rice bases.
Supply Chain Analysis
Egypt and Saudi Arabia anchor regional extrusion capacity through integrated corn milling and dairy-snack distribution infrastructure. Raw material flows draw from North African grain networks, Southeast Asian palm oil estates, and European equipment suppliers for twin-screw extruder systems. Single-source vulnerability concentrates in Italian and German die-head manufacturers, exposing processors to euro-denominated capex cycles and extended lead times. Distribution runs through Jebel Ali free zone logistics corridors serving re-export into Oman and Qatar, alongside Cairo-based wholesale networks penetrating Levantine and Libyan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extrusion process optimization expertise concentrates in Cairo and Dubai, leaving Riyadh and Jeddah facilities dependent on expatriate talent with elevated turnover—this capability gap defines competitive mobility barriers across the forecast horizon.
For Market Incumbents: Shield margin pools by accelerating in-house analytical laboratory investment ahead of Gulf Cooperation Council harmonization timelines, and secure captive supply of pulse flour inputs through backward integration into Tunisian and Moroccan agricultural processing. Sodium-compliant reformulation speed serves as the priority defensive lever against Egyptian exporters facing steep compliance ramps. For New Entrants and Emerging Players: MOHAP nutritional certification fast-tracks unlock premium shelf placement in Dubai pharmacy and wellness retail formats where unit economics exceed conventional channels. Algerian wholesale cash-and-carry networks in Oran and Constantine represent the most penetrable white space, accessible through pouch-format SKUs bypassing underdeveloped modern trade infrastructure. Direct-to-consumer subscription models aggregating regional flavor variants offer go-to-market traction in Saudi secondary cities. For Investors and Strategic Acquirers: Mid-scale North African family-owned processors with established route-to-market density and reformulation-ready extrusion lines represent the most attractive acquisition target archetype. Long-term viability hinges on regulatory compliance agility rather than manufacturing scale alone across the projection horizon. The signal to watch is Gulf Cooperation Council sodium harmonization timeline acceleration, which would redraw competitive boundaries between imported and domestically manufactured portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | SFDA sodium mandates compress product development cycles for compliant manufacturers. |
| Backward Integration into Pulse Flour Supply | Tunisian and Moroccan agricultural processing secures protein-fortification input chains. |
| MOHAP Certification Investment | UAE Ministry of Health and Prevention tiered placement unlocks pharmacy channel premiums. |
| Algerian Distribution Network Expansion | Oran and Constantine wholesale cash-and-carry penetration captures first-mover positioning. |
| E-Commerce Subscription Model Launch | Direct-to-consumer boxes bypass traditional distributor markups in Saudi secondary cities. |
Research Approach
A standing panel of extrusion process engineers, Saudi Food and Drug Authority compliance officers, Dubai hypermarket category buyers, and Cairo-based food technologists provided ongoing calibration against secondary validation through customs records, Nielsen retail audit data, Gulf Cooperation Council technical regulation filings, and Egyptian Organization for Standardization and Quality specifications. Bottom-up facility capacity assessments and top-down consumption demand modeling were triangulated to anchor volume and value estimates.
Consistency checks validated outputs against external benchmarks including regional grain production statistics and palm oil import trajectories. The analytical framework segmented across product type, flavor profile, packaging format, and distribution channel throughout the forecast period, with CAGRs derived from elasticity-adjusted demand curves and regulatory compliance cost trajectories. Industry-specific inputs incorporated sodium reduction mandate phase-in schedules and convenience store density expansion timelines.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf urbanization and stable grain import policies; material deviation in palm oil tariff structures or extrusion equipment lead times would warrant model refresh. Recalibration cycles align with material shifts in SFDA regulatory timelines and Gulf Cooperation Council harmonization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Kale Chips Market
Snacks
North America Energy Bar Market
Snacks
Nachos Market
Snacks
High Carb Low Fat Snack Market
Snacks
Global Fruit Snacks Market
Snacks
Italy Snack Bar Market
Snacks
North America Pretzel Market
Snacks
Energy Bar Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Protein Crisps Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Grass-Fed Jerkies Market
Snacks
Thailand Snack Bar Market
Snacks
Europe Energy Bar Market
Snacks
South America Snack Bar Market
Snacks
Europe Cereal Bar Market