
 Europe Popcorn Market | 2026-2036
Europe Popcorn Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Popcorn Market Insights
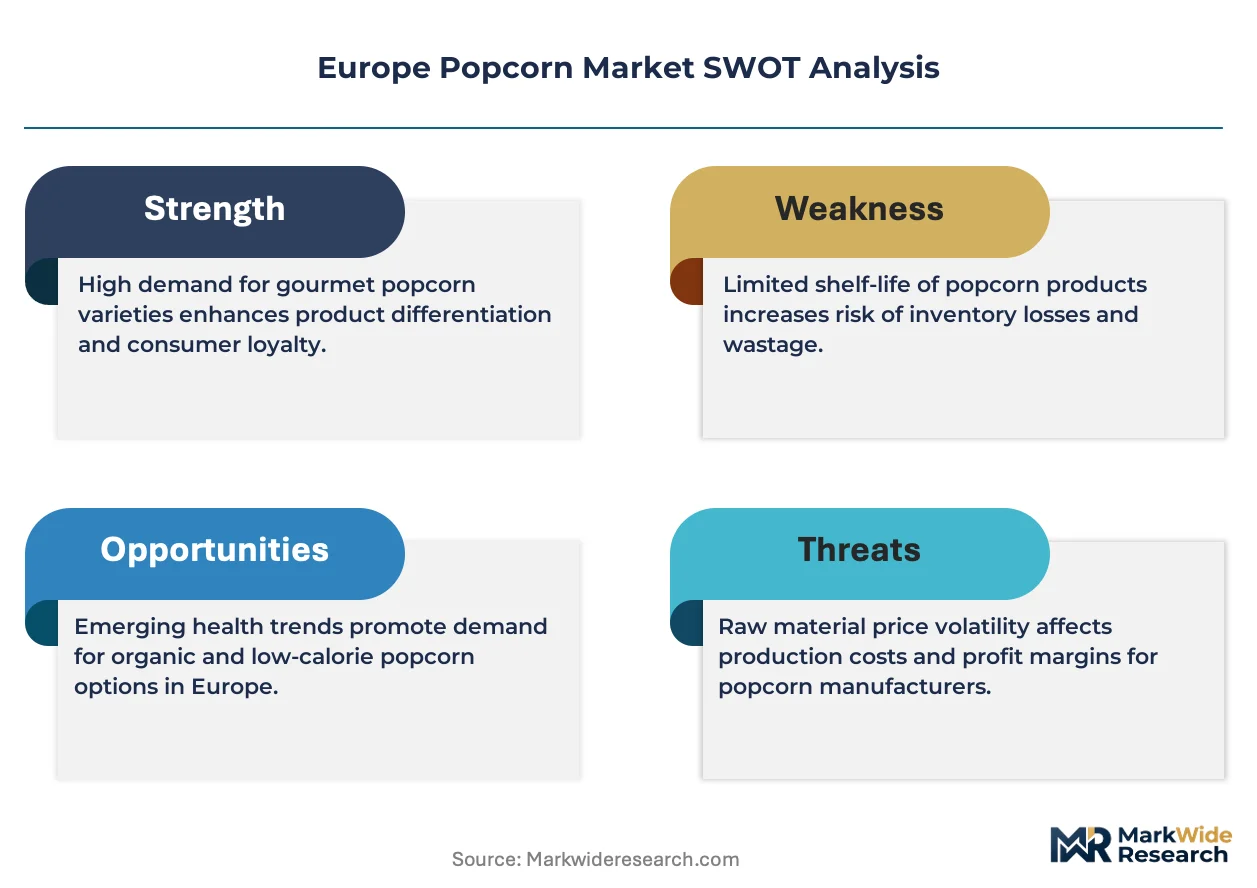
Cinema operators are unwinding their reliance on traditional concession mixes as at-home streaming households expand their snack repertoire. Intersnack Group leverages its pan-European distribution network to dominate private-label supply across German retail channels. Propercorn differentiates through clean-label positioning and flavor innovation that commands shelf space in British premium grocers. Quinn Foods anchors its growth on organic grain sourcing and transparent supply chain storytelling that resonates with French ethical consumers.
Popcorn comprises dried maize kernels that expand and puff when exposed to concentrated heat, typically via hot-air or oil-popped methods, yielding a light, brittle snack with moisture content below five percent and bulk density ranging from thirty to fifty grams per liter. Its primary commercial purpose spans ready-to-eat retail packs, food-service bulk portions, and ingredient applications in confectionery and trail mixes. Caramel and gourmet flavor profiles capture expanding margin pools as consumers trade up from basic butter formulations, while online retail channels outpace supermarkets in growth velocity due to subscription-box models and direct-to-consumer trial packs. Savory variants maintain volume leadership across Southern European markets where salt-forward snacking traditions persist.
EFSA sodium-reduction targets and the EU Packaging and Packaging Waste Regulation reshape product formulation and material specifications, compelling manufacturers to reformulate recipes and adopt recyclable or compostable film structures. ECHA REACH compliance governs flavoring substance approvals, creating a barrier for novel ingredient introductions that delays regional launches. France's DGCCRF enforces strict labeling on origin claims and nutritional declarations, tightening market access for non-compliant imports. Stakeholders must monitor evolving Extended Producer Responsibility schemes and decide whether to absorb compliance costs or accelerate price repositioning ahead of regulatory deadlines.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing accelerated reformulation of film structures and sodium-reduction targets across ready-to-eat popcorn portfolios, compressing margin structures while opening premium positioning for compliant producers.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclable and compostable film requirements are pulling investment into bio-based barrier technologies, creating first-mover advantages for manufacturers with certified material pipelines.
- Cinema concession diversification:Multiplex operators are expanding gourmet flavor portfolios to offset declining ticket volumes, generating bulk demand for artisanal and ethnic varietals.
- Hot-air popping equipment:Oil-free production methods are gaining traction in German and French contract manufacturing, enabling clean-label claims that command retail shelf-space premiums.
Market Restraints
- Maize price volatility:Ukrainian grain supply disruptions and drought cycles in Romanian growing regions are transmitting cost spikes through ingredient procurement contracts.
- ECHA REACH flavoring approvals:Novel seasoning substances face eighteen-to-thirty-six month safety assessment timelines, delaying regional launches for innovative taste profiles.
- Savory snack substitution:Salt-forward nuts and roasted legumes are capturing occasion share in Spanish and Italian convenience channels where popcorn penetration remains shallow.
Strategic Opportunities
- Polish and Romanian retail modernization:Discounter format expansion in Warsaw and Bucharest creates distribution whitespace for private-label and branded ready-to-eat entrants.
- Extended Producer Responsibility schemes:Early compliance with deposit-return frameworks in Germany and the Netherlands positions suppliers for preferred vendor status with sustainability-scoring retailers.
- Confectionery ingredient applications:Puffed maize integration into chocolate clusters and trail mixes opens industrial volume channels beyond direct consumption.
Industry Challenges
- Food technologist scarcity:Formulation expertise in low-sodium taste engineering and clean-label shelf-life extension is concentrating in Benelux and Nordic research clusters, creating recruitment bottlenecks.
- Packaging line reconfiguration:Transitioning from multilayer laminates to mono-material or paper-based structures requires seven-figure capital commitments with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Popcorn Market |
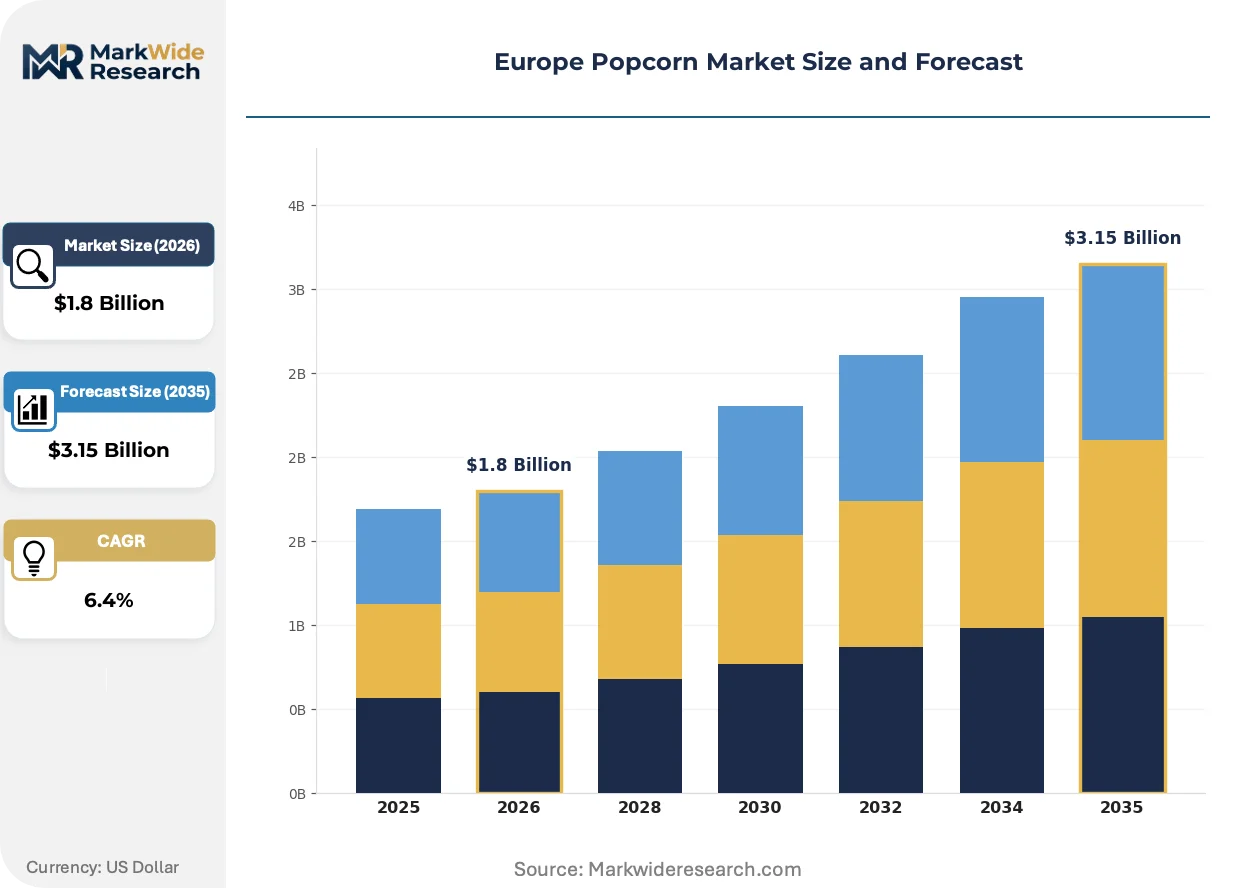
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Cheese, Caramel, Kettle Corn Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End User: Households, Cinemas, Restaurants, Events Flavor Profile: Savory, Sweet, Spicy, Gourmet |
| Companies Covered | Weaver Popcorn Company, Intersnack Group, ConAgra Brands, Tyrrells, Propercorn, PepsiCo, Quinn Foods, Metcalfe's, Hershey Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Popcorn Market Trends and Innovations
Reformulation pressures and channel fragmentation are reshaping competitive positioning across European popcorn manufacturing, with sustainability credentials and direct-to-consumer access emerging as primary differentiation vectors.
Water-based barrier coatings are supplanting conventional polyethylene laminates in microwave bag construction. British and Scandinavian retailers are accelerating adoption timelines, demanding full portfolio transitions by 2027. This shift is compressing legacy converter margins while enabling premium pricing for certified compostable alternatives.
EFSA sodium-reduction targets are tightening maximum thresholds for savory snack categories. Manufacturers are deploying potassium chloride blends and umami-enhancing yeast extracts to maintain taste intensity. French DGCCRF enforcement actions on misleading nutritional claims have made compliance documentation the decisive factor in retail listing decisions.
Subscription-box curation is displacing impulse supermarket purchases among urban millennial households. Direct-to-consumer trial packs and flavor discovery kits are capturing trial budgets previously allocated to conventional retail. This pattern concentrates in London, Paris, and Berlin metropolitan zones where delivery infrastructure and premium positioning align.
Europe Popcorn Market Segmentation
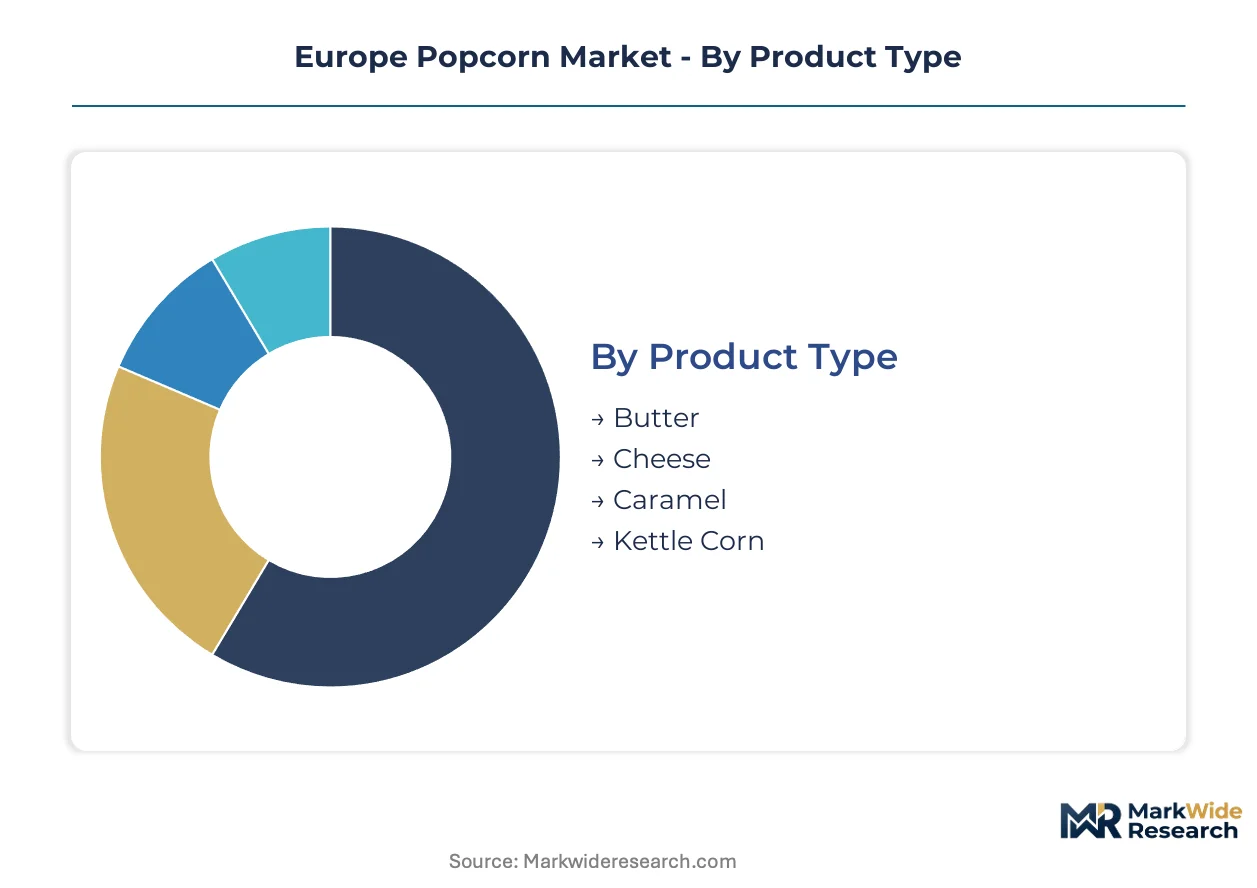
Popcorn manufacturers must navigate distinct margin structures across flavor formulations and channel economics. Product type and distribution channel segmentation reveals where premium pricing commands shelf space versus where volume throughput drives profitability.
Product Type:
Premium flavor formulations capture expanding margin pools as consumers trade up from basic commodity offerings.
- Caramel:Sugar-based coating creates a brittle, glossy shell with moisture content below three percent. German and French retail channels concentrate demand for artisanal small-batch variants that command price premiums over mass-market butter lines.
- Cheese:Powdered cheese seasoning adheres to oil-popped kernels through tumbler coating, delivering intense umami profiles. British multiplex operators generate bulk procurement volumes for nacho-cheese formulations that offset declining ticket revenues.
- Butter:Standard oil-popped base with butter-flavored topping dominates private-label portfolios across Polish and Romanian discount channels.
- Kettle Corn:Batch-cooked in sugar-salt oil blends, this hybrid sweet-savory profile maintains niche positioning in Scandinavian outdoor event channels.
The dominant share belongs to Butter, while Caramel is closing the gap fastest.
Distribution Channel:
Channel selection determines packaging format requirements and working capital intensity.
- Online Retail:Direct-to-consumer subscription models and trial-size discovery kits bypass traditional retail slotting fees. British and German urban households drive velocity through recurring delivery schedules that lock in brand loyalty.
- Supermarkets:Aisle-end displays and seasonal promotional cycles generate impulse purchase volume across French and Italian hypermarket chains.
- Food Service:Bulk bag-in-box formats supply cinema concession stands and stadium vendors with portion-controlled dispensing systems.
- Convenience Stores:Single-serve grab-and-go packs target Spanish and Portuguese fuel-station channels with limited shelf space.
Supermarkets retain volume leadership, though Online Retail is expanding most quickly.
End User:
Occasion-based consumption patterns split procurement between at-home pantry stocking and out-of-home experiential snacking.
- Households:Multi-pack grocery purchases for streaming entertainment occasions concentrate in British and German suburban markets where microwave and ready-to-eat formats compete for pantry space.
- Cinemas:Multiplex concession diversification into gourmet flavor portfolios generates contract manufacturing demand for portion-controlled bulk supply.
- Restaurants:Bar and casual dining establishments deploy popcorn as low-cost appetizer alternatives in French and Belgian urban locations.
- Events:Festival and sporting venue catering requires mobile popping equipment and on-site preparation capabilities across Eastern European summer markets.
Households anchor procurement volumes, while Cinemas are gaining share fastest through concession innovation.
Flavor Profile:
Consumer palate evolution and regulatory sodium constraints reshape formulation priorities across savory and sweet lines.
- Savory:Salt-forward profiles with umami enhancement dominate Southern European snacking traditions, though EFSA reduction targets compel potassium chloride substitution in reformulated recipes.
- Gourmet:Ethnic and fusion flavor combinations—truffle, sriracha, wasabi—command premium positioning in British and Scandinavian specialty retail channels.
- Sweet:Chocolate-drizzled and fruit-glazed variants target younger demographics through impulse-oriented packaging formats.
- Spicy:Chili and pepper-based heat profiles maintain regional strength in Spanish and Portuguese markets with established tolerance for capsaicin intensity.
Savory holds the dominant position, though Gourmet is climbing the fastest as consumers trade up from basic formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight network underwrites continental distribution efficiency, positioning Central European manufacturing clusters as the logistical backbone for snack supply across the region.
Germany
Discounter format expansion and private-label concentration drive volume demand through Rewe and Aldi Süd channels. EFSA sodium-reduction targets compel reformulation of savory portfolios before 2026 deadlines. The Rhine-Main industrial zone hosts contract manufacturers deploying hot-air popping equipment for clean-label production.
United Kingdom
Streaming entertainment households and subscription-box curation accelerate at-home consumption velocity. DGCCRF-equivalent FSA enforcement on nutritional claims tightens compliance documentation for import listings. London metropolitan logistics clusters concentrate direct-to-consumer fulfillment infrastructure for premium brands.
France
Ethical consumer segments prioritize organic grain sourcing and transparent supply chain narratives. DGCCRF labeling enforcement on origin claims creates non-tariff barriers for non-compliant suppliers. The Île-de-France region anchors gourmet flavor innovation through proximity to food-tech research institutes.
Poland
Retail modernization in Warsaw and Kraków creates distribution whitespace for branded and private-label entrants. EU Packaging and Packaging Waste Regulation timelines accelerate local converter investment in mono-material films. The Silesian industrial basin concentrates secondary packaging suppliers serving Central European markets.
Netherlands
Extended Producer Responsibility schemes and deposit-return frameworks reward early compliance with preferred vendor status. Rotterdam port infrastructure enables efficient maize import from Black Sea origins despite Ukrainian supply disruptions. The Randstad logistics cluster supports pan-European distribution hub operations for multinational snack portfolios.
Europe Popcorn Market Competitive Landscape
Concentration sits with diversified snack conglomerates and specialized premium insurgents rather than pure-play popcorn specialists. The vendor base splits between pan-European distribution networks capturing private-label volume and clean-label innovators commanding shelf-space premiums. Three archetypes dominate: multinational snack conglomerates with captive supply chains, regional private-label suppliers leveraging scale economics, and premium insurgents differentiating through flavor innovation and sustainability credentials. Competitive moves center on packaging line reconfiguration for regulatory compliance and portfolio diversification into gourmet flavor profiles.
Among diversified snack conglomerates, PepsiCo and ConAgra Brands occupy positions defined by scale advantages and cross-category leverage. Within the premium insurgent tier, Propercorn and Quinn Foods exemplify clean-label positioning strategies that resonate with ethical consumer segments in British and French metropolitan markets. The Hershey Company represents confectionery-sector diversification into adjacent snacking categories through ingredient-format applications.
| Leading Market Players |
|---|
| Weaver Popcorn Company |
| Intersnack Group |
| ConAgra Brands |
| Tyrrells |
| Propercorn |
| PepsiCo |
| Quinn Foods |
| Metcalfe's |
| Hershey Company |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal packaging mandates gate both supplier qualification and price differentiation simultaneously, compelling manufacturers to absorb seven-figure capital commitments for mono-material line reconfiguration while enabling certified compostable variants to command shelf-space premiums over legacy laminates. Cinema concession diversification and subscription-box curation split buyer archetypes between bulk contract negotiators and direct-to-consumer subscribers, fragmenting pricing power across channel tiers.
Pricing Analysis
Volume-discount tiering structures stratify across premium artisanal, standard retail, and economy private-label levels. Three-tier pricing separates certified organic small-batch formulations from mass-market butter lines and discount channel commodity packs. Price differentiation hinges on clean-label certification status and flavor complexity. Margins are tightening due to maize price volatility transmitted through Ukrainian supply disruptions. Polish and Romanian discount channels exhibit highest price sensitivity, while British premium grocers demonstrate lowest elasticity for gourmet varietals.
Supply Chain Analysis
Romania and Ukraine anchor continental maize supply for European popcorn manufacturing, with Rhine-Main and Silesian industrial zones concentrating secondary processing and packaging converter capacity. Raw material procurement draws from Black Sea grain origins, bio-based barrier film technologies, and potassium chloride substitution inputs for sodium-reduction compliance. Single-source vulnerability concentrates in Ukrainian grain corridors subject to geopolitical disruption. Distribution runs through Rhine-Alpine freight networks serving pan-European retail and food-service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward sustainability-scoring retailers and cinema consolidation chains, as multiplex operators and Aldi Süd-Rewe procurement alliances concentrate volume leverage against fragmented supplier bases.
For Market Incumbents: Compound defensive positioning through backward integration into organic grain sourcing and captive hot-air popping equipment deployment across Rhine-Main contract manufacturing clusters. Accelerate EFSA-compliant sodium-reduction formulation pipelines ahead of regulatory deadlines. Channel control through exclusive cinema concession partnerships represents the critical lever against private-label substitution threats. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation fast-track certification enables white-space entry into British and Scandinavian retail channels demanding 2027-ready compostable portfolios. Polish and Romanian discounter format expansion offers the most penetrable geography for private-label supply contracts. Direct-to-consumer trial-pack subscription models provide the decisive go-to-market angle for flavor discovery kits targeting Berlin and London metropolitan zones. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across packaging line reconfiguration and bio-based barrier R&D. Five-to-ten year viability favors acquisition targets with certified material pipelines and established cinema concession relationships. The signal to watch is EFSA sodium-reduction enforcement timing, which will determine reformulation cost burdens and compliance-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Packaging Line Reconfiguration | Mono-material film transitions unlock preferred vendor status with sustainability-scoring British and Dutch retailers. |
| Clean-Label Certification Investment | Organic grain sourcing and transparent supply chain narratives resonate with French ethical consumer segments. |
| Cinema Concession Partnership Expansion | Gourmet flavor portfolio diversification offsets declining ticket volumes for multiplex operators. |
| Direct-to-Consumer Channel Launch | Subscription-box curation captures trial budgets from urban millennial households in London and Berlin. |
| Regional Manufacturing Footprint Addition | Polish and Romanian production capacity reduces logistics costs for Eastern European retail modernization. |
Research Methodology
A spread of perspectives from brand managers, category buyers at Rewe and Aldi Süd, supply planners, and channel sales heads converged on the working assumptions. Primary interviews with cinema concession procurement officers and clean-label R&D directors combined with secondary validation from Nielsen retail audit data, EFSA regulatory filings, EU Packaging and Packaging Waste Regulation documentation, and customs trade records. Bottom-up channel volume estimates and top-down macroeconomic triangulation anchored the analytical framework.
Segmentation dimensions modeled span flavor profile, distribution channel, and end-use occasion across the projection horizon. Product-type splits between caramel, cheese, butter, and kettle corn formulations intersected with channel economics for supermarkets, online retail, food service, and convenience stores. CAGRs derived from trend extrapolation of streaming entertainment snacking velocity and regulatory compliance cost absorption. Industry-specific forecast inputs incorporated EFSA sodium-reduction timeline enforcement and EU Green Deal packaging transition deadlines.
Decision-makers should treat outputs as directional under assumptions of sustained maize supply disruption and cinema concession diversification; material deviation in Ukrainian grain corridor stability or EFSA enforcement timing would warrant model refresh. Recalibration cycles align with material shifts in regulatory compliance deadlines and Black Sea logistics conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South America Cereal Bar Market
Snacks
Energy Balls Market
Snacks
Energy Bar Market
Snacks
Meat Snacks Market
Snacks
High Fiber Snack Foods Market
Snacks
United States Popcorn Market
Snacks
United States Snack Bar Market
Snacks
Austria Snack Bar Market
Snacks
Trail Mix Market
Snacks
Vegan Snacks Market
Snacks
North America Energy Bar Market
Snacks
India Snack Bar Market
Snacks
United Kingdom Energy Bar Market
Snacks
Healthy Snacks Market
Snacks
South Africa Snack Bar Market
Snacks
Low Calorie Cookies Market