
 Low Fat Sweet Snacks Market | 2026-2036
Low Fat Sweet Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Sweet Snacks Market Analytics
The EU Green Deal's nutritional profiling criteria is pivoting European retail buyers toward reformulated sweet snack portfolios. General Mills leverages its North American manufacturing scale to sustain distribution dominance in reduced-fat cookie lines. Mondelz International anchors its competitive stance through specialized chocolate formulations that meet dual-market fat reduction targets.
Low fat sweet snacks are confectionery and bakery products engineered to contain substantially reduced lipid content, typically achieved through fat replacer technologies such as maltodextrin-based systems or oleogel structuring, while maintaining sensory parameters acceptable to mainstream consumers. Their primary commercial purpose centers on satisfying indulgence-oriented purchase occasions within dietary constraint frameworks. The cookies segment occupies mature volume leadership yet faces margin compression from commodity ingredient volatility, while bars leads growth velocity among fitness-oriented end users seeking portable macronutrient balance. Single-serve packaging controls the highest margin pool through convenience premiums and portion-control positioning that aligns with health-conscious consumer behavioral patterns.
FDA nutritional labeling mandates and EU health claims regulations shape permissible front-of-pack communication, directly determining which reformulation investments achieve retail listing access. The Hain Celestial Group navigates these compliance layers through organic certification stacking that extends beyond baseline fat reduction into clean-label territory. Stakeholders must monitor evolving WHO nutrient profiling standards and their anticipated adoption trajectories across national health ministries to anticipate next-wave reformulation requirements.
Market Dynamics
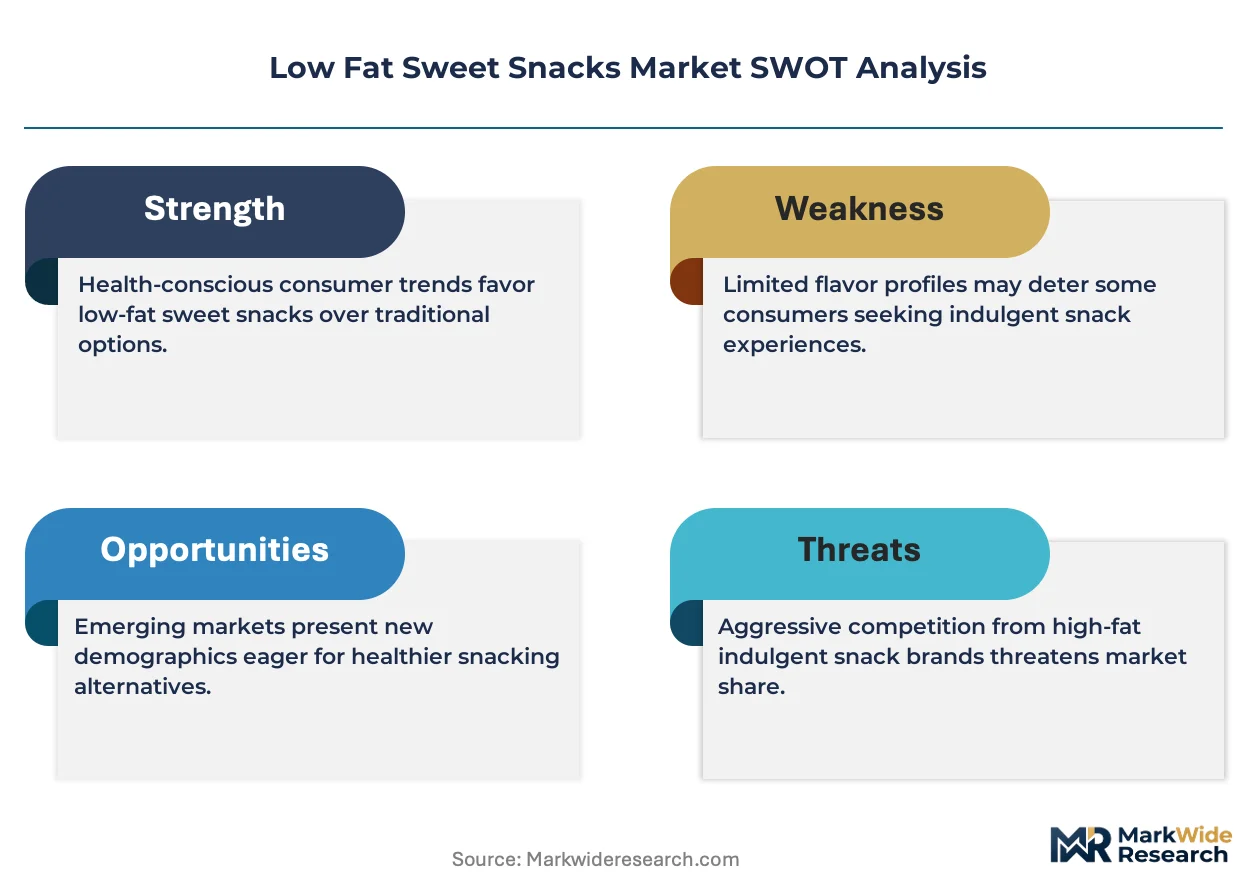
Fat replacer technologies—specifically oleogel structuring and maltodextrin-based systems—are compressing the sensory-performance gap that previously constrained reformulation depth, allowing manufacturers to meet FDA nutritional labeling thresholds without sacrificing mouthfeel.
Growth Catalysts
- EU Green Deal nutritional profiling:European retail buyers now prioritize reformulated sweet snack portfolios, creating procurement pull-through for compliant manufacturers.
- Urban wellness corridors:Health-conscious consumers in dense metropolitan clusters concentrate demand for portion-controlled single-serve formats.
- Clean-label certification stacking:Organic and non-GMO credentials layered atop fat reduction command shelf-space premiums in premium retail channels.
Market Restraints
- Commodity ingredient volatility:Cocoa butter and alternative lipid feedstocks face price swings that compress margins on reformulated chocolate lines.
- Technical mouthfeel ceiling:Current fat replacers hit sensory limits above 50% lipid reduction, constraining formulation ambition.
- WHO nutrient profiling adoption:Anticipated national health ministry implementations create compliance uncertainty ahead of finalized standards.
Strategic Opportunities
- Japanese functional foods corridor:FOSHU-approved positioning for low-fat sweet snacks remains underdeveloped relative to Western markets.
- Direct-to-subscription channels:Personalized nutrition platforms bypass traditional retail gatekeepers for niche reformulation variants.
- Dual carbon goal alignment:China's MIIT sustainability frameworks incentivize low-fat processing as energy-intensive fat extraction declines.
Industry Challenges
- Reformulation talent scarcity:Food scientists with cross-functional expertise in sensory science and regulatory navigation command premium compensation.
- Legacy equipment retrofit costs:Existing extrusion and enrobing lines require capital-intensive modification for reduced-viscosity fat replacer handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Sweet Snacks Market |
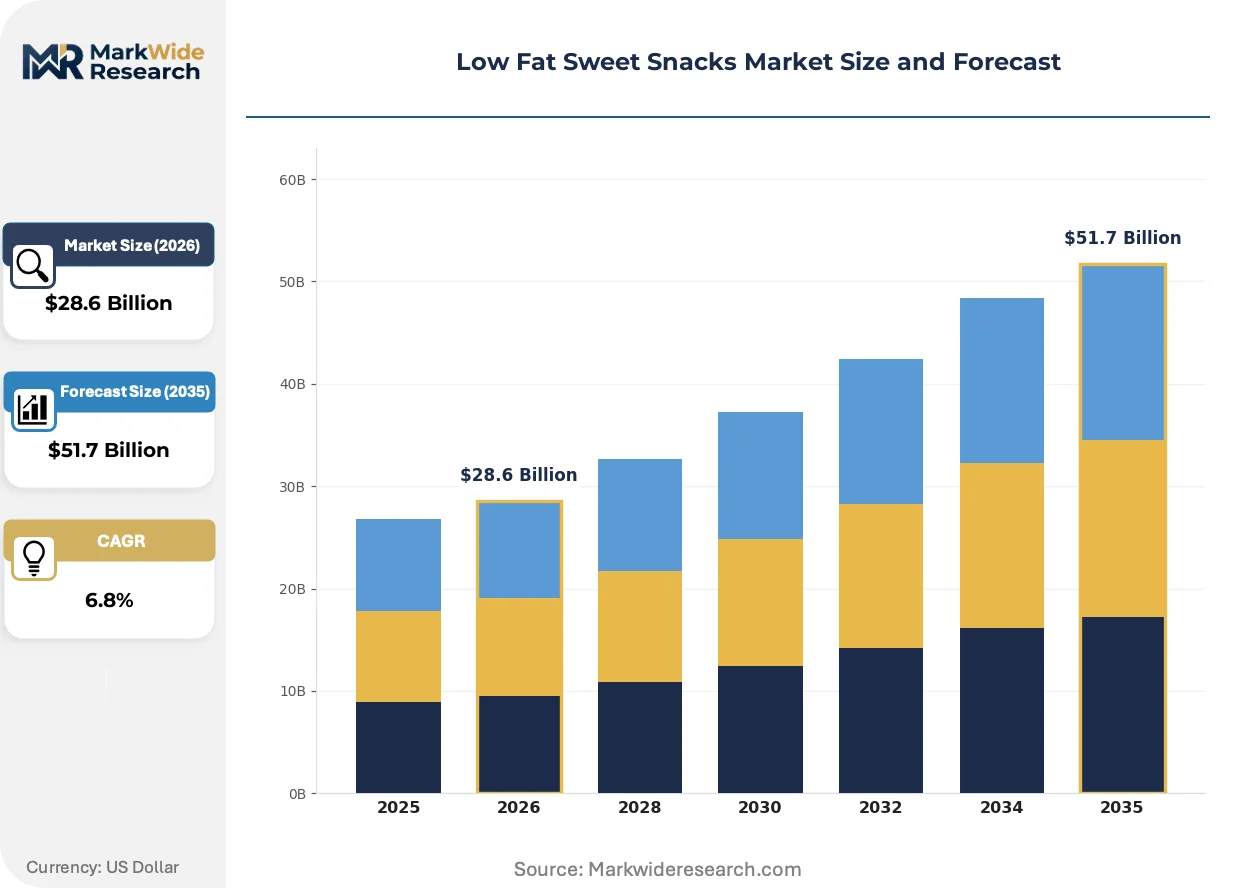
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookies, Cakes, Chocolates, Bars End User: Health-Conscious Consumers, Teens, Families, Fitness Enthusiasts Packaging Type: Single-Serve Packs, Bulk Packaging, Resealable Bags, Boxes Flavor Profile: Chocolate, Vanilla, Fruit, Caramel |
| Companies Covered | General Mills, ITC Limited, Kellogg Company, PepsiCo, Mondelz International, Kraft Heinz Company, The Hain Celestial Group, Nestle, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Sweet Snacks Market Evolving Landscape
Reformulation science is converging with digital sensory mapping tools to compress development cycles, while regulatory transparency mandates and shifting purchase occasions reshape competitive positioning.
Oleogel structuring is absorbing the technical burden of lipid mimetic performance in chocolate and bakery applications. Mid-tier manufacturers in Germany and the United States are adopting these systems at accelerating rates to avoid clean-label disqualification. The technology is absorbing margin pressure from commodity cocoa butter alternatives by enabling stable crystallization at lower saturated fat levels.
EU health claims regulations now mandate substantiated front-of-pack communication, forcing reformulation investments to demonstrate physiological benefit beyond simple fat reduction. This industrial consequence elevates clinical validation costs for market access. The cookies segment faces the steepest compliance burden as heritage recipes resist clean-label adaptation without sensory trade-offs.
Subscription-based personalized nutrition platforms are fragmenting traditional grocery channel dominance for health-positioned sweet snacks. Fitness-oriented end users in Japan and Germany increasingly bypass retail entirely for algorithm-curated monthly deliveries. This behavioral pivot concentrates brand loyalty among direct-relationship players while commoditizing shelf-stable mass-market alternatives.
Low Fat Sweet Snacks Market Segmentation
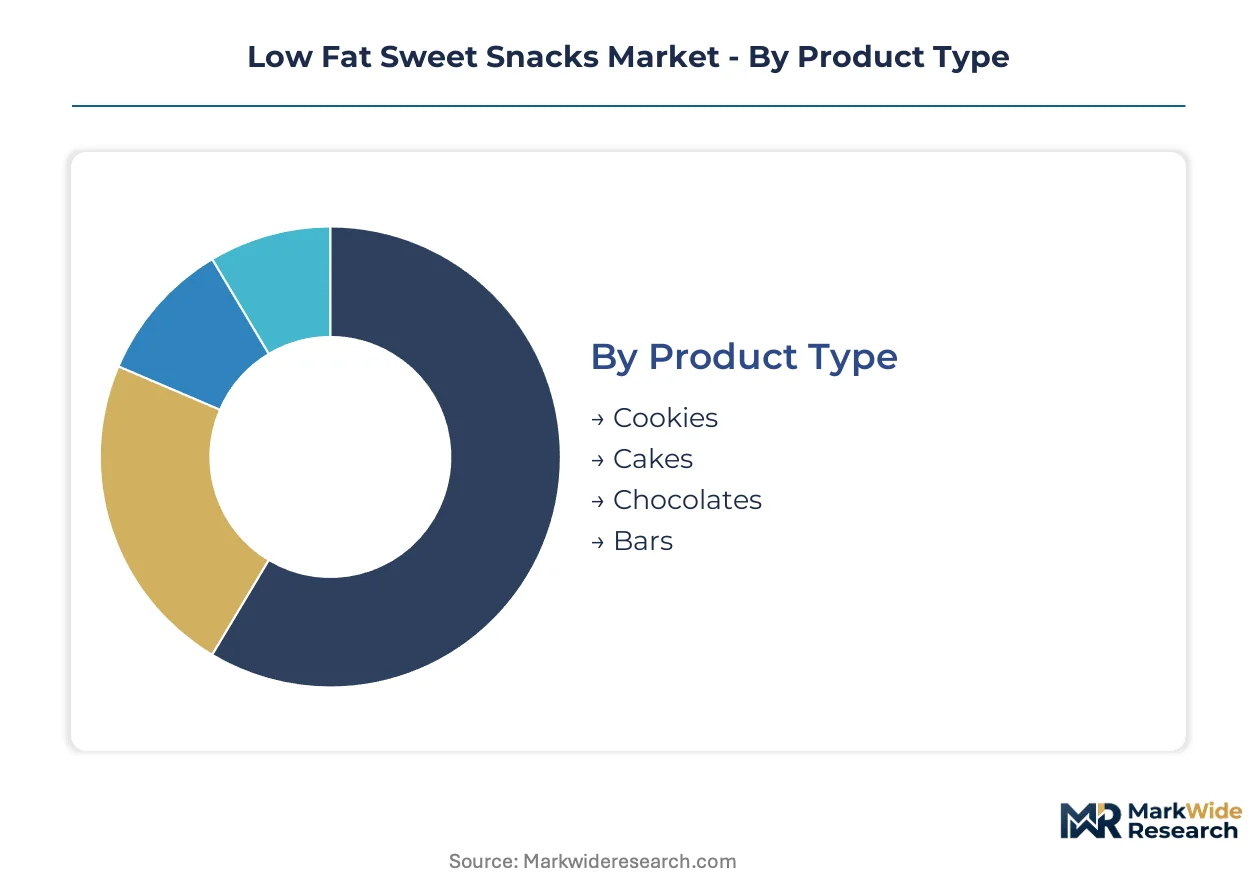
Segmentation in low fat sweet snacks reveals how reformulation investments align with distinct consumption occasions and channel requirements. Manufacturers must match fat replacer technology choices to the sensory tolerance thresholds of each buyer cluster.
Product Type:
Supply concentration in cookies reflects legacy manufacturing infrastructure and established retail shelf space dominance, while emerging categories attract capital seeking growth premiums.
- Cookies:Heritage formulations rely on maltodextrin-based fat replacers to preserve crumb structure under FDA nutritional labeling thresholds. Demand concentrates in United States metropolitan wellness corridors where portion-controlled variants command convenience premiums.
- Bars:Oleogel structuring enables protein-fortified formats that satisfy fitness-oriented end users seeking portable macronutrient balance. German and Japanese direct-to-consumer channels absorb the steepest volume expansion as subscription platforms fragment traditional grocery dominance.
- Cakes:Aerated sponge structures require specialized emulsifier systems to maintain volume at reduced lipid content.
- Chocolates:Cocoa butter alternative crystallization demands precise tempering control for snap and mouthfeel retention.
Today's leader: Cookies. Tomorrow's challenger: Bars.
End User:
Cost tier differentiation separates premium-positioned organic variants from mass-market reformulations, with certification stacking determining margin capture.
- Health-Conscious Consumers:Clean-label certification seekers drive organic and non-GMO layering atop baseline fat reduction. United States and German premium retail channels widen shelf space for compliant portfolios under EU Green Deal nutritional profiling criteria.
- Fitness Enthusiasts:Macro-tracking buyers prioritize protein-carbohydrate ratios and algorithm-curated subscription deliveries. Japan's underdeveloped FOSHU-approved positioning presents untapped functional foods corridor potential relative to Western markets.
- Teens:Flavor-forward positioning with reduced-fat claims navigates school nutrition policies.
- Families:Multi-serve formats balance economy pricing with parental health preference signaling.
The steepest expansion trajectory belongs to Fitness Enthusiasts as personalized nutrition platforms bypass retail gatekeepers.
Packaging Type:
Application-driven format selection determines fat replacer stability requirements and distribution channel compatibility.
- Single-Serve Packs:Highest margin pool through convenience premiums and portion-control positioning. Urban wellness corridors in United States, Germany, and Japan concentrate demand for behavioral alignment with health-conscious consumption patterns.
- Resealable Bags:Extended freshness demands barrier properties that protect oleogel-structured products from oxidative degradation. Fitness-oriented end users in direct-to-subscription channels prefer this format for pantry stocking flexibility.
- Bulk Packaging:Foodservice and institutional channels absorb volume at compressed margins.
- Boxes:Gifting occasions and pantry visibility drive premium shelf placement.
Single-Serve Packs dominate value capture. Resealable Bags gain share fastest in subscription channels.
Flavor Profile:
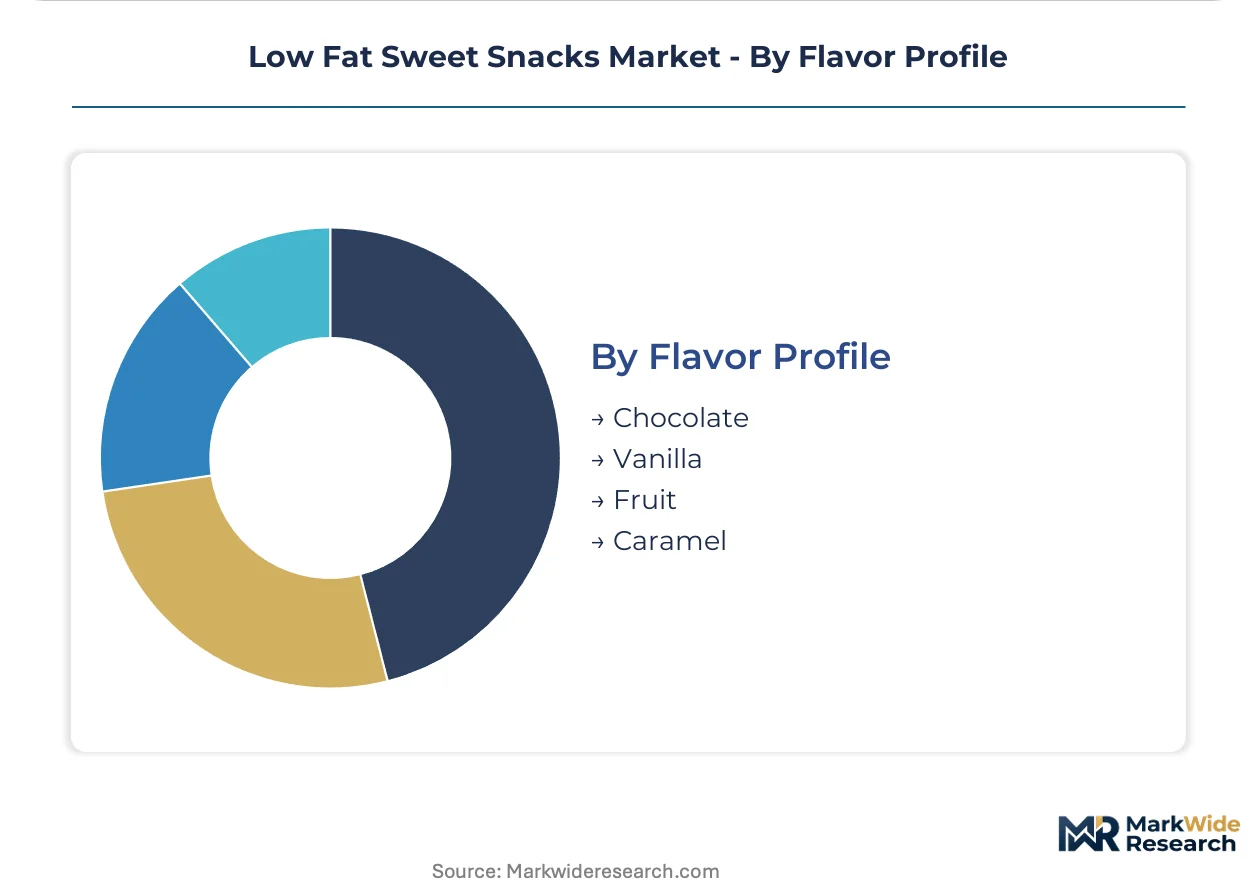
Volume concentration in chocolate masks technical complexity as cocoa butter reduction hits sensory limits above fifty percent lipid replacement.
- Chocolate:Oleogel structuring absorbs margin pressure from commodity cocoa butter volatility by enabling stable crystallization at lower saturated fat levels. EU health claims regulations mandate substantiated front-of-pack communication that elevates clinical validation costs for market access.
- Fruit:Natural acidity masks fat replacer aftertaste, permitting deeper reformulation ambition than dairy-based profiles. German mid-tier manufacturers adopt accelerated rates to avoid clean-label disqualification under tightening EU nutritional profiling.
- Vanilla:Neutral carrier properties suit base formulations for certification stacking.
- Caramel:Maillard reaction complexity challenges clean-label adaptation without sensory trade-offs.
Chocolate anchors volume leadership. Fruit offers the cleanest path to deep reformulation compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The low fat sweet snacks industry traces its commercial origins to 1990s United States health-food retail channels, where early fat replacer technologies first achieved mass-market sensory thresholds. Reformulation capabilities subsequently diffused to European and Japanese manufacturers seeking regulatory-compliant wellness positioning. Today, demand concentrates in metropolitan wellness corridors across three continents where clean-label certification and portion-controlled formats command shelf-space premiums.
United States
Urban wellness corridors in New York, Los Angeles, and Chicago concentrate demand for single-serve portion-controlled formats. FDA nutritional labeling mandates push manufacturers toward substantiated front-of-pack health claims. General Mills leverages North American manufacturing scale to sustain distribution dominance in reduced-fat cookie lines across these metropolitan clusters.
Germany
EU Green Deal nutritional profiling criteria pivot retail buyers toward reformulated sweet snack portfolios with clean-label certification stacking. EFSA health claims regulations mandate clinical validation for permissible front-of-pack communication. Mid-tier manufacturers in Bavaria and North Rhine-Westphalia adopt oleogel structuring at accelerating rates to avoid disqualification under tightening nutritional standards.
Japan
Fitness-oriented end users in Tokyo and Osaka increasingly bypass retail for algorithm-curated subscription deliveries of protein-fortified bars. METI functional foods frameworks and FOSHU approval processes create regulatory pathways for physiological benefit claims. The underdeveloped FOSHU-approved positioning for low-fat sweet snacks presents untapped corridor potential relative to Western markets.
United Kingdom
Health-conscious consumers in London and the Southeast drive organic and non-GMO layering atop baseline fat reduction. FSA front-of-pack labeling schemes align with EU nutritional profiling criteria post-Brexit transitional arrangements. Premium retail channels widen shelf space for compliant portfolios as reformulation investments demonstrate sensory performance without heritage recipe trade-offs.
China
Dual carbon goals under MIIT sustainability frameworks incentivize low-fat processing as energy-intensive fat extraction declines. SAMR national food safety standards shape permissible reformulation claims for urban middle-class consumers in Shanghai and Beijing. Yangtze River Delta manufacturing clusters absorb technology transfer from Western fat replacer system suppliers seeking volume scale.
Low Fat Sweet Snacks Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the low fat sweet snacks landscape, creating a tiered structure where integrated multinationals face agile specialty formulators. The vendor base separates into three strategic archetypes: diversified packaged food conglomerates with reformulation R&D infrastructure, wellness-focused specialty players stacking clean-label certifications, and private-label manufacturers serving retail channel consolidation. Dominant competitive moves include M&A-driven technology acquisition for fat replacer capabilities and strategic partnerships with personalized nutrition platforms bypassing traditional grocery gatekeepers.
Within the diversified conglomerate tier, General Mills and Mondelz International exemplify scale-driven positioning through North American manufacturing footprints and specialized chocolate formulation expertise respectively. The Hain Celestial Group occupies a specialty-tier position representing organic certification stacking that extends reformulation investments into clean-label territory. Among these archetypes, ITC Limited anchors emerging market exposure through its India-based corporate structure. Each represents distinct strategic bets on whether regulatory compliance or wellness-premium positioning delivers superior margin capture.
| Leading Market Players |
|---|
| General Mills |
| ITC Limited |
| Kellogg Company |
| PepsiCo |
| Mondelz International |
| Kraft Heinz Company |
| The Hain Celestial Group |
| Nestle |
| Danone |
| Others |
Value Network & Pricing Analysis
EU Green Deal nutritional profiling mandates are forcing retail buyers toward reformulated portfolios with clean-label certification stacking, compelling manufacturers to absorb oleogel technology costs and compress margins on heritage cookie lines while premium-positioned bars capture pricing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified subscription formats from mass-market retail variants and private-label alternatives. Certification grade and volume scale drive price differentiation, with fitness-oriented algorithm-curated deliveries commanding the highest premiums. Cost compression in standard-tier cookies is intensifying because maltodextrin feedstock volatility feeds into reformulation budgets. Health-conscious urban consumers in Germany and Japan show the least price sensitivity, while family-oriented multi-serve buyers in mass channels exhibit the greatest.
Supply Chain Analysis
China's MIIT domestic-content frameworks and EU Green Deal local sourcing incentives are reshaping fat replacer procurement patterns for manufacturers serving Asian and European markets. Supply concentrates in the United States, Germany, and Japan for finished goods, while cocoa butter alternatives and oleogel precursors draw from Malaysian and Indonesian palm derivative clusters. Single-source vulnerability in specialized emulsifier systems creates exposure to regulatory restriction cascades. Distribution runs through direct-to-subscription platforms that bypass traditional grocery gatekeepers for fitness-oriented end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low fat sweet snacks market reads as a late-cycle quality story where reformulation investments now concentrate on sensory performance thresholds that satisfy algorithm-curated subscription buyers rather than mass-market price competition.
For Market Incumbents: Anchor reformulation R&D spending on oleogel structuring capabilities that exceed 50% lipid reduction sensory limits, defending against agile specialty formulators with patent-protected crystallization methods. Deepen backward integration into cocoa butter alternative supply to offset commodity volatility compression on chocolate lines. Prioritize certification stacking investments that secure EU Green Deal-compliant shelf space before nutritional profiling tightens further. For New Entrants and Emerging Players: FOSHU approval pathways in Japan open a window for protein-fortified bar formats that bypass saturated Western markets. Target Tokyo and Osaka fitness corridors with algorithm-curated subscription positioning that leverages METI functional foods frameworks. White space concentrates in personalized nutrition platforms where heritage manufacturers lack direct-relationship infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier German manufacturers possessing oleogel adoption capability but lacking brand scale to exploit EU nutritional profiling procurement shifts. Long-term viability favors targets with cross-functional food science talent and established clean-label certification stacks. Watch FOSHU approval volume as the inflection signal for Japanese market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Oleogel Technology Licensing | Enables mid-tier manufacturers to meet EU Green Deal thresholds without sensory trade-offs. |
| Direct-to-Consumer Platform Launch | Bypasses retail gatekeepers for fitness-oriented algorithm-curated subscription deliveries. |
| Organic Certification Stacking | Commands shelf-space premiums under tightening FDA and EFSA labeling mandates. |
| Japanese FOSHU Approval Pathway | Unlocks physiological benefit claims in underdeveloped functional foods corridor. |
| Backward Integration into Feedstocks | Reduces exposure to cocoa butter alternative commodity volatility in chocolate lines. |
Research Methodology
Direct dialogue with brand managers at diversified conglomerates, category buyers at German and United States premium retail channels, food science R&D directors, and subscription platform operators combined with FDA filing reviews, EFSA health claims databases, EU Green Deal policy documents, and Nielsen retail audit data. Bottom-up volume modeling triangulates against top-down macroeconomic consumption indicators.
Bottom-up segment-level modeling across product type, end user, packaging format, and flavor profile dimensions integrates with top-down GDP elasticity assumptions across the analysis window. CAGRs derive from curve-fitting historical volume trajectories against regulatory implementation timelines and technology adoption S-curves. Forecast inputs incorporate oleogel structuring penetration rates and FOSHU approval pipeline visibility.
Revisions become necessary when WHO nutrient profiling standards materialize ahead of anticipated national health ministry adoption schedules or when commodity feedstock volatility exceeds historical bands. Forecasts reflect documented assumptions about sensory performance thresholds and regulatory compliance costs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Packaged Rice Snacks Market
Snacks
Fried Potato Chips Market
Snacks
Pretzel Salts Market
Snacks
Asia Pacific Snack Food Market
Snacks
Protein Crisps Market
Snacks
Low Calorie Dip Market
Snacks
Forti Flakes Market
Snacks
Fiber Bars Market
Snacks
Global Protein Snack Market
Snacks
China Snack Bar Market
Snacks
UAE Snack Bar Market
Snacks
Middle East Snack Bar Market
Snacks
Mushroom Based Jerky Market
Snacks
Sweet Potato Fries Market
Snacks
Organic Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market