
 Argentina Snack Bar Market | 2026-2036
Argentina Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Snack Bar Market Outlook
Oat fiber is pivoting toward replacing corn syrup as the dominant binding agent in mid-priced Argentine snack bars, cutting production costs while aligning with clean-label preferences. Arcor leverages its vertically integrated grain milling network to secure supply chain advantages across the Pampas region. Grupo Bimbo sustains bakery-adjacent manufacturing scale that lowers per-unit costs for granola-based lines. Nestlé differentiates through proprietary extrusion technology that preserves protein integrity in ambient storage conditions.
Argentina snack bars are shelf-stable, extruded or cold-pressed food products typically comprising cereals, proteins, sweeteners, and binding agents, manufactured to deliver portable energy or nutritional supplementation within 40-gram single-serve formats. Granola bars occupy the mature volume base, while protein bars capture accelerating demand from gym-affiliated consumers in metropolitan Buenos Aires. Nut bars command premium shelf positioning in health shops and specialized retailers, reflecting higher raw material costs and perceived functional density.
Argentina's national food regulator enforces Mercosur labeling standards that mandate nutritional disclosure and allergen warnings, directly shaping formulation decisions and packaging redesign cycles. The Secretariat of Agriculture, Livestock and Fisheries oversees grain quality standards that affect oat and nut supply chains for domestic bar manufacturers. Stakeholders must monitor pending front-of-pack labeling regulations that could recalibrate permissible health claims and reformulate competitive positioning across flavor and protein tiers.
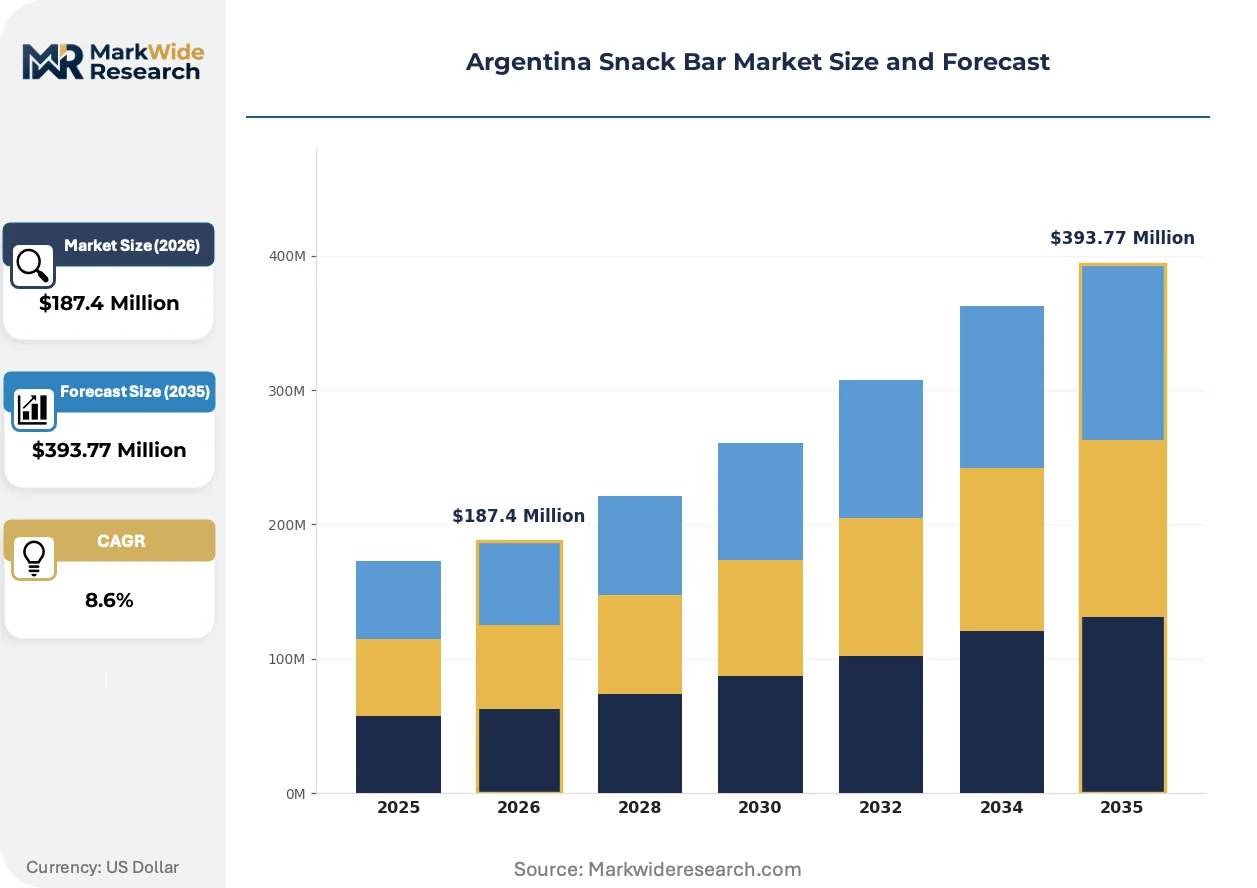
Market Dynamics
Oat fiber substitution for corn syrup is compressing formulation costs while Mercosur labeling mandates force packaging redesign cycles. Buenos Aires gym culture accelerates protein bar demand against this regulatory backdrop.
Growth Catalysts
- Mercosur Food Code:Mandatory nutritional disclosure and allergen warnings create compliance barriers that favor established domestic manufacturers with reformulation capabilities.
- Metropolitan Fitness Culture:Gym-affiliated consumers in Buenos Aires and Córdoba sustain double-digit demand velocity for protein-enriched formats.
- Pampas Grain Infrastructure:Vertically integrated oat milling networks secure supply chain cost advantages for mid-priced product lines.
Market Restraints
- Input Cost Volatility:Argentine nut prices fluctuate with peso instability, compressing margins on premium-positioned nut bar SKUs.
- Supply Concentration Risk:Domestic whey protein relies on concentrated dairy processing capacity in Santa Fe province.
- Regulatory Friction:Pending front-of-pack labeling regulations create formulation uncertainty that delays new product launches.
Strategic Opportunities
- Underpenetrated Interior:Mendoza and Rosario retail corridors show convenience store density gaps versus Buenos Aires.
- E-Commerce Subscription Models:Direct-to-consumer channels bypass traditional wholesale markups for protein bar repeat purchases.
- Clean-Label Binding Agents:Date paste and tapioca syrup converge with oat fiber to replace artificial stabilizers.
Industry Challenges
- Extrusion Technician Scarcity:Protein bar manufacturing requires specialized operators familiar with low-moisture thermal processing.
- Cold Chain Ambiguity:Ambient-stable claims demand validation against Argentina's variable summer storage conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Snack Bar Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Fruit Bars, Nut Bars Flavor Profile: Chocolate, Fruit, Nutty, Spicy Packaging Type: Single Serve, Multipack, Bulk, Recyclable Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Shops |
| Companies Covered | General Mills, The Hershey Company, Arcor, Grupo Bimbo, Skout Backcountry, Nestlé, GEORGALOS HNOS SAICA, Mondelez International, The Kellogg's Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Snack Bar Market Strategic Shifts
Reformulation around plant-based binders and cold-pressed processing is compressing traditional extrusion dominance. Regulatory disclosure requirements and channel fragmentation are simultaneously reshaping competitive positioning.
Extrusion technology is consolidating around proprietary low-temperature systems that preserve protein integrity without refrigeration. Boutique manufacturers in Buenos Aires adopt these systems to compete with multinational ambient-stable portfolios. This consolidation is compressing shelf-life differentiation as a competitive moat.
Mercosur food code amendments mandate expanded allergen warnings and nutritional front-of-pack disclosures. Manufacturers face compressed redesign timelines and reformulation costs. Protein bar SKUs encounter the strictest scrutiny due to composite ingredient lists and health claim density.
Gym-affiliated consumers now bypass traditional retail entirely through specialized subscription services. Buenos Aires metropolitan distributors lose volume to direct brand relationships. This channel rotation is most visible among 25-40 year old protein bar purchasers with established flavor preferences.
Argentina Snack Bar Market Segmentation
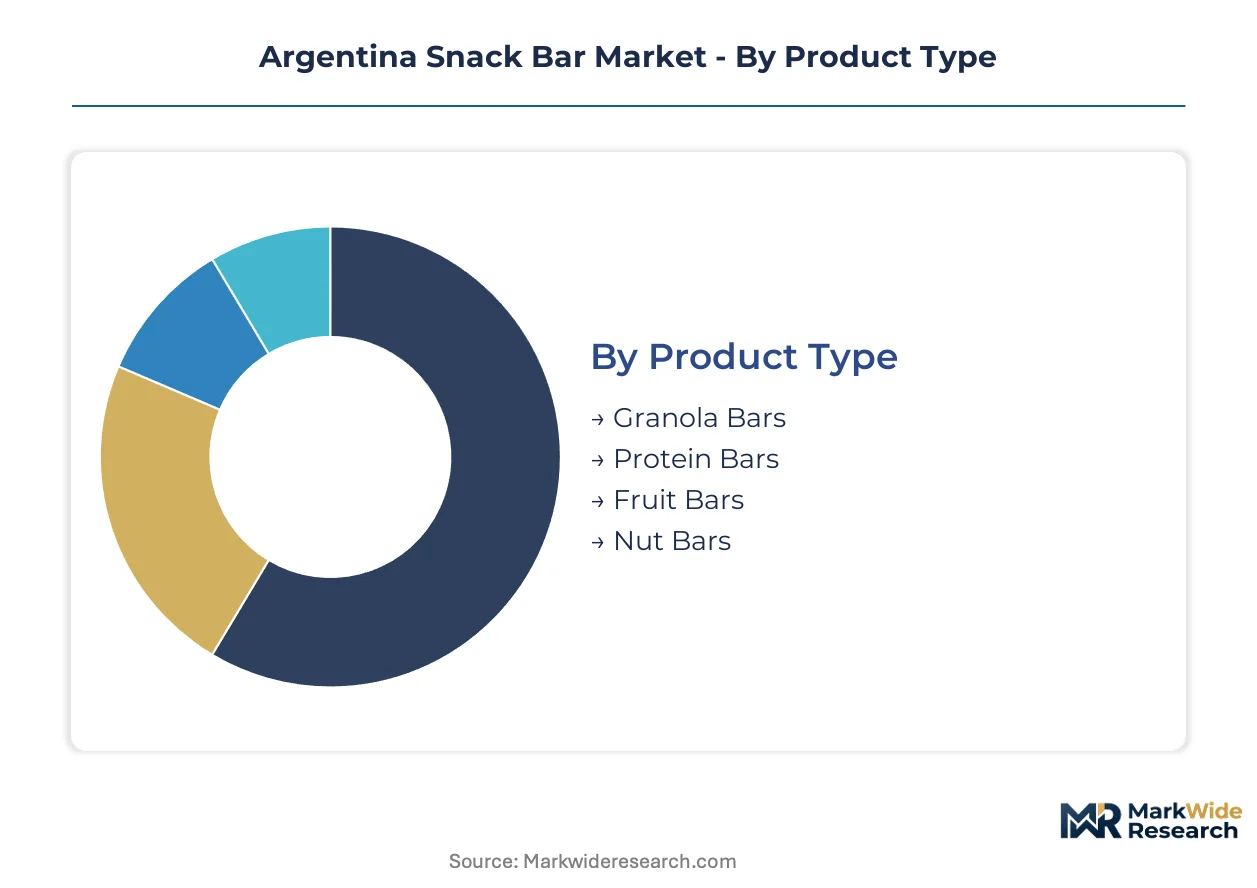
Snack bar manufacturers in Argentina calibrate formulation, packaging, and channel strategy against distinct consumer occasions and price sensitivities. Segmentation reveals where protein density commands premium positioning versus where oat-based formats compete on accessibility.
Product Type:
Extrusion and cold-press specifications differentiate shelf-stable formats across protein targets and binding technologies.
- Granola Bars:Oat and honey-based formulations with moderate protein content dominate unit volumes through supermarket and convenience channels. Buenos Aires families purchase these for school lunchboxes and commuter snacking, sustaining baseline manufacturing runs across Pampas-region facilities.
- Protein Bars:Whey and plant-isolate formats with 15-25g protein per 40g serving capture gym-affiliated demand in metropolitan Buenos Aires and Córdoba. Cold-pressed variants with date-based binding are displacing traditional extruded lines among clean-label purchasers.
- Fruit Bars:Compressed fruit pulp with minimal grain content targets pediatric and natural-food segments.
- Nut Bars:Almond and peanut-dense formulations with higher caloric density occupy premium shelf positioning in specialized health retailers.
Granola bars lead on scale; protein bars lead on momentum.
Flavor Profile:
Flavor development tracks ingredient cost curves and regional palate preferences across Argentina's urban corridors.
- Chocolate:Cocoa-based coatings and inclusions mask protein aftertaste in whey-dominant bars, making this the default formulation for mass-market protein lines. Mendoza and Rosario retail data show chocolate variants outselling fruit alternatives by substantial margins in supermarket placements.
- Fruit:Berry and citrus notes align with clean-label positioning and natural sweetener claims, expanding fastest among subscription-direct purchasers in Buenos Aires.
- Nutty:Peanut butter and almond butter centers leverage domestic nut processing capacity.
- Spicy:Chili and cinnamon variants target experimental urban consumers and export-adjacent formulations.
Chocolate dominates current revenue; fruit flavors are climbing the fastest.
Packaging Type:
Packaging specifications balance Mercosur labeling compliance, shelf-life requirements, and retail channel economics.
- Single Serve:Individual 40g wrappers with full nutritional disclosure panels satisfy convenience store and gym vending requirements. Buenos Aires commuters purchase these for immediate consumption, driving highest velocity in urban convenience corridors.
- Multipack:4-6 count boxes reduce per-unit packaging cost for supermarket pantry stocking.
- Bulk:Unwrapped or minimal-pack formats serve foodservice and institutional channels.
- Recyclable:Paper-based and mono-material wrappers respond to pending extended producer responsibility regulations.
Single serve commands channel presence; recyclable formats are gaining share fastest.
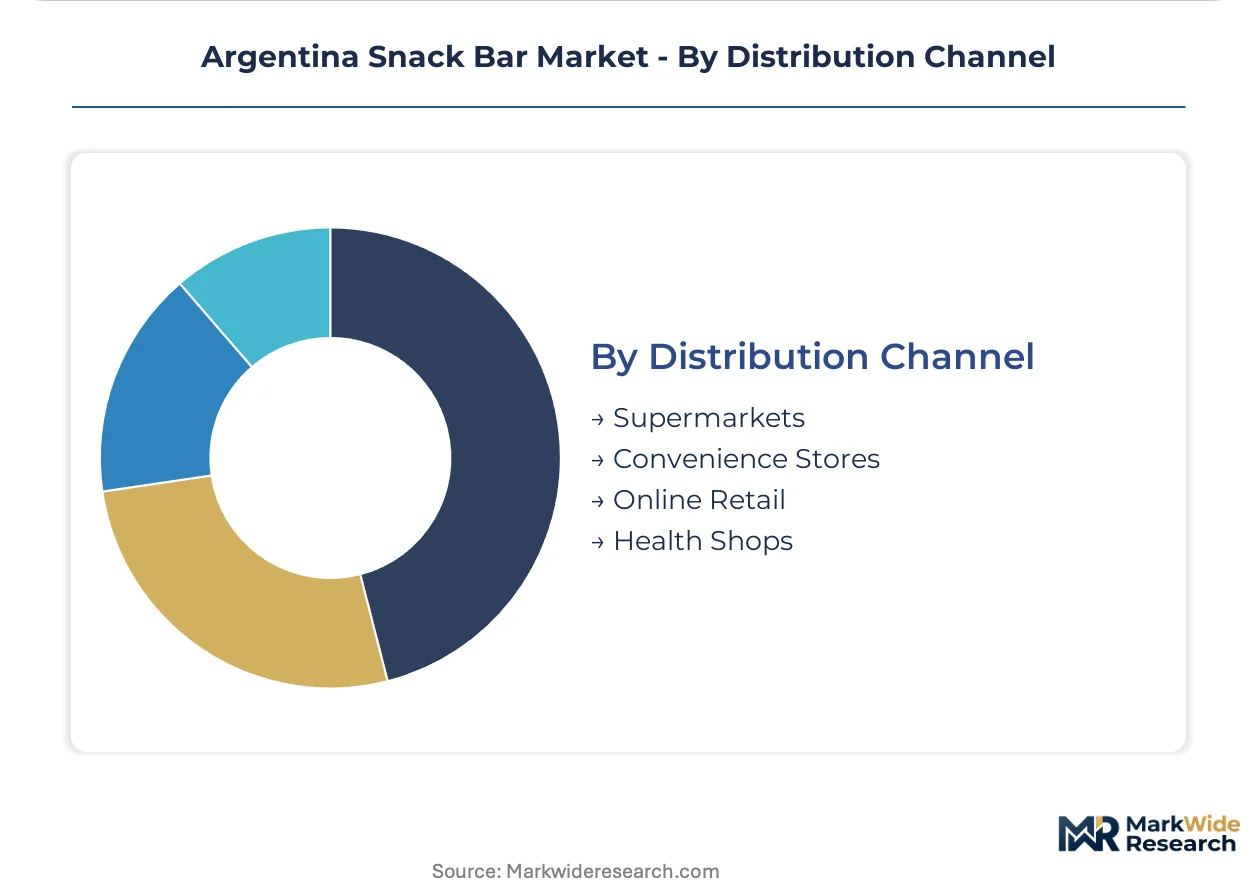
Distribution Channel:
Channel selection determines margin structure and consumer relationship depth across Argentina's fragmented retail landscape.
- Supermarkets:Multi-brand shelf sets with promotional stacking drive volume for granola and mid-tier protein lines. Córdoba and Buenos Aires hypermarket chains negotiate annual listing fees that favor established manufacturers with reformulation capabilities.
- Convenience Stores:Impulse-oriented placements near checkout capture commuter and late-night demand in urban centers.
- Online Retail:Direct-to-consumer and marketplace platforms bypass wholesale markups for subscription protein bar purchases.
- Health Shops:Specialized retailers in Buenos Aires Palermo and Recoleta neighborhoods command premium positioning for clean-label and organic-certified lines.
Supermarkets lead on scale; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buenos Aires anchors Argentine snack bar demand through dense gym networks and convenience retail corridors that concentrate purchasing power. The Pampas grain belt supplies oat and wheat inputs to vertically integrated manufacturers. Provincial capitals lag in protein bar penetration but show accelerating granola adoption.
Buenos Aires Province
Metropolitan fitness culture drives protein bar velocity through specialized health shops in Palermo and Recoleta neighborhoods. The Secretariat of Agriculture oversees grain quality standards affecting local oat milling operations. San Isidro and Vicente López retail corridors command premium shelf positioning for clean-label formats.
Córdoba
Gym-affiliated consumers sustain double-digit demand for whey-isolate bars in Argentina's second-largest metropolitan area. Mercosur food code compliance costs filter smaller brands from supermarket shelf sets. Villa Carlos Paz and Río Cuarto secondary markets show convenience store density gaps versus the capital corridor.
Santa Fe
Domestic whey protein processing concentrates in this province's dairy manufacturing belt, creating supply chain dependencies for bar manufacturers. The national food regulator audits allergen disclosure compliance at production facilities. Rosario retail corridors underperform Buenos Aires in protein bar velocity but lead in granola multipack volumes.
Mendoza
Wine tourism corridors create seasonal demand spikes for portable snack formats among international visitors. Provincial commerce regulations govern health claim permissions on packaging distributed through Andean border crossings. Mendoza City convenience penetration trails national averages, leaving whitespace for direct-to-consumer subscription models.
Argentina Snack Bar Market Competitive Environment
Global majors compete with regional champions across formulation expertise and distribution reach in Argentina's snack bar sector. The market structures around three tiers: multinational CPG conglomerates with extrusion technology advantages, Latin American regional players with Pampas grain integration, and domestic specialists with clean-label positioning. Strategic moves concentrate on portfolio diversification into protein-enriched lines and backward integration into oat milling capacity.
Within the multinational tier, General Mills and Nestlé occupy positions defined by proprietary manufacturing scale and ambient-stable formulation capabilities. Arcor and Grupo Bimbo exemplify regional champions leveraging captive supply chains across Argentine grain belts. Mondelez International and The Hershey Company represent confectionery-origin diversifiers reformulating chocolate expertise into bar formats.
| Leading Market Players |
|---|
| General Mills |
| The Hershey Company |
| Arcor |
| Grupo Bimbo |
| Skout Backcountry |
| Nestlé |
| GEORGALOS HNOS SAICA |
| Mondelez International |
| The Kellogg's Company |
| Others |
Value Chain & Pricing Dynamics
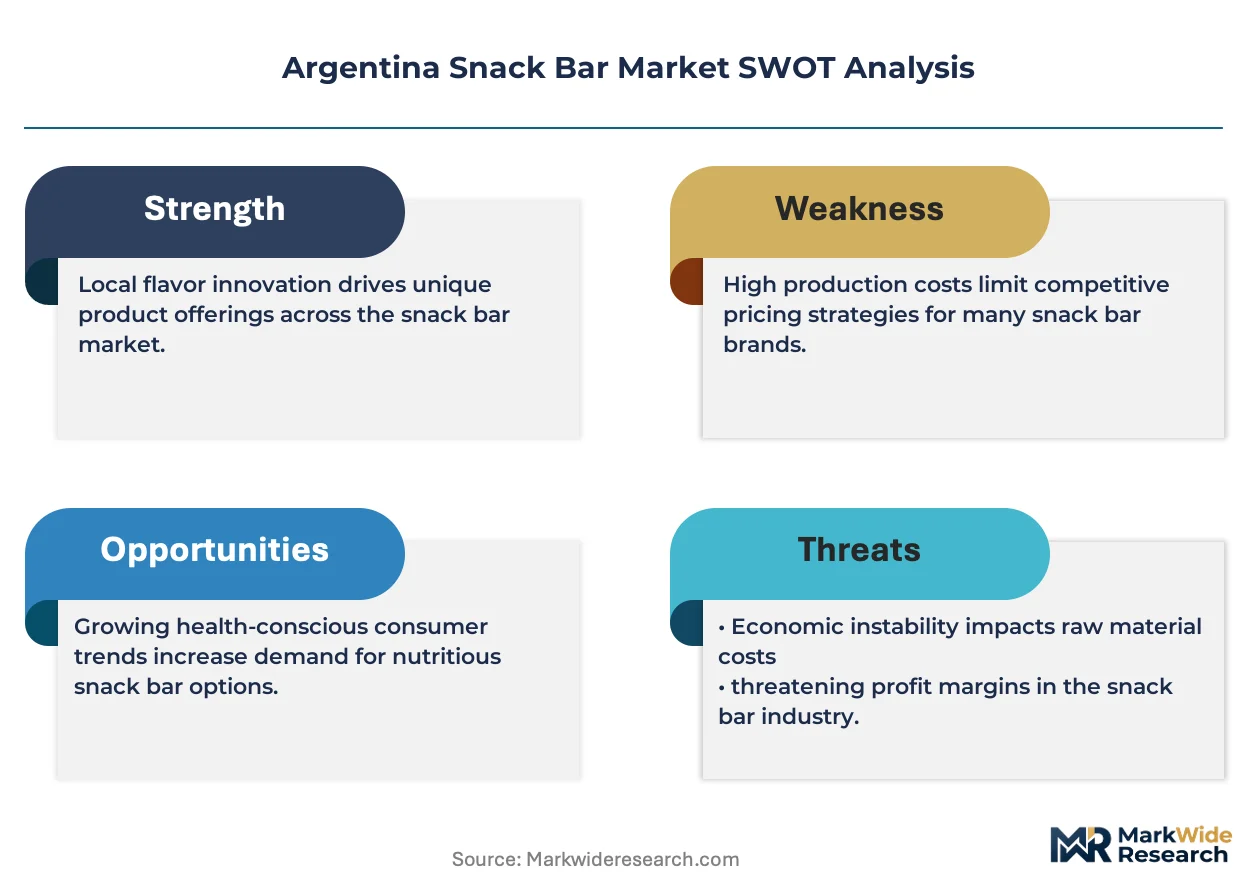
Mercosur front-of-pack labeling mandates gate qualified supply for premium-tier Argentine snack bars, restricting clean-label positioning to manufacturers with reformulation capital while compressing margin recovery across mid-priced oat-based lines. Buenos Aires health shops enforce certification premiums that Santa Fe and Mendoza retail corridors cannot replicate, fragmenting pricing power by geography.
Pricing Analysis
Input-cost pass-through from Argentine peso volatility shapes tiered pricing across protein, granola, and nut bar categories. Three-tier pricing structure across premium, standard, and economy levels separates whey-isolate formulations with cold-pressed processing from extruded mid-market lines and corn-syrup-bound economy SKUs. Cost compression in nut bars intensifies because almond and peanut prices fluctuate with currency instability, squeezing margins on premium-positioned SKUs. Gym-affiliated subscribers in metropolitan Buenos Aires show least price sensitivity, while provincial convenience store purchasers in Rosario and Mendoza drive volume through promotional multipacks.
Supply Chain Analysis
Freight cost differentials between Pampas-region oat milling centers and coastal protein processing facilities in Santa Fe province compress logistics economics for interior distribution. Domestic supply draws from Argentina's grain belt for oat and wheat inputs, Brazil for whey protein concentrate, and Chile for specialty nut imports. Single-source vulnerability concentrates in Santa Fe dairy processing capacity, where domestic whey protein production anchors bar manufacturing. Distribution runs through vertically integrated Arcor and Grupo Bimbo networks for supermarket and convenience penetration, with direct-to-consumer channels bypassing wholesale markups for subscription protein bar purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina snack bar market structure rewards geographic arbitrage between Buenos Aires premium positioning and underpenetrated provincial corridors, exploiting regulatory compliance cost differentials that filter smaller brands from metropolitan shelf sets.
For Market Incumbents: Cement cold-pressed manufacturing capabilities against extrusion technology commoditization, while securing captive oat milling capacity across the Pampas region to defend margin position against peso-driven input volatility. Arcor and Grupo Bimbo should prioritize backward integration into date paste and tapioca syrup supply chains before Mercosur labeling mandates accelerate clean-label reformulation costs. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models targeting Mendoza and Rosario retail corridors, where convenience store density gaps and lower regulatory compliance burdens create whitespace versus Buenos Aires saturation. Cold-pressed protein bars with date-based binding offer the most penetrable segment, leveraging gym-affiliated consumer willingness to bypass traditional wholesale channels entirely. For Investors and Strategic Acquirers: Roll-up economics work for boutique clean-label manufacturers because Mercosur disclosure requirements create fixed compliance costs that disadvantage sub-scale operators without reformulation infrastructure. Acquisition targets should demonstrate proprietary low-temperature extrusion technology or established subscription direct relationships with Buenos Aires metropolitan consumers. Watch front-of-pack labeling regulation finalization as inflection indicator for accelerated consolidation among non-compliant smaller brands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Milling | Captive Pampas grain supply secures cost advantage against peso-driven input volatility for mid-priced lines. |
| Cold-Pressed Manufacturing Scale-Up | Proprietary low-temperature systems preserve protein integrity without refrigeration, differentiating ambient-stable portfolios. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional wholesale markups and captures gym-affiliated repeat purchases in Buenos Aires metropolitan corridors. |
| Clean-Label Reformulation Investment | Date paste and tapioca syrup substitution aligns with pending Mercosur front-of-pack disclosure requirements. |
| Provincial Distribution Channel Expansion | Mendoza and Rosario convenience store penetration addresses density gaps versus saturated Buenos Aires retail. |
Study Parameters
Bottom-up snack bar consumption modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with brand managers at multinational CPG firms, category buyers at Buenos Aires supermarket chains, supply planners at oat milling operations, and channel sales heads at regional distributors were validated against secondary sources including Argentine customs records, Secretariat of Agriculture grain quality filings, and Nielsen retail audit data for Córdoba and Mendoza corridors.
Historical trendline analysis of protein bar velocity versus granola bar volume established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with protein density tiers and binding technology specifications as industry-specific overlays. CAGRs were derived from reconciling bottom-up demand estimates with top-down manufacturing capacity constraints, incorporating oat fiber substitution rates and cold-pressed adoption curves as forecast inputs.
Inputs from Argentine regulatory filings and Pampas-region grain production databases were available through the study window; gaps in real-time provincial retail scanner data introduce uncertainty bands around interior market penetration assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Fruit Jerky Market
Snacks
Marshmallow Market
Snacks
India Snack Bar Market
Snacks
North America Snack Pellets Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Global Protein Snack Market
Snacks
UAE Snack Bar Market
Snacks
No Fat Snacks Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Savory Snacks Market
Snacks
Low Fat Sweet Snacks Market
Snacks
Seafood Snacks Market
Snacks
Veggie Chips Market
Snacks
Qatar Potato Chips Market
Snacks
France Energy Bar Market
Snacks
Middle East Snack Bar Market