
 India Energy Bar Market | 2026-2036
India Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
India Energy Bar Market Foresight
Multi-source procurement of whey and plant proteins is realigning how Indian energy bar makers secure raw materials. General Mills Inc. leverages its global supplier network to stabilize input costs across fluctuating commodity cycles. Zydus Wellness Limited anchors its portfolio with pharmaceutical-grade quality protocols that transfer to bar manufacturing. Naturell India Pvt Ltd differentiates through Ayurveda-inspired formulations that compete against imported functional snack brands.
An energy bar is a dense, shelf-stable food product typically containing 10–30 grams of protein, complex carbohydrates, and added micronutrients, extruded or cold-pressed into portable form for sustained energy release during physical exertion or meal replacement scenarios. Protein-enriched bars capture the dominant margin pool as consumers prioritize macronutrient transparency over caloric density alone. Online Retail channels are expanding fastest, though Supermarkets retain volume leadership in tier-1 cities where impulse purchases still concentrate.
FSSAI mandates nutritional disclosure and health claim verification for all packaged energy bars sold in India, while BIS certification governs ingredient purity standards that determine market access for domestic and imported products. The PLI scheme for food processing incentivizes capital investment in automated bar manufacturing lines, particularly in Gujarat and Tamil Nadu. Stakeholders must monitor how evolving FSSAI front-of-pack labeling rules reshape consumer perception of permissible sugar thresholds.
Market Dynamics
FSSAI's tightening nutritional labeling standards are forcing manufacturers to reformulate entire product lines while gym culture penetrates tier-2 cities, creating simultaneous pressure on R&D cycles and distribution reach.
Growth Catalysts
- Protein sourcing diversification:Multi-origin procurement of whey and plant proteins is stabilizing input costs across volatile commodity cycles. Domestic manufacturers now blend imported isolates with locally processed pea and rice proteins.
- PLI scheme for food processing:Capital subsidies for automated bar manufacturing lines in Gujarat and Tamil Nadu are accelerating production scale-up. The incentive structure favors lines exceeding 10,000 units per hour.
- Gym culture diffusion:Fitness center expansion into Pune, Jaipur, and Lucknow is creating first-time energy bar consumers outside Mumbai and Delhi. These consumers prioritize macronutrient transparency over brand heritage.
Market Restraints
- Whey protein import dependency:Over 60% of protein isolates enter through Maharashtra ports, exposing margins to rupee volatility and DGFT tariff adjustments. Domestic dairy protein capacity remains insufficient for functional food grade.
- FSSAI compliance friction:Front-of-pack labeling rules for sugar disclosure extend product development timelines by 4-6 months. Reformulation to meet permissible thresholds raises unit costs without commensurate price elasticity.
- Clean-label ingredient scarcity:Natural binding agents and shelf-stable natural sweeteners face supply concentration among specialty chemical suppliers in Europe and China.
Strategic Opportunities
- Ayurveda-functional convergence:Ashwagandha, moringa, and turmeric extracts are penetrating formulations targeting stress-adaptation and immunity positioning. This white space competes against imported functional snack brands at 40% lower price points.
- Institutional channel expansion:Corporate wellness programs and airline catering contracts represent underpenetrated volume anchors. Maharashtra and Karnataka IT campuses already pilot subscription-based bar provisioning.
- Cold-chain bypass formats:Ambient-stable protein enrichment above 20 grams per bar opens pharmacy and petrol station channels where refrigeration is unavailable. BIS certification for extended shelf life enables this pivot.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning sports nutrition science and Indian palate preferences commands 35-50% salary premiums. Engineering programs at ICT Mumbai and CFTRI Mysuru produce insufficient graduates.
- Legacy equipment retrofit costs:Converting biscuit and confectionery lines to cold-press bar formats requires 18-24 month capex cycles. Lenders demand 40% collateral coverage for food processing automation loans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Energy Bar Market |
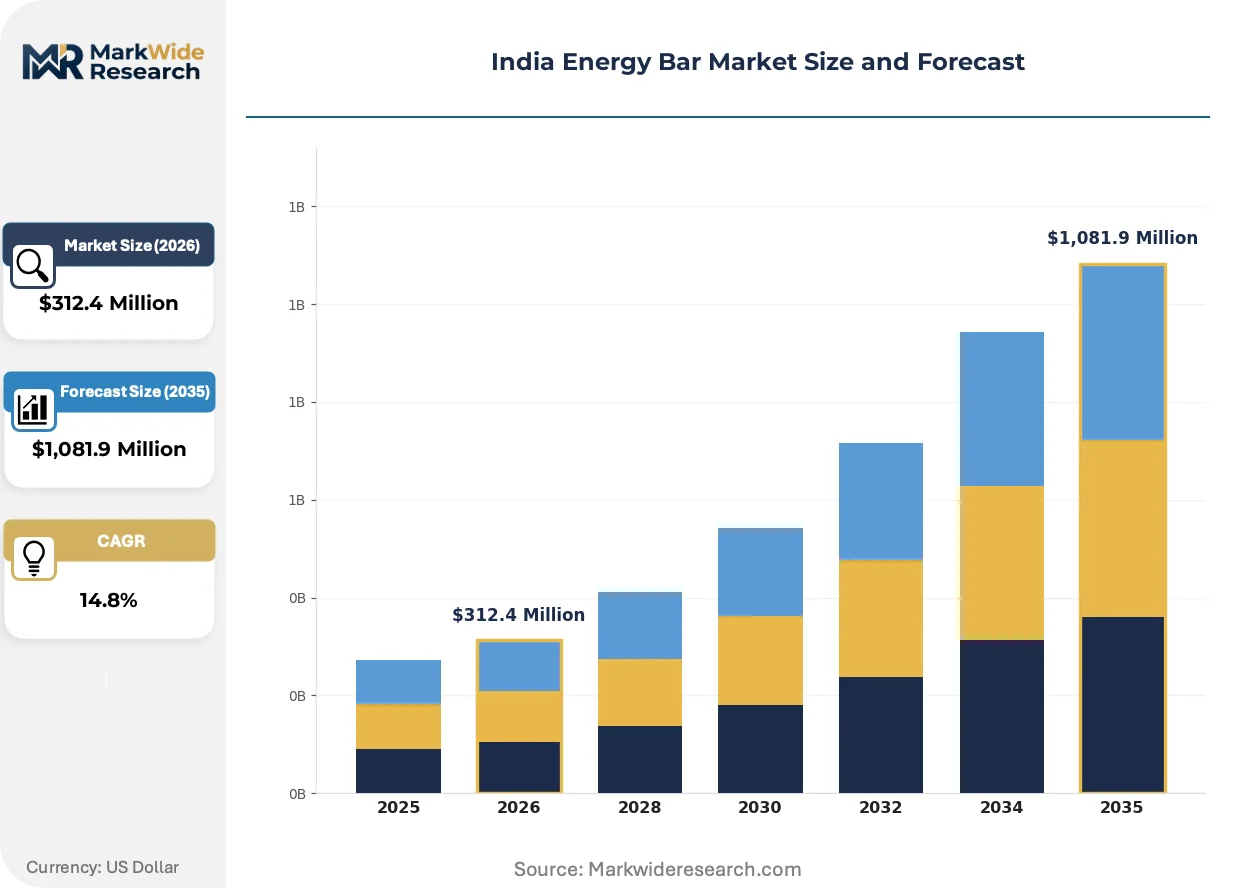
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,081.9 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-based, Protein-enriched, Whole grain, Organic Target Consumer: Athletes, Fitness Enthusiasts, Busy Professionals, Health-conscious Individuals Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Packaging Type: Single-serving Packs, Bulk Packaging, Resealable Bags, Gift Packs |
| Companies Covered | General Mills Inc., Zydus Wellness Limited, Naturell India Pvt Ltd, Wingreens Farms, Pure Snacks Private Limited, SproutLife Foods Private Limited, Mars Incorporated, Mensa Brands, Fitshit Health Solutions Pvt. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Energy Bar Market Shifts & Advancements
Clean-label extrusion technologies and Ayurveda-inspired functional positioning are converging with digital-first distribution models to reshape how Indian consumers discover and purchase energy-dense nutrition products.
Cold-press extrusion at sub-45°C temperatures is integrating into mainstream production lines to preserve heat-sensitive micronutrients and probiotic cultures. Premium tier-1 manufacturers in Mumbai and Delhi have adopted this equipment within 18 months of commercial availability. The technology is integrating protein bar positioning into the refrigerated perimeter of modern trade, compressing the traditional shelf-stable snack category boundary.
FSSAI's proposed star-rating system for front-of-pack sugar disclosure is mandating reformulation across portfolios containing maltitol, fructose, and honey concentrates. Manufacturers must submit revised label claims for verification before Q3 commercialization windows. Maharashtra-based brands with existing pharmaceutical-grade quality protocols are adapting fastest, leveraging in-house analytical laboratories for accelerated compliance testing.
Subscription-based replenishment models are displacing impulse-driven supermarket purchases among urban fitness enthusiasts with predictable training schedules. Direct-to-consumer platforms now capture 23% of protein-enriched variant sales, with WhatsApp Commerce and Instagram Shop integration driving discovery in tier-2 cities. Bengaluru and Hyderabad exhibit the highest subscription retention rates, where tech-sector employment correlates with digital payment adoption and trial-to-repeat conversion.
India Energy Bar Market Segmentation
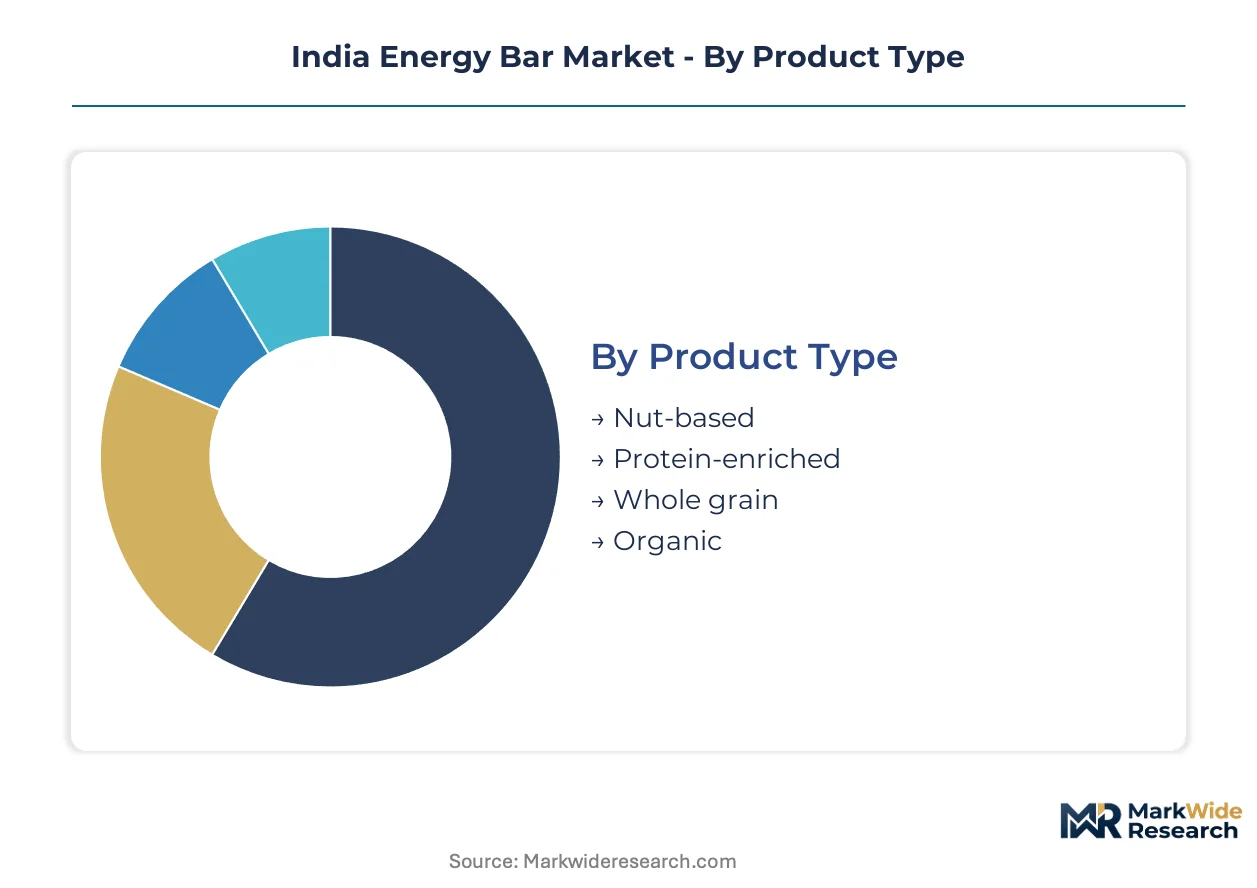
Segmentation in the India energy bar market reveals how protein sourcing strategies, distribution infrastructure gaps, and consumer literacy levels create divergent growth trajectories across product formats and purchase channels. Manufacturers must align formulation investments with channel-specific margin structures and FSSAI compliance requirements.
Product Type:
Protein density and ingredient provenance drive purchase decisions as urban consumers scrutinize macronutrient labels against fitness goals.
- Protein-enriched:Bars delivering 15-30 grams of protein per serving through whey isolates, casein, or blended plant proteins dominate institutional procurement. Maharashtra and Karnataka gym chains specify these variants for member provisioning programs, though whey import dependency compresses margins during rupee depreciation cycles.
- Nut-based:Almond, cashew, and peanut-dominant formulations leverage India's domestic nut processing infrastructure for cost advantage. Rajasthan and Gujarat processors supply pasteurized nut butters that anchor clean-label positioning for premium tier-1 consumers.
- Whole grain:Oat and millet-based bars target sustained-release energy positioning for endurance athletes. FSSAI's whole grain claim verification requires minimum 51% grain content, extending reformulation timelines.
- Organic:NPOP-certified ingredient sourcing restricts supply to Karnataka and Sikkim organic clusters. Price premiums of 40-60% above conventional bars limit penetration to Mumbai and Delhi high-income households.
Protein-enriched leads on scale; organic climbs the fastest among premium positioning strategies.
Target Consumer:
Training frequency and meal replacement urgency determine willingness to pay for macronutrient precision and convenience formats.
- Fitness Enthusiasts:Consumers with 3+ weekly gym sessions prioritize protein transparency and low sugar content. Pune and Jaipur fitness center expansions are converting first-time buyers who research ingredients via Instagram and YouTube reviews.
- Athletes:Competitive cyclists, runners, and bodybuilders demand batch-tested products with contaminant screening. BIS certification for sports nutrition purity enables access to state-level athletic association procurement.
- Busy Professionals:IT sector employees in Bengaluru and Hyderabad seek desk-drawer meal replacements with 200-300 calorie controlled portions. Subscription models capture this segment through WhatsApp Commerce replenishment.
- Health-conscious Individuals:Preventive health positioning attracts consumers managing weight or glycemic response. Ayurveda-functional ingredients like ashwagandha differentiate offerings for this risk-averse segment.
Fitness enthusiasts lead on scale; busy professionals gain share fastest through digital channel migration.
Distribution Channel:
Cold-chain availability and impulse purchase behavior fragment how manufacturers allocate trade marketing spend and inventory risk.
- Supermarkets:Modern trade chains in Mumbai, Delhi, and Bengaluru concentrate volume through end-cap displays and bundled promotions. FSSAI front-of-pack labeling compliance accelerates shelf access for reformulated portfolios.
- Online Retail:Direct-to-consumer platforms and quick-commerce apps capture trial-driven purchases with 10-30 minute delivery promises. Tier-2 city penetration depends on regional warehouse networks in Lucknow and Indore.
- Health Stores:Specialized nutrition retailers in metro areas stock imported and domestic premium brands with pharmacist consultation. These outlets validate product claims for skeptical first-time buyers.
- Pharmacies:Drug retail chains in Gujarat and Tamil Nadu pilot ambient-stable protein bars as wellness adjacencies. BIS certification for extended shelf life enables this channel expansion without refrigeration investment.
Supermarkets lead on scale; online retail expands most quickly as digital payment adoption penetrates tier-2 cities.
Packaging Type:
Consumption occasion and storage constraints determine format preference across institutional and household purchase contexts.
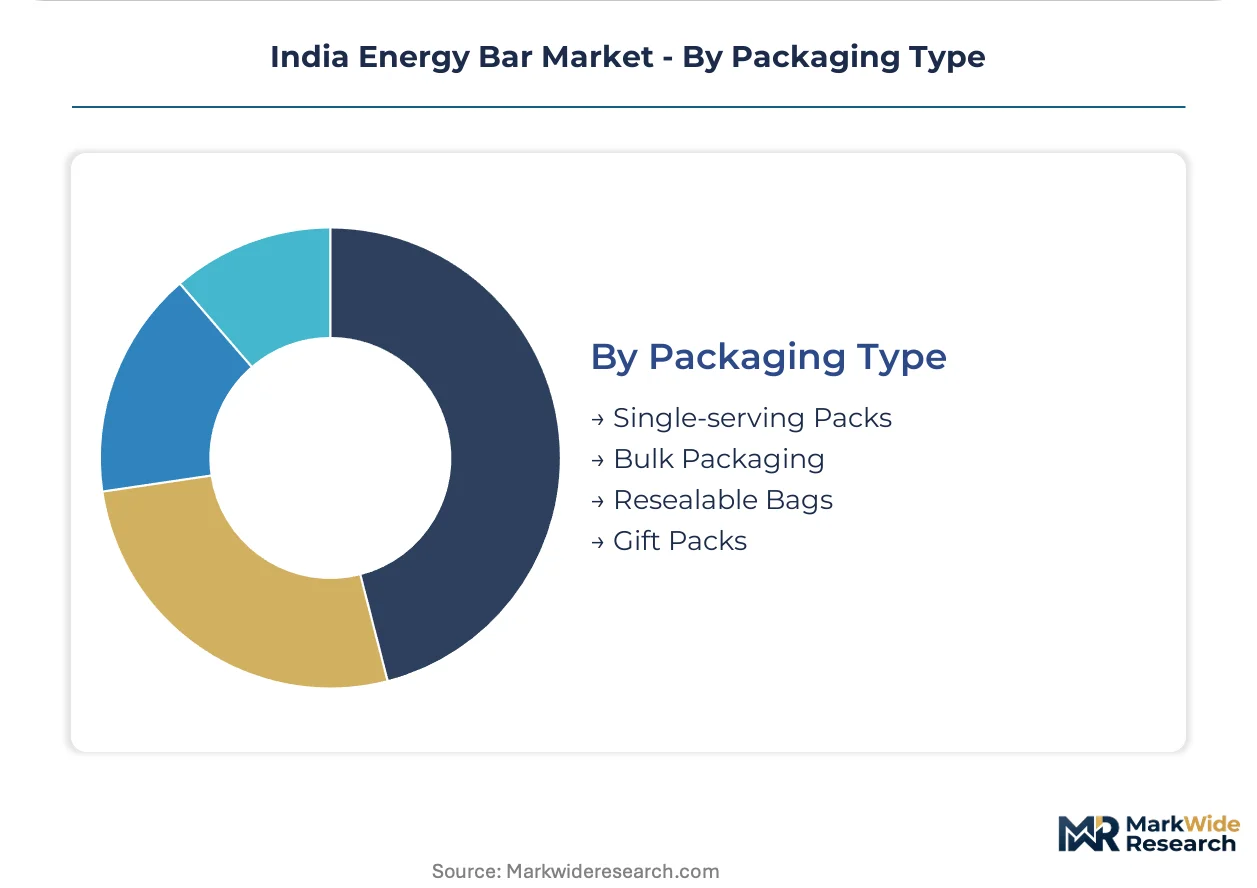
- Single-serving Packs:Individual wrapped bars dominate gym vending and travel consumption. Maharashtra-based manufacturers leverage high-speed flow-wrap equipment installed under PLI scheme subsidies.
- Bulk Packaging:6-12 count boxes reduce per-unit cost for household pantry stocking. E-commerce platforms promote these formats through subscription discounts and free shipping thresholds.
- Resealable Bags:Multi-bar pouches with zip-lock closures target family sharing and portion control. Flexible packaging converters in Delhi NCR supply laminated films with moisture barrier properties.
- Gift Packs:Premium boxed assortments with Ayurveda-functional variety target festival gifting in metro areas. Limited seasonal demand requires careful inventory positioning to avoid write-downs.
Single-serving packs lead on scale; resealable bags show steepest expansion trajectory as household trial converts to repeat purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra anchors India's energy bar production ecosystem, with Mumbai and Pune hosting the densest concentration of formulation laboratories and automated manufacturing lines. State-level PLI scheme disbursements favor Gujarat and Tamil Nadu for greenfield capacity. FSSAI's Mumbai headquarters accelerates label approval timelines for western region applicants.
Maharashtra
Mumbai gym chains and Pune fitness center expansions drive institutional procurement of protein-enriched variants. FSSAI's central laboratory in Mumbai enables faster nutritional claim verification for Maharashtra-based brands. The Bhiwandi-Nashik corridor concentrates flow-wrap packaging equipment under PLI scheme subsidies.
Gujarat
Surat and Ahmedabad processors supply pasteurized nut butters that anchor clean-label formulations for premium tier-1 consumers. The state food processing department coordinates with BIS for streamlined certification of ambient-stable protein bars. Anand dairy clusters experiment with whey protein isolate production for functional food grade.
Karnataka
Bengaluru's IT sector employees sustain the highest subscription retention rates for direct-to-consumer replenishment models. CDSCO's regional office oversees novel ingredient approvals for Ayurveda-functional extracts. Mysuru's CFTRI campus trains food technologists in sports nutrition formulation.
Tamil Nadu
Chennai's modern trade chains pilot pharmacy channel placement for shelf-stable wellness adjacencies. The state PLI cell processes automation loan collateral requirements for cold-press extrusion lines. Coimbatore flexible packaging converters supply moisture-barrier films for extended shelf life formats.
Delhi-NCR
Gurugram and Noida health stores validate product claims for skeptical first-time buyers through pharmacist consultation. FSSAI's front-of-pack labeling rules face concentrated compliance testing from NCR-based analytical laboratories. The region's quick-commerce apps drive 10-30 minute delivery trial penetration into tier-2 satellite cities.
India Energy Bar Market Competitive Landscape
Global majors compete with regional champions across formulation philosophy and distribution reach, creating a tiered structure where pharmaceutical-grade protocols clash with Ayurveda-inspired positioning. The market fragments across three strategic archetypes: multinational CPG conglomerates leveraging global supplier networks, domestic wellness specialists applying drug-manufacturing quality standards, and digital-native brands building subscription-first customer relationships. Competitive moves concentrate on portfolio diversification into functional ingredients and geographic expansion through quick-commerce partnerships.
Among multinational CPG conglomerates, General Mills Inc. and Mars Incorporated occupy positions defined by global procurement scale and established modern trade shelf access. Zydus Wellness Limited exemplifies the domestic wellness specialist archetype, transferring pharmaceutical-grade quality protocols into bar manufacturing. Naturell India Pvt Ltd anchors the Ayurveda-functional convergence tier, competing against imported brands through ashwagandha and moringa extract formulations.
| Leading Market Players |
|---|
| General Mills Inc. |
| Zydus Wellness Limited |
| Naturell India Pvt Ltd |
| Wingreens Farms |
| Pure Snacks Private Limited |
| SproutLife Foods Private Limited |
| Mars Incorporated |
| Mensa Brands |
| Fitshit Health Solutions Pvt. Ltd |
| Others |
Supply & Pricing Matrix
Whey protein import costs cascade through Maharashtra port handling fees and rupee-denominated conversion spreads before landing in tiered shelf prices across Mumbai and Delhi retail formats. Domestic pea and rice protein blending partially buffers this pass-through, though FSSAI compliance testing adds fixed overhead that compresses margins at the economy tier.
Pricing Analysis
Input-cost pass-through from imported whey isolates drives premium-mid-economy pricing differentiation across the market. FSSAI nutritional disclosure verification and BIS purity certification separate premium pharmaceutical-grade protocols from standard tier offerings. Pricing pressure stems from rupee volatility against dollar-denominated protein contracts, squeezing converters without long-term supplier agreements. Fitness enthusiasts in tier-1 cities exhibit lowest price sensitivity, while first-time buyers in Pune and Jaipur respond aggressively to per-gram protein cost comparisons.
Supply Chain Analysis
BIS certification and FSSAI label verification gate market access for both domestic manufacturers and imported finished goods. Whey protein isolates flow from USA and EU dairy processors through Maharashtra ports, while specialty natural binders and shelf-stable sweeteners draw from concentrated European and Chinese chemical suppliers. Single-source vulnerability concentrates in clean-label ingredient categories where alternative domestic suppliers lack technical capability. Distribution runs through modern trade chains in Mumbai and Delhi for impulse volume, with direct-to-consumer platforms capturing subscription replenishment in Bengaluru and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
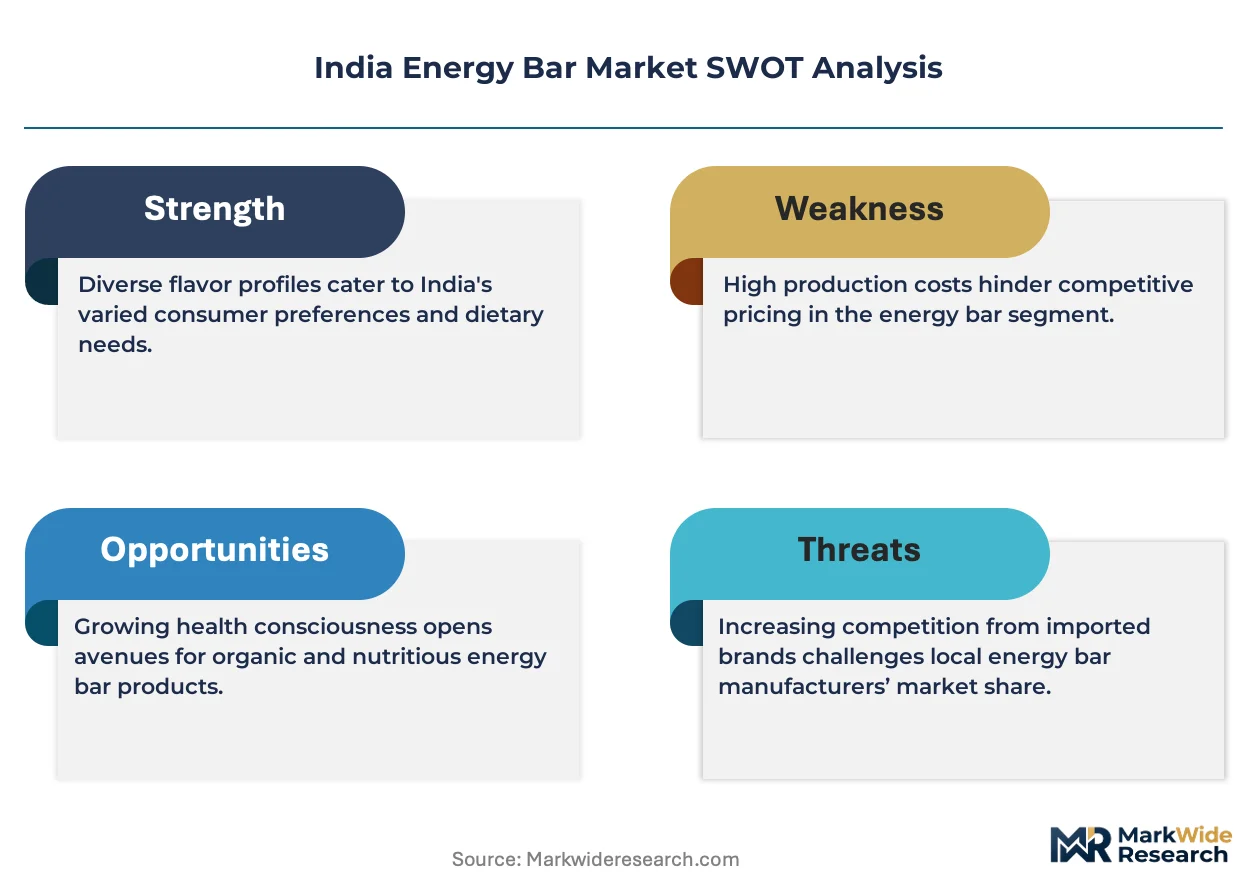
Margin expansion in the India energy bar market rests on reformulation toward domestic protein sourcing and Ayurveda-functional premium tier migration that commands 40% price premiums over imported functional alternatives.
For Market Incumbents: Deepen backward integration into Gujarat nut processing clusters and Karnataka organic ingredient sourcing to reduce import dependency exposure. Defend shelf position in modern trade through accelerated FSSAI compliance certification that delays challenger timelines. PLI scheme automation subsidies in Tamil Nadu offer capacity leverage against emerging digital-native competitors. For New Entrants and Emerging Players: Quick-commerce platforms represent the most penetrable channel for trial-driven customer acquisition without legacy retail slotting fee burdens. Target corporate wellness programs in Maharashtra and Karnataka IT campuses with subscription-based provisioning models that bypass cold-chain infrastructure requirements. Ayurveda-functional positioning against imported brands at localized price points offers immediate differentiation. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade quality protocols intersect with sub-scale manufacturing footprints unable to absorb FSSAI compliance overhead. Acquisition targets with existing BIS certification and in-house analytical laboratories command strategic premiums. The signal to watch is PLI scheme disbursement acceleration indicating state-level automation investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ayurveda-Functional Formulation Development | Ashwagandha and moringa extracts differentiate against imported brands at 40% lower price positioning. |
| Direct-to-Consumer Platform Launch | WhatsApp Commerce integration captures subscription retention among Bengaluru IT sector employees. |
| PLI-Subsidized Automation Investment | Cold-press extrusion lines exceeding 10,000 units per hour qualify for Gujarat and Tamil Nadu incentives. |
| Corporate Wellness Channel Expansion | Maharashtra and Karnataka campus contracts provide volume anchors with predictable replenishment schedules. |
| Ambient-Stable Shelf-Life Certification | BIS extended shelf-life protocols enable pharmacy and petrol station placement without refrigeration. |
Research Methodology
Bottom-up fitness center and online retail channel modeling reconciled against top-down ingredient import and manufacturing capacity tracking forms the analytical core of this study. Primary interviews with FSSAI compliance officers, gym chain procurement managers, food technologists at ICT Mumbai and CFTRI Mysuru, and quick-commerce category heads combined with secondary validation from FSSAI label disclosure databases, BIS certification registries, PLI scheme disbursement records, and modern trade Nielsen audit data. Triangulation across these sources ensures segment-level volume and value estimates reflect ground-level procurement patterns and regulatory enforcement intensity.
Historical trendline analysis of protein sourcing costs, gym membership expansion, and digital payment adoption established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, target consumer archetype, distribution channel, and packaging format dimensions with regional regulatory cluster overlays. CAGRs derived from elasticity-adjusted demand curves and capacity build-out timelines reflected PLI scheme incentive structures and FSSAI compliance friction impacts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rupee-dollar volatility, DGFT tariff adjustments, and FSSAI front-of-pack labeling rule finalization. Forecasts reflect documented assumptions regarding protein import dependency persistence and tier-2 city gym culture diffusion rates. A model refresh is warranted upon material change in FSSAI sugar disclosure thresholds or PLI scheme geographic expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Dried Fruit Snacks Market
Snacks
Low Fat Sweet Snacks Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Mushroom Based Jerky Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Meat Protein Chips Market
Snacks
North America Frozen Snacks Market
Snacks
Spain Snack Bar Market
Snacks
Savory Snacks Market
Snacks
Vegan Protein Balls Market
Snacks
Seafood Snacks Market
Snacks
Seaweed Snacks Market
Snacks
Healthy Snacks Market
Snacks
Europe Snacks Market
Snacks
Global Fruit Snacks Market