
 Fat Free Meals and Snacks Market | 2026-2036
Fat Free Meals and Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Meals and Snacks Market Analytics
Premium clean-label certification is bifurcating the competitive landscape into mass-market and health-positioned tiers. Nestlé S.A. leverages its global R&D infrastructure to sustain formulation leadership in reduced-fat dairy alternatives. Kraft Heinz Company anchors its portfolio through brand equity in household pantry staples. General Mills, Inc. differentiates via specialized grain-based snack platforms targeting wellness-oriented shoppers.
Fat free meals and snacks denote prepared food products containing less than 0.5 grams fat per labeled serving, achieved through enzymatic fat replacement, steam-injection cooking, or aqueous-phase binding systems. These products serve commercial and retail buyers seeking macronutrient-controlled options without caloric density penalties. Snack bars and ready-to-eat meals command the deepest margin pools as consumers prioritize portability and time compression. The vegetables and grains ingredient segments lead volume contribution due to fiber fortification compatibility and cost-stable sourcing. Online retailers represent the fastest-growing distribution vector, displacing conventional supermarket dominance among fitness enthusiasts and busy professionals.
The FDA governs fat-free nutrient content claims through 21 CFR 101.62, while the USDA oversees school nutrition standards that shape institutional procurement specifications. The EU's Nutri-Score labeling framework and EFSA health claim evaluations further constrain permissible marketing language and reformulation pathways. Stakeholders must monitor evolving front-of-pack warning systems and sugar-reduction mandates that will redefine permissible formulations faster than consumer taste adaptation cycles.
Market Dynamics
Enzymatic fat replacement technology is compressing formulation cycles while India's FSSAI tightens nutritional labeling rules, forcing manufacturers to rebuild recipes around aqueous-phase binding systems that maintain mouthfeel without lipid content.
Growth Catalysts
- Front-of-pack warning mandates:Brazil's ANVISA and Chile's Ministry of Health now require high-fat product warnings, redirecting consumer attention toward certified fat-free alternatives in supermarket aisles.
- Steam-injection cooking adoption:Ready-to-eat meal producers deploy this aqueous-phase technology to eliminate frying oils while preserving moisture profiles in grain-based mini meals.
- Urban India demand concentration:Metropolitan clusters in Mumbai, Bangalore, and Delhi generate disproportionate trial rates for clean-label snack bars as fitness culture penetrates middle-class households.
Market Restraints
- Input cost volatility:Specialized hydrocolloid stabilizers and enzymatic agents face price pressure from concentrated biotech supplier bases in Germany and Switzerland.
- Technical limitation:Fat-free dairy alternatives struggle to replicate lipid-soluble vitamin bioavailability and satiety signaling without reformulating protein matrices.
- Substitution threat:Low-fat products (0.5-3g fat per serving) capture price-sensitive consumers unwilling to accept texture trade-offs of fat-free formulations.
Strategic Opportunities
- Underpenetrated institutional channel:USDA school nutrition standards create procurement specifications that favor fat-free entrees in K-12 cafeterias across Texas, California, and New York districts.
- Regulatory tailwind:The EU's Nutri-Score labeling framework assigns favorable ratings to fat-free products, opening shelf-space negotiations with French and German retail buyers.
- Technology convergence:Combining enzymatic fat replacement with fiber fortification enables dual-claim positioning for metabolic health and digestive wellness in snack bar formats.
Industry Challenges
- Formulation talent scarcity:Food chemists skilled in aqueous-phase binding systems and sensory masking techniques command premium compensation, constraining mid-tier manufacturer R&D staffing.
- Certification timeline compression:EFSA health claim evaluations and evolving FSSAI documentation requirements extend product launch windows by 8-14 months for multi-market introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Meals and Snacks Market |
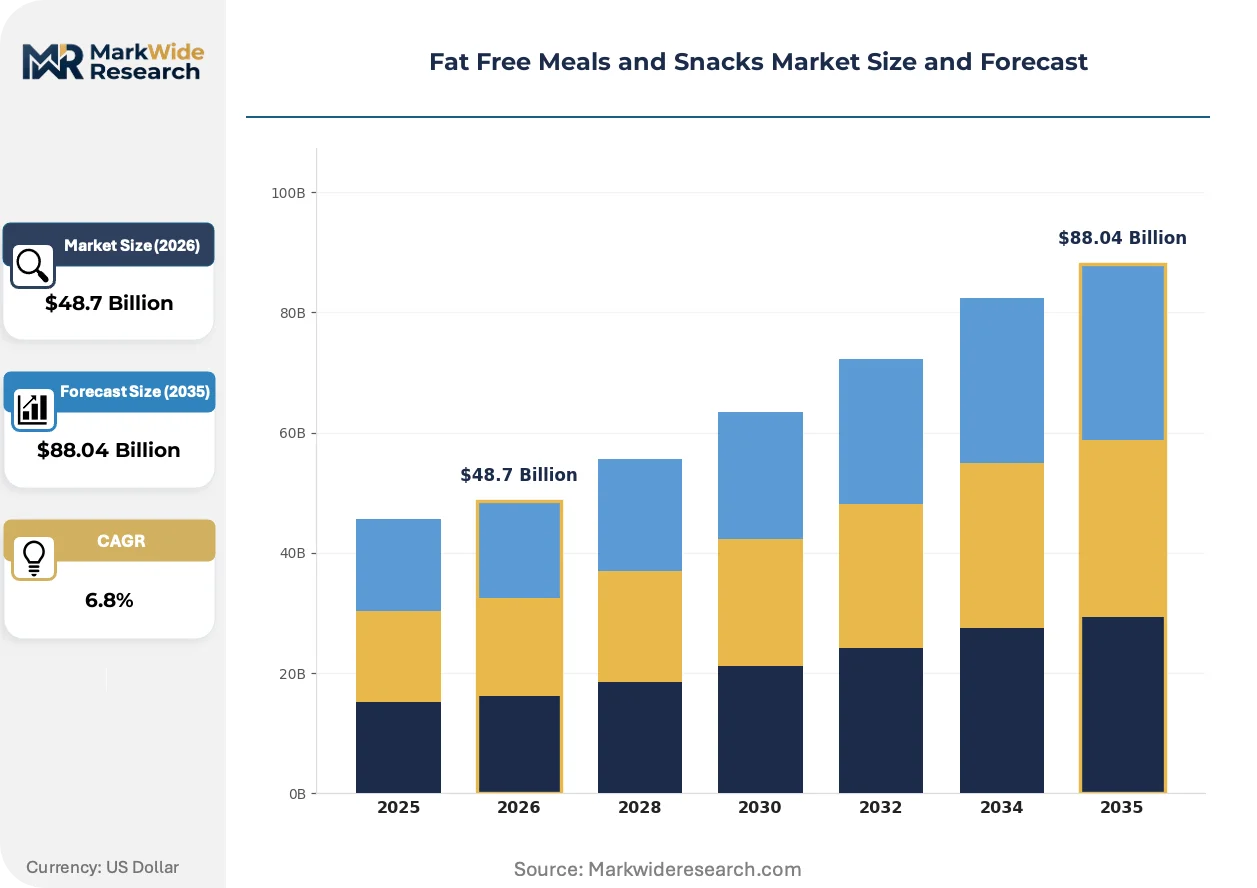
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Meals, Snack Bars, Ready-to-Eat Meals, Dips Ingredient Type: Vegetables, Grains, Fruits, Legumes Distribution Channel: Online Retailers, Supermarkets, Health Stores, Convenience Stores Consumer Segment: Fitness Enthusiasts, Health Conscious Consumers, Busy Professionals, Students |
| Companies Covered | Nestlé S.A., Kraft Heinz Company, General Mills, Inc., The Hershey Company, Hain Celestial Group, Mondelez International, Inc., Kellogg Company, Campbell Soup Company, PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Meals and Snacks Market Evolving Landscape
Clean-label certification is bifurcating competitive tiers as enzymatic technologies mature and regulatory frameworks tighten permissible marketing language. Manufacturers must now rebuild supply chains around aqueous-phase production while navigating divergent national labeling standards.
Enzymatic fat replacement systems utilizing lipase-modified starches and protein-stabilized emulsions are achieving commercial scale in ready-to-eat mini meals. Wellness-oriented shoppers in metropolitan India and coastal US cities adopt these reformulated products despite 15-20% price premiums. This adoption pattern is bifurcating the market into mass-market conventional lines and health-positioned premium tiers with segregated manufacturing footprints.
The FDA's 21 CFR 101.62 nutrient content claim enforcement and the EU's pending extension of front-of-pack warning systems are compressing permissible formulation pathways. Manufacturers face simultaneous pressure to eliminate fat while maintaining palatability thresholds that drive repeat purchase. Snack bar segments in Germany and France respond fastest, with retail buyers demanding third-party clean-label verification before shelf placement.
Direct-to-consumer subscription models are displacing conventional supermarket dominance among fitness enthusiasts and busy professionals. Online retailers capture deepening margin pools by offering personalized macronutrient-matched assortments that brick-and-mortar formats cannot replicate. This channel rotation is most visible in Bangalore, Mumbai, and Austin metropolitan clusters where time-compressed households prioritize delivery convenience over in-store browsing.
Fat Free Meals and Snacks Market Segmentation
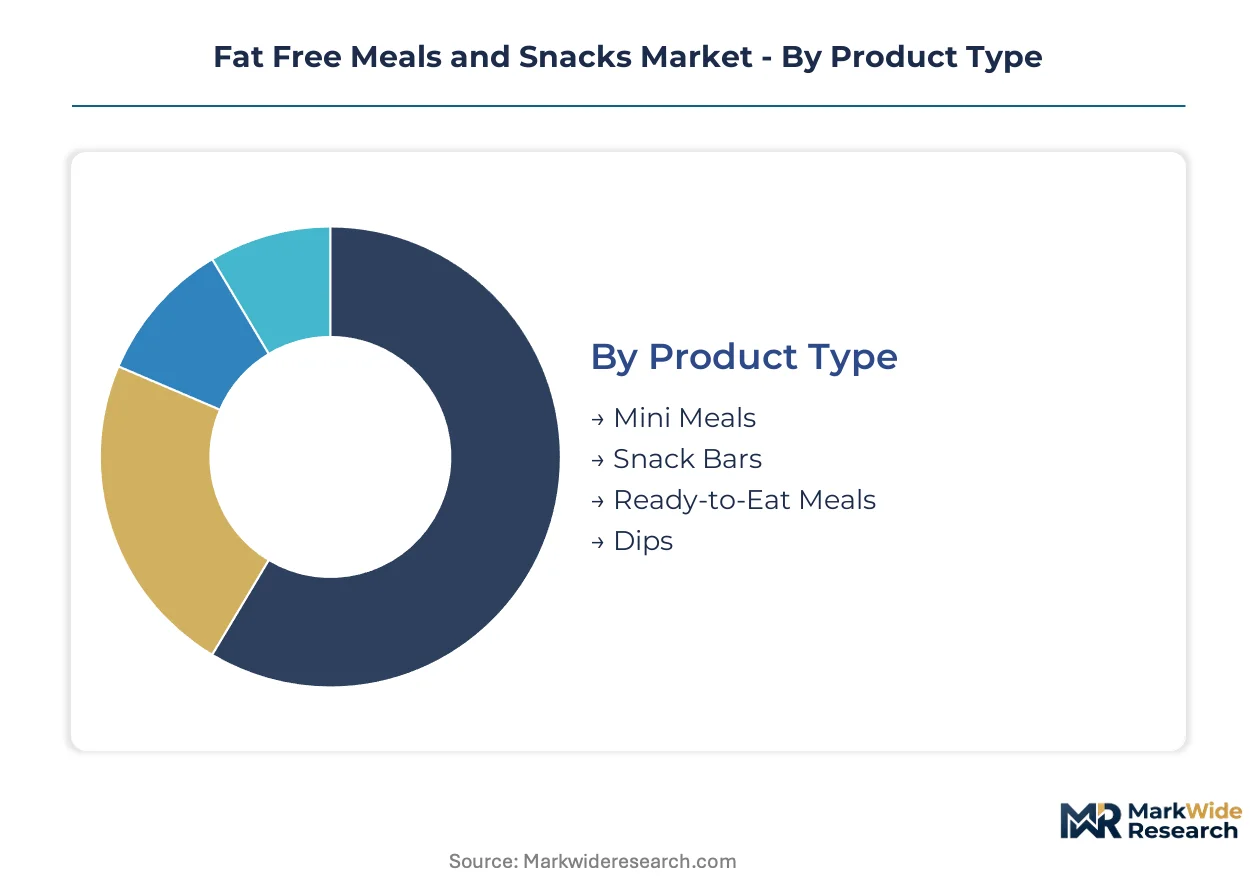
Segmentation in the Fat Free Meals and Snacks Market reveals how formulation technology and channel access determine competitive positioning. Each category exposes distinct margin structures and regulatory exposure that shape manufacturer resource allocation.
Product Type:
Domestic consumption dominates mini meals and snack bars in India and the US, while ready-to-eat meals and dips show stronger export orientation toward European retail buyers.
- Mini Meals:Portion-controlled grain and vegetable combinations utilizing steam-injection cooking to eliminate frying oils. Demand clusters in Mumbai, Bangalore, and Delhi metropolitan areas where FSSAI-compliant clean-label certification drives trial among fitness-oriented households.
- Snack Bars:Fiber-fortified compressed formats employing enzymatic fat replacement with lipase-modified starches. German and French retail buyers now mandate third-party clean-label verification before shelf placement, compressing supplier qualification timelines.
- Ready-to-Eat Meals:Aqueous-phase binding systems preserve moisture profiles in institutional and retail formats. USDA school nutrition standards in Texas and California districts favor these entrees for K-12 procurement.
- Dips:Vegetable and legume-based spreads achieving fat-free thresholds through protein-stabilized emulsions. Health Stores and online channels in Austin and coastal US cities show disproportionate adoption rates.
Mini Meals commands the established base. The steepest expansion runs through Snack Bars.
Ingredient Type:
Cost tier stratification separates fiber-compatible commodities from premium-positioned functional inputs, with sourcing geography determining margin stability.
- Vegetables:Cost-stable sourcing from domestic agricultural bases supports volume manufacturing. Fiber fortification compatibility enables dual-claim positioning for metabolic health in snack bar applications.
- Grains:Specialized grain-based platforms anchor General Mills' differentiation strategy. Steam-injection cooking adoption in ready-to-eat mini meals relies on aqueous-phase technology with these inputs.
- Fruits:Natural sugar content complicates fat-free formulation without triggering front-of-pack warning thresholds under Brazil's ANVISA and Chile's Ministry of Health mandates.
- Legumes:Protein matrix reformulation potential addresses dairy alternative limitations in lipid-soluble vitamin bioavailability. Sourcing concentrates in India and US Midwest agricultural belts.
Vegetables and Grains anchor volume contribution. Fruits face formulation constraints from tightening sugar-reduction mandates.
Distribution Channel:
Customer type differentiation separates subscription-based fitness enthusiasts from time-compressed professionals seeking immediate availability.
- Online Retailers:Personalized macronutrient-matched assortments displace conventional supermarket dominance. Bangalore, Mumbai, and Austin metropolitan clusters show deepest margin pools through direct-to-consumer subscription models.
- Supermarkets:Conventional shelf-space negotiations now require clean-label certification bifurcation into mass-market and health-positioned tiers. Nestlé S.A. and Kraft Heinz Company anchor presence through brand equity.
- Health Stores:Third-party verification requirements from EFSA health claim evaluations extend product launch windows. Premium pricing tolerance supports 15-20% markups over conventional channels.
- Convenience Stores:Time-compressed purchase occasions favor portability and immediate consumption formats. Limited refrigeration capacity constrains aqueous-phase binding system products.
Supermarkets retain volume leadership. Online Retailers gain share fastest among fitness enthusiasts and busy professionals.
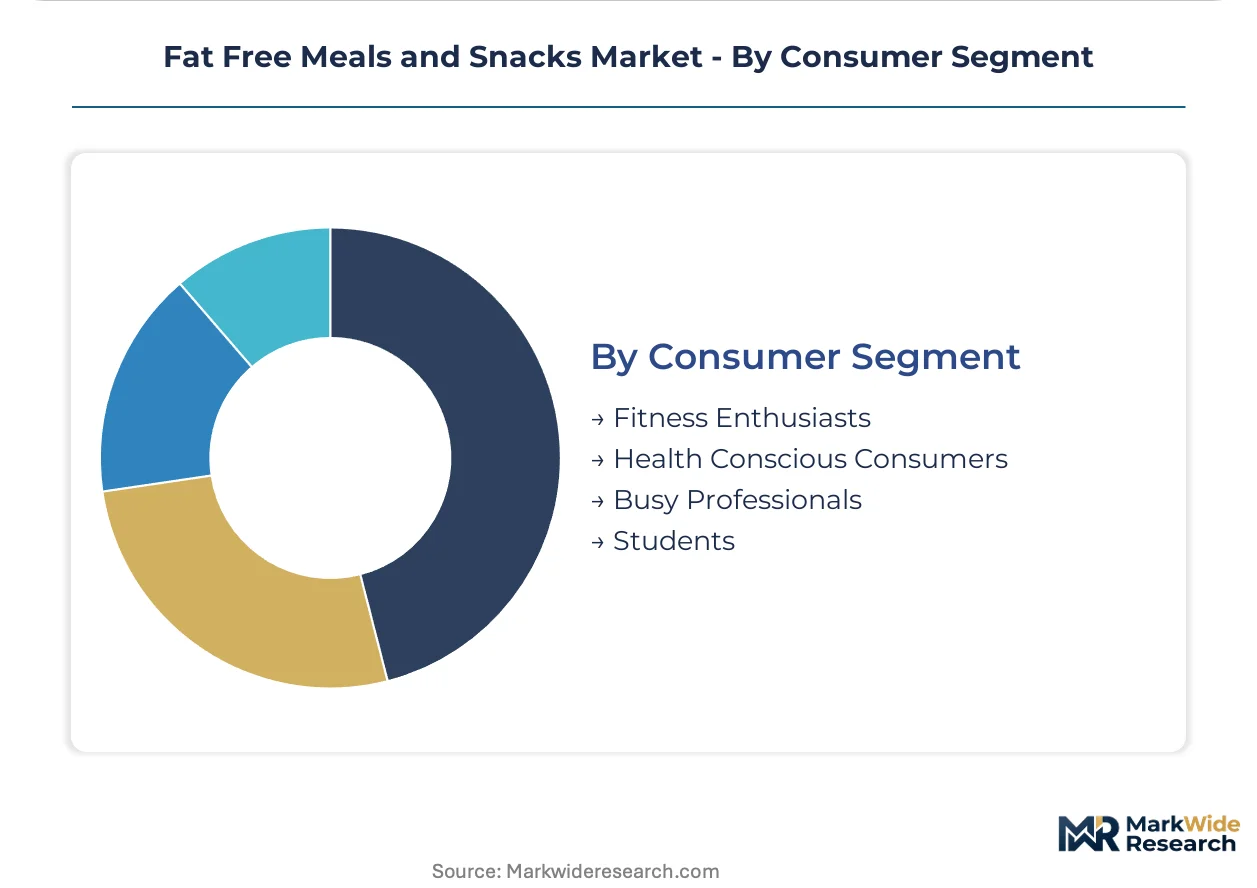
Consumer Segment:
Maturity differentiation separates established wellness adopters from emerging trial segments with distinct price sensitivity and certification requirements.
- Fitness Enthusiasts:Early adopters of enzymatic fat replacement technology in snack bars and mini meals. Direct-to-consumer subscription penetration highest in this cohort across Austin and coastal US cities.
- Health Conscious Consumers:Middle-class households in urban India drive clean-label snack bar trial. FSSAI tightening of nutritional labeling rules accelerates adoption of certified fat-free alternatives.
- Busy Professionals:Time compression prioritizes portability and delivery convenience over in-store browsing. Online Retailers capture disproportionate share through personalized assortments.
- Students:Price sensitivity limits acceptance of 15-20% premiums for enzymatic formulation products. USDA school nutrition standards create institutional procurement pathway through K-12 cafeteria specifications.
Fitness Enthusiasts anchor premium tier adoption. Busy Professionals show the steepest expansion trajectory through channel rotation toward online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in fat-free formulations tilt toward import-dependent markets in Europe and Asia, while the United States and Brazil sustain exportable surplus positions in grain-based and enzymatic-processed outputs. Regulatory divergence across FDA, EFSA, and FSSAI jurisdictions fragments standardization pathways. Metropolitan demand clusters concentrate where clean-label certification commands retail shelf-space premiums.
United States
Fitness enthusiasts in Austin and coastal metropolitan areas drive direct-to-consumer subscription adoption of enzymatic fat replacement products. The FDA enforces 21 CFR 101.62 nutrient content claims that shape permissible formulation language and marketing thresholds. Texas and California school districts anchor institutional procurement volumes under USDA nutrition standards favoring fat-free entrees.
Germany
Retail buyers in Berlin and Munich mandate third-party clean-label verification before shelf placement of snack bar formats. The EFSA health claim evaluation framework constrains permissible marketing language for reformulated products. Bavaria's food technology corridor concentrates aqueous-phase binding system R&D alongside enzymatic agent supplier bases.
India
Middle-class households in Mumbai, Bangalore, and Delhi metropolitan clusters generate disproportionate trial rates for FSSAI-compliant snack bars. The FSSAI tightening of nutritional labeling rules accelerates certified fat-free adoption among urban health-conscious consumers. Karnataka's agri-processing belt supplies cost-stable vegetable inputs for fiber-fortified mini meal production.
Brazil
ANVISA front-of-pack warning mandates for high-fat products redirect supermarket aisle attention toward certified fat-free alternatives. São Paulo's urban consumer base shows rising price tolerance for enzymatic formulation premiums in ready-to-eat categories. The country's grain surplus supports exportable volumes of steam-injection cooked mini meals.
France
The EU Nutri-Score labeling framework assigns favorable ratings that open shelf-space negotiations with Paris and Lyon retail buyers. Île-de-France concentrates demand for protein-stabilized emulsion dips through health store and online channels. EFSA documentation requirements extend product launch windows for multi-market introductions targeting French consumers.
Fat Free Meals and Snacks Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and channel access dimensions. The vendor base spans Swiss and American multinational conglomerates alongside mid-tier North American health-positioned specialists. Three archetypes dominate: scale-driven pantry staples operators, wellness-oriented clean-label specialists, and diversified snack platform holders. Competitive moves concentrate on M&A for enzymatic technology access and geographic expansion into FSSAI-regulated South Asian markets.
Within the diversified snacking tier, Mondelez International, Inc. and PepsiCo, Inc. exemplify scale-driven portfolio breadth across multiple format categories. Kellogg Company occupies a position among North American breakfast and snack bar specialists with heritage brand equity. These three entities anchor competitive dynamics through divergent strategic postures toward clean-label certification bifurcation.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Kraft Heinz Company |
| General Mills, Inc. |
| The Hershey Company |
| Hain Celestial Group |
| Mondelez International, Inc. |
| Kellogg Company |
| Campbell Soup Company |
| PepsiCo, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for specialized hydrocolloid stabilizers lock in supply access and price visibility for enzymatic fat replacement manufacturers, insulating against biotech supplier concentration in Germany and Switzerland while compressing margin flexibility for mid-tier formulators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in fat-free formulations. Certification grade under FSSAI and FDA 21 CFR 101.62 tiers plus volume scale separate price bands. Cost compression in standard-tier snack bars intensifies because low-fat substitutes capture price-sensitive consumers. Students show highest price sensitivity; fitness enthusiasts tolerate 15-20% enzymatic formulation premiums.
Supply Chain Analysis
Specialized enzymatic agent production concentrates in Bavaria's food technology corridor and Swiss biotech clusters, creating single-source vulnerability for lipase-modified starch inputs. Aqueous-phase binding systems draw from domestic vegetable bases in Karnataka and the US Midwest alongside imported protein-stabilized emulsions. Tariff exposure on German hydrocolloid imports threatens margin stability. Distribution runs through direct-to-consumer subscription platforms displacing conventional supermarket dominance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as direct-to-consumer subscription models and personalized macronutrient-matching create interoperability between formulation technology and last-mile delivery infrastructure.
For Market Incumbents: Compound brand equity in household pantry staples through backward integration into enzymatic agent production, defending against private-label clean-label specialists. Prioritize FSSAI certification investment to secure shelf-space negotiations in Mumbai and Delhi metropolitan clusters where regulatory tightening accelerates trial. For New Entrants and Emerging Players: Differentiate on aqueous-phase binding system specialization targeting USDA school nutrition procurement in Texas and California K-12 districts. White-space concentrates in institutional channel fat-free entrees and fiber-fortified snack bars for German retail buyers demanding third-party verification. Pursue direct-to-consumer launch with fitness enthusiast subscription models. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier clean-label specialists with captive enzymatic technology and FSSAI-compliant manufacturing footprints. Long-term viability over the next decade hinges on regulatory navigation capability across FDA, EFSA, and FSSAI jurisdictions. Watch front-of-pack warning system extensions as inflection indicator for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Technology Acquisition | Lipase-modified starch capabilities from Bavarian R&D clusters accelerate formulation cycle compression. |
| Direct-to-Consumer Launch | Subscription models in Austin and Bangalore metropolitan clusters capture deepening margin pools. |
| FSSAI Certification Investment | Clean-label verification unlocks shelf-space negotiations with Mumbai and Delhi retail buyers. |
| Backward Integration | In-house production of hydrocolloid stabilizers mitigates German-Swiss supplier concentration risk. |
| Institutional Channel Expansion | USDA school nutrition compliance opens K-12 procurement pathways in Texas and California districts. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with food formulation chemists, FSSAI regulatory affairs officers, retail category buyers, and direct-to-consumer subscription platform operators; and secondary validation through FDA 21 CFR filings, EFSA health claim evaluation databases, FSSAI nutritional labeling directives, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation anchored projections.
Across the analysis window, forecasts segment by product type, ingredient category, distribution channel, and consumer archetype, with CAGRs derived from enrollment curve analysis and regulatory adoption pattern correlation. Enzymatic technology penetration rates and clean-label certification velocity served as primary demand-side inputs.
Material uncertainties — front-of-pack warning system extensions, hydrocolloid supply disruptions, and consumer taste adaptation cycles — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EFSA documentation requirements and FSSAI enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Seaweed Snacks Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
North America Baked Savory Snacks Market
Snacks
Germany Energy Bar Market
Snacks
Organic Snacks Market
Snacks
Low Calorie Snack Foods Market
Snacks
RTE Popcorn Market
Snacks
North America Baked Chips Market
Snacks
Low Calorie Dip Market
Snacks
Premium Snacks Market
Snacks
Low Fat Crackers Market
Snacks
Nutritional Bar Market
Snacks
Gluten Free Snacks Market
Snacks
Europe Snack Bar Market