
 Asia Pacific Frozen Snacks Market | 2026-2036
Asia Pacific Frozen Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Frozen Snacks Market Outlook
Consolidation among quick-service restaurant chains and cloud kitchen operators is repositioning procurement power toward large-format buyers who negotiate directly with frozen snack suppliers. McCain Foods Limited leverages its potato processing scale to anchor supply contracts with these consolidated foodservice channels across Australia and India. Nestle SA sustains brand recognition in the retail freezer aisle through differentiated product positioning aimed at family consumer segments. Ajinomoto Co Inc competes on umami-forward flavor profiles that resonate with East Asian palates and specialized regional tastes.
Frozen snacks comprise pre-cooked or partially cooked food items preserved at sub-zero temperatures, typically formulated with moisture content below seventy percent and flash-frozen within minutes of preparation to maintain cellular structure and sensory quality; their primary commercial purpose is to deliver consistent, ready-to-heat consumption experiences across retail and foodservice channels. Potato snacks dominate volume throughput due to established processing infrastructure and raw material availability across the region's agricultural belts. Online retailers represent the fastest-growing distribution channel as last-mile cold chain capabilities expand and working professionals prioritize doorstep delivery over supermarket visits.
FSSAI in India enforces frozen food labeling and cold chain compliance that elevates entry barriers for unorganized producers while standardizing quality expectations across retail channels. Australia's FSANZ and Japan's Ministry of Health, Labour and Welfare impose additive limits and nutritional disclosure rules that shape reformulation priorities for exporters targeting these jurisdictions. Stakeholders must monitor evolving packaging waste regulations and energy labeling requirements as sustainability criteria increasingly filter into retailer procurement standards and consumer purchase decisions across the region.
Market Dynamics
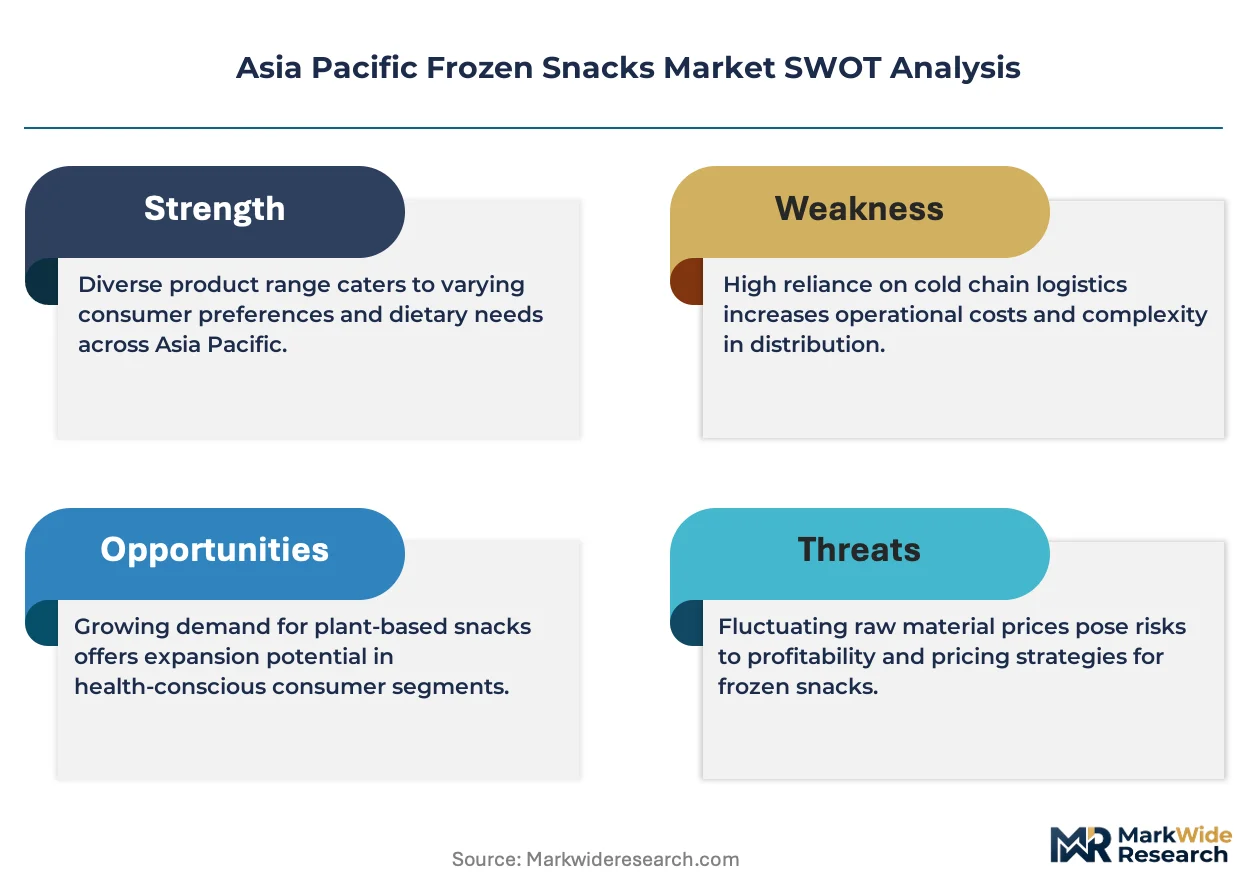
Cold chain infrastructure investments across India and Southeast Asia are compressing distribution timelines while FSSAI enforcement tightens product standards, creating a structural squeeze where only scaled processors can meet both speed and compliance demands simultaneously.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive scheme for food processing subsidizes capital equipment for frozen snack manufacturers, accelerating domestic capacity expansion.
- Cloud kitchen procurement consolidation:Aggregated demand from consolidated foodservice operators in Bangalore, Jakarta, and Sydney concentrates volume toward large-format frozen snack suppliers.
- Flash-freezing technology adoption:IQF tunnel systems now preserve cellular structure in battered vegetable snacks, extending shelf-stable sensory quality from production to point-of-sale.
Market Restraints
- Palm oil price volatility:Input cost swings for frying mediums compress margin buffers for mid-tier processors lacking forward-contract coverage.
- Cold chain fragmentation:Last-mile refrigeration gaps in tier-2 Indian cities and Indonesian archipelago logistics create spoilage risk that deters distribution expansion.
- Fresh snack substitution:Local wet markets and quick-commerce fresh food delivery in Vietnamese and Thai urban centers compete directly on perceived quality and immediacy.
Strategic Opportunities
- Philippine provincial penetration:Freezer penetration in Cebu and Davao corridors remains below metropolitan Manila levels, creating whitespace for regional distribution partnerships.
- FSANZ clean-label alignment:Australian additive disclosure rules reward reformulated product lines that can pivot toward premium positioning across ASEAN export channels.
- Direct-to-institution channels:Hospital and corporate cafeteria procurement bypasses traditional retail markup structures, enabling volume contracts with specialized frozen snack portfolios.
Industry Challenges
- Cold chain technician scarcity:Refrigeration maintenance expertise lags equipment deployment rates across India's expanding frozen food logistics networks.
- FSSAI certification timelines:Product approval queues for novel ingredient formulations extend go-to-market windows beyond competitive response cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Frozen Snacks Market |
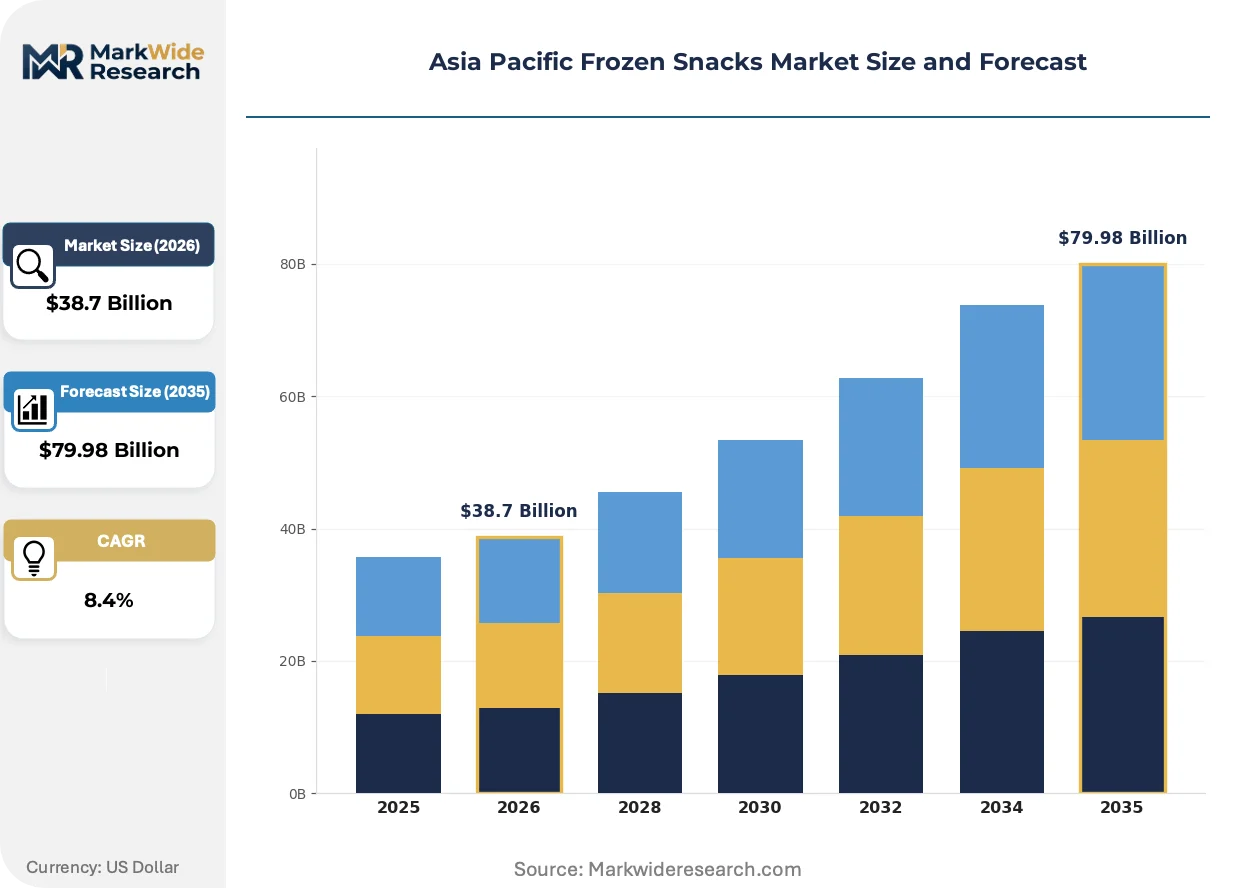
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato Snacks, Meat Snacks, Bakery Products, Vegetables Consumer Segment: Kids, Young Adults, Families, Working Professionals Packaging Type: Bag, Box, Pouch, Tray Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores |
| Companies Covered | McCain Foods Limited, Nestle SA, Ajinomoto Co Inc, Conagra Brands, Tyson Foods, General Mills, ITC Limited, Prasuma, Simplot Australia Pty Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Frozen Snacks Market Strategic Shifts
Reformulation priorities and channel restructuring are compressing traditional competitive moats, with technology adoption and regulatory alignment now determining margin sustainability more than brand heritage or scale alone.
Air fryer-compatible batter systems are absorbing R&D investment across Australian and Japanese processing facilities, with starch-modified coatings that crisp at lower oil temperatures. Health-conscious households in Sydney and Tokyo are adopting these products at rates that outpace conventional fried snack segments. The technology is absorbing shelf space from traditional oil-fried alternatives as retailers recalibrate freezer aisle layouts toward perceived wellness positioning.
FSSAI's 2022 frozen food labeling amendments mandate nutritional disclosure panels and cold chain integrity declarations that elevate documentation burdens. Indian importers and domestic manufacturers must now maintain batch-traceable temperature logs from production through retail handoff. Exporters targeting India from Thailand and Vietnam are restructuring quality assurance departments to meet these documentation thresholds, with smaller regional players facing compliance cost disadvantages.
Quick-commerce platforms are disintermediating traditional supermarket freezer sections in Mumbai, Bangalore, and Jakarta metropolitan zones. Working professionals in dual-income households now prioritize 15-minute delivery windows over in-store browsing, compressing brand loyalty cycles. This pattern concentrates most visibly in Indian tier-1 cities where Swiggy Instamart and Blinkit dark stores maintain dedicated frozen food sections with rapid-turn inventory models.
Asia Pacific Frozen Snacks Market Segmentation
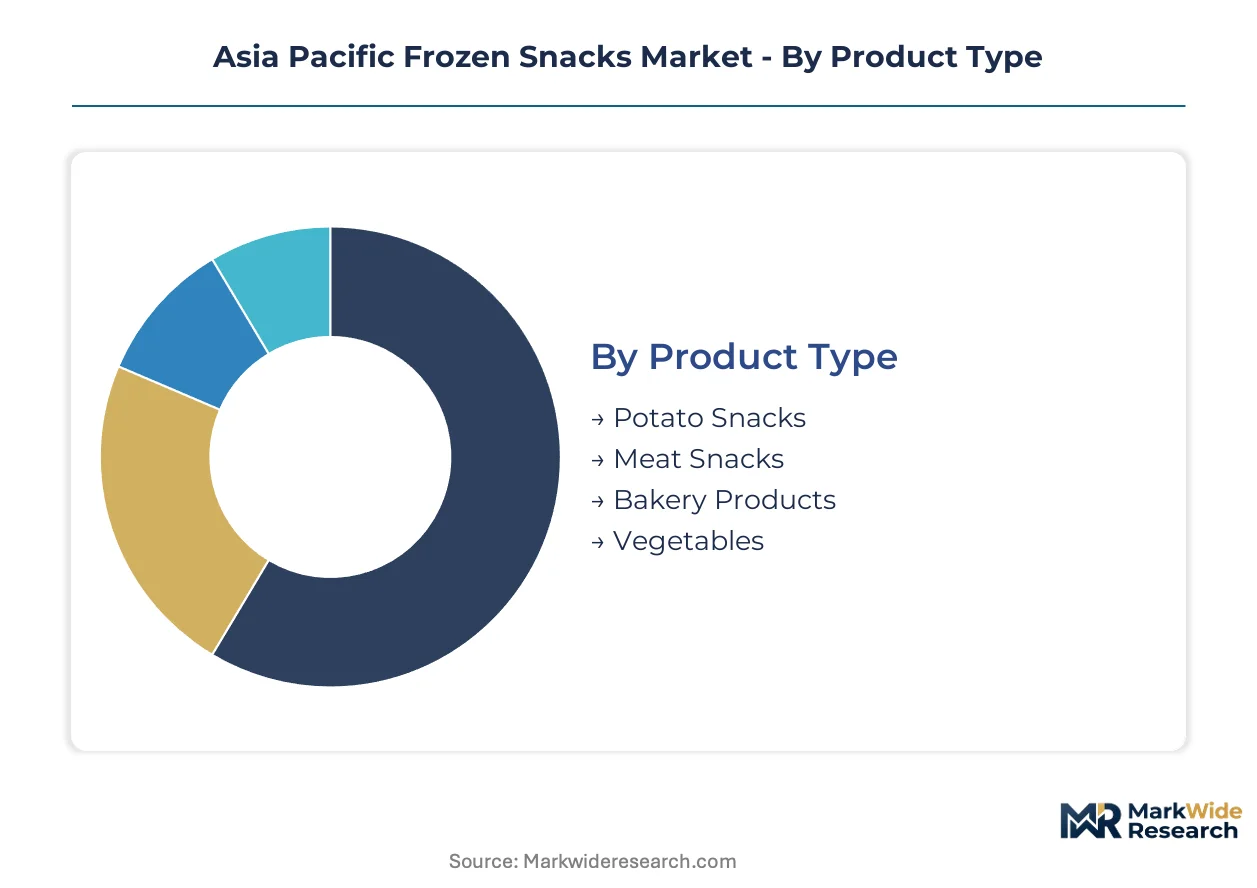
Segmentation in the Asia Pacific frozen snacks market reveals how capital deployment, regulatory exposure, and channel infrastructure vary sharply across product formats and buyer categories. Processors allocate equipment investments differently depending on which segments they target, with cold chain intensity and FSSAI compliance costs creating divergent margin structures.
Product Type:
Potato snacks demand the heaviest upfront capital for processing infrastructure, while meat snacks require specialized freezing and pathogen control systems that extend payback timelines.
- Potato Snacks:Formulated from starch-modified potato varieties with moisture content engineered below 70 percent before flash-freezing. Demand concentrates in India's metropolitan corridors and Australia's capital cities, where McCain Foods and similar processors have anchored supply contracts with consolidated foodservice channels.
- Meat Snacks:Partially cooked protein items preserved through IQF tunnel systems with strict cold chain integrity from slaughter to retail. Working professionals across urban India and Southeast Asia are expanding purchases, though FSSAI labeling mandates and pathogen testing requirements elevate compliance burdens for smaller processors.
- Bakery Products:Pre-cooked dough-based items requiring controlled fermentation arrest through rapid freezing, with established processing infrastructure concentrated in Japan and South Korea.
- Vegetables:Battered and breaded vegetable formulations gaining traction through air fryer-compatible coating technologies developed in Australian and Japanese facilities.
Most installed capacity flows through Potato Snacks. Expansion is steepest in Meat Snacks.
Consumer Segment:
Volume throughput and price sensitivity diverge markedly across life-stage groupings, with dual-income households driving premiumization while family segments sustain baseline throughput.
- Working Professionals:Time-constrained urban consumers prioritizing 15-minute delivery windows through quick-commerce platforms in Mumbai, Bangalore, and Jakarta. Swiggy Instamart and Blinkit dark stores maintain dedicated frozen food sections with rapid-turn inventory models serving this segment.
- Families:Multi-person households purchasing larger-format packaging through supermarket freezer aisles, with brand loyalty cycles compressing as online retailers disintermediate traditional retail.
- Kids:Smaller-portion snack formats with simplified ingredient panels responding to parental scrutiny of additive content under FSSAI disclosure rules.
- Young Adults:Experimentation-oriented buyers responding to umami-forward flavor profiles from Ajinomoto and similar processors targeting East Asian palates.
Working Professionals command the highest per-capita spend. Kids-oriented lines face the steepest reformulation cost pressure.
Packaging Type:
Cold chain integrity requirements and retail display constraints shape material selection, with sustainability regulations increasingly filtering into procurement standards.
- Bag:Flexible polyethylene formats dominating high-velocity potato snack SKUs, with lightweight construction reducing transport costs across fragmented Indonesian archipelago logistics.
- Tray:Rigid formats with modified atmosphere sealing for premium meat snacks, absorbing shelf space in Australian supermarkets recalibrating freezer aisle layouts toward perceived wellness positioning.
- Box:Corrugated outer shells with inner moisture barriers for multi-unit bakery product assortments.
- Pouch:Stand-up flexible formats with reseal features for single-serve vegetable snack lines targeting convenience store channels.
Bag formats carry the lowest unit packaging cost. Tray formats are climbing the fastest as premium positioning expands.
Distribution Channel:
Channel selection determines cold chain investment recovery rates, with last-mile capabilities now the critical bottleneck for geographic expansion.
- Online Retailers:Quick-commerce platforms disintermediating traditional supermarket freezer sections through dark store networks with dedicated frozen food sections. Last-mile cold chain capabilities are expanding fastest in Indian tier-1 cities, though tier-2 refrigeration gaps create spoilage risk.
- Supermarkets:Traditional retail freezer penetration remains densest in Australia's capital cities and India's metropolitan corridors, where dual-income household density aligns with retail infrastructure.
- Convenience Stores:High-frequency, small-format purchases in Japanese and South Korean urban centers with mature cold chain infrastructure.
- Specialty Stores:Curated import selections and premium positioning in Manila and Bangkok serving expatriate and affluent local consumers.
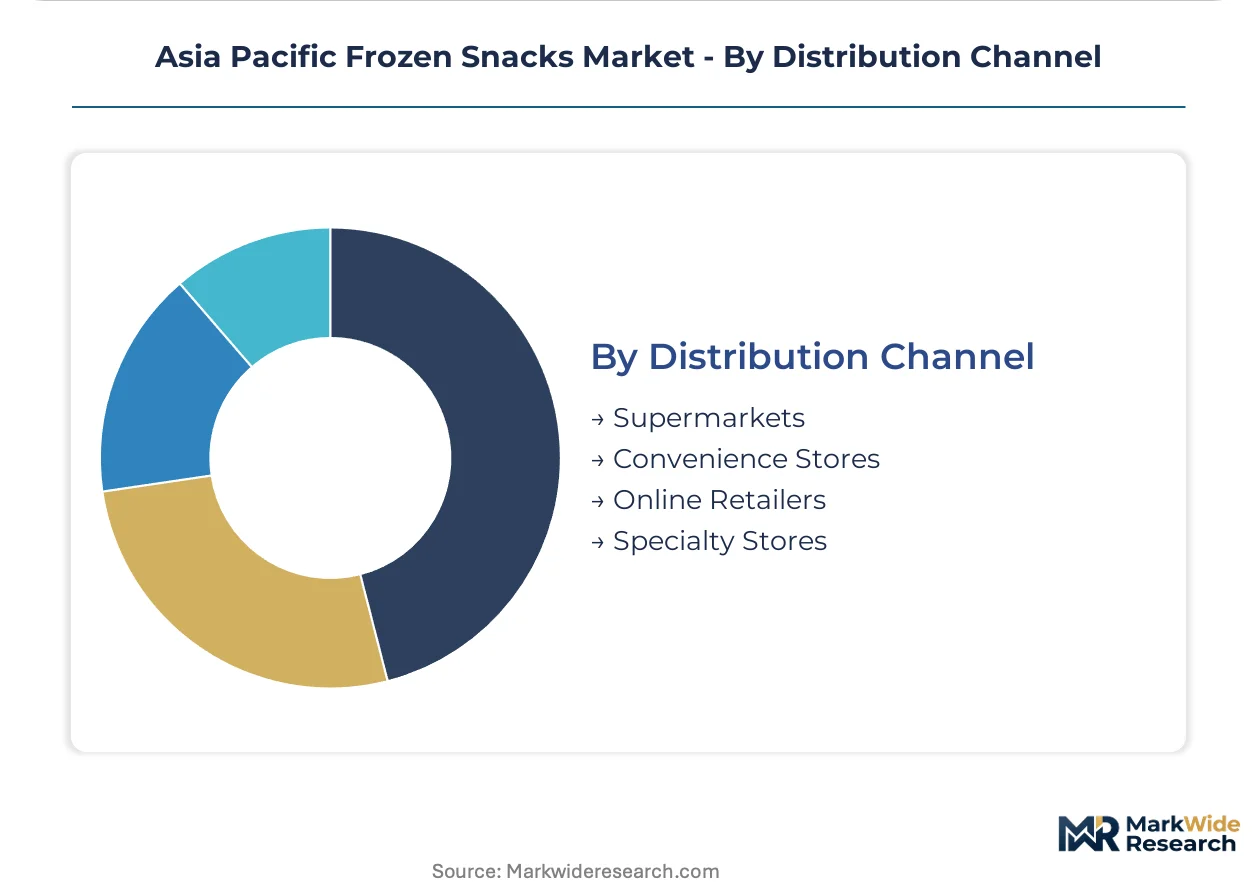
Supermarkets retain the largest frozen snack volume base. Online retailers are gaining share fastest as working professionals prioritize doorstep delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working professionals in dual-income households across the region's metropolitan corridors anchor frozen snack demand, with cold chain infrastructure investments and regulatory enforcement shaping geographic expansion patterns.
India
FSSAI labeling mandates and PLI scheme subsidies are accelerating domestic processing capacity in Maharashtra and Karnataka. Mumbai and Bangalore metropolitan zones concentrate quick-commerce dark store networks serving time-constrained urban consumers through 15-minute delivery windows.
Australia
FSANZ additive disclosure rules and clean-label preferences in Sydney and Melbourne are driving reformulation toward air fryer-compatible coatings. Retail freezer penetration remains densest in capital cities where wellness-positioned products absorb expanding shelf space.
Japan
Ministry of Health, Labour and Welfare nutritional regulations and aging demographics sustain demand for portion-controlled formats in Tokyo and Osaka corridors. Established processing infrastructure in Kansai and Kanto regions supports premium positioning for umami-forward flavor profiles.
Indonesia
Cold chain fragmentation across the archipelago creates spoilage risk that deters distribution beyond Jakarta and Surabaya metropolitan zones. Palm oil price volatility compresses margin buffers for mid-tier processors lacking forward-contract coverage.
Philippines
Freezer penetration in Cebu and Davao corridors remains below metropolitan Manila levels, creating whitespace for regional distribution partnerships. Provincial expansion depends on last-mile refrigeration investments lagging equipment deployment rates.
Asia Pacific Frozen Snacks Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia Pacific frozen snacks landscape, creating a tiered structure where scale advantages in procurement and compliance separate market positions. The vendor base clusters around three strategic archetypes: multinational food conglomerates with diversified frozen portfolios, regional potato and protein processors with captive agricultural supply, and specialized Asian flavor houses leveraging umami expertise. Dominant competitive moves include backward integration into raw material sourcing and strategic partnerships with consolidated foodservice channels.
Within the multinational conglomerate tier, Nestle SA and McCain Foods Limited occupy positions exemplifying divergent strategic approaches to regional penetration. Nestle SA anchors brand recognition in retail freezer aisles through family-oriented positioning. McCain Foods Limited represents scale-driven supply contract concentration with consolidated quick-service and cloud kitchen operators. Ajinomoto Co Inc sits within the specialized flavor house archetype, competing on regional taste expertise rather than commodity scale.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Nestle SA |
| Ajinomoto Co Inc |
| Conagra Brands |
| Tyson Foods |
| General Mills |
| ITC Limited |
| Prasuma |
| Simplot Australia Pty Limited |
| Others |
Value Chain & Pricing Dynamics
Quick-commerce procurement consolidation in Indian and Australian metropolitan corridors is forcing suppliers to absorb last-mile cold chain costs while maintaining FSSAI and FSANZ compliance documentation, compressing margin structures for processors lacking scale economies in freezer-aisle negotiations.
Pricing Analysis
Capacity additions in Maharashtra and Karnataka under India's PLI scheme are reshaping price floors for potato snack processors, with three-tier pricing structure across premium, standard, and economy levels separating air fryer-compatible formulations from conventional oil-fried alternatives. Price differentiation hinges on clean-label certification grade and volume scale commitments to consolidated cloud kitchen operators. Cost compression in mid-tier segments is intensifying because palm oil input volatility lacks forward-contract hedging. Family segments through supermarket channels show highest price sensitivity, while working professionals via quick-commerce platforms accept premium positioning for delivery convenience.
Supply Chain Analysis
Regional distribution centers in Mumbai, Bangalore, and Sydney operate hub-and-spoke patterns feeding quick-commerce dark stores and consolidated foodservice channels. Supply concentrates in India, Australia, and Thailand, with raw material dependencies on starch-modified potato varieties, palm oil frying mediums, and specialized IQF equipment components. Single-source vulnerability in Indonesian archipelago logistics creates spoilage risk from last-mile refrigeration gaps. Distribution runs through direct-to-institution contracts with hospital and corporate cafeteria procurement, bypassing traditional retail markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on air fryer-compatible coating technology premiums offsetting cold chain compliance cost absorption, with PLI scheme capital subsidies enabling domestic capacity scale that captures procurement consolidation benefits.
For Market Incumbents: Anchor supply contracts with consolidated cloud kitchen operators in Bangalore and Jakarta through dedicated frozen food section partnerships, while backward integration into starch-modified potato sourcing defends against palm oil price volatility. Invest in batch-traceable temperature logging systems to preempt FSSAI certification timeline extensions that delay competitive response cycles.
For New Entrants and Emerging Players: Begin with Cebu and Davao provincial corridors in the Philippines where freezer penetration lags metropolitan Manila, creating whitespace for regional distribution partnerships with local cold chain operators. Target direct-to-institution channels in Indian tier-2 cities where hospital and corporate cafeteria procurement bypasses retail markup concentration.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized Asian flavor houses possessing umami formulation expertise and clean-label reformulation capabilities aligned with FSANZ disclosure rules. Long-term viability favors processors with captive agricultural supply and IQF tunnel system ownership. Watch for quick-commerce platform vertical integration signals as inflection indicators for channel control shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Air Fryer-Compatible Coating Development | R&D investment in starch-modified formulations captures wellness-positioned shelf space in Sydney and Tokyo freezer aisles. |
| Backward Integration into Potato Sourcing | Captive supply of starch-modified varieties insulates margin buffers from agricultural commodity volatility. |
| Quick-Commerce Dark Store Partnership | Dedicated frozen food sections in Swiggy Instamart and Blinkit networks secure 15-minute delivery channel access. |
| FSSAI Clean-Label Certification Investment | Batch-traceable temperature logging systems preempt product approval queue delays for novel ingredient formulations. |
| Provincial Distribution Partnership | Regional cold chain alliances in Cebu and Davao unlock whitespace penetration below metropolitan Manila freezer density. |
Study Parameters
Direct dialogue with frozen snack brand managers, quick-commerce category buyers, cold chain logistics operators, and FSSAI regulatory affairs specialists anchored primary intelligence, cross-referenced against customs trade records, Nielsen retail audit data, PLI scheme disclosure filings, and food processing equipment import manifests. Bottom-up capacity installation tracking and top-down consumption pattern modeling enabled triangulation across data sources.
Segment-level projections across product type, consumer segment, packaging format, and distribution channel dimensions were generated through demand elasticity modeling and supply capacity buildout tracking across the projection horizon. CAGRs were derived from installed base expansion rates and penetration trajectory analysis, with specific inputs including cloud kitchen procurement consolidation timelines and cold chain infrastructure investment flows.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to FSSAI labeling requirements, abrupt palm oil commodity shocks beyond historical volatility bands, and quick-commerce platform bankruptcy events. Stakeholders should weight assumptions against their own operating context and regional cold chain partnership stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Energy Bar Market
Snacks
Popcorn Market
Snacks
Super Low Calorie Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Low Fat Granola Market
Snacks
Saudi Arabia Snacks Industry Market
Snacks
Europe Popcorn Market
Snacks
Baked Chips Market
Snacks
Snack Subscription Market
Snacks
South Africa Savory Snacks Market
Snacks
India Energy Bar Market
Snacks
South Korea Snack Bar Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
North America Pretzel Market
Snacks
Dried Fruit Snacks Market
Snacks
Gluten Free Snacks Market