
 Savoury Biscuits Market | 2026-2036
Savoury Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Savoury Biscuits Market Analysis
Market Context with Strategic Players
Asset-light contract manufacturing is fragmenting capital requirements for new entrants in savoury biscuits. Burton's Foods leverages its British heritage and specialty cracker expertise to sustain premium positioning in European grocery channels. Mondelez International anchors global scale through multiserve pack distribution, while Parle dominates value-tier penetration across South Asian markets.
Technical Definition and Structural Segments
Savoury biscuits comprise baked cereal-based products with reduced sugar content, typically containing wheat flour, vegetable oils, and seasoning blends at moisture levels below five percent, designed for shelf-stable snacking and meal accompaniment. Crackers and pita chips capture the fastest-growing flavour-profile slots, with spicy and cheese variants driving repeat purchases in flexible bag formats. Cheddar biscuits occupy mature margin pools in rigid container packaging, while breadsticks compete for food-service placement through bulk pack economics.
Regulatory Frame and Forward-Looking Close
FSSAI in India enforces maximum sodium thresholds for processed baked goods, compelling reformulation of herb and garlic flavour lines. EFSA's evolving nutrient profiling criteria and FDA serving-size disclosure rules reshape label architecture and portion architecture across export-bound production. Stakeholders must monitor divergence between EU Green Deal packaging mandates and India's PLI scheme incentives for domestic manufacturing scale.
Market Dynamics
Clean-label reformulation mandates from EFSA and FSSAI are compressing sodium thresholds across savoury biscuit portfolios, forcing manufacturers to rebuild seasoning architectures without sacrificing shelf stability or taste profiles.
Growth Catalysts
- EFSA Nutrient Profiling:Evolving criteria for front-of-pack labelling in Europe push manufacturers toward transparent ingredient decks that resonate with health-conscious urban consumers.
- Snacking Among Working Professionals:Compressed lunch breaks and hybrid work patterns in India, the UK, and the US sustain demand for portable, portion-controlled savoury formats.
- Contract Manufacturing Scale:Asset-light production models lower capital barriers for regional entrants seeking to test localized flavour variants without building owned facilities.
Market Restraints
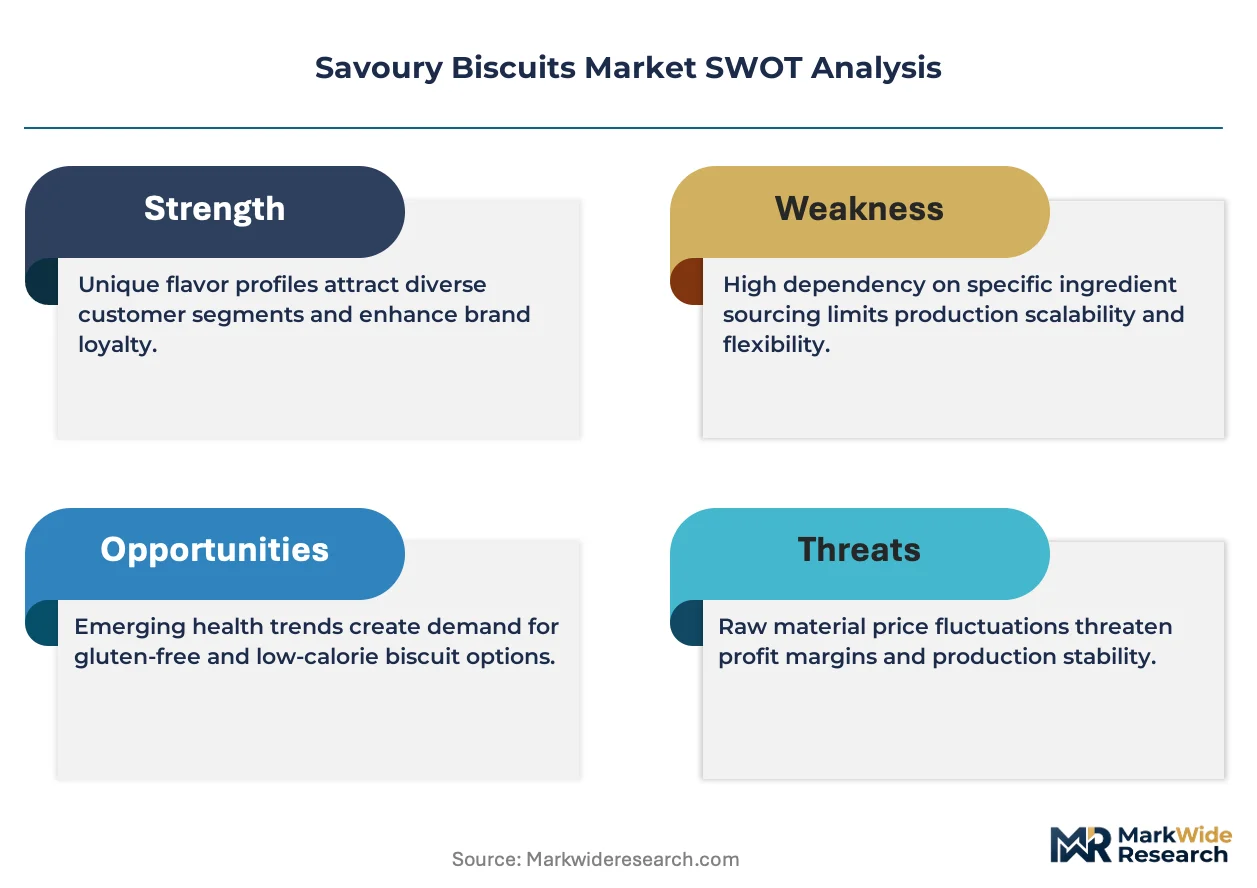
- Wheat Price Volatility:Input cost swings in Black Sea grain markets compress margins for standard-tier cracker lines with limited pricing power.
- Sodium Threshold Compliance:FSSAI's phased reduction mandates force costly reformulation cycles that disproportionately burden small and mid-sized Indian producers.
- Alternative Snack Substitution:Roasted chickpeas, seaweed crisps, and air-popped grains capture shelf space in premium urban retail, diverting trial budgets from traditional savoury biscuits.
Strategic Opportunities
- India's PLI Scheme Incentives:Production-linked incentives for food processing scale reward domestic manufacturing investments with tax offsets and capital subsidies.
- E-commerce Direct-to-Consumer Channels:Platform algorithms favour niche flavour variants, enabling challenger brands to build awareness without traditional slotting fees.
- EU Green Deal Packaging Mandates:Biodegradable film requirements create first-mover advantage for suppliers with certified compostable flexible bag capabilities.
Industry Challenges
- Reformulation Talent Scarcity:Food scientists capable of balancing sodium reduction with microbial stability and sensory appeal command premium compensation in competitive labour markets.
- Legacy Equipment Retrofit Costs:Existing oven and seasoning lines require capital-intensive modifications to handle alternative flours and reduced-oil dough systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savoury Biscuits Market |
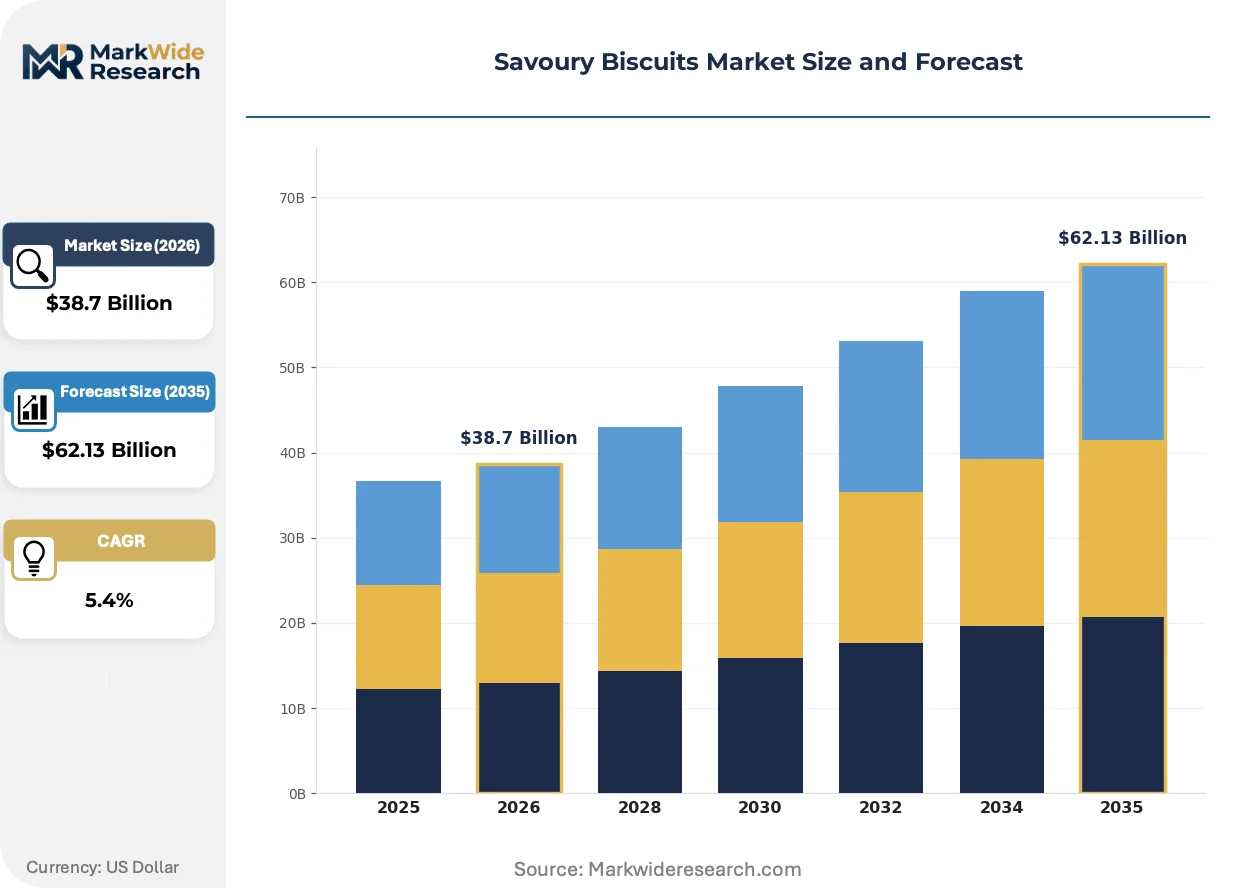
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Crackers, Pita Chips, Breadsticks Flavor Profile: Spicy, Herb, Cheese, Garlic End User: Retailers, Food Service, Wholesale, Exporters Packaging Type: Flexible Bags, Rigid Containers, Multiserve Packs, Bulk Packs |
| Companies Covered | Burton's Foods, Walkers Shortbread, Parle, ITC Limited, Mondelez International, Britannia, Lotus Bakeries, Kellogg, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savoury Biscuits Market Emerging Trajectories
Reformulation science and packaging material innovation are converging to reshape how savoury biscuits deliver taste, convenience, and environmental accountability without trade-offs that alienate core buyers.
Extrusion technology is hybridizing with traditional lamination processes to create layered crackers with irregular air pockets that amplify texture perception while reducing fat content. European and North American manufacturers pilot these hybrid lines to meet clean-label expectations without sacrificing the snap and mouthfeel that define cracker categories. The capital efficiency of shared extrusion-lamination equipment is compressing the cost gap between artisan-positioned and mass-market texture profiles.
EFSA's evolving nutrient profiling criteria are forcing label architecture redesigns that prioritize front-of-pack colour coding over back-panel ingredient lists. Manufacturers exporting to EU member states must restructure sodium and saturated fat levels to avoid red-category ratings that trigger retail delisting in health-focused chains. The UK and Germany show the steepest compliance curves, with cheddar and herb-garlic variants undergoing the most aggressive reformulation cycles.
Urban Indian consumers are fragmenting their savoury snack purchases across multiple channels rather than consolidating in traditional kirana stores. Quick-commerce platforms capture impulse trials for novel flavours, while modern trade maintains family-pack volumes, splitting brand investment across incompatible service models. Metro clusters in Mumbai, Bangalore, and Delhi exhibit the sharpest channel divergence, forcing portfolio segmentation by pack size and price point.
Savoury Biscuits Market Segmentation
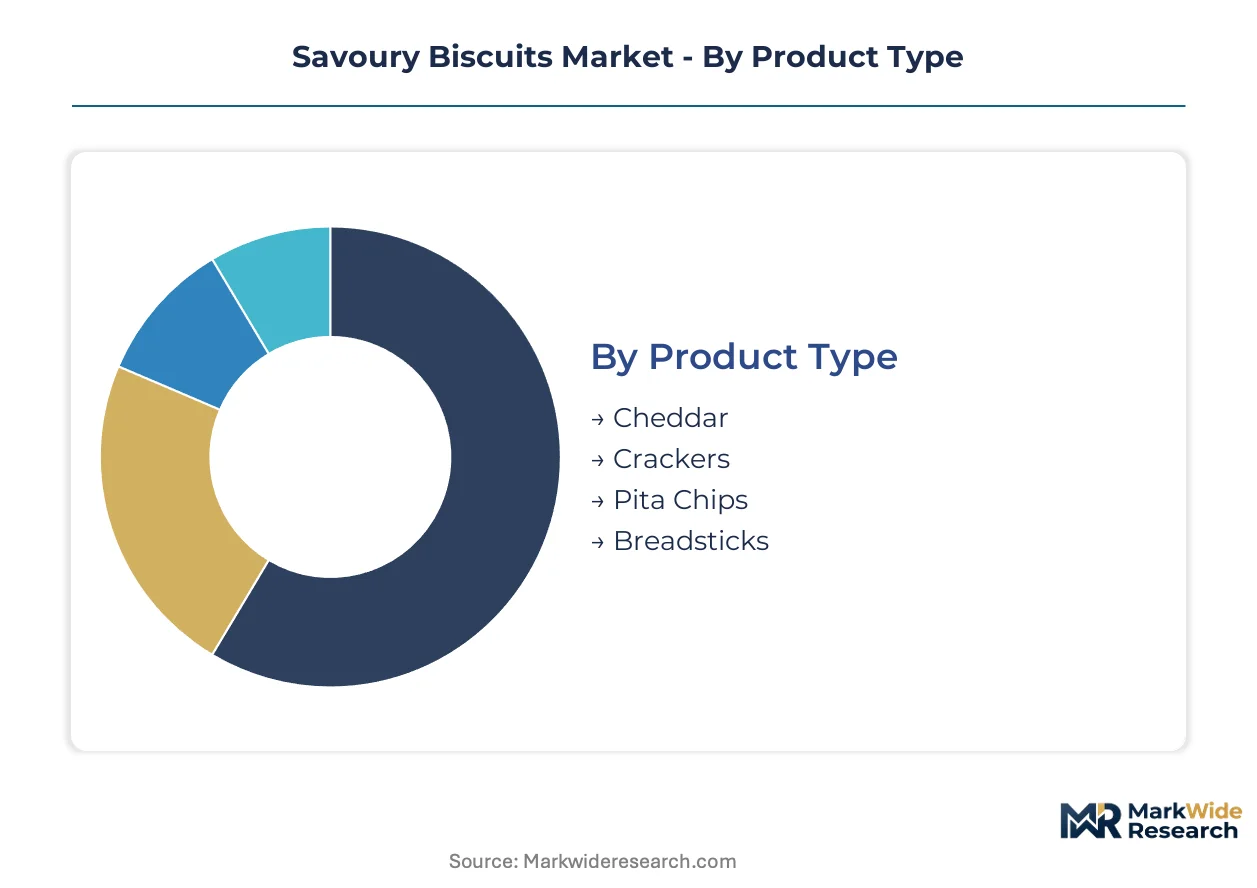
Savoury biscuit manufacturers segment portfolios to align production economics with divergent channel requirements. Pack format and flavour architecture decisions cascade through margin structures, shelf-life engineering, and distribution logistics.
Product Type:
Cost tier stratification separates commodity-positioned formats from premium texture-engineered lines requiring specialized lamination or extrusion equipment.
- Cheddar:Baked cheese-infused dough systems with moisture content below four percent deliver dense, crumbly textures. UK and US grocery multiples drive family-format volumes, though EFSA sodium thresholds force reformulation of traditional recipes.
- Crackers:Laminated or chemically leavened sheets with layered fat inclusions create snap and flakiness. Spicy and cheese variants in flexible bags capture repeat purchase frequency in Indian urban markets and North American convenience channels.
- Pita Chips:Twice-baked flatbread fragments with irregular surface area for seasoning adhesion. Mediterranean and Middle Eastern flavour positioning supports premium pricing in specialty retail.
- Breadsticks:Extruded, elongated formats with low oil absorption suited to food-service dipping applications. Italian and Spanish manufacturing clusters supply European restaurant chains with extended-length bulk configurations.
Cheddar holds installed capacity. Crackers are rotating up the share rankings.
Flavor Profile:
Application context determines whether flavour intensity prioritizes standalone snacking or meal accompaniment compatibility.
- Spicy:Chili, pepper, and masala blends with heat-delivery systems that survive baking temperatures. Indian quick-commerce platforms and US Hispanic-market retailers drive trial velocity for novel Scoville-calibrated variants.
- Herb:Dried rosemary, thyme, and oregano inclusions requiring moisture management to prevent rancidity. Mediterranean diet positioning supports shelf placement in German and French health-focused chains.
- Cheese:Powdered cheddar, parmesan, or blue cheese coatings applied post-bake for volatile compound retention. Mature margin pools in rigid container formats face pressure from clean-label scrutiny on artificial flavour enhancers.
- Garlic:Dehydrated granule or oil-based systems with allicin-stability challenges. FSSAI maximum sodium thresholds compel reduction of salt-garlic synergy in Indian reformulation cycles.
Cheese commands the largest addressable base. Spicy is climbing the fastest.
End User:
Customer type dictates pack architecture, order frequency, and margin capture through direct versus intermediated relationships.
- Retailers:Supermarkets, convenience stores, and quick-commerce platforms requiring case-ready merchandising with barcode-standardized outer packs. Slotting fee structures and promotional calendars shape supplier negotiation leverage.
- Food Service:Restaurants, cafeterias, and catering operations purchasing bulk or portion-controlled formats. Breadsticks and cracker assortments dominate with dipping-compatibility specifications.
- Wholesale:Distributors serving independent grocers and institutional buyers with pallet-scale logistics and extended payment terms.
- Exporters:Cross-border traders navigating divergent shelf-life regulations, label language requirements, and phytosanitary certifications for grain-based products.
Retailers anchor volume throughput. Food Service is gaining share fastest.
Packaging Type:
Volume and margin trade-offs between material cost, shelf differentiation, and consumption occasion matching determine format selection.
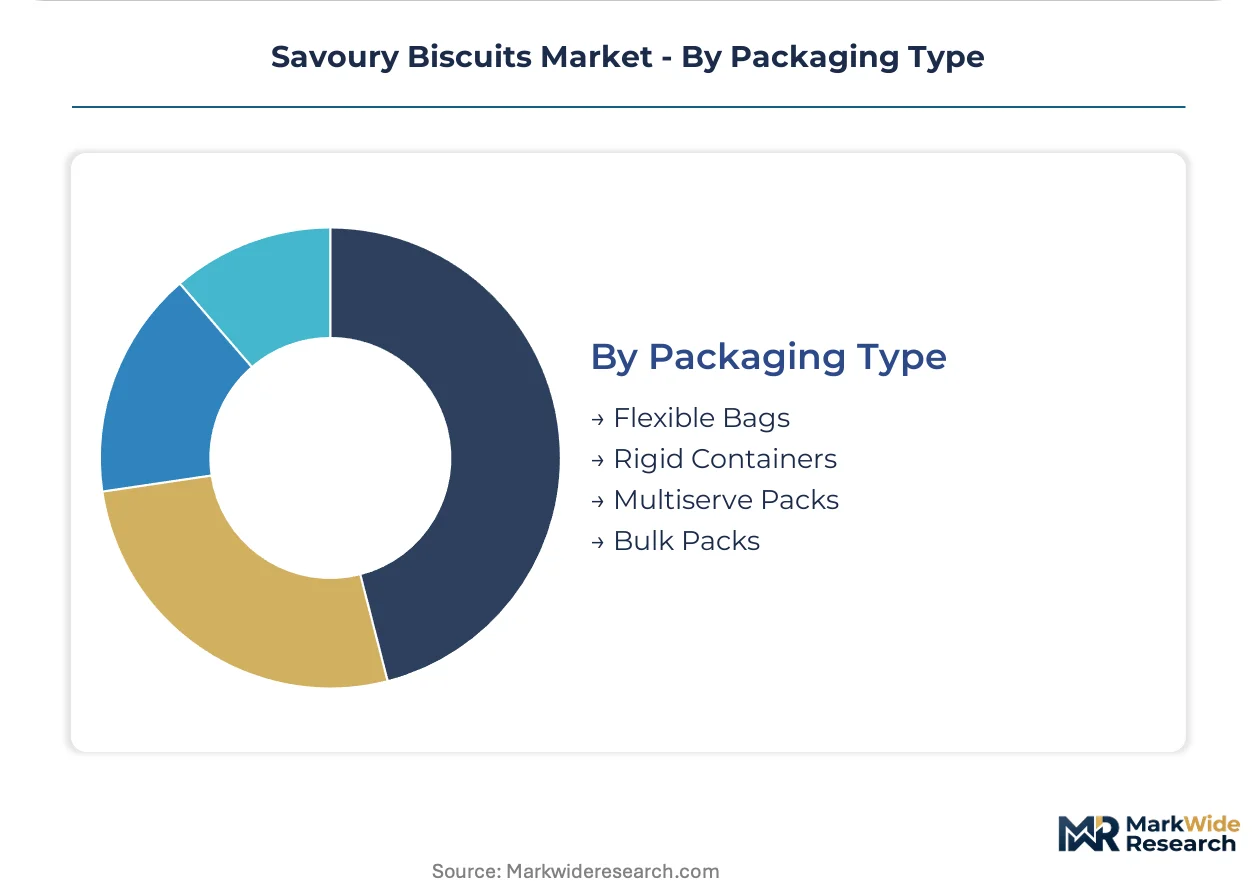
- Flexible Bags:Metallized or clear polyethylene structures with reseal zippers for portion control. Spicy and cheese cracker variants in this format show steepest velocity in Indian metro quick-commerce and US club channels.
- Rigid Containers:Composite paperboard or plastic tubs with stackability for pantry storage. Cheddar biscuits occupy this margin pool, though EU Green Deal mandates accelerate transition trials to molded fiber alternatives.
- Multiserve Packs:Intermediate count configurations balancing per-unit economics with household consumption rates. Mondelez-scale manufacturers optimize line efficiency through standardized case counts.
- Bulk Packs:Food-service-oriented outer cases with inner pillow packs or loose fill. Breadstick applications concentrate here with cost-per-ounce minimization for restaurant chain procurement.
Flexible Bags hold installed capacity. Rigid Containers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI sodium mandates and India's PLI scheme incentives are redirecting capital toward South Asian manufacturing scale. EFSA nutrient profiling and EU Green Deal packaging rules reshape European export economics.
India
Quick-commerce platforms in Mumbai, Bangalore, and Delhi fragment channel loyalty for impulse biscuit purchases. FSSAI's phased sodium reduction thresholds force reformulation of herb-garlic and cheese variants. Parle and Britannia compete for modern trade shelf space in Maharashtra and Gujarat manufacturing corridors.
United Kingdom
Hybrid work patterns sustain demand for portable snacking formats in London and Southeast England commuter belts. EFSA front-of-pack colour coding requirements drive cheddar biscuit reformulation cycles. Burton's Foods anchors specialty cracker production in Scottish and Midlands baking clusters.
Germany
Health-focused retail chains in Berlin and Hamburg enforce strict nutrient profiling for shelf placement. EU Green Deal biodegradable packaging mandates accelerate transition trials away from rigid composite containers. Bavarian and North Rhine-Westphalia food processing hubs pilot molded fiber alternatives for premium lines.
United States
Hispanic-market retailers in Texas and California drive trial velocity for spicy Scoville-calibrated variants. FDA serving-size disclosure rules reshape label architecture for export-bound production. Midwest grain processing corridors supply wheat flour inputs to cracker manufacturing facilities.
France
Mediterranean diet positioning supports herb-flavoured biscuit placement in Paris and Lyon health-focused chains. EFSA evolving criteria compel sodium and saturated fat restructuring to avoid red-category ratings. Île-de-France distribution hubs coordinate export logistics to North African markets.
Savoury Biscuits Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price-positioning bands. Multinational packaged food conglomerates leverage multiserve pack scale and grocery slotting leverage against regional heritage brands emphasizing provenance narratives. Three archetypes dominate: global scale operators, national heritage champions, and contract-manufacturing platforms. Competitive moves concentrate on clean-label reformulation racing and e-commerce direct-to-consumer channel building.
Within the heritage-brand tier, Burton's Foods and Walkers Shortbread occupy positions emphasizing British baking tradition and specialty texture expertise. Parle and Britannia exemplify the national-champion archetype in South Asian value-tier penetration. Mondelez International anchors the scale-driven end with global distribution infrastructure and standardized case-count optimization.
| Leading Market Players |
|---|
| Burton's Foods |
| Walkers Shortbread |
| Parle |
| ITC Limited |
| Mondelez International |
| Britannia |
| Lotus Bakeries |
| Kellogg |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
Black Sea wheat milling clusters anchor global flour supply for savoury biscuit manufacturers, concentrating margin capture in the hands of grain traders and compressing pricing power for downstream producers dependent on standardized cracker formulations.
Pricing Analysis
Certification level creates the primary spread between commodity and export-grade production, with FSSAI-compliant and EFSA-aligned formulations commanding shelf placement premiums in regulated channels. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient grade, pack format sophistication, and channel slotting investment. Cost compression in the economy tier is intensifying because contract manufacturers compete aggressively on volume contracts for private-label retail programs. Quick-commerce platforms exhibit the sharpest price sensitivity, while food-service procurement teams prioritize consistency over per-unit cost.
Supply Chain Analysis
Extended payment terms from Indian and UK retail consolidates strain working capital for mid-tier producers, forcing reliance on supply-chain finance facilities backed by commodity traders. Wheat sourcing concentrates in Ukraine, Russia, and Australia, with vegetable oil inputs drawn from Malaysian palm and European rapeseed processing hubs. Single-source vulnerability in Black Sea grain corridors threatens formulation continuity for sodium-reduced lines requiring specific protein content. Distribution runs through modern trade and quick-commerce platforms in Indian metros, with food-service breadstick volumes flowing through specialized bakery distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as quick-commerce algorithms fragment brand loyalty and reward niche flavour variants with discoverability advantages previously purchased through slotting fees.
For Market Incumbents: Harden clean-label credentials through captive sodium-reduction R&D capabilities that smaller competitors cannot replicate. Anchor shelf position in Maharashtra and Gujarat manufacturing corridors with PLI-linked capacity additions. Defend against contract-manufacturing challengers by controlling seasoning supplier relationships. For New Entrants and Emerging Players: Spicy Scoville-calibrated variants in Indian quick-commerce represent the most penetrable entry point for challenger brands seeking trial velocity without modern trade slotting investment. E-commerce direct-to-consumer channels in UK commuter belts offer secondary white-space for premium texture-engineered lines. Launch through algorithm-native platform positioning rather than traditional retail negotiation. For Investors and Strategic Acquirers: Capital is best deployed toward heritage-positioned regional brands with reformulation-ready product architectures and existing FSSAI or EFSA compliance documentation. Five-to-ten year viability hinges on sodium-reduction technical capabilities and quick-commerce fulfillment partnerships. Watch for FSSAI enforcement acceleration as the signal to differentiate between compliant and stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FSSAI sodium mandates force seasoning architecture rebuilds without taste trade-offs. |
| Quick-Commerce Channel Entry | Platform algorithms favour novel flavours, bypassing traditional slotting fee barriers. |
| PLI-Linked Capacity Expansion | Indian tax offsets reward domestic manufacturing scale in Maharashtra corridors. |
| Biodegradable Packaging Transition | EU Green Deal mandates create first-mover advantage for certified compostable films. |
| Contract Manufacturing Platform | Asset-light production lowers capital barriers for regional flavour variant testing. |
Methodological Framework
A spread of perspectives from brand managers, category buyers at retailers, channel sales heads, and supply planners converged on the working assumptions driving volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through Nielsen retail audit data, customs records, SEC filings from listed food manufacturers, and FSSAI regulatory notifications. Bottom-up SKU-level build-ups triangulated against top-down category spend analysis.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation modeled by product type, flavour profile, packaging format, and channel architecture. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and platform-channel growth curves. Wheat price volatility indices and sodium-reduction compliance timelines served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in grain commodity prices, consumer discretionary spending, or regulatory enforcement timelines would shift the trajectory. Forecasts reflect documented assumptions about PLI scheme continuity and EFSA nutrient profiling evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Extruded Snack Food Market
Snacks
UAE Cereal Bar Market
Snacks
Low Calorie Snack Foods Market
Snacks
High Carb Low Fat Snack Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Roasted Corn Market
Snacks
Qatar Potato Chips Market
Snacks
South America Frozen Snacks Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Protein Crisps Market
Snacks
Savory Snacks Market
Snacks
Global Tortilla Chips Market
Snacks
Middle East Snack Bar Market
Snacks
Gluten Free Snacks Market
Snacks
Cereal Bars Market
Snacks
Fruit Jerky Market