
 Germany Snack Bar Market | 2026-2036
Germany Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Snack Bar Market Foresight
The EU Green Deal is expanding compliance burdens for snack bar manufacturers sourcing palm oil and cocoa, forcing reformulation investments and supply chain audits. Mars Incorporated leverages its European R&D infrastructure to navigate evolving sustainability mandates. Nestlé SA anchors its German portfolio through specialized nutrition science. Mondelēz International Inc. competes via established confectionery-to-snack cross-selling channels.
A snack bar is a pre-portioned, shelf-stable food product typically comprising cereals, dried fruits, nuts, proteins, or seeds bound by syrups or edible adhesives, manufactured through extrusion, cold-pressing, or baking processes to achieve target moisture content below 15%. Protein bars lead German value generation due to premium positioning among fitness enthusiasts, while granola bars sustain volume through breakfast replacement habits. Seed bars represent the fastest-growing product type as consumers seek allergen-friendly alternatives to nut-dominant formulations.
German snack bar producers face binding requirements under BfR food contact material standards, EU Nutrition and Health Claims Regulation, and national Lebensmittelrecht purity laws that restrict additive use and mandate transparent labeling. These frameworks elevate R&D costs for entrants while rewarding incumbents with established compliance infrastructure. Stakeholders must monitor pending EU packaging waste directives that will reshape material specifications and recycling obligations across the value chain.
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are forcing German snack bar manufacturers to restructure procurement networks for cocoa and palm oil, elevating compliance costs while creating tiered competitive advantages for firms with pre-existing sustainability infrastructure.
Growth Catalysts
- Clean-label protein demand:Fitness enthusiasts in Berlin and Munich are driving premium positioning for functional bars with transparent ingredient decks, compressing margins for legacy formulations with artificial additives.
- Nutri-Score labeling mandate:Germany's front-of-pack rating system rewards reformulated products with favorable scores, incentivizing manufacturers to reduce sugar density and improve nutritional profiles.
- Seed bar innovation:Allergen-friendly alternatives to nut-dominant formulations are capturing shelf space as sunflower and pumpkin seed bases overcome technical binding challenges through cold-pressing advances.
Market Restraints
- Cocoa price volatility:West African supply concentration exposes German processors to weather-driven input cost swings that compress gross margins on chocolate-coated and cocoa-inclusive bars.
- BfR food contact material compliance:Binding standards for packaging substrates elevate R&D expenditure for entrants lacking established testing protocols and supplier certification networks.
- Breakfast cereal substitution:Traditional muesli and yogurt parfait formats retain habitual loyalty among older demographics, limiting penetration velocity for granola bar breakfast replacement claims.
Strategic Opportunities
- Pending packaging waste directives:EU recycling obligation frameworks will reshape material specifications, rewarding early movers with mono-material flexible packaging and closed-loop collection infrastructure.
- Corporate wellness channel expansion:Employer-subsidized snack programs in Frankfurt and Hamburg financial districts create institutional procurement volumes with lower price sensitivity than retail.
- Lebensmittelrecht purity law alignment:Transparent additive restrictions enable premium positioning for domestic manufacturers against imports with less stringent formulation standards.
Industry Challenges
- Extrusion equipment retooling:Legacy production lines require capital-intensive modification to handle alternative protein isolates and novel binding syrups without moisture content degradation.
- Supply chain audit complexity:Deforestation-free due diligence obligations demand traceability systems that fragment procurement relationships and extend ingredient qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Snack Bar Market |
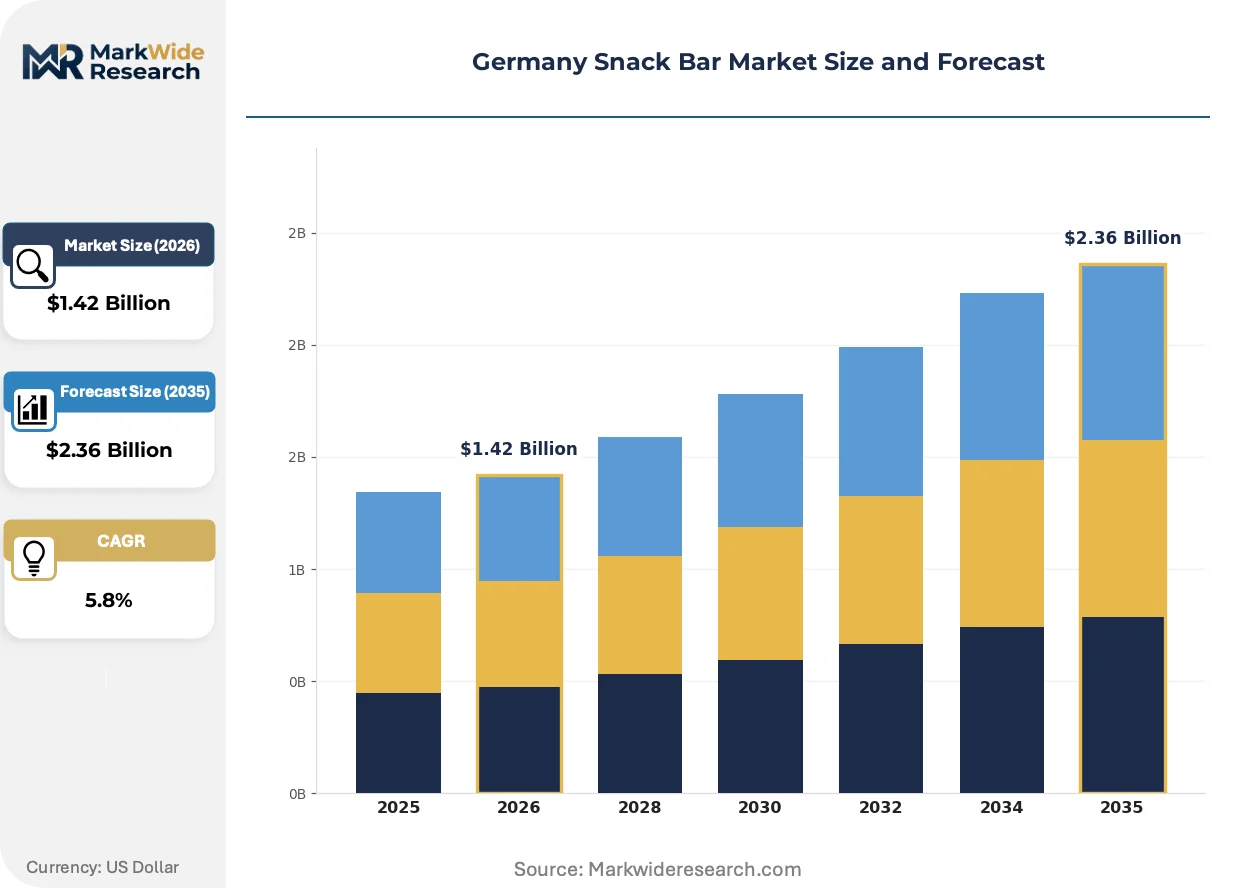
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Fruit Bars, Protein Bars, Nut Bars, Cereal Bars, Seed Bars Packaging Type: Wrapper Packs, Boxed Packs, Multipacks, Stand-up Pouches, Carton Packs, Blister Packs Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Health Food Stores, Vending Machines Customer Type: Children, Teenagers, Adults, Fitness Enthusiasts, Office Workers, Travelers |
| Companies Covered | Mars Incorporated, Natural Balance Foods, Mondelēz International Inc., Bauli SpA, The Kellogg Company, Nestlé SA, Hero Group, Dr. Schar, General Mills Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Snack Bar Market Shifts & Advancements
Reformulation science and packaging engineering are converging to reshape competitive positioning, with sustainability credentials and functional claims displacing taste-centric marketing as primary purchase determinants among German urban consumers.
Cold-pressed protein bar manufacturing is modularizing production workflows by enabling smaller-batch flexibility without extrusion infrastructure. Regional craft producers in Bavaria and Baden-Württemberg are adopting these systems to test limited-release formulations. This technology is modularizing the traditional scale economies that concentrated volume with industrial incumbents.
REACH chemical safety protocols and pending EU packaging waste directives are tightening material specifications for flexible films and adhesives. German manufacturers face reformulation deadlines for multilayer structures that currently impede mechanical recycling. Seed bar specialists with mono-material pouches are responding fastest to these constraints.
Direct-to-gym distribution models are compressing traditional retail intermediation as fitness chains in Cologne and Stuttgart build private-label bar portfolios. Boutique studio networks negotiate exclusive flavor collaborations that bypass conventional wholesale markups. This channel shift is most visible among CrossFit and boutique cycling verticals where community identity drives brand attachment.
Germany Snack Bar Market Segmentation
German snack bar manufacturers calibrate formulation density, packaging formats, and channel economics against distinct consumption rituals. Segmentation reveals where premium functional claims command price premiums versus where volume throughput depends on breakfast substitution habits.
Product Type:
Standardization dominates commodity granola formats while customization accelerates across protein-fortified and allergen-free alternatives.
- Protein Bars:High-isolate formulations with 20g+ protein content target post-workout recovery windows. Demand clusters in Munich and Berlin fitness studio networks where Nutri-Score A ratings justify 40% price premiums over conventional bars.
- Seed Bars:Sunflower and pumpkin seed bases bound with rice syrup overcome nut-allergen restrictions while delivering comparable fat profiles. Cold-pressing adoption in Baden-Württemberg craft facilities is compressing batch minimums for regional distribution.
- Granola Bars:Oat-dominant formulations with dried fruit inclusions sustain breakfast replacement volume through Aldi and Lidl private-label programs.
- Fruit Bars:Compressed date and fig matrices with minimal processing appeal to clean-label purists in organic retail channels.
- Nut Bars:Almond and cashew-dense formats face BfR aflatoxin testing burdens that elevate qualification costs for imported nut supplies.
- Cereal Bars:Puffed rice and wheat flake constructions compete directly with muesli segments for morning consumption occasions.
Most installed capacity flows through Granola Bars. Expansion is steepest in Seed Bars.
Packaging Type:
Cost tiers separate single-serve convenience formats from multipack economy positioning, with sustainability premiums reshaping material specifications.
- Wrapper Packs:Individual flow-wrapped units in metallized films dominate impulse channels. REACH compliance deadlines are forcing mono-material transitions that eliminate current multilayer structures by pending EU packaging waste directive timelines.
- Stand-up Pouches:Resealable multi-serve formats with zip-lock closures capture family pantry placement. Bavarian producers piloting paper-based barriers are gaining shelf space in dm-drogerie markt sustainability-forward assortments.
- Multipacks:Outer carton with flow-wrapped inner units balance per-unit cost reduction with portion control.
- Boxed Packs:Rigid paperboard presentations support gift-oriented premium positioning in department store food halls.
- Carton Packs:Gable-top liquid carton adaptations for drinkable grain formats remain niche in German convenience channels.
- Blister Packs:Thermoformed trays with lidding films serve pharmaceutical-adjacent positioning for clinical nutrition segments.
Highest throughput runs through Wrapper Packs. Material innovation is concentrating in Stand-up Pouches.
Distribution Channel:
Volume concentrates in consolidated retail while margin expansion tracks through specialized health and institutional channels.
- Supermarkets:Edeka, Rewe, and Kaufland assortments drive 70%+ volume throughput via prominent checkout and breakfast aisle placement. Nutri-Score shelf-talkers are reallocating space toward reformulated SKUs with favorable ratings.
- Online Retailers:Amazon.de and specialized platforms enable subscription models for protein bar replenishment. Direct-to-consumer margins bypass wholesale markups while generating consumption data for flavor development.
- Health Food Stores:Alnatura and Basic Bio channels command 25-35% price premiums for certified organic and vegan formulations.
- Convenience Stores:Shell and Aral petrol station networks sustain grab-and-go velocity for single-serve impulse purchases.
- Specialty Stores:Fitness equipment retailers and running shops build private-label bar portfolios alongside apparel.
- Vending Machines:Automated retail in Frankfurt and Hamburg office towers is expanding through employer-subsidized wellness programs.
Dominant volume flows through Supermarkets. Margin expansion is fastest in Online Retailers.
Customer Type:
Application intensity separates habitual daily consumers from occasional situational purchasers across life-stage and activity segments.
- Fitness Enthusiasts:Gym-attached consumers with 4+ weekly training sessions drive premium protein bar velocity. Cologne and Stuttgart CrossFit affiliate exclusive flavor collaborations bypass conventional distribution economics.
- Office Workers:Desk-bound professionals in Frankfurt financial district towers sustain mid-afternoon energy bar rituals through corporate pantry programs.
- Adults:Broad 25-55 demographic sustains granola bar breakfast replacement habits with lower price sensitivity to ingredient provenance than fitness segments.
- Teenagers:Secondary school vending access and parental lunchbox inclusion drive fruit bar and cereal bar volume.
- Children:Strict BfR additive restrictions and Lebensmittelrecht purity standards limit formulation options for under-12 positioning.
- Travelers:Deutsche Bahn station convenience and airport retail sustain shelf-stable portability claims for long-distance rail passengers.
Core volume concentrates among Adults. Growth intensity is highest among Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing workforce and food science talent clusters anchor the European snack bar innovation corridor. Regional demand concentrates in metropolitan fitness ecosystems and corporate wellness programs across western federal states.
Bavaria
Munich's CrossFit affiliate networks and boutique cycling studios drive premium protein bar velocity through exclusive flavor collaborations. The BfR enforces strict food contact material standards that elevate packaging compliance costs for regional craft producers. Cold-pressing facilities in Augsburg and Nuremberg are modularizing production workflows for seed bar experimentation.
North Rhine-Westphalia
Cologne's fitness chain private-label programs and Düsseldorf corporate headquarters sustain institutional procurement volumes with lower price sensitivity. REACH chemical safety protocols tighten specifications for flexible film adhesives used in wrapper packs. Extrusion equipment retooling in the Ruhr industrial belt addresses alternative protein isolate handling requirements.
Baden-Württemberg
Stuttgart's automotive executive wellness programs and Freiburg's organic retail density create bifurcated demand for functional and clean-label formats. EU Green Deal deforestation-free mandates force supply chain audits for cocoa and palm oil sourcing. Regional craft producers in the Black Forest pilot paper-based barrier stand-up pouches for dm-drogerie markt placement.
Hesse
Frankfurt's financial district employer-subsidized snack programs generate mid-afternoon energy bar rituals among desk-bound professionals. Lebensmittelrecht purity laws restrict additive use and mandate transparent labeling that favors domestic manufacturers. Vending machine operators in Mainz and Wiesbaden office towers are expanding automated retail through wellness program contracts.
Berlin-Brandenburg
Berlin's health-conscious office workers and fitness enthusiasts concentrate demand for Nutri-Score A-rated reformulations with reduced sugar density. Germany's front-of-pack labeling mandate reallocates supermarket shelf space toward favorably scored SKUs. Direct-to-gym distribution models in Potsdam bypass traditional wholesale markups through boutique studio exclusive arrangements.
Germany Snack Bar Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price and function segments. The market structure rewards incumbents with established compliance infrastructure under BfR and EU regulatory frameworks while elevating barriers for entrants lacking testing protocols and supplier certification networks. Three archetypes dominate: multinational CPG conglomerates with European R&D infrastructure, regional craft producers leveraging cold-press modularization, and private-label specialists serving fitness chain exclusive programs. Competitive moves concentrate on portfolio diversification into allergen-friendly seed formulations and strategic partnerships for closed-loop packaging collection infrastructure.
Within the multinational conglomerate tier, Mars Incorporated, Nestlé SA, and Mondelēz International Inc. exemplify archetypes distinguished by R&D scale and channel anchoring. Mars Incorporated occupies a position leveraging European infrastructure to navigate sustainability mandates. Nestlé SA represents the specialized nutrition science approach to portfolio construction. Mondelēz International Inc. sits within the confectionery-to-snack cross-selling channel strategy. These three entities collectively illustrate how regulatory compliance capabilities and established supplier networks create tiered competitive advantages under evolving EU Green Deal and packaging waste directive frameworks.
| Leading Market Players |
|---|
| Mars Incorporated |
| Natural Balance Foods |
| Mondelēz International Inc. |
| Bauli SpA |
| The Kellogg Company |
| Nestlé SA |
| Hero Group |
| Dr. Schar |
| General Mills Inc. |
| Others |
Supply & Pricing Matrix
Captive sourcing of cocoa and palm oil through audited West African cooperatives anchors margin stability for German snack bar manufacturers while insulating premium-tier producers from commodity spot volatility that erodes standard-segment pricing power. This upstream integration choice concentrates compliance investment among incumbents with established traceability infrastructure, creating tiered competitive positions that reflect BfR certification depth rather than formulation sophistication alone.
Pricing Analysis
Product-plus-service bundling separates functional protein bars with gym-channel exclusive flavors from unbundled granola formats competing on per-gram shelf price. Three-tier pricing structure across premium functional, standard clean-label, and economy private-label levels tracks Nutri-Score rating and certification depth. Cost compression in the standard tier intensifies as Aldi and Lidl private-label programs compress wholesale markups. Fitness enthusiasts in Munich and Berlin studios exhibit lowest price sensitivity, while family-pack granola purchasers through discount channels resist premiums above 15 percent for organic positioning.
Supply Chain Analysis
Workforce availability in Bavaria's precision food manufacturing belt and Baden-Württemberg's craft production clusters anchors domestic extrusion and cold-pressing capacity. Cocoa bean supply draws from Côte d'Ivoire and Ghana, sunflower seed protein isolates from Eastern European processors, and flexible film substrates from German and Italian converters. Single-source vulnerability concentrates in West African cocoa cooperatives exposed to weather-driven crop failure. Distribution runs through Edeka and Rewe supermarket networks with direct-store-delivery logistics, supplemented by Amazon.de fulfillment centers for subscription replenishment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's Lebensmittelrecht purity standards and front-of-pack Nutri-Score mandates create a regulatory arbitrage window against neighboring EU markets with less stringent additive transparency requirements, rewarding domestic production footprint over import-dependent competitors.
For Market Incumbents: Lock in deforestation-free supply chain certification ahead of EU Green Deal enforcement deadlines to foreclose entrant access to premium retail placement. Secure exclusive distribution partnerships with CrossFit and boutique cycling studio networks in Cologne and Stuttgart before regional craft producers scale cold-press capacity. Capacity addition in Bavaria's automated extrusion facilities addresses alternative protein isolate handling requirements while building technical moats against modular craft competitors. For New Entrants and Emerging Players: REACH chemical safety protocols in Germany open a window for mono-material flexible packaging specialists to capture dm-drogerie markt shelf space ahead of multilayer film incumbents facing reformulation deadlines. Target seed bar formulations in Baden-Württemberg organic retail channels where allergen-friendly positioning commands 25-35 percent price premiums with minimal incumbent saturation. Direct-to-gym distribution through boutique studio exclusive flavor collaborations bypasses conventional wholesale markups and builds community-driven brand attachment. For Investors and Strategic Acquirers: Roll-up economics work for regional craft producers with cold-press modularization capabilities because fragmentation across Bavaria and Baden-Württemberg leaves scale advantages unconsolidated. Focus acquisition screening on facilities with existing BfR food contact material testing protocols and established supplier certification networks. Watch for EU packaging waste directive implementation timelines as inflection indicator for mono-material packaging specialists with closed-loop collection infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Supply Chain Certification | EU Green Deal compliance secures premium retail placement and insulates against cocoa procurement disruption. |
| Mono-Material Packaging Transition | REACH protocol alignment captures dm-drogerie markt sustainability-forward assortment ahead of incumbent reformulation. |
| Direct-to-Gym Distribution Buildout | Boutique studio exclusive arrangements in Cologne and Stuttgart compress wholesale intermediation and deepen brand attachment. |
| Seed Bar Formulation Expansion | Allergen-friendly positioning in Alnatura and Basic Bio channels addresses unmet demand from nut-restricted consumers. |
| Cold-Press Production Modularization | Baden-Württemberg craft facilities enable limited-release experimentation without extrusion infrastructure capital burden. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at Mars Incorporated and Nestlé SA, category buyers at Edeka and Rewe, supply planners at German flexible film converters, and R&D directors at Bavarian extrusion facilities with secondary validation. Nielsen retail audit data, BfR food contact material guidance documents, EU Green Deal regulatory filings, and customs records for cocoa and sunflower seed protein isolate imports anchored supply-side assessment. Bottom-up SKU-level demand modeling and top-down category value triangulation cross-checked volume assumptions.
Segment-weighting approaches applied differential growth assumptions across protein bars, seed bars, and granola formats by distribution channel intensity and customer type penetration rates. Product type, packaging format, distribution channel, and regional federal state dimensions structured the analytical framework across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory catalyst timing and channel shift elasticity. Nutri-Score adoption velocity and cold-press equipment installation rates in craft facilities informed industry-specific forecast inputs.
Revisions become necessary when EU packaging waste directive implementation timelines accelerate, cocoa price volatility exceeds historical bands, or BfR additive restrictions tighten beyond current Lebensmittelrecht baselines. Forecasts reflect documented assumptions about regulatory enforcement consistency and consumer willingness-to-pay for sustainability credentials. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Protein Bars Market
Snacks
Indonesia Snack Bar Market
Snacks
Europe Extruded Snack Food Market
Snacks
Roasted Corn Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Low Sodium Snacks Market
Snacks
Asia Pacific Tortilla Market
Snacks
Sweet Potato Chips Market
Snacks
Forti Flakes Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Baked Savoury Snacks Market
Snacks
South America Snack Bar Market
Snacks
Fruit Jerky Market
Snacks
Better for You Snacks Market
Snacks
Crackers Market
Snacks
United States Children's Snack Bar Market