
 Low-Carb Low-Fat Bread Market | 2026-2036
Low-Carb Low-Fat Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Carb Low-Fat Bread Market Analytics
The capital-intensity gap between artisan-scale bakers and industrial producers is collapsing as automated extrusion and cold-press fermentation equipment becomes accessible at smaller volumes. Carbonaut leverages proprietary high-fiber dough systems to sustain margin across gluten-free and multigrain lines. Lewis Bake Shop anchors supermarket distribution through direct-store-delivery networks that dominate conventional retail bread aisles. Julian Bakery specializes in psyllium-husk formulations that differentiate its portfolio within the athlete and diabetic end-user segments.
Low-carb low-fat bread denotes baked goods engineered to reduce net carbohydrate and lipid content below conventional wheat bread thresholds, typically achieving under 10 grams net carbs and under 2 grams fat per serving through modified flour matrices, protein isolates, and hydrocolloid binders. The category serves consumers managing glycemic response, caloric restriction, or macronutrient-targeted diets. Whole grain and sourdough product types command premium shelf positioning as perceived clean-label alternatives, while gluten-free variants experience the fastest velocity growth in health food stores and online retail channels. Almond flour and wheat protein ingredient types concentrate margin pools due to supply constraints and functional performance requirements in dough structuring.
FDA nutritional labeling and the USDA Dietary Guidelines for Americans shape permissible health claims and serving-size disclosures, directly influencing product positioning and reformulation cycles. EFSA health claim regulations in Europe and FSSAI standards in India impose parallel compositional thresholds that govern cross-border market access and export qualification. Stakeholders must monitor evolving definitions of dietary fiber across jurisdictions, as regulatory reclassifications of resistant starches and oligosaccharides would force rapid ingredient substitutions and label revisions.
Market Dynamics
Automated cold-press fermentation equipment is collapsing the capital-intensity gap between artisan-scale bakers and industrial producers, redistributing competitive leverage toward mid-volume specialists who can now achieve industrial-grade consistency without legacy plant investments.
Growth Catalysts
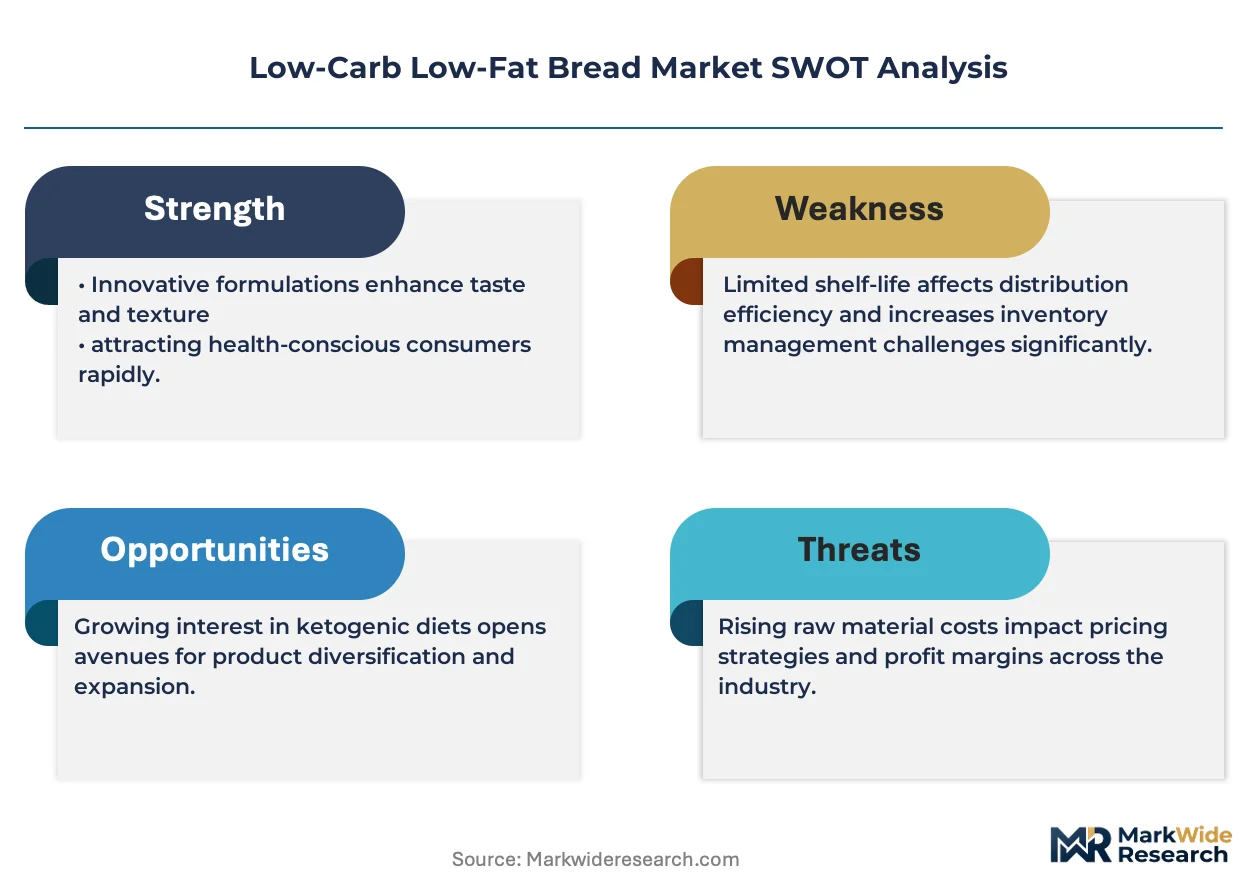
- FDA Nutritional Labeling Requirements:Updated serving-size disclosures and permissible health claim frameworks compel reformulation toward cleaner macronutrient profiles, accelerating portfolio refresh cycles across conventional retail channels.
- Fitness and Wellness Program Integration:Health-conscious consumers managing glycemic response or macronutrient-targeted diets drive sustained velocity in specialty bread aisles, particularly among athlete and diabetic end-user segments.
- Almond Flour Supply Chain Maturation:Expanded cultivation in California and Mediterranean growing regions eases prior supply constraints, enabling broader adoption of premium protein-isolate formulations.
Market Restraints
- Resistant Starch Reclassification Risk:Evolving FDA and EFSA definitions of dietary fiber threaten rapid ingredient substitutions and forced label revisions, creating compliance uncertainty.
- Wheat Protein Concentration:Functional performance requirements in dough structuring concentrate margin pools among limited suppliers of vital wheat gluten isolates.
- Hydrocolloid Cost Volatility:Guar gum and psyllium husk prices fluctuate with Indian and Pakistani agricultural yields, compressing formulation economics for high-fiber dough systems.
Strategic Opportunities
- Japan's Aging Demographic:Diabetic and metabolic syndrome management protocols create specialized demand for sub-10 gram net carb formulations in convenience retail channels.
- Direct-to-Consumer Subscription Models:Frozen low-carb bread delivery bypasses conventional retail slotting fees, capturing margin from health food store shoppers.
- USDA Dietary Guidelines Alignment:Updated macronutrient recommendations create tailwinds for whole grain and sourdough variants positioned as clean-label alternatives.
Industry Challenges
- Extrusion Equipment Calibration:Automated dough processing requires specialized maintenance expertise scarce among traditional bakery workforces, extending commissioning timelines.
- Cross-Border FSSAI Qualification:Indian export certification demands compositional threshold documentation that conflicts with Western resistant starch classifications, complicating market access.
- Legacy ERP Integration:Cold-press fermentation monitoring systems interface poorly with conventional bakery production software, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Carb Low-Fat Bread Market |
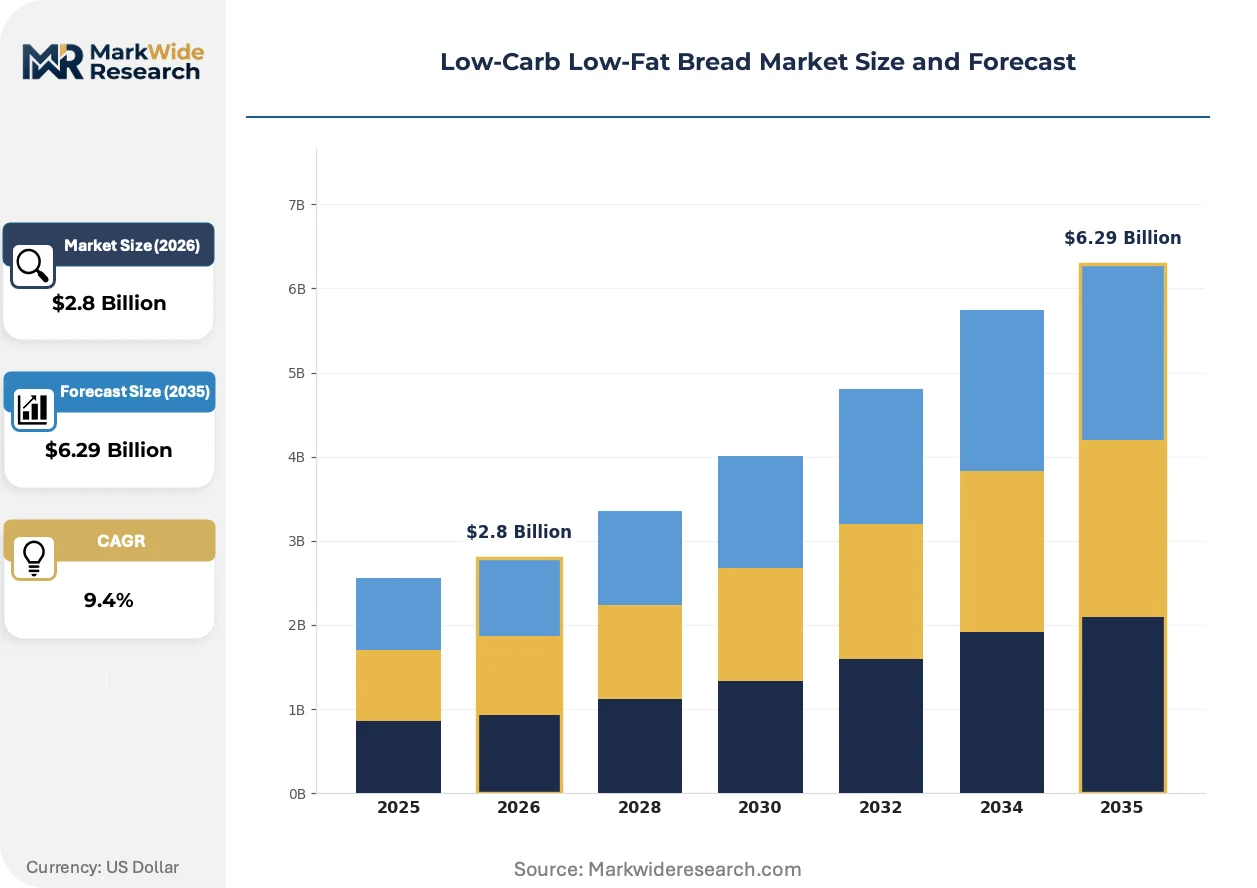
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Multigrain, Sourdough, Gluten-Free Ingredient Type: Almond Flour, Coconut Flour, Wheat Protein, Psyllium Husk Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Health-Conscious Consumers, Diabetics, Athletes, Weight Watchers |
| Companies Covered | Low Carb Avenue, Carbonaut, Sola, Lewis Bake Shop, L'oven Fresh, Julian Bakery, ThinSlim Foods, Shibolim, The Great Low Carb Bread Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Carb Low-Fat Bread Market Evolving Landscape
Reformulation science is accelerating beyond simple macronutrient subtraction toward functional fiber architectures that replicate conventional wheat bread's sensory properties without glycemic penalty.
Cold-press fermentation technology is fragmenting the equipment supply base, enabling smaller producers to achieve industrial-grade dough consistency. Boutique health food manufacturers and regional bakery cooperatives adopt these systems at accelerating replacement cycles. The technology is fragmenting volume concentration away from legacy industrial plant networks toward distributed production models.
EFSA health claim regulations in Europe impose parallel compositional thresholds that govern cross-border market access and permissible marketing language. Industrial consequence includes forced harmonization of resistant starch and oligosaccharide classifications across formulation teams. Gluten-free variants experience the most acute compliance pressure, requiring dedicated regulatory affairs functions.
Health food store procurement patterns are compressing supplier qualification timelines as buyers demand faster portfolio rotation. Direct-store-delivery networks that dominate conventional retail bread aisles face disintermediation from frozen specialty distributors. Germany's REWE and EDEKA supermarket chains exhibit the most aggressive slotting fee renegotiation in response.
Low-Carb Low-Fat Bread Market Segmentation
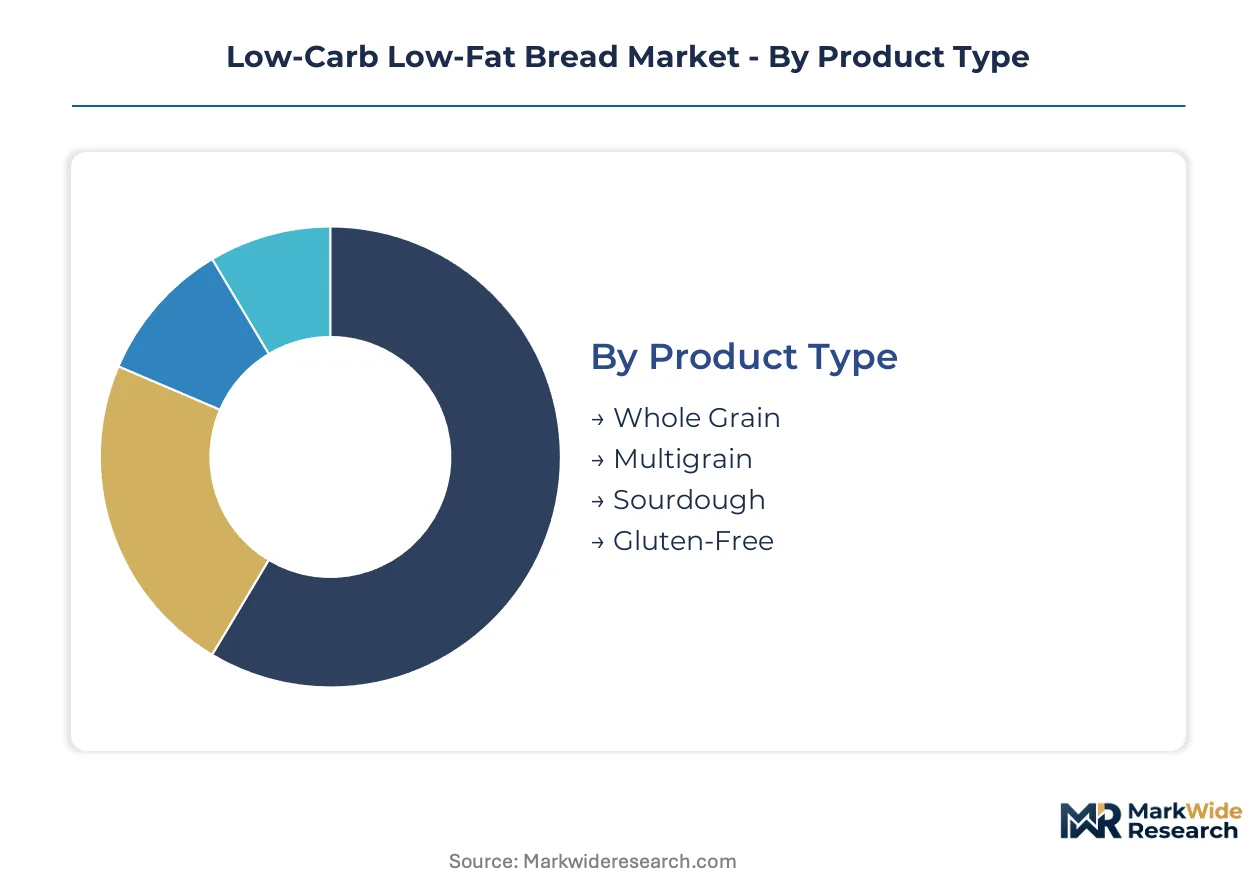
Segmentation in the low-carb low-fat bread market reveals how formulation choices, channel access, and user physiology create distinct margin architectures. Manufacturers must align R&D investment with the highest-velocity combinations across these four dimensions.
Product Type:
Margin pools concentrate in premium-positioned variants that command shelf-space premiums through clean-label positioning and extended fermentation protocols.
- Whole Grain:Formulations retain bran and germ layers while achieving sub-10 gram net carb thresholds through sprouted grain processing and enzyme-modified starches. Demand concentrates in Germany and the United States among consumers prioritizing USDA Dietary Guidelines alignment over strict ketogenic protocols.
- Gluten-Free:Psyllium-husk and xanthan gum binding systems replace gluten networks, creating dough structures with elevated production complexity. Health food stores and online retail channels in Japan exhibit the steepest velocity growth as celiac and NCGS diagnoses expand.
- Multigrain:Composite flour matrices blend modified wheat proteins with seeds and legumes for textural complexity.
- Sourdough:Extended fermentation reduces phytic acid and glycemic index through organic acid production.
The dominant share belongs to Whole Grain, while Gluten-Free is closing the gap fastest.
Ingredient Type:
Supply scarcity and functional performance requirements create tiered input cost structures that cascade directly into finished goods pricing.
- Almond Flour:Blanched California almonds yield fine-milled protein isolates with superior moisture retention and neutral flavor profiles. Mediterranean cultivation expansion is easing prior supply constraints that had concentrated margin pools among limited processors.
- Wheat Protein:Vital gluten isolates provide elastic dough structure essential for conventional bread mouthfeel in reduced-carb formulations. Athlete and diabetic end-user segments in the United States drive sustained demand despite price volatility from concentrated supplier bases.
- Coconut Flour:High-fiber byproduct of coconut oil extraction absorbs moisture aggressively, requiring precise hydration calibration.
- Psyllium Husk:Indian and Pakistani agricultural yields directly determine input cost stability for high-fiber binding systems.
Wheat Protein maintains volume leadership, though Almond Flour is expanding most quickly as supply chain maturation enables broader adoption.
Distribution Channel:
Channel economics diverge sharply between high-slotting-fee conventional retail and margin-preserving direct access models.
- Online Retail:Frozen direct-to-consumer delivery bypasses conventional retail slotting fees while capturing health food store shoppers through subscription mechanics. Japan's aging demographic and convenience-oriented purchasing patterns favor this channel for specialized metabolic management products.
- Supermarkets:Direct-store-delivery networks dominate conventional bread aisles through established relationships with Lewis Bake Shop and similar regional producers. EDEKA and REWE chains in Germany are renegotiating slotting fee structures aggressively as specialty bread assortments deepen.
- Health Food Stores:Compressed supplier qualification timelines demand faster portfolio rotation from boutique manufacturers.
- Specialty Shops:Artisan-scale positioning supports premium pricing for small-batch cold-press fermentation products.
Supermarkets retain the largest transaction volume, yet Online Retail is gaining share fastest through frozen delivery infrastructure investments.
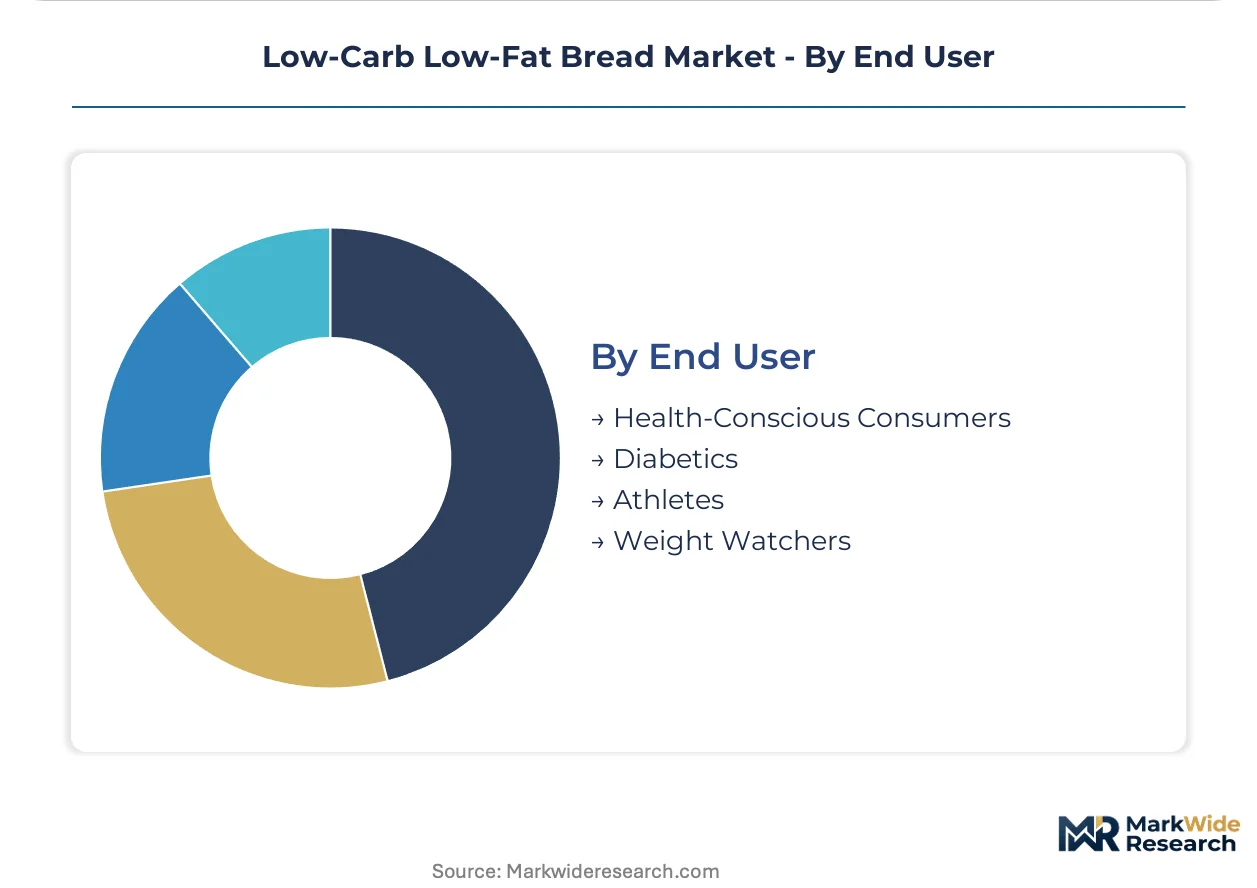
End User:
Physiological need states create distinct formulation requirements that segment R&D priorities and marketing investment.
- Diabetics:Glycemic response management demands precise net carbohydrate quantification and resistant starch verification for insulin protocol alignment. FDA nutritional labeling requirements and updated serving-size disclosures directly shape permissible health claims in this segment.
- Athletes:Macronutrient-targeted diets prioritize protein density and rapid glycogen recovery compatibility. Julian Bakery and similar specialists command premium positioning through psyllium-husk formulations tailored to body composition protocols.
- Health-Conscious Consumers:General wellness positioning emphasizes clean-label ingredient transparency over strict macronutrient thresholds.
- Weight Watchers:Caloric restriction focus prioritizes satiety index and portion-controlled serving architectures.
Health-Conscious Consumers represent the broadest addressable base, while Diabetics demonstrate the steepest expansion trajectory as metabolic syndrome prevalence rises across aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Japanese consumers demonstrate the lowest price sensitivity for metabolic management products, while Indian buyers prioritize affordability in emerging specialty segments. European markets occupy a middle ground where regulatory compliance costs drive premium positioning.
United States
Fitness enthusiasts and diabetic consumers sustain velocity in specialty bread aisles through macronutrient-targeted purchasing. FDA nutritional labeling requirements and updated USDA Dietary Guidelines compel reformulation toward cleaner profiles. California's almond flour processing clusters and Midwest direct-store-delivery networks anchor supply chain density for conventional retail penetration.
Germany
Whole grain and sourdough variants command premium shelf positioning through perceived clean-label alignment with federal nutrition policies. EFSA health claim regulations impose compositional thresholds governing permissible marketing language. REWE and EDEKA supermarket chains in North Rhine-Westphalia and Bavaria drive aggressive slotting fee renegotiation as specialty assortments deepen.
Japan
Aging demographics and metabolic syndrome management protocols create specialized demand for sub-10 gram net carb formulations. METI standards and convenience retail channel expansion favor frozen direct-to-consumer delivery models. Tokyo and Osaka metropolitan areas concentrate health food store procurement patterns with compressed supplier qualification timelines.
India
Price-conscious health food shoppers drive emerging interest in modified wheat protein formulations for glycemic management. FSSAI standards impose compositional threshold documentation that conflicts with Western resistant starch classifications, complicating import qualification. Maharashtra and Gujarat processing hubs experiment with localized psyllium husk supply chains for regional bakery networks.
Low-Carb Low-Fat Bread Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in this market. Automated cold-press fermentation equipment has redistributed leverage toward mid-volume specialists achieving industrial-grade consistency without legacy plant investments. The vendor base separates into three strategic archetypes: proprietary high-fiber dough system innovators, direct-store-delivery network dominators, and psyllium-husk formulation specialists. Dominant competitive moves include portfolio diversification across gluten-free and multigrain lines, and backward integration into almond flour processing to secure margin pools.
Among North American specialists, Carbonaut, Lewis Bake Shop, and Julian Bakery exemplify distinct competitive positioning. Carbonaut occupies the proprietary technology tier through high-fiber dough system ownership. Lewis Bake Shop anchors conventional retail penetration through direct-store-delivery infrastructure. Julian Bakery sits within the athlete and diabetic end-user specialization vector. Each represents a viable path to margin defense against industrial-scale entrants.
| Leading Market Players |
|---|
| Low Carb Avenue |
| Carbonaut |
| Sola |
| Lewis Bake Shop |
| L'oven Fresh |
| Julian Bakery |
| ThinSlim Foods |
| Shibolim |
| The Great Low Carb Bread Company |
| Others |
Value Network & Pricing Analysis
Automated cold-press fermentation equipment at mid-scale volumes compresses unit economics and anchors price floors for premium-positioned loaves. California almond flour processing clusters and Indian psyllium husk cultivation regions concentrate margin pools among limited suppliers, forcing buyers into long-term offtake contracts or vertical integration to secure input cost stability.
Pricing Analysis
Subscription-based frozen delivery models capture lifetime value through recurring revenue mechanics that bypass supermarket slotting fees. Three-tier pricing structure across premium, standard, and economy levels separates cold-press artisan loaves from conventional multigrain lines and private-label economy tiers. Price differentiation rests on clean-label certification grade and direct-store-delivery network density. Cost compression in economy tiers intensifies as private-label entrants replicate basic modified-wheat formulations. Diabetic end-user segments demonstrate lowest price sensitivity due to insulin protocol alignment requirements, while general health-conscious consumers exhibit highest elasticity.
Supply Chain Analysis
Strait of Hormuz transit risk for Indian and Pakistani psyllium husk shipments underwrites supply vulnerability for high-fiber binding systems. Raw material sourcing concentrates in California for almond flour, India for psyllium husk, and Midwest processing hubs for vital wheat gluten isolates. Formulation economics hinge on guar gum price volatility tied to monsoon-dependent agricultural yields. Tariff exposure on Mediterranean almond imports threatens margin compression for European producers. Distribution runs through direct-store-delivery networks for conventional retail penetration and frozen specialty distributors for health food channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against plant-based whole-food alternatives and functional food bars that bypass bread consumption entirely. Incumbents must fortify positioning through proprietary formulation moats and captive ingredient supply.
For Market Incumbents: Shield market share by securing backward integration into California almond flour processing to capture margin pools currently concentrated among limited suppliers. Deepen proprietary high-fiber dough system R&D to maintain differentiation against replicable modified-wheat formulations. Prioritize FDA nutritional labeling compliance investment to preempt reformulation cycles that disadvantage smaller competitors.
For New Entrants and Emerging Players: Differentiate on psyllium-husk formulation specialization for diabetic and athlete end-user segments where physiological need states command premium pricing. Target Japan's aging demographic through frozen direct-to-consumer subscription models that bypass entrenched supermarket slotting fee structures. Leverage cold-press fermentation equipment accessibility to achieve industrial-grade consistency without legacy plant capital requirements.
For Investors and Strategic Acquirers: Mid-volume specialists with automated extrusion capabilities and established health food store relationships represent prime acquisition targets for portfolio diversification. Long-term viability over the projection horizon depends on regulatory affairs capabilities navigating resistant starch reclassification risk across FDA and EFSA jurisdictions. Watch EFSA health claim regulation harmonization efforts as the inflection indicator for cross-border market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Almond Processing | Captures margin pools concentrated among limited California suppliers amid cultivation expansion. |
| Cold-Press Fermentation Equipment Deployment | Enables mid-volume producers to achieve industrial-grade dough consistency without legacy capital. |
| Direct-to-Consumer Subscription Launch | Bypasses REWE and EDEKA slotting fee renegotiation pressure in German conventional retail. |
| Regulatory Affairs Function Buildout | Navigates FSSAI compositional threshold conflicts that complicate Indian export qualification. |
| Psyllium-Husk Formulation Patent Filing | Protects differentiated positioning within athlete and diabetic end-user specialization vectors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nutritional labeling guidance documents, USDA Dietary Guidelines technical appendices, and EFSA health claim regulation databases. Interviews with bakery R&D directors, health food store category buyers, almond flour procurement managers, and regulatory affairs specialists at cross-border exporters inform demand elasticity and compliance burden assessments. Secondary validation draws from customs trade data, Nielsen retail audit figures, and FSSAI compositional threshold documentation. Bottom-up volume builds from segment-level consumption patterns triangulate against top-down macroeconomic scaling factors.
Segmentation dimensions modeled span product type, ingredient type, distribution channel, and end-user physiology across the projection horizon. Whole grain, gluten-free, multigrain, and sourdough variants anchor product-level disaggregation. Almond flour, wheat protein, coconut flour, and psyllium husk inputs drive ingredient-level margin analysis. CAGRs derive from trend extrapolation of fitness program integration rates and diabetic population prevalence curves. FDA serving-size disclosure evolution and EFSA resistant starch reclassification scenarios inform regulatory sensitivity testing.
The analysis sits within stated boundaries; outcomes outside sustained almond flour supply chain maturation and stable Indian agricultural yields would require recalibration. Forecasts reflect assumptions regarding cold-press fermentation equipment adoption curves and health food store procurement pattern continuity. Practitioners should keep alternative scenarios live as METI standards evolution and FSSAI import qualification protocols develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Baking Mixes Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Specula Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Banana Bread Market
Bakery Products
United States Cookies Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
South America Ice Cream Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Dough Conveyor Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Pastry Dough Market