
 North America Gluten-Free Food and Beverage Market | 2026-2036
North America Gluten-Free Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gluten-Free Food and Beverage Market Analytics
Precision fermentation and enzymatic processing is reconfiguring how gluten-free flours achieve texture parity with wheat-based alternatives. General Mills Inc. leverages its cereal manufacturing infrastructure to sustain national distribution of gluten-free product lines. The Hain Celestial Group Inc. anchors its portfolio in organic-certified gluten-free offerings that command shelf space in health-focused retail channels. Conagra Brands Inc. competes through frozen meal specialization that addresses convenience-seeking households with dietary restrictions.
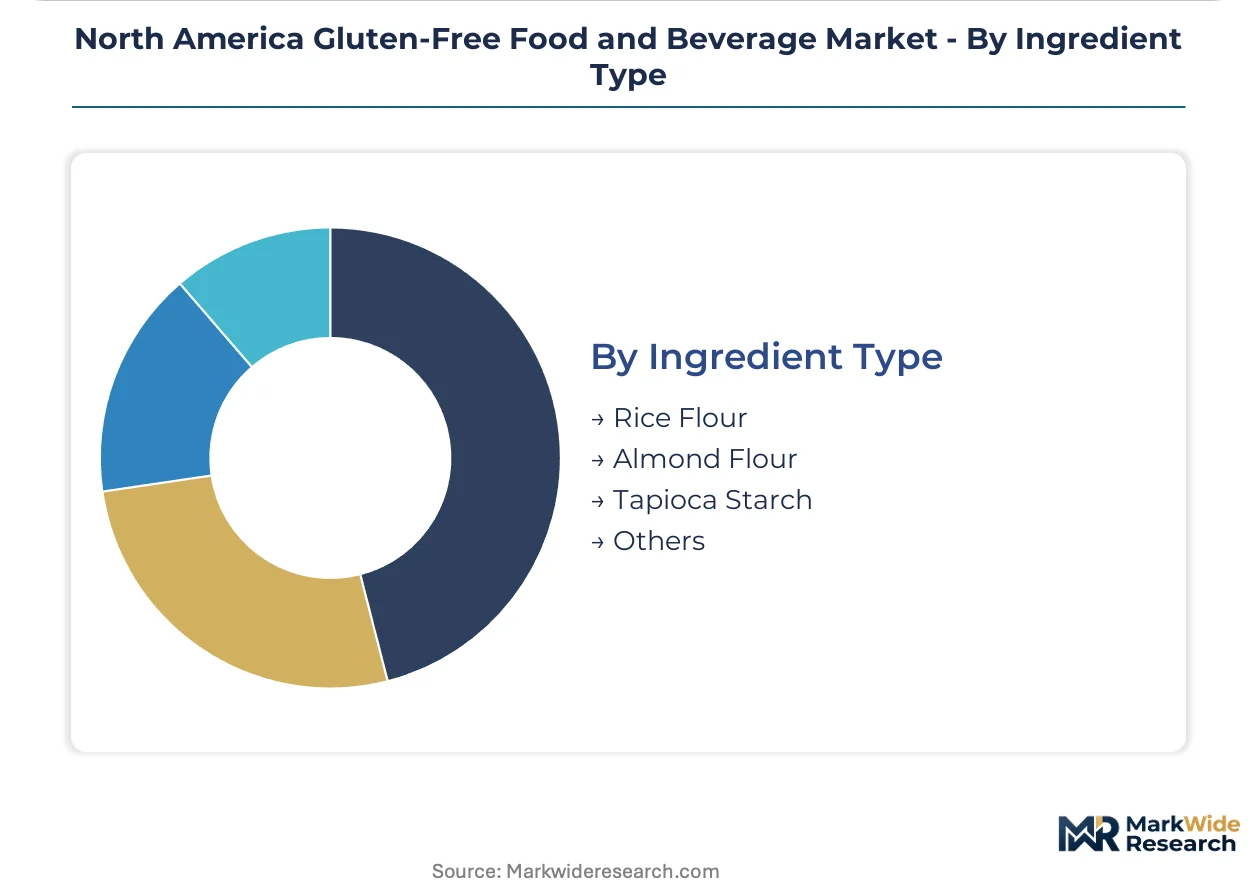
North America gluten-free food and beverage encompasses formulated products containing fewer than 20 parts per million gluten, utilizing alternative grains and starches to replicate the viscoelastic properties of wheat gluten in baked goods, pasta, and beverages. The category serves consumers with celiac disease, non-celiac gluten sensitivity, and elective wheat-avoidance diets seeking safe nutritional alternatives. Breads and snacks occupy the largest volume share within product type segmentation, though beverages demonstrate the fastest expansion as functional drink formulations incorporate gluten-free positioning. Rice flour dominates ingredient type selection due to neutral flavor and cost efficiency, while almond flour captures premium positioning in grain-free sub-segments targeting paleo and keto-adjacent consumers.
The FDA enforces gluten-free labeling standards under the Food Allergen Labeling and Consumer Protection Act, requiring substantiated claims that manufacturers verify through supply chain testing protocols. Health Canada maintains parallel thresholds and enforcement mechanisms that govern cross-border product movement within the integrated North American market. USDA organic certification frequently intersects with gluten-free positioning, creating dual-compliance requirements that filter smaller producers from mainstream retail access. Stakeholders must monitor evolving allergen management protocols and traceability mandates that will determine which suppliers retain shelf space as retailer accountability standards tighten.
Market Dynamics
Precision fermentation is restructuring how manufacturers achieve functional parity in gluten-free formulations without wheat proteins, compressing R&D cycles and flattening cost curves for texture-matched alternatives.
Growth Catalysts
- FDA Gluten-Free Labeling Rule:The FDA's enforcement of the Food Allergen Labeling and Consumer Protection Act mandates substantiated gluten-free claims, compelling supply chain testing protocols that build consumer trust and expand retail shelf access for compliant products.
- Urban Health-Conscious Demand:Metropolitan consumers across the United States drive category innovation through elective wheat-avoidance diets, creating pull for functional beverages and premium-positioned grain-free alternatives that command higher margins.
- Enzymatic Processing:Advanced enzymatic treatments of alternative flours are replicating the viscoelastic properties of wheat gluten, enabling pasta and baked goods manufacturers to broaden their gluten-free portfolios without sacrificing mouthfeel quality.
Market Restraints
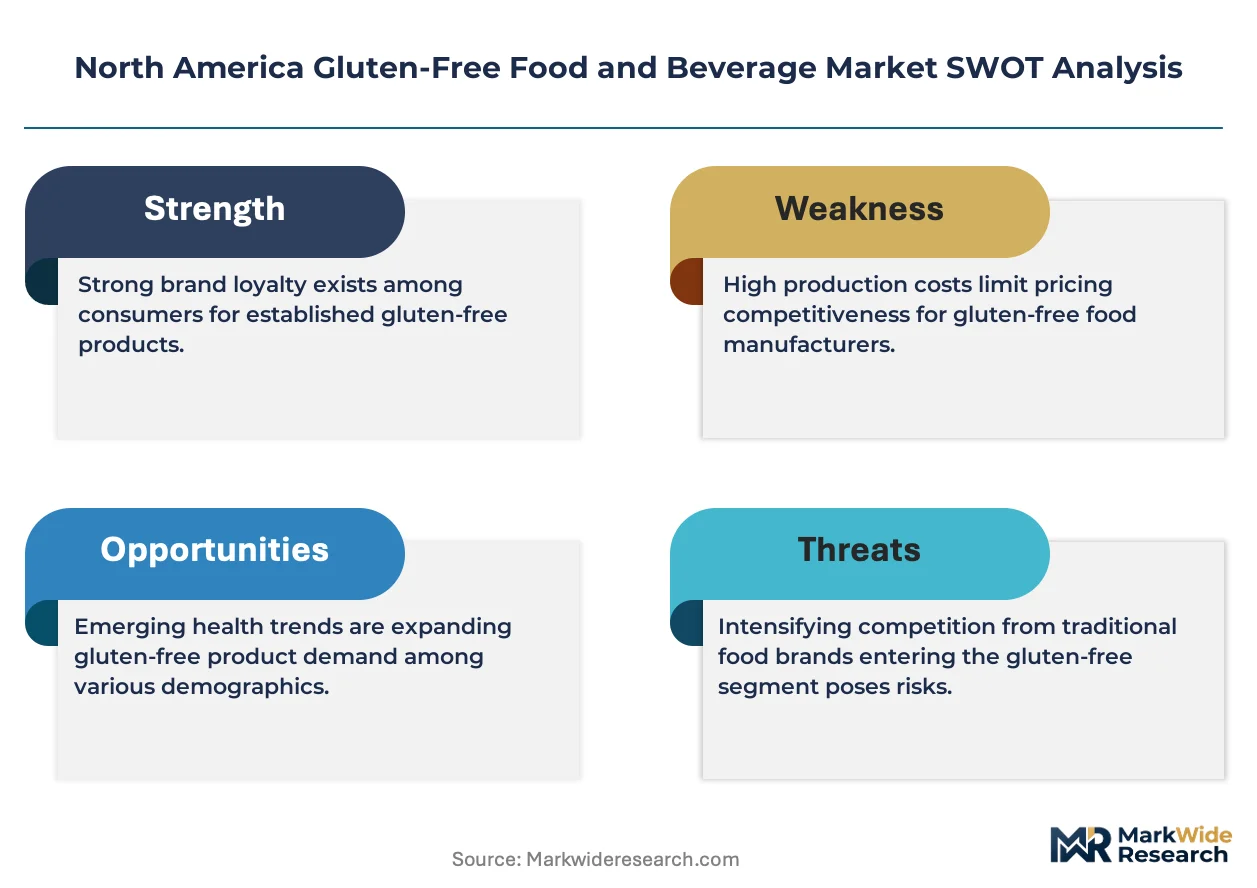
- Input Cost Volatility:Almond flour and other nut-based ingredients face price swings tied to California drought cycles and pollination costs, squeezing margins for premium grain-free sub-segments targeting paleo-adjacent consumers.
- Supply Concentration Risk:Rice flour sourcing concentrates in specific agricultural regions, exposing manufacturers to climate-related yield variability and trade flow disruptions that cascade through North American production networks.
- Dual-Compliance Burden:USDA organic certification intersecting with FDA gluten-free standards creates filtering effects that exclude smaller producers from mainstream retail channels, consolidating shelf access among multi-certification holders.
Strategic Opportunities
- Canadian Market Expansion:Health Canada's parallel gluten-free thresholds and enforcement mechanisms present underpenetrated white space for US manufacturers with existing FDA-compliant supply chains to extend distribution northward.
- Foodservice Channel Innovation:Restaurants and institutional operators are expanding gluten-free menu offerings as celiac awareness rises, creating direct procurement relationships that bypass traditional retail markup structures.
- Functional Beverage Convergence:The fastest-expanding product category within gluten-free positioning invites cross-pollination with adaptogenic and probiotic formulations, opening shelf space in health-focused retail channels beyond conventional grocery.
Industry Challenges
- Traceability System Integration:Evolving allergen management protocols require granular lot-tracking infrastructure that many mid-tier manufacturers lack, forcing capital deployment into ERP upgrades or third-party verification services.
- Cross-Contamination Control:Dedicated production lines and sanitation protocols for gluten-free certification impose facility reconfiguration costs and capacity constraints that complicate SKU expansion strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gluten-Free Food and Beverage Market |
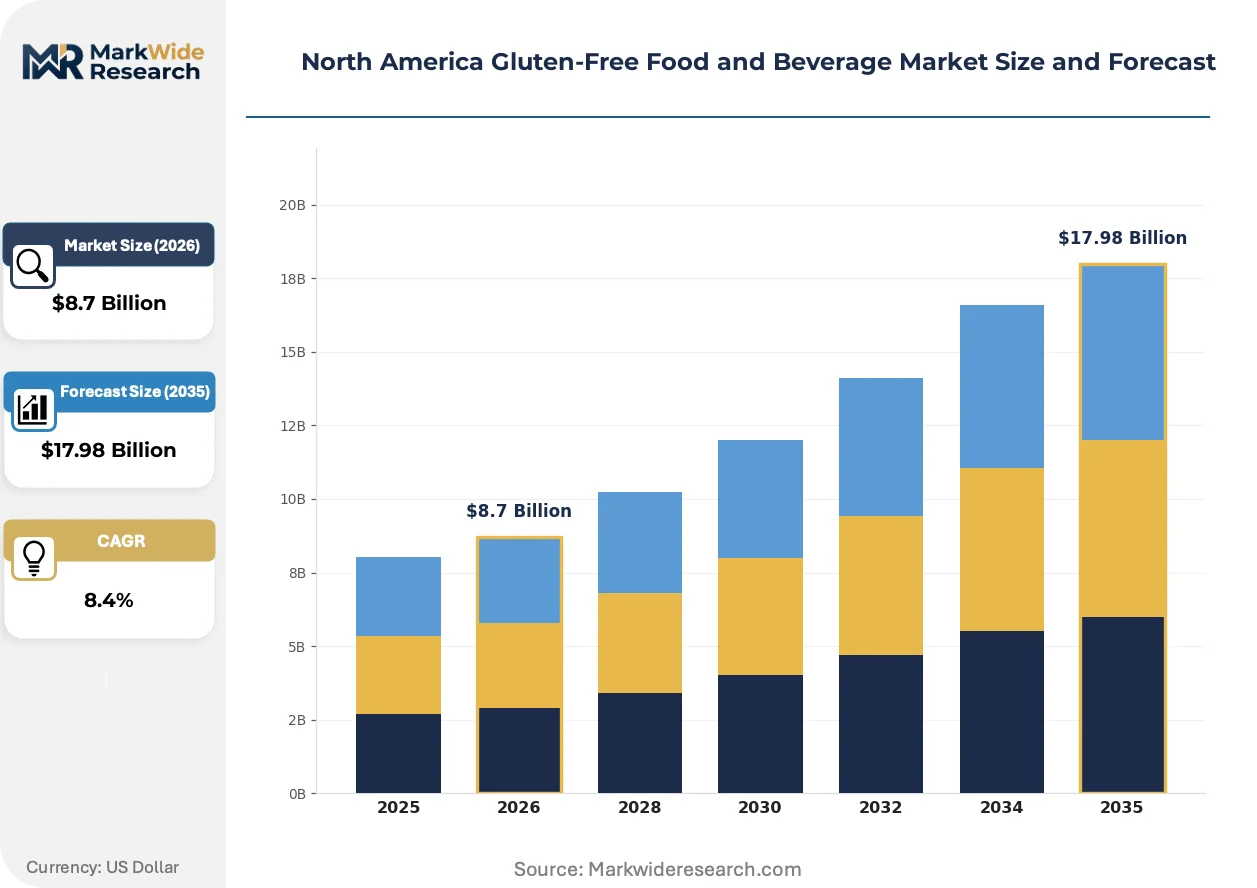
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Snacks, Pasta, Beverages End User: Retail Consumers, Restaurants, Foodservice, Healthcare Providers Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Shops Ingredient Type: Rice Flour, Almond Flour, Tapioca Starch, Others |
| Companies Covered | The Kraft Heinz Company, General Mills Inc., The Hain Celestial Group Inc., Conagra Brands Inc., PepsiCo Inc., Nestlé SA, Kellanova, Amy's Kitchen Inc., Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gluten-Free Food and Beverage Market Evolving Landscape
Active reformulation of alternative starches and proteins is collapsing the texture gap between gluten-free and conventional wheat products, while regulatory clarity and channel diversification accelerate category maturation.
Precision fermentation of microbial proteins is virtualizing the functional role of wheat gluten in dough systems, enabling bakers to replicate extensibility and gas retention without grain inputs. Foodservice operators and industrial bakeries are piloting these ingredients at accelerated testing cycles. The technology is virtualizing traditional commodity supply chains by decoupling protein functionality from agricultural cultivation.
Health Canada's alignment with FDA gluten-free thresholds under the Food and Drug Regulations creates regulatory coherence across the integrated North American market. This harmonization reduces formulation complexity for cross-border manufacturers. Frozen meal and ready-to-eat segments are responding by standardizing dual-compliant product lines that satisfy both jurisdictions without separate SKUs.
Direct-to-restaurant procurement is displacing traditional distributor intermediation for gluten-free specialty ingredients. Foodservice operators with dedicated gluten-free kitchen protocols are sourcing certified flours and pre-mixes through specialized foodservice purveyors rather than broadline distributors. This pattern concentrates in metropolitan United States markets where celiac-safe dining options command premium positioning.
North America Gluten-Free Food and Beverage Market Segmentation
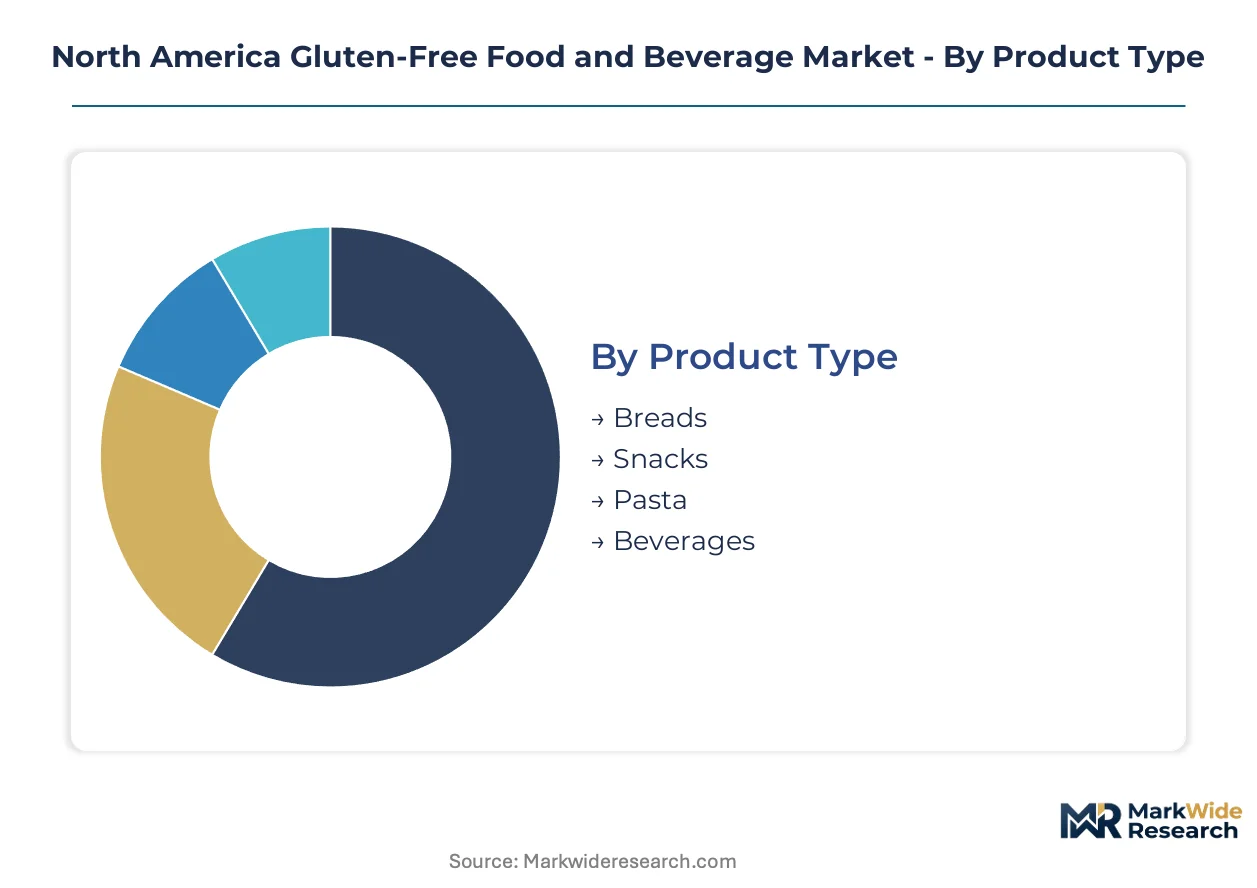
Gluten-free market segmentation reveals distinct performance profiles across formulation types and procurement channels. Each dimension carries specific margin structures and regulatory compliance burdens that determine supplier viability.
Product Type:
After-sales intensity varies sharply across product categories, with fresh breads requiring shortest shelf-life management and beverages demanding formulation stability guarantees.
- Breads:Formulated from rice flour and tapioca starch blends to replicate wheat's crumb structure and moisture retention. Demand concentrates in United States metropolitan retail channels where celiac-safe fresh bakery alternatives command premium positioning against frozen substitutes.
- Snacks:Crackers, cookies, and extruded products utilizing alternative starches for crisp texture and extended shelf stability. United States health-conscious consumers in urban clusters drive innovation toward grain-free and paleo-adjacent positioning that bypasses rice flour entirely.
- Pasta:Corn and rice flour extrusions requiring precise hydration control to prevent cooking disintegration.
- Beverages:Functional drink formulations with gluten-free certification as secondary positioning element.
Breads holds the largest share; momentum sits with beverages.
End User:
Cost tier stratification separates premium healthcare-directed nutrition from mass-market retail accessibility.
- Retail Consumers:Individual households purchasing through grocery and specialty channels for at-home consumption. United States urban centers generate highest per-capita spending on certified-organic gluten-free alternatives that satisfy dual FDA-USDA compliance requirements.
- Restaurants:Independent and chain operators sourcing certified ingredients for dedicated gluten-free menu sections. Metropolitan United States markets with elevated celiac awareness support premium pricing for verified kitchen protocols that prevent cross-contamination incidents.
- Foodservice:Institutional cafeterias and catering operations with volume procurement contracts.
- Healthcare Providers:Hospitals and clinical nutrition programs prescribing gluten-free therapeutic diets.
Retail Consumers dominates volume; Restaurants are expanding most quickly.
Distribution Channel:
Margin compression intensity tracks channel concentration, with supermarkets extracting slotting fees and online platforms demanding logistics subsidies.
- Supermarkets:Mass-market grocery chains with dedicated gluten-free aisle sections and private-label offerings. United States national retailers leverage FDA labeling compliance as gatekeeping mechanism that filters smaller suppliers from shelf access.
- Health Stores:Natural products retailers emphasizing organic-certified and grain-free sub-segments. United States coastal metropolitan clusters support premium positioning for almond flour and alternative protein formulations targeting keto-adjacent consumers.
- Online Retail:Direct-to-consumer platforms with subscription models for specialty ingredient replenishment.
- Specialty Shops:Independent gluten-free bakeries and boutiques with localized production.
Supermarkets holds the largest share; momentum sits with Online Retail.
Ingredient Type:
Supply concentration risk varies by agricultural source geography and climate exposure.
- Rice Flour:Neutral-flavor, cost-efficient base starch dominating mass-market formulations. United States manufacturers face yield variability exposure from concentrated sourcing regions that cascade through North American production networks during drought cycles.
- Almond Flour:Premium-positioned protein-rich alternative for grain-free and paleo formulations. California production concentration creates margin squeeze from pollination cost inflation and water scarcity that restricts supply elasticity.
- Tapioca Starch:South American cassava-derived binder providing chew and elasticity.
- Others:Sorghum, millet, and emerging microbial protein alternatives from precision fermentation.
Rice Flour holds the largest share; Others are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border trade in gluten-free ingredients flows predominantly northward from the United States into Canada, while Mexican import demand for premium-certified products expands through integrated supply chains. Regulatory alignment between FDA and Health Canada thresholds reduces tariff-equivalent compliance costs for manufacturers operating across the integrated North American market.
United States
Metropolitan health-conscious consumers in New York, Los Angeles, and Chicago drive premium positioning for certified-organic gluten-free alternatives that satisfy dual FDA-USDA compliance requirements. The FDA enforces gluten-free labeling standards under the Food Allergen Labeling and Consumer Protection Act, mandating substantiated claims verified through supply chain testing protocols. California's Central Valley anchors almond flour production, though drought cycles and pollination cost inflation squeeze margins for grain-free sub-segments targeting paleo-adjacent consumers.
Canada
Health Canada's parallel gluten-free thresholds under the Food and Drug Regulations create regulatory coherence that reduces formulation complexity for cross-border manufacturers. Toronto and Vancouver metropolitan clusters support premium retail positioning for dual-certified organic-gluten-free products that command shelf space in health-focused channels. The country's national food regulator maintains enforcement mechanisms governing cross-border product movement within the integrated North American market.
Mexico
Mexico City and Monterrey metropolitan areas generate concentrated demand for imported gluten-free products as celiac awareness rises among upper-middle-class consumers. The country's national health regulator oversees labeling standards that increasingly align with FDA thresholds to facilitate trade integration. Northern border states concentrate retail distribution infrastructure that channels US-manufactured certified products into domestic Mexican markets through established logistics networks.
California
Los Angeles and San Francisco Bay Area consumers drive category innovation through elective wheat-avoidance diets and functional beverage demand. The state's agricultural regions face water scarcity constraints that restrict supply elasticity for almond flour and other nut-based ingredients. Precision fermentation startups in San Diego and Berkeley pilot microbial protein alternatives that virtualize traditional commodity supply chains by decoupling protein functionality from agricultural cultivation.
New York Metro
The metropolitan New York corridor concentrates foodservice procurement relationships as restaurants expand dedicated gluten-free kitchen protocols. Brooklyn and Manhattan independent operators source certified flours and pre-mixes through specialized foodservice purveyors rather than broadline distributors. This pattern accelerates as celiac-safe dining options command premium positioning in competitive metropolitan restaurant markets.
North America Gluten-Free Food and Beverage Market Competitive Landscape
On the supply side, the industry is consolidating around multi-certification holders capable of satisfying intersecting FDA gluten-free and USDA organic standards. Tiered competitive positioning separates national-scale cereal manufacturers from mid-cap organic specialists and frozen meal convenience providers. Dominant competitive moves include portfolio diversification into functional beverage adjacencies and backward integration into alternative flour sourcing to secure supply chain resilience against climate-related yield variability.
Within the diversified packaged foods tier, General Mills Inc., Conagra Brands Inc., and The Hain Celestial Group Inc. occupy positions that exemplify distinct strategic archetypes. General Mills Inc. represents scale-driven national distribution leverage through existing cereal manufacturing infrastructure. Conagra Brands Inc. anchors frozen meal specialization addressing convenience-seeking households with dietary restrictions. The Hain Celestial Group Inc. exemplifies organic-certified portfolio positioning that commands shelf space in health-focused retail channels.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| General Mills Inc. |
| The Hain Celestial Group Inc. |
| Conagra Brands Inc. |
| PepsiCo Inc. |
| Nestlé SA |
| Kellanova |
| Amy's Kitchen Inc. |
| Kellogg Company |
| Others |
Value Network & Pricing Analysis
California almond flour production concentration anchors premium-tier margin pools in grain-free sub-segments, while rice flour sourcing from specific agricultural regions determines cost competitiveness across mass-market formulations. FDA gluten-free certification requirements filter smaller producers from mainstream retail channels, consolidating pricing power among multi-certification holders capable of absorbing dual-compliance overhead.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize input costs for foodservice operators and institutional procurement. Three-tier pricing structure across premium, standard, and economy levels separates certified-organic dual-compliant products from conventional gluten-free alternatives and private-label economy tiers. Cost compression in the premium grain-free segment is intensifying because California drought cycles and pollination cost inflation squeeze almond flour margins. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement scale, while specialty health stores demonstrate lowest sensitivity as consumers prioritize certification credibility over per-unit cost.
Supply Chain Analysis
Tariff exposure between the United States and Canada remains minimal due to regulatory harmonization under USMCA, though cross-border documentation requirements for gluten-free certification add administrative friction. Raw material sourcing draws from California for almond flour, the Mississippi Delta and Arkansas for rice cultivation, and South American cassava regions for tapioca starch. Single-source vulnerability concentrates in California nut processing infrastructure exposed to climate-related yield variability. Distribution runs through broadline foodservice distributors for institutional accounts, specialized gluten-free purveyors for restaurant direct procurement, and national retail brokers for supermarket shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation of microbial proteins presents a credible substitute threat to traditional grain-based gluten-free formulations, forcing incumbents to defend positioning through rapid technology adoption or exclusive supplier partnerships.
For Market Incumbents: Entrench market position by backward integration into alternative flour sourcing to secure supply chain resilience against California drought exposure, and accelerate precision fermentation pilot programs to match texture parity claims from emerging biotech entrants. FDA certification maintenance serves as the critical defensive lever against smaller organic specialists seeking retail shelf access. For New Entrants and Emerging Players: Pursue white-space expansion in Canadian metropolitan markets where Health Canada regulatory coherence reduces compliance complexity for US-origin supply chains, and target direct-to-restaurant procurement relationships in New York and Los Angeles that bypass traditional distributor markups. Functional beverage convergence with adaptogenic positioning offers the most penetrable entry angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap organic-certified specialists with existing dual FDA-USDA compliance infrastructure and established health-store retail relationships, positioned for consolidation as retailer accountability standards tighten. Precision fermentation technology maturation serves as the critical inflection signal indicating when microbial protein alternatives achieve cost parity with agricultural inputs.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial protein production decouples gluten functionality from agricultural cultivation, collapsing texture gap with wheat. |
| Dual-Certification Investment | Simultaneous FDA gluten-free and USDA organic compliance filters competitors from mainstream supermarket shelf access. |
| Foodservice Direct Procurement | Specialized purveyor relationships bypass broadline distributor markups and capture premium positioning in metropolitan restaurants. |
| Canadian Distribution Expansion | Health Canada regulatory alignment reduces SKU complexity for cross-border manufacturers with existing FDA-compliant infrastructure. |
| Alternative Flour Backward Integration | Upstream control over rice and almond sourcing mitigates margin squeeze from California water scarcity and pollination cost inflation. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at diversified packaged food companies, category buyers at national supermarket chains, supply planners at alternative flour processors, and foodservice procurement directors at metropolitan restaurant groups, and refined through secondary validation against FDA labeling guidance documents, USDA organic certification databases, Health Canada Food and Drug Regulations, Nielsen retail audit data, and SEC 10-K filings from publicly traded manufacturers. Bottom-up volume modeling across product type, ingredient, and distribution channel segments was triangulated against top-down market sizing derived from trade flow analysis.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product type, end user archetype, distribution channel, and ingredient sourcing geography, with CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted forward projections. Forecast inputs incorporated FDA enforcement intensity scenarios, precision fermentation technology readiness curves, and climate-adjusted agricultural yield assumptions for California almond and Delta rice production regions.
Sensitivities concentrate around regulatory enforcement intensity shifts, precision fermentation cost curve acceleration, and severe drought cycles affecting California nut production. Forecasts reflect documented assumptions regarding certification compliance rates and technology adoption timelines. Material shifts in FDA gluten-free labeling enforcement or breakthrough microbial protein cost parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Food Intolerance Products Market